
 Foam Glass Market | 2026-2036
Foam Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Glass Market Analysis
Project finance for industrial insulation retrofits is tilting competitive dynamics toward capital-backed suppliers with balance-sheet capacity to underwrite long-term performance contracts. Owens Corning leverages its fiberglass-to-foam-glass technology bridge to cross-sell building envelope systems. GLAPOR Werk Mitterteich GmbH anchors Central European supply through its dedicated cellular glass furnace network in Bavaria. AeroAggregates of North America, LLC specializes in lightweight aggregate derivatives for geotechnical fill, carving a niche outside conventional insulation channels.
Foam glass is a rigid cellular material manufactured from recycled glass powder, foamed at high temperatures with carbon-based blowing agents to achieve closed-cell structures with bulk densities between 100 and 200 kg/m³ and compressive strengths exceeding 0.5 MPa; its primary purpose is thermal insulation in environments demanding fire resistance, moisture immunity, and dimensional stability across cryogenic to elevated temperatures. Closed cell formulations dominate margin pools in LNG and petrochemical applications where vapor barrier integrity commands premium pricing. Construction application volumes lead absolute consumption, though industrial process insulation is recording the fastest specification shift as energy-efficiency retrofit mandates tighten across manufacturing facilities.
EPA industrial emissions guidelines and OSHA thermal hazard standards in the United States shape product certification requirements for high-temperature pipe insulation. The EU F-Gas Regulation and REACH chemical restrictions constrain blowing agent chemistry, filtering market access to formulations with verified environmental profiles. Stakeholders must monitor evolving carbon-border adjustment mechanisms and building code harmonization trajectories to anticipate where specification advantages will crystallize for certified cellular glass suppliers.
Market Dynamics
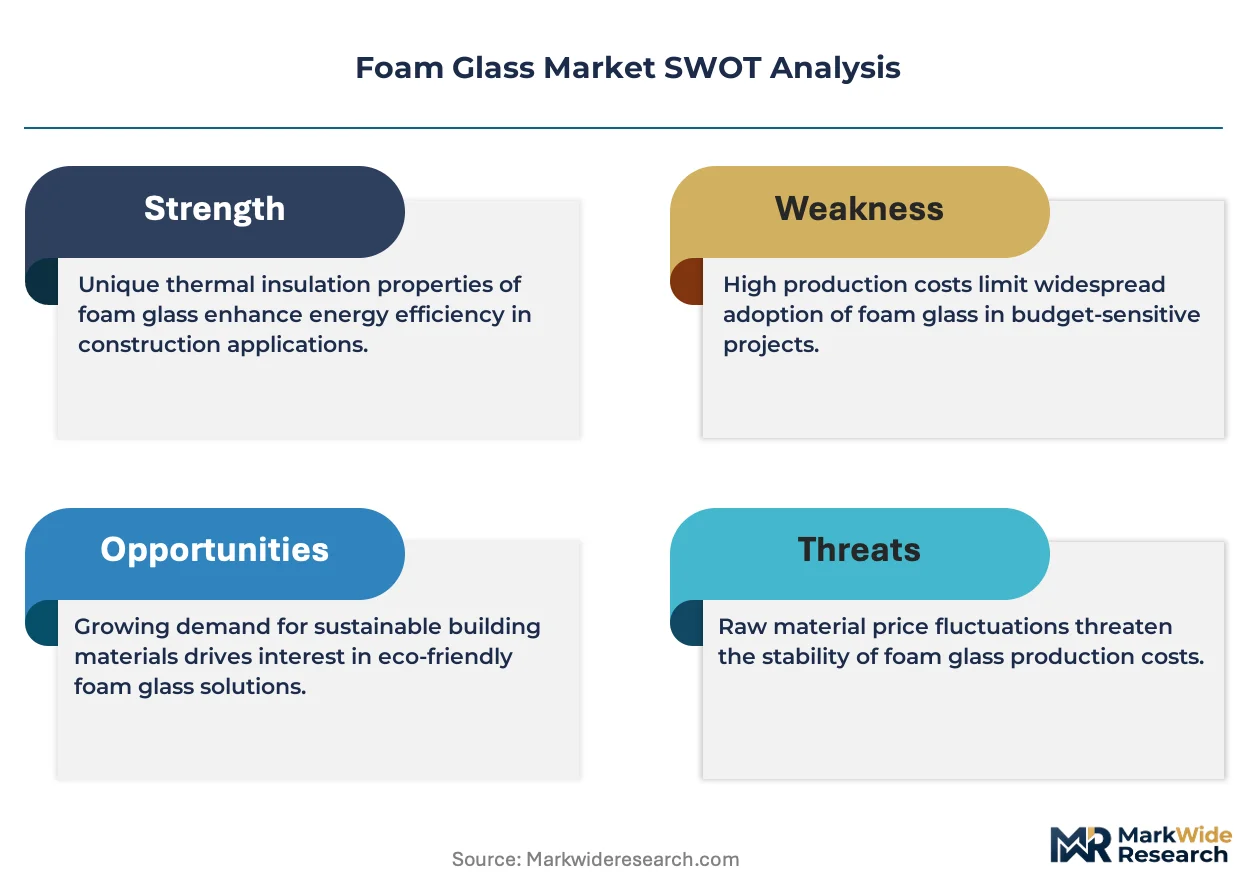
The EU F-Gas Regulation is systematically dismantling hydrofluorocarbon-dependent insulation chemistries, forcing specification migration toward carbon-blown cellular glass formulations that satisfy cryogenic vapor-barrier requirements without ozone-depleting potential.
Growth Catalysts
- EU F-Gas Regulation phase-down:The mandated reduction in hydrofluorocarbon blowing agents redirects industrial procurement toward inert gas cellular glass alternatives for LNG storage and petrochemical processing infrastructure.
- German commercial building renovation codes:Mandatory high-performance thermal envelope standards in industrial facilities accelerate specification of rigid cellular insulation with verified fire resistance and moisture immunity.
- Cryogenic storage expansion:LNG infrastructure developers are scaling procurement of closed-cell foam glass for liquefaction terminals and regasification facilities requiring dimensional stability across extreme temperature differentials.
Market Restraints
- Recycled glass powder supply concentration:Dependence on post-consumer cullet streams from container glass recycling creates input cost volatility when municipal collection rates fluctuate regionally.
- High-temperature furnace capex intensity:Cellular glass production requires dedicated tunnel kilns operating above 800°C, creating barrier-to-entry economics that limit supplier base expansion.
- Polyisocyanurate substitution in ambient applications:Lower-cost polymer foam alternatives capture building envelope share where fire-code restrictions do not mandate inorganic insulation.
Strategic Opportunities
- Geotechnical fill applications:Lightweight aggregate derivatives from foam glass manufacturing waste streams open non-insulation channels in civil engineering and soil stabilization projects.
- Carbon-border adjustment mechanism alignment:EU CBAM implementation creates competitive advantage for cellular glass with verified recycled content and low-carbon production credentials.
- Industrial process insulation retrofit mandates:Energy-efficiency compliance deadlines in manufacturing facilities generate replacement demand for high-temperature pipe and vessel insulation systems.
Industry Challenges
- Refractory engineering skill scarcity:Specialized furnace operation and thermal process control expertise constrains production scaling and quality consistency across manufacturing sites.
- Multi-jurisdiction certification timelines:Parallel EPA, OSHA, and EU CE marking approval processes extend product launch cycles for new density-grade formulations targeting transatlantic projects.
- Legacy system integration complexity:Retrofit specification of rigid cellular glass onto existing piping networks requires custom fabrication coordination that disrupts standard procurement workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Glass Market |
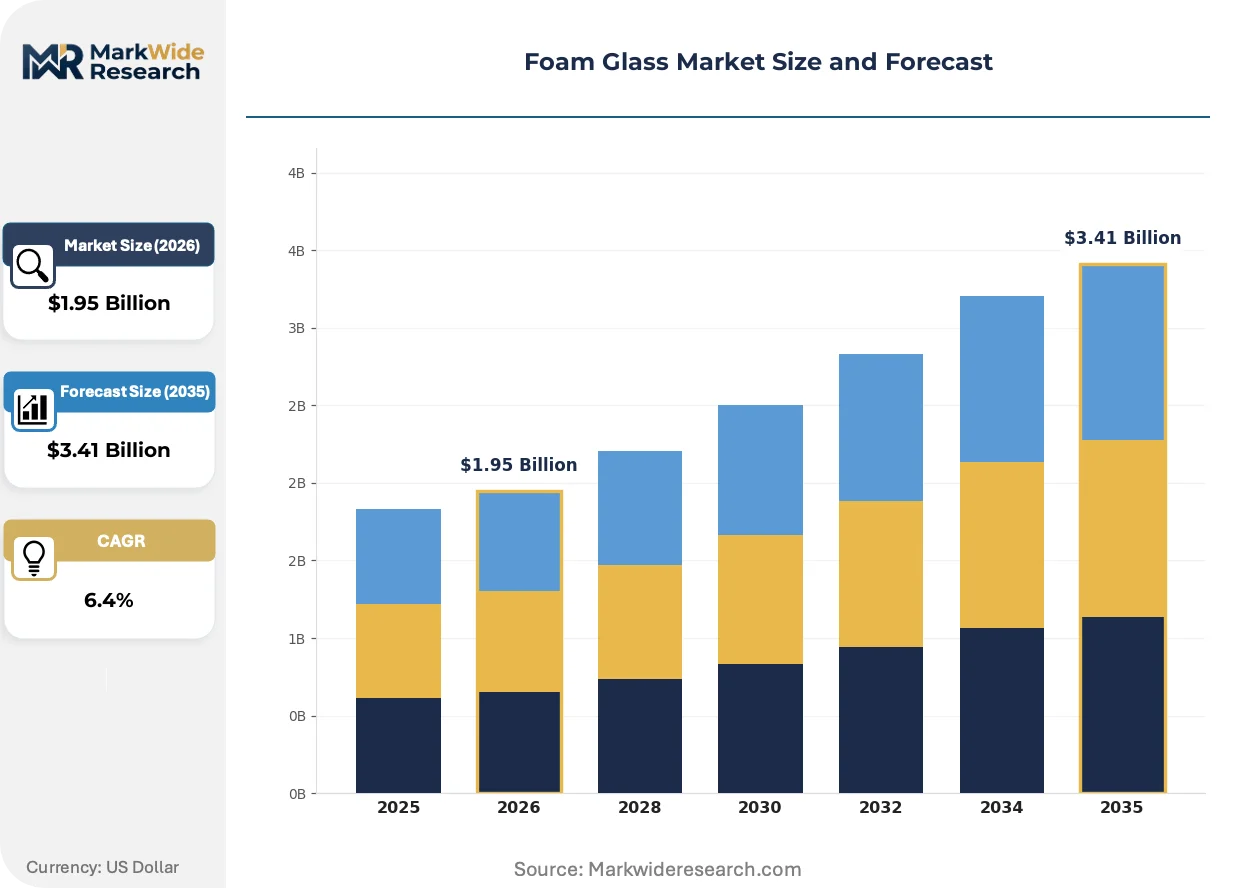
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Cell, Open Cell, Structural Foam, Insulation Foam Application: Construction, Automotive, Aerospace, Industrial End User: Contractors, Manufacturers, Architects, Engineers Distribution Channel: Direct Sales, Distributors, Online, Retail |
| Companies Covered | Uusioaines Oy, Misapor AG, Owens Corning, PINOSKLO, Shanghai Metal Corporation, GLAPOR Werk Mitterteich GmbH, REFAGLASS, Dehe Technology Group Co., LTD, AeroAggregates of North America, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Glass Market Emerging Trajectories
Computational modeling of cellular microstructure is compressing formulation development cycles while regulatory chemistry constraints are forcing blowing-agent innovation away from established industrial gas pathways.
Advanced foaming control systems using real-time thermal imaging and automated atmosphere modulation are virtualizing quality assurance processes that previously required destructive testing of production samples. LNG terminal developers in the United States and Germany are adopting these sensor-integrated furnace systems to guarantee closed-cell integrity for cryogenic applications. The technology is virtualizing batch-to-batch variation management, reducing rejection rates and compressing warranty liability exposure for insulation contractors.
REACH chemical restrictions and EU F-Gas Regulation enforcement are systematically disqualifying hydrocarbon and fluorocarbon blowing agents from specification-grade cellular glass production. Manufacturers are responding by reformulating around carbon black and inert gas nucleation chemistries that satisfy environmental profile verification requirements. The regulatory pressure is most acute in German and French industrial renovation markets, where building permit approval now mandates full material disclosure for thermal envelope components.
Long-term performance contracting is displacing transactional material supply in large-scale industrial retrofit projects. EPC contractors and facility operators in the United States are bundling cellular glass installation with 15-20 year thermal performance guarantees backed by supplier balance-sheet capacity. This procurement evolution is most visible in Texas and Louisiana petrochemical corridors, where energy-efficiency upgrade financing increasingly ties contractor payment to verified heat-loss reduction metrics rather than installed volume alone.
Foam Glass Market Segmentation
Foam glass specification cycles vary dramatically by segment—cryogenic industrial installations demand 15-20 year performance contracts while construction retrofits turn on annual building code cycles. Understanding these velocity differentials reveals where supplier working capital gets tied up longest and where procurement patterns shift quickest.
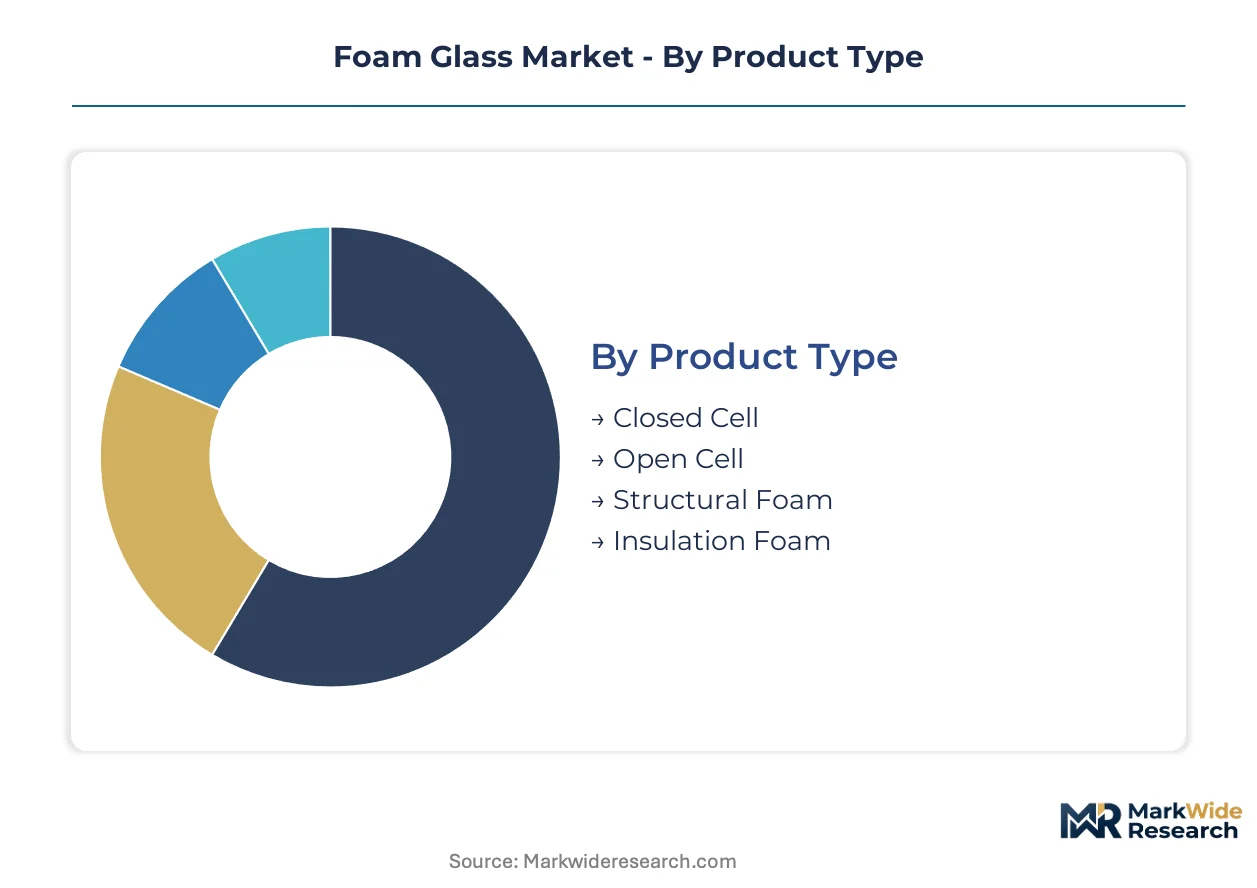
Product Type:
Closed cell formulations command the longest specification cycles due to LNG infrastructure validation protocols, while open cell variants face rapid substitution pressure from polymer foams in ambient-temperature construction.
- Closed Cell:Dense cellular structures with vapor-tight cell walls achieve bulk densities of 100-200 kg/m³ and compressive strengths exceeding 0.5 MPa. LNG terminal developers in Germany and the United States specify these formulations for cryogenic storage systems where dimensional stability across extreme temperature differentials is mandatory. The EU F-Gas Regulation phase-down redirects procurement from hydrocarbon-blown alternatives toward carbon-nucleated closed cell grades.
- Open Cell:Interconnected pore networks prioritize acoustic absorption and moderate thermal performance over vapor barrier integrity. Building envelope contractors in Germany favor open cell foam glass for interior partition insulation where fire resistance codes outweigh moisture immunity requirements.
- Structural Foam:High-density variants engineered for load-bearing geotechnical applications including lightweight fill and soil stabilization projects.
- Insulation Foam:Standard-density grades targeting general-purpose thermal envelope specification in commercial and industrial building retrofits.
Closed cell anchors the volume base while open cell faces the steepest share erosion from polyisocyanurate substitution in cost-sensitive construction segments.
Application:
Cost tier differentiation separates mission-critical cryogenic systems from commodity building envelope specification, with margin pools concentrating where failure consequences include catastrophic vapor loss.
- Construction:Building envelope and interior partition insulation drives absolute consumption volumes across commercial, residential, and institutional structures. German commercial renovation codes mandate high-performance thermal envelopes with verified fire resistance, accelerating rigid cellular glass specification in industrial facility retrofits. Polyisocyanurate foams capture ambient-temperature share where code restrictions do not mandate inorganic insulation.
- Industrial:Process piping, vessel insulation, and cryogenic storage systems record the fastest specification shift as energy-efficiency retrofit mandates tighten across manufacturing facilities. EPA industrial emissions guidelines and OSHA thermal hazard standards shape certification requirements for high-temperature pipe insulation in United States petrochemical corridors.
- Automotive:Limited adoption concentrated in specialty vehicle thermal management and fire-resistant compartmentalization applications.
- Aerospace:Niche specification for lightweight thermal protection in satellite and launch vehicle structures demanding extreme temperature cycling resistance.
Construction dominates absolute volume while industrial application climbs the fastest as compliance deadlines for manufacturing facility energy efficiency accelerate replacement cycles.
End User:
Customer type determines procurement complexity—contractors bundle material with installation labor while manufacturers integrate foam glass into original equipment specifications with multi-year validation requirements.
- Contractors:Installation-focused procurement dominates construction application channels, with EPC firms increasingly bundling cellular glass supply with long-term thermal performance guarantees.
- Manufacturers:Original equipment specification for industrial process systems and prefabricated building components requires extended qualification protocols and batch-to-batch quality verification.
- Architects:Design-phase influence shapes thermal envelope specification in German commercial renovation projects where building permit approval mandates full material disclosure.
- Engineers:Technical specification authority in LNG infrastructure and petrochemical processing drives closed cell formulation selection based on cryogenic performance validation.
Contractors anchor the volume base while manufacturers gain procurement influence fastest as industrial OEMs internalize insulation system design.
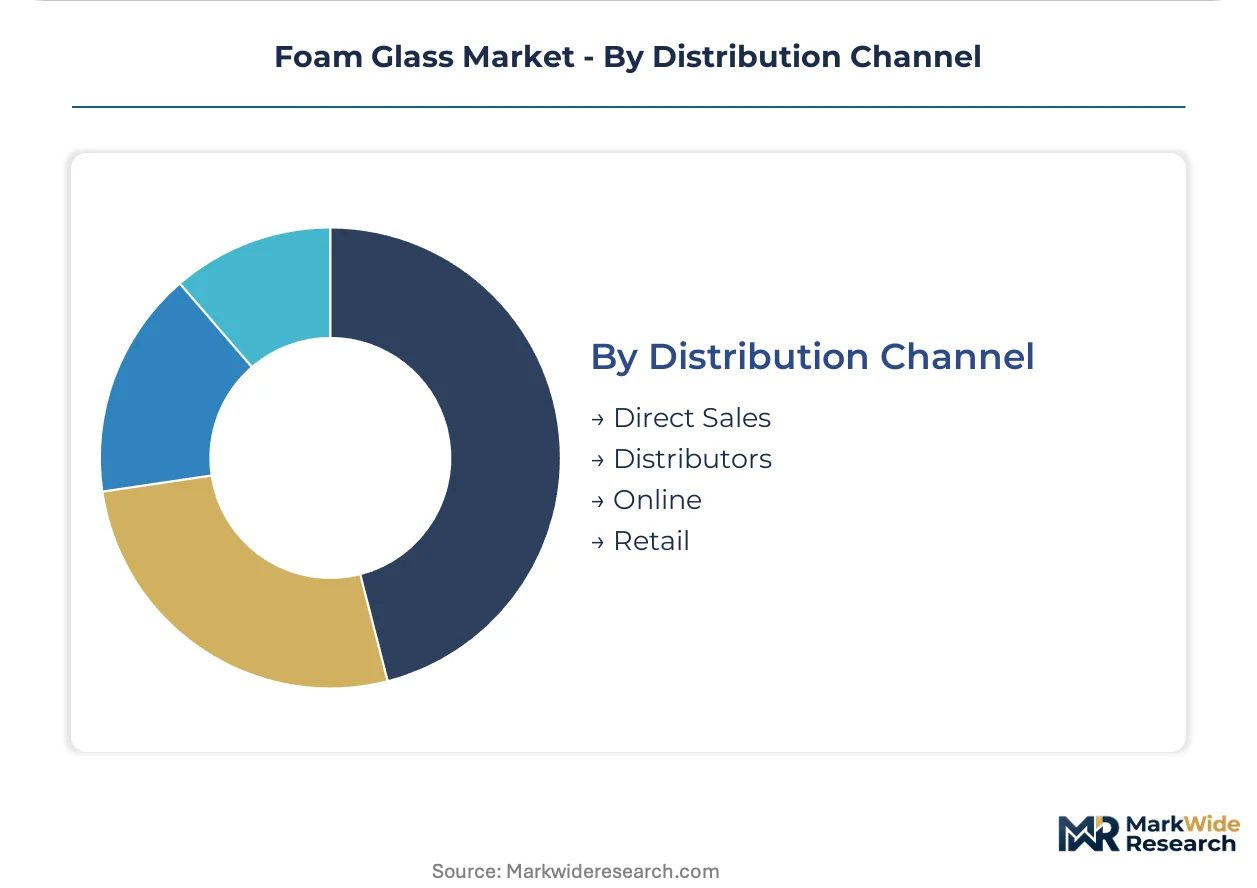
Distribution Channel:
Supply concentration in Central European furnace networks favors direct sales for large-scale industrial projects, while fragmented construction demand sustains distributor intermediation.
- Direct Sales:Large-volume procurement from LNG terminal developers and industrial facility operators bypasses intermediaries for closed cell formulations with customized density grades. Long-term performance contracting ties supplier payment to verified heat-loss reduction metrics rather than installed volume alone.
- Distributors:Regional stockholding networks serve construction contractors with standardized insulation foam grades requiring rapid job-site delivery and cut-to-size fabrication services.
- Online:Limited penetration concentrated in small-quantity geotechnical fill derivatives and technical documentation access for specification engineers.
- Retail:Minimal presence restricted to specialty building material outlets serving residential renovation contractors with limited foam glass product familiarity.
Direct sales anchors the value base while distributor channels face compression from project finance trends concentrating procurement with capital-backed suppliers capable of underwriting performance guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports finished cellular glass insulation while importing raw cullet feedstock, creating a trade balance shaped by EU F-Gas Regulation enforcement and Central European furnace concentration. The United States runs a modest deficit in cryogenic-grade formulations, sourcing specialized closed-cell densities from Bavarian producers for LNG terminal projects. China balances substantial domestic production with selective importation of high-purity recycled glass powder.
Germany
Industrial renovation codes in commercial buildings mandate rigid cellular insulation with verified fire resistance and moisture immunity. The EU F-Gas Regulation accelerates specification migration from hydrocarbon-blown alternatives toward carbon-nucleated grades. Bavaria hosts GLAPOR Werk Mitterteich GmbH's dedicated furnace network, supplying cryogenic formulations to LNG infrastructure developers.
United States
EPA industrial emissions guidelines and OSHA thermal hazard standards shape certification requirements for high-temperature pipe insulation in petrochemical corridors. The IRA energy-efficiency provisions fund manufacturing facility retrofits, expanding specification of rigid cellular glass for process systems. Texas and Louisiana concentrate demand from LNG terminal developers scaling cryogenic storage procurement.
China
Dual carbon goals and industrial energy-efficiency mandates tighten retrofit requirements across steel and chemical processing facilities. GB standards and MIIT regulations constrain blowing agent chemistry in thermal envelope materials. The Yangtze River Delta clusters manufacturing capacity for construction-grade insulation foam targeting commercial building renovation.
Japan
METI industrial decarbonization programs accelerate replacement cycles for high-temperature process insulation in chemical and semiconductor fabrication facilities. JIS standards verify thermal performance and fire resistance for rigid cellular materials. The Kansai region concentrates demand from petrochemical refineries upgrading vapor barrier systems.
France
Building permit approval now mandates full material disclosure for thermal envelope components under REACH chemical restrictions and EU F-Gas Regulation enforcement. ANSM and CNIL oversight extends to industrial facility environmental compliance. The Provence-Alpes-Côte d'Azur region develops LNG import terminal capacity, specifying closed-cell foam glass for cryogenic storage.
Foam Glass Market Vendor Landscape
On the supply side, the industry is structured around capital-intensive furnace operations that limit supplier base expansion and concentrate production in established manufacturing clusters. Owens Corning leverages cross-material technology bridges between fiberglass and foam-glass systems. Three strategic archetypes dominate: integrated building materials conglomerates with balance-sheet capacity for performance contracting, specialized cellular glass furnace operators with dedicated regional supply networks, and lightweight aggregate specialists serving geotechnical fill niches. Competitive moves center on long-term thermal performance guarantee underwriting and automated furnace quality control system deployment.
Within the specialized furnace operator tier, GLAPOR Werk Mitterteich GmbH and REFAGLASS occupy positions anchored in Central European production geography, representing the dedicated cellular glass manufacturing archetype distinct from diversified materials portfolios. Owens Corning exemplifies the integrated conglomerate model with cross-selling capacity across building envelope systems. AeroAggregates of North America, LLC represents the niche specialization vector, occupying a position in lightweight aggregate derivatives outside conventional insulation channels.
| Leading Market Players |
|---|
| Uusioaines Oy |
| Misapor AG |
| Owens Corning |
| PINOSKLO |
| Shanghai Metal Corporation |
| GLAPOR Werk Mitterteich GmbH |
| REFAGLASS |
| Dehe Technology Group Co., LTD |
| AeroAggregates of North America, LLC |
| Others |
Supply Flow & Price Mechanics
Bavarian furnace concentration anchors margin capture for cryogenic-grade formulations, with GLAPOR Werk Mitterteich GmbH's dedicated cellular glass network commanding premium positioning downstream where LNG terminal developers require 15-20 year performance guarantees.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratifying across certified cryogenic grades, standard industrial densities, and construction commodity volumes. Price differentiation centers on CE marking tier and batch-to-batch quality verification depth, with certified closed-cell formulations holding firm against polyisocyanurate substitution pressure in ambient applications. Cost compression in construction-grade open cell is intensifying because municipal cullet collection volatility feeds raw material uncertainty. EPC contractors show least price sensitivity where bundled performance guarantees de-risk project finance.
Supply Chain Analysis
Dedicated tunnel kiln operators in Germany, the United States, and China hold effective capacity control, with production geography tethered to recycled glass powder sourcing radius and high-temperature furnace engineering expertise scarcity. Input streams rest on post-consumer container cullet, carbon black nucleation agents, and refractory furnace linings requiring specialized thermal process knowledge. Single-source vulnerability concentrates in Bavarian cryogenic-grade supply for transatlantic LNG projects. Distribution runs through direct sales channels for industrial offtake and regional distributor networks serving fragmented construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foam glass sits in early-cycle expansion as EU F-Gas Regulation enforcement redirects industrial procurement from hydrocarbon-blown alternatives, with penetration headroom concentrated in manufacturing facility retrofit mandates tightening across German and US petrochemical corridors.
For Market Incumbents: Harden furnace network utilization through automated thermal imaging quality systems that virtualize batch-to-batch variation management, reducing warranty exposure on cryogenic performance contracts. Deepen backward integration into captive cullet sorting operations to buffer municipal collection volatility. Prioritize certification investment for EPA and OSHA parallel approval pathways to compress transatlantic product launch cycles against refractory engineering skill scarcity. For New Entrants and Emerging Players: Pursue geotechnical fill white space where lightweight aggregate derivatives from manufacturing waste streams escape conventional insulation channel competition. Target civil engineering contractors in soil stabilization and lightweight embankment applications with technical specification support bypassing established thermal envelope procurement workflows. Lead with volume-scale pricing on construction-grade open cell where fire-code jurisdictions exclude polymer foam alternatives. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialized furnace operators possessing regional supply networks but lacking balance-sheet depth for performance guarantee underwriting. Long-term viability frames around 5-10 year industrial retrofit compliance deadlines and carbon-border adjustment mechanism alignment for verified recycled content credentials. Watch EU CBAM implementation pace as inflection signal for competitive repositioning toward low-carbon production verification.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Furnace Quality Control Deployment | Real-time thermal imaging systems reduce cryogenic-grade rejection rates for LNG terminal developers. |
| Backward Integration into Cullet Processing | Captive recycled glass powder supply buffers input cost volatility from municipal collection fluctuations. |
| Long-Term Performance Contract Underwriting | Balance-sheet-backed thermal guarantees displace transactional supply in Texas and Louisiana petrochemical corridors. |
| Geotechnical Fill Channel Development | Lightweight aggregate derivatives from waste streams access civil engineering procurement outside insulation channels. |
| Multi-Jurisdiction Certification Parallel Processing | Simultaneous EPA, OSHA, and CE marking approval compresses launch cycles for new density-grade formulations. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade data, and industry association reports from ACC and Cefic, with input from plant managers at cellular glass furnace operations, procurement leads at LNG terminal developers, EPC contractors in petrochemical corridors, and technical R&D directors at building materials conglomerates. Bottom-up volume modeling triangulates against top-down market sizing across product type, application, and end user segments.
Forecast inputs span closed cell versus open cell formulation mix, cryogenic storage expansion trajectories, and industrial retrofit compliance deadline phasing across the projection horizon. Segmentation modeling incorporates product density grade, end-use industry thermal envelope requirements, and regional regulatory cluster differentiation. CAGRs derive from regression analysis against historical specification cycle data and energy-efficiency mandate enforcement intensity.
Macroeconomic conditions sit as an overlay; deviation in construction activity indices, industrial capital expenditure cycles, or recycled glass collection rates would shift the trajectory. Forecasts reflect documented assumptions regarding EU F-Gas Regulation phase-down pace and carbon-border adjustment mechanism scope expansion. Quarterly review of LNG infrastructure project announcements, municipal cullet pricing, and furnace capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Flat Glass Market
Glass
Glass Mat Thermoplastic Market
Glass
Crystalware and Glassware Market
Glass
Birefringent Crystals Market
Glass
Glass Balustrade Lamination Market
Glass
Insulating Glass Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Asia Pacific Flexible Glass Market
Glass
North America Glass Insulators Market
Glass
Glass Mason Jars Market
Glass
Silica Market
Glass
Solar Control Glass Market
Glass
Glass Reactors Market
Glass
Antibacterial Glass Market
Glass
Soda Feldspar Market
Glass
Sapphire Glass Market