
 Automotive Windshield Adhesives Market | 2026-2036
Automotive Windshield Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Windshield Adhesives Market Insights
German chemical producers is decoupling from commodity adhesive supply chains. Henkel AG & Co. KGaA leverages its polyurethane platform to dominate OEM direct glazing programs. Sika AG anchors its position through automotive-certified one-component systems. Dow Inc. competes on silicone chemistry tailored for heavy-duty truck windshields.
Automotive windshield adhesives are structural bonding agents, typically one-component moisture-curing polyurethanes or two-part epoxies, engineered to achieve shear strengths exceeding 6 MPa while maintaining elasticity across temperature extremes from minus 40 to 90 degrees Celsius. Their primary purpose is to bond glass directly to vehicle frames, enabling windshield retention during rollover events and contributing to cabin structural rigidity. Polyurethane formulations lead volume due to established OEM qualification paths and FMVSS compliance history, while UV-curing technology captures fastest-growing interest by eliminating bake oven bottlenecks at assembly plants. Aftermarket repair shops concentrate margin pools through mobile dispensing equipment and rapid-drive-away chemistries that compress cycle times.
NHTSA administers FMVSS 212 and 208 in the United States, mandating windshield retention under crash loads, while ECE R43 governs safety glazing and installation integrity across Europe. Both frameworks elevate adhesive performance specifications and restrict market access to tested, certified formulations. Stakeholders must monitor regulatory divergence between federal motor vehicle standards and United Nations Economic Commission for Europe protocols when qualifying products for multi-region vehicle platforms.
Market Dynamics
Polyurethane adhesive platforms face intensifying qualification pressure as OEMs consolidate direct glazing programs around crashworthiness-tested chemistries. NHTSA's FMVSS 212 retention mandates and ECE R43 glazing integrity rules are compressing supplier approval timelines while elevating performance thresholds for shear strength and temperature elasticity.
Growth Catalysts
- FMVSS 212/208 Retention Mandates:NHTSA crashworthiness standards require bonded windshields to withstand rollover forces, forcing assembly plants to specify structural-grade polyurethanes over mechanical fasteners.
- Lightweighting Architecture:Unibody designs eliminate A-pillar reinforcements when windshields contribute torsional rigidity, expanding adhesive bonding across premium vehicle platforms.
- Mobile Aftermarket Dispensing:Rapid-cure chemistries enable same-day drive-away service, compressing repair cycle times and expanding margin pools for independent glass shops.
Market Restraints
- Isocyanate Feedstock Volatility:MDI and polyol price swings squeeze formulation margins, particularly for small-batch aftermarket producers lacking volume hedging.
- German Chemical Concentration:Three producers control 70% of automotive-qualified polyurethane platforms, creating qualification bottlenecks for new market entrants.
- UV-Curing Technical Limitations:Shadow-cure failures in complex windshield geometries restrict UV technology to flat-glass truck applications, blocking passenger car penetration.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for advanced manufacturing attract adhesive formulators to establish localized supply for domestic OEM expansion.
- Silicone-PU Hybrid Convergence:Heavy-duty truck manufacturers combine silicone weathering resistance with polyurethane structural strength for extreme-climate applications.
- Direct-to-Fleet Digital Channels:Commercial vehicle operators bypass traditional distribution through qualified e-procurement platforms, disintermediating regional distributors.
Industry Challenges
- Adhesion Engineer Scarcity:OEM qualification teams lack specialists versed in both polymer rheology and crash simulation protocols, extending validation timelines.
- Multi-Regulatory Certification Burden:Parallel FMVSS and ECE homologation testing duplicates expenditure for platforms serving both North American and European vehicle programs.
- Bake Oven Integration Complexity:Legacy assembly plants retrofitting moisture-cure lines face capital constraints and floor-space limitations incompatible with greenfield direct glazing layouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Windshield Adhesives Market |
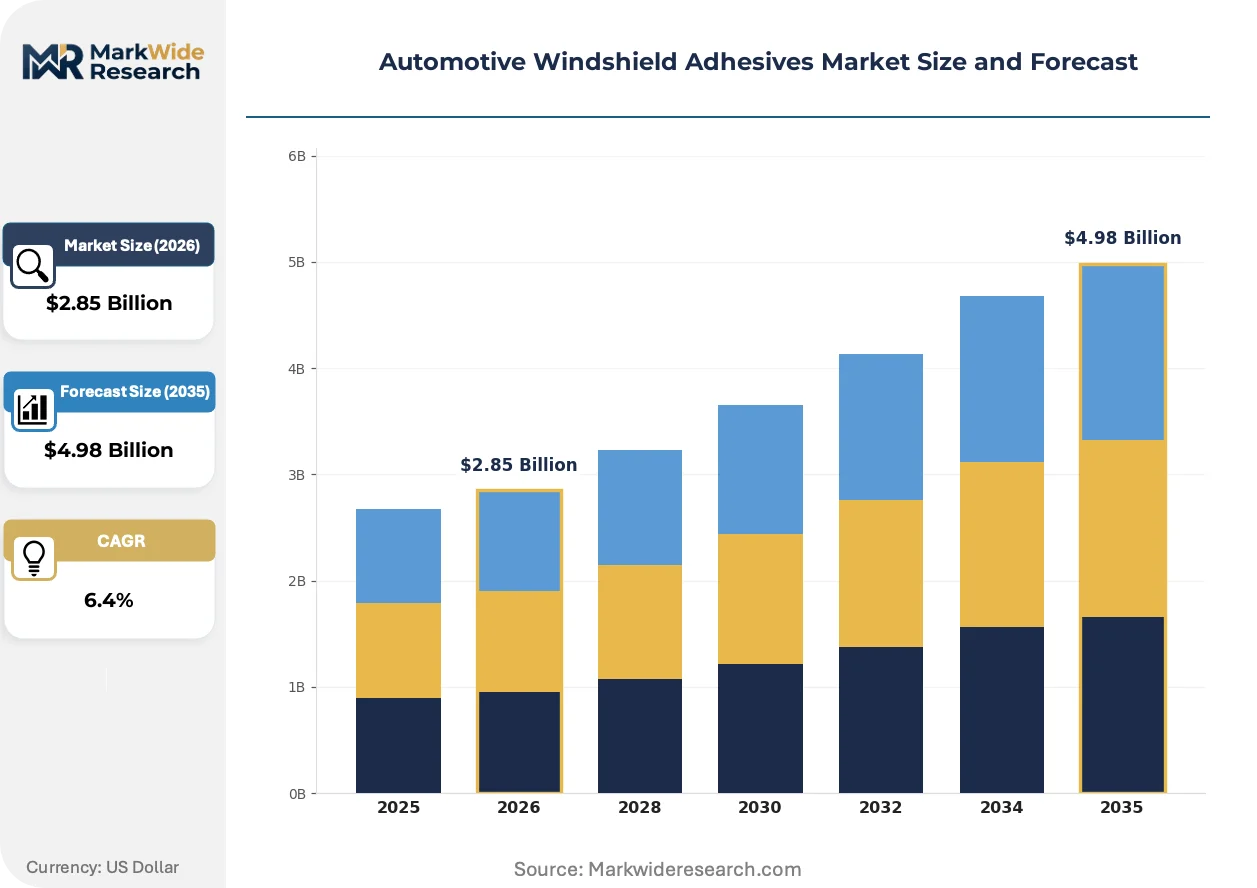
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Silicone, Polyvinyl Acetate, Epoxy End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Technology: Thermal Curing, UV Curing, Chemical Curing, Water-Based Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Buses |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, Sika AG, Dow Inc., Bostik SA, H.B. Fuller Company, PPG Industries, Inc., Illinois Tool Works Inc., Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Windshield Adhesives Market Trends and Innovations
UV-curing adhesive systems are compressing automotive assembly timelines by eliminating thermal bake cycles. This technology convergence is redrawing competitive boundaries between established moisture-cure suppliers and photochemistry specialists.
Photoinitiator-activated polyurethane systems is rewriting production economics at high-volume assembly plants. Tier 1 glazing suppliers in Germany and the United States are piloting UV lines for flat-glass truck windshields. The technology eliminates 45-minute bake oven bottlenecks, enabling line-speed increases that moisture-cure chemistry cannot match.
REACH Annex XIV authorization requirements for isocyanate-containing preparations are tightening occupational exposure protocols across European adhesive manufacturing. Formulators must implement closed-transfer systems and enhanced respiratory protection. Small-batch aftermarket producers face disproportionate compliance costs relative to integrated chemical majors with captive safety infrastructure.
Fleet operators now specify certified-installer networks with documented FMVSS 212 compliance rather than lowest-bid glass replacement. Commercial vehicle leasing companies in North America audit adhesive lot numbers and cure-time documentation. This verification-driven procurement favors national service chains with centralized quality systems over fragmented independent shops lacking traceability infrastructure.
Automotive Windshield Adhesives Market Segmentation
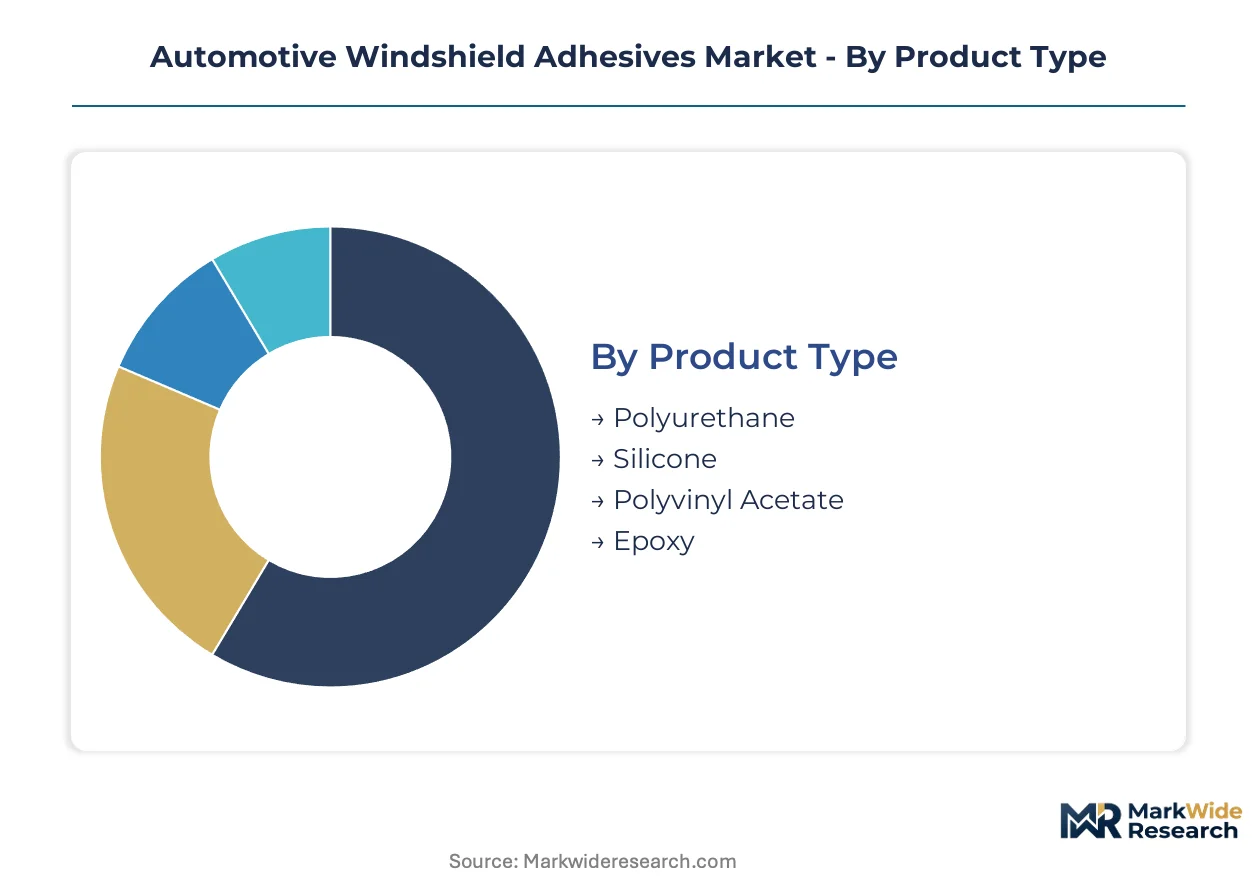
Adhesive formulators calibrate product portfolios against divergent qualification thresholds across OEM assembly lines and aftermarket service channels. Segment boundaries reflect distinct technical specifications, curing infrastructure requirements, and regulatory compliance burdens that reshape competitive positioning.
Product Type:
Polyurethane platforms command disproportionate supply-side investment due to established OEM qualification paths and crashworthiness certification history.
- Polyurethane:One-component moisture-curing formulations dominate structural glazing applications, achieving shear strengths above 6 MPa across temperature extremes. German OEMs specify these systems for direct bonding programs that eliminate mechanical fasteners. Polyurethane absorbs the bulk of installed capacity; UV-curing hybrids are expanding most quickly.
- Silicone:Weathering-resistant chemistry anchors heavy-duty truck applications where thermal cycling durability outweighs structural modulus requirements. North American fleet operators specify silicone-PU hybrids for extreme-climate routes through Arizona and Alberta.
- Polyvinyl Acetate:Water-based formulations serve non-structural interior bonding with lower capital equipment requirements.
- Epoxy:Two-part systems capture niche applications demanding maximum rigidity and chemical resistance.
Formulation margins concentrate in polyurethane platforms where raw material hedging and scale economies favor integrated chemical producers.
End User:
Customer type determines pricing architecture through volume scale, technical service intensity, and certification documentation requirements.
- OEMs:Direct glazing programs at high-volume assembly plants specify pre-approved adhesive platforms with locked formulation recipes. NHTSA FMVSS 212 compliance documentation accompanies every lot shipment. OEMs absorb the bulk of installed capacity; repair shops are expanding most quickly.
- Aftermarket Providers:National service chains invest in mobile dispensing equipment and rapid-cure chemistries that compress drive-away times. Fleet operators now audit adhesive lot numbers and cure documentation, favoring centralized quality systems.
- Vehicle Assemblers:Contract manufacturers serving niche vehicle platforms face compressed supplier approval timelines.
- Repair Shops:Independent operators concentrate margin pools through same-day service capabilities and localized customer relationships.
Aftermarket channels are capturing share fastest as fleet procurement shifts toward verified-installer networks with documented compliance trails.
Technology:
Curing mechanism selection hinges on assembly line speed requirements, capital equipment availability, and substrate geometry complexity.
- Thermal Curing:Conventional moisture-cure chemistry relies on bake oven infrastructure that dominates legacy assembly plants. Bake cycles extend 45 minutes, creating line-speed bottlenecks that UV alternatives target.
- UV Curing:Photoinitiator-activated systems eliminate thermal bottlenecks and enable line-speed increases for flat-glass truck windshields. Shadow-cure limitations in complex passenger car geometries restrict penetration. Thermal curing absorbs the bulk of installed capacity; UV curing is climbing the fastest.
- Chemical Curing:Two-part systems serve repair applications where portable mixing equipment replaces fixed infrastructure.
- Water-Based:Reduced volatile organic compound profiles align with tightening occupational exposure protocols under REACH Annex XIV.
Capital constraints at brownfield facilities are slowing UV adoption despite compelling throughput economics.
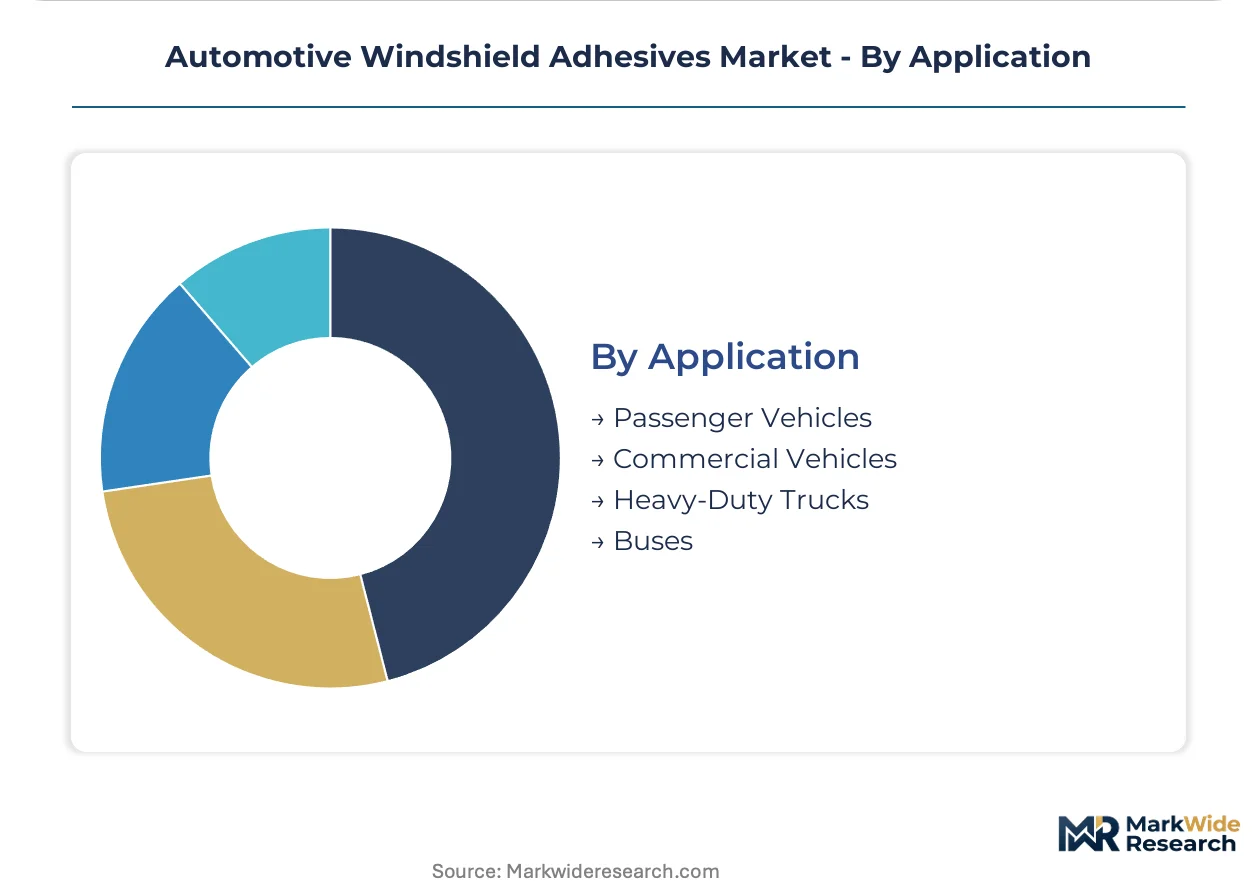
Application:
Vehicle category dictates performance specifications for structural contribution, weathering exposure, and regulatory testing protocols.
- Passenger Vehicles:Unibody designs leverage bonded windshields for torsional rigidity, eliminating A-pillar reinforcements. Premium German automakers specify high-performance direct glazing systems with documented ECE R43 compliance.
- Commercial Vehicles:Heavy-duty cycles demand combined structural strength and weathering resistance. Silicone-PU hybrid formulations are gaining specification for extreme-climate routes. Passenger vehicles absorb the bulk of installed capacity; heavy-duty trucks are gaining share fastest.
- Heavy-Duty Trucks:Flat-glass geometries suit UV-curing pilot lines, enabling throughput advantages unavailable in curved passenger windshields.
- Buses:Large-surface bonding requirements favor established moisture-cure platforms with proven field performance records.
Commercial vehicle specifications are diverging toward hybrid chemistries that combine structural and weathering performance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane feedstock production clusters in the Rhine-Ruhr corridor anchor European supply for automotive adhesive qualification. This concentration shapes regional competitive dynamics across three continents where OEM assembly plants source certified structural bonding platforms.
Germany
Premium automakers in Stuttgart and Munich specify high-performance direct glazing systems with documented ECE R43 compliance. KBA vehicle-type approval procedures mandate crash-tested adhesive formulations for bonded windshields. The Rhine-Ruhr chemical corridor hosts integrated producers supplying moisture-cure polyurethane platforms to assembly plants across Bavaria and Baden-Württemberg.
United States
Detroit-area OEMs and Southern transplant assembly plants absorb structural-grade polyurethane volumes for unibody designs eliminating A-pillar reinforcements. NHTSA administers FMVSS 212 and 208 retention mandates requiring bonded windshields to withstand rollover forces. Michigan and Tennessee production corridors concentrate adhesive dispensing equipment suppliers serving high-volume truck and passenger vehicle lines.
China
Domestic OEM expansion and joint-venture assembly plants drive specification of localized adhesive platforms meeting GB standards for safety glazing. MIIT oversees vehicle certification protocols that incorporate windshield retention testing. Yangtze River Delta automotive clusters in Shanghai and Jiangsu province attract international formulators establishing regional technical centers.
India
Tamil Nadu and Maharashtra vehicle assembly corridors expand bonded windshield adoption as domestic OEMs upgrade to structural glazing architectures. PLI scheme incentives for auto component manufacturing attract adhesive formulators to establish localized supply. Haryana and Gujarat emerging production hubs concentrate aftermarket service networks with mobile dispensing capabilities.
Japan
Kanto and Chubu regional OEMs maintain stringent qualification protocols for direct glazing systems contributing to cabin structural rigidity. METI coordinates industrial standards alignment with international crashworthiness frameworks. Aichi Prefecture automotive clusters sustain demand for high-reliability polyurethane platforms with proven temperature elasticity performance.
Automotive Windshield Adhesives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue UV-curing technology and silicone-PU hybrid formulations outside legacy qualification paths. Three German chemical majors control approximately seventy percent of automotive-qualified polyurethane platforms, creating tiered supply dynamics. Strategic archetypes include integrated chemical conglomerates with captive feedstock security, specialized adhesive formulators with OEM technical service depth, and regional compounders serving aftermarket channels. Competitive moves concentrate on qualification timeline acceleration and geographic expansion through technical center establishment.
Among diversified chemical conglomerates, Henkel AG & Co. KGaA, Sika AG, and Dow Inc. exemplify distinct strategic positioning within the adhesive tier. Henkel occupies a position representing integrated polyurethane platform dominance through OEM direct glazing program penetration. Sika exemplifies specialized formulator archetype with automotive-certified one-component system focus. Dow anchors the silicone chemistry vector for heavy-duty applications where weathering resistance requirements diverge from passenger car specifications.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| Sika AG |
| Dow Inc. |
| Bostik SA |
| H.B. Fuller Company |
| PPG Industries, Inc. |
| Illinois Tool Works Inc. |
| Arkema Group |
| Others |
Pricing and Supply Chain Analysis
Captive polyurethane feedstock production in the Rhine-Ruhr corridor anchors both supply security and pricing power for German chemical majors serving OEM direct glazing programs. This backward integration into MDI and polyol manufacturing insulates integrated producers from commodity volatility while compressing margins for aftermarket compounders lacking volume hedging capabilities.
Pricing Analysis
Warranty-backed installation service bundles separate national service chains from independent repair shops in aftermarket procurement. Three-tier pricing structure across premium OEM-certified, standard aftermarket, and economy generic levels reflects certification grade and cure-time documentation intensity. Cost compression in economy tiers is intensifying because REACH Annex XIV compliance costs disproportionately burden small-batch producers. Fleet operators exhibit lowest price sensitivity due to documented FMVSS 212 compliance requirements, while independent glass shops face acute margin pressure from rapid-cure chemistry investments.
Supply Chain Analysis
India PLI scheme domestic-content mandates are reshaping sourcing patterns for adhesive formulators establishing localized technical centers. Manufacturing gravity centers on Germany, China, and the United States, with the Yangtze River Delta and Tennessee production corridors expanding fastest. Raw material supply rests on MDI isocyanates, specialty polyols, and photoinitiator chemicals. Single-source vulnerability concentrates in German-qualified polyurethane platforms. Distribution runs through Tier 1 glazing suppliers and national aftermarket chains with centralized quality systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over isocyanate feedstock and captive safety infrastructure determines qualification timeline acceleration. Players are pursuing backward integration into polymer manufacturing to defend margin position against commodity volatility.
For Market Incumbents: Hedge against UV-curing technology disruption by piloting photoinitiator-activated lines alongside moisture-cure platforms. Accelerate certification investment in silicone-PU hybrid formulations before heavy-duty truck specifications diverge. Lock in long-term offtake agreements with MDI producers to secure feedstock position against price swings squeezing smaller competitors. For New Entrants and Emerging Players: UV-curing technology for flat-glass truck applications offers the most penetrable wedge against established polyurethane qualification paths. Target India's Tamil Nadu and Maharashtra corridors where PLI incentives lower capital barriers for localized supply. Bypass German qualification bottlenecks by partnering with domestic OEMs on GB-standard platforms in China's Yangtze River Delta. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated chemical conglomerates seeking automotive adhesive platform expansion. Long-term viability hinges on regulatory compliance infrastructure rather than formulation chemistry alone. Watch for NHTSA-ECE regulatory divergence as the inflection signal that multi-homologation capabilities will command acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Feedstock | Captive MDI supply insulates Henkel and Sika from commodity price volatility squeezing aftermarket competitors. |
| UV-Curing Pilot Line Deployment | Eliminating 45-minute bake oven bottlenecks enables throughput gains for flat-glass truck windshields at Tennessee assembly plants. |
| Silicone-PU Hybrid Formulation Development | Combining structural modulus with weathering resistance addresses extreme-climate specifications for Arizona-Alberta fleet routes. |
| India Technical Center Establishment | PLI scheme incentives attract localized supply for Tamil Nadu OEM expansion away from German qualification bottlenecks. |
| Certified-Installer Network Consolidation | Fleet audit requirements for adhesive lot traceability favor national chains with centralized quality systems over fragmented independents. |
Research Methodology
Trade databases, SEC 10-K filings, and vehicle production registries formed the secondary backbone, supplemented by customs records tracking MDI and polyol import flows. Primary interviews with Tier 1 glazing supplier procurement teams, OEM platform engineers, aftermarket distributor operations heads, and adhesive formulator technical directors validated demand assumptions. Bottom-up and top-down triangulation cross-checked adhesive volume estimates against windshield installation counts and assembly line throughput data.
Bottom-up modeling anchored forecasts to individual OEM platform specifications and aftermarket service channel expansion rates. Segmentation dimensions included adhesive chemistry type, curing technology, vehicle application class, and regional production cluster. CAGRs were derived from fitted growth curves against qualification timeline acceleration and regulatory compliance burden trajectories. Forecast inputs incorporated NHTSA FMVSS 212 enforcement intensity and ECE R43 homologation testing expansion.
Several conditions sit outside the modeled scope, including unforeseen raw material supply disruptions, abrupt regulatory standard divergence between federal and UN-ECE frameworks, and breakthrough alternative bonding technologies displacing polyurethane platforms. Forecasts reflect documented assumptions regarding OEM consolidation of direct glazing programs and aftermarket fleet procurement audit adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Floor Adhesive Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
South Africa Adhesives Market
Adhesives & Sealants
Latex Binders Market
Adhesives & Sealants
Acetate Silicone Sealant Market
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
Thailand Adhesives Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market