
 Glass Recycling Market | 2026-2036
Glass Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Recycling Market Intelligence
Demand from large-scale food and beverage container manufacturers is consolidating around suppliers who can guarantee high-purity cullet. This shift benefits vertically-integrated producers like O-I Glass Inc., which controls significant portions of its raw material stream. Ardagh Group leverages its extensive collection and processing network to serve these concentrated buyers. Meanwhile, Veolia operates across multiple stages of the value chain, from collection to processing, to meet stringent quality requirements.
Glass recycling involves processing waste glass into a furnace-ready raw material known as cullet. The process requires advanced optical sorting to separate glass by color—flint (clear), amber, and green—to meet manufacturing specifications. Its primary purpose is to displace virgin raw materials like sand and soda ash in glass production. Container glass represents the largest product segment, driven by persistent demand from the packaging industry for bottles and jars.
Regulatory frameworks, including mandates from the US EPA and targets within the EU Green Deal, are setting higher recycled content requirements for packaging. In parallel, China's dual carbon goals promote recycling as a method to lower the energy intensity of glass manufacturing. Success for processors and manufacturers will ultimately depend on securing consistent, high-purity feedstock streams through effective collection systems.
Market Dynamics
The central dynamic in the glass recycling market is the tension between regulatory mandates for increased recycled content and the stringent purity requirements of end-users. This pressure from frameworks like the EU Green Deal is compelling large container manufacturers to secure high-quality cullet, concentrating demand around processors with advanced sorting capabilities.
Growth Catalysts
- Regulatory Mandates:Policies such as the EU's Circular Economy Action Plan are establishing binding targets for recycled content in packaging, creating a guaranteed, long-term demand signal for processed cullet.
- Corporate ESG Commitments:Food and beverage brand owners are voluntarily increasing recycled glass in their packaging to meet sustainability goals and appeal to environmentally conscious consumers, directly boosting cullet demand.
- Advanced Sorting Technology:The deployment of optical and digital sorting systems enables processors to produce color-separated, high-purity cullet that meets the precise specifications of glass furnace operations.
Market Restraints
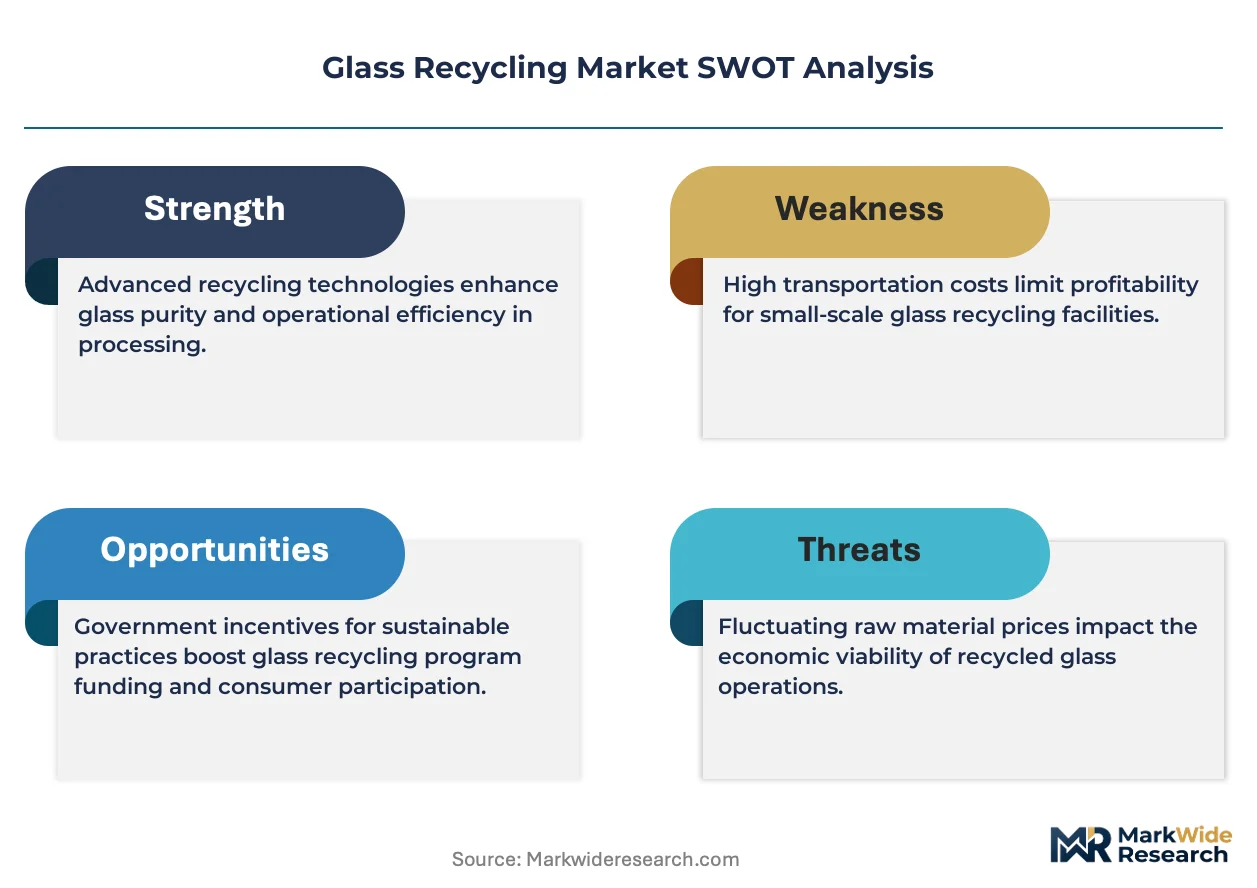
- Feedstock Inconsistency:Municipal collection systems often yield mixed-quality feedstock with high contamination rates, creating a structural bottleneck that limits the supply of usable glass for recycling.
- Contaminant Removal Costs:The presence of ceramics, stones, metals, and plastics in collected glass requires costly and energy-intensive processing to prevent defects and furnace damage, impacting processor margins.
- Substitution from Virgin Materials:In regions with abundant and inexpensive raw materials like sand and soda ash, the economic incentive to use recycled cullet diminishes, especially when collection and processing costs are high.
Strategic Opportunities
- Infrastructure Expansion in North America:The United States presents a significant opportunity for growth through the wider implementation of deposit-return systems (DRS) and curbside collection programs to improve collection rates and feedstock quality.
- New End-Use Applications:Expanding the use of processed glass into non-container applications, such as construction aggregates, reflective paints, and filtration media, can create new revenue streams for lower-grade cullet.
- Emerging EPR Frameworks:The adoption of Extended Producer Responsibility (EPR) legislation in new jurisdictions creates financial incentives for producers to design for recyclability and fund the development of collection infrastructure.
Industry Challenges
- Capital Investment for Modernization:Upgrading processing facilities with advanced optical sorting and AI-driven robotics requires significant capital expenditure, posing a barrier for smaller, independent recyclers.
- Logistical Hurdles:The high weight and low value of raw waste glass make transportation from dispersed collection points to centralized processing plants a significant operational and cost challenge.
- Lack of Global Standards:The absence of universally accepted quality standards for furnace-ready cullet complicates international trade and creates friction for manufacturers sourcing material from different regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Recycling Market |
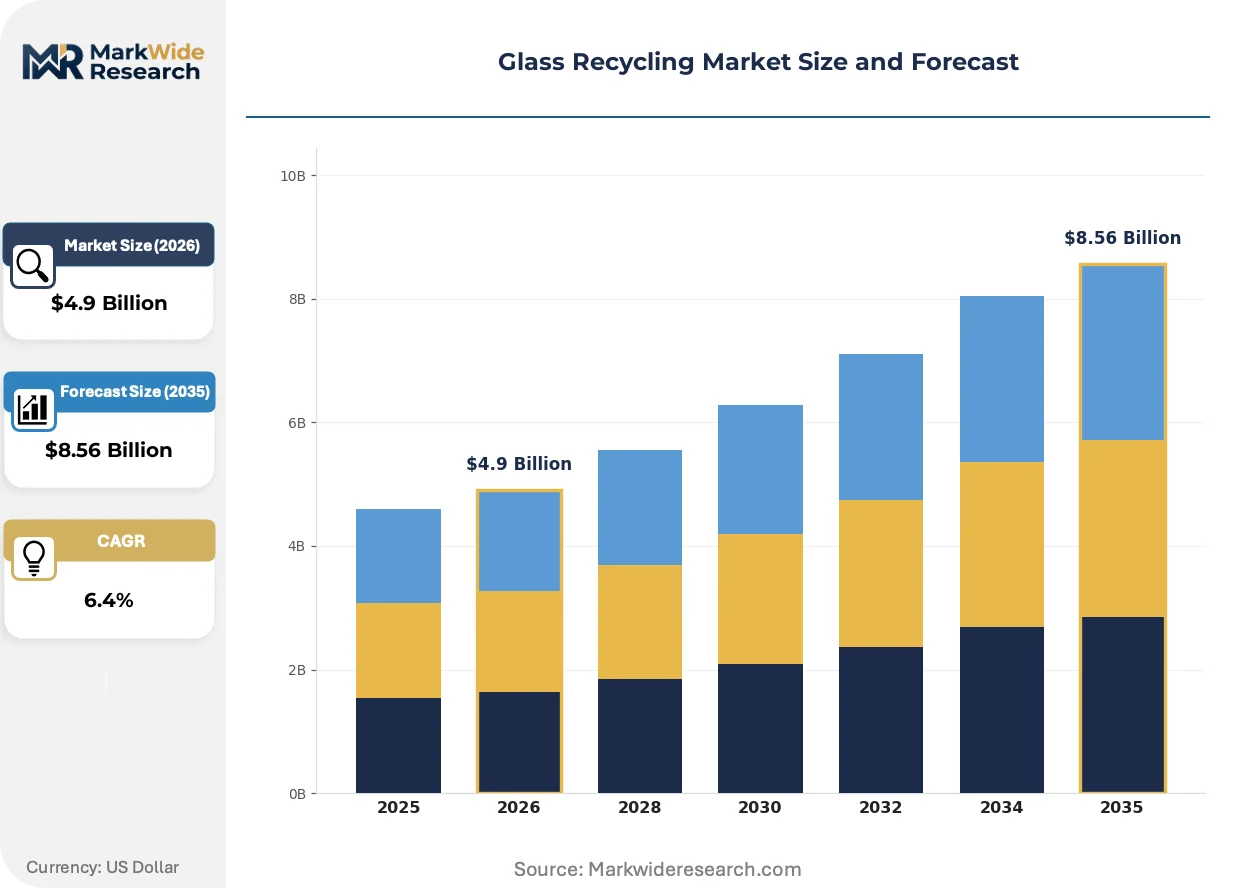
| Market Size in 2026 | $4.9 Billion |
| Market Size in 2035 | $8.56 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Container Glass, Flat Glass, Fiberglass, Specialty Glass, Laboratory Glass Collection Method: Curbside Pickup, Drop-off Centers, Deposit Return Systems, Commercial Collection, Reverse Vending Machines End Use Industry: Building & Construction, Automotive Manufacturing, Electronics Production, Consumer Goods, Packaging Industry Processing Technology: Crushing, Sorting, Melting, Purification, Re-molding |
| Companies Covered | Veolia, O-I Glass Inc, Strategic Materials Inc., Verallia, Momentum Recycling, Ardagh Group, Sibelco, Vetropack Holding AG, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Recycling Market Strategic Shifts & Innovations
Technological advancements in sorting and purification are fundamentally altering the value proposition of recycled glass. The market is shifting from a waste management focus to a raw material production model, driven by the need for consistent, high-purity inputs for industrial manufacturing.
AI-powered optical sorting is a key technological driver, using advanced sensors and machine learning algorithms to identify and eject contaminants with extreme precision. Large-scale processors supplying the beverage container industry are rapidly adopting this equipment to meet stringent quality demands. This technology is rewriting the operational playbook for recyclers, enabling the production of furnace-ready cullet that can directly displace virgin materials at scale.
Regulatory action, such as China's dual carbon goals, is creating powerful incentives for industrial decarbonization. This policy directly encourages energy-intensive sectors like glass manufacturing to increase their use of recycled cullet, which melts at a lower temperature than virgin raw materials. As a result, both container and flat glass producers in China are now compelled to build more resilient and high-volume cullet supply chains.
A significant behavioral shift is underway as major food and beverage brand owners transition from transactional cullet purchases to strategic, long-term supply agreements. This change disrupts the role of spot-market brokers and favors larger, certified processors capable of guaranteeing volume and quality. The pattern is most pronounced in Europe, where manufacturers in Germany and France must secure feedstock to comply with EU recycled content mandates.
Glass Recycling Market Segmentation
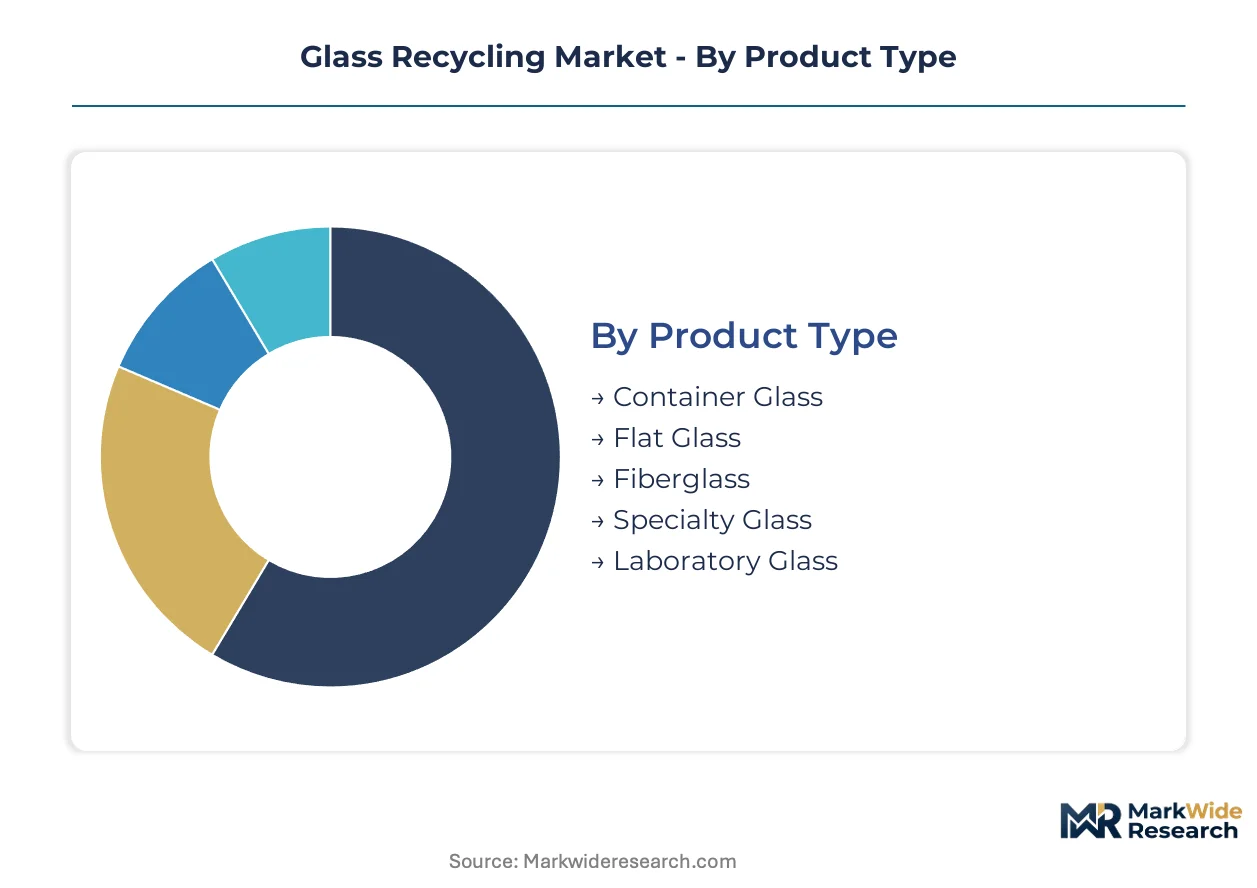
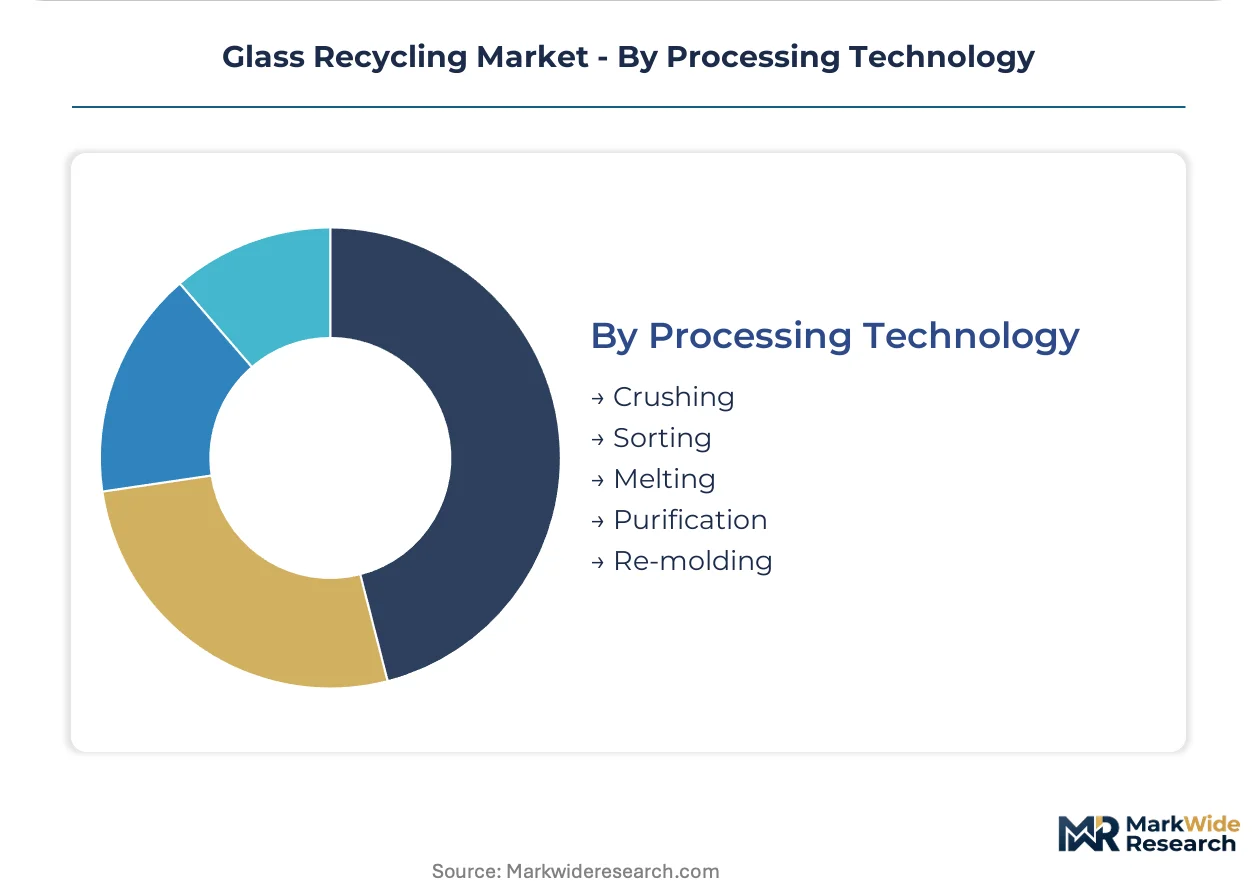
The Glass Recycling Market exhibits diverse characteristics across various dimensions, reflecting distinct operational requirements, material specifications, and end-user demands. Understanding these segmentation categories is crucial for identifying targeted growth opportunities and addressing specific logistical or technological challenges within the value chain.
Product Type:
This category delineates the different forms of glass that undergo recycling, ranging from those integrated into complex products to standalone packaging solutions.
- Container Glass:This segment includes bottles and jars primarily used in the food and beverage industry, representing the largest volume of recycled glass globally. Demand is concentrating in European nations like Germany, driven by stringent EU Green Deal recycled content mandates.
- Flat Glass:Comprising windows, mirrors, and automotive glass, this product type requires careful separation due to potential coatings or laminates. Procurement is shifting towards dedicated collection points in urban centers to ensure purity for new construction applications.
- Fiberglass:Recycled fiberglass, often from insulation or composite materials, requires specific processing to remove binders and contaminants. Its use is expanding in construction and industrial applications where material properties can be maintained.
- Specialty Glass:This segment encompasses high-performance glass types, such as laboratory glassware or optical fibers, demanding highly specialized sorting and purification methods.
- Laboratory Glass:Waste from scientific and medical laboratories, including beakers and test tubes, typically requires sterilization and careful handling before recycling into non-critical applications.
Container Glass leads volumes today; Flat Glass is gaining share fastest.
Collection Method:
This category highlights the varying efficiency and purity outcomes associated with different approaches to gathering waste glass from consumers and businesses.
- Deposit Return Systems:These systems incentivize consumers to return glass containers for a refund, yielding high-purity, color-separated cullet with minimal contamination. Demand for this high-quality feedstock is strong from large container manufacturers in countries with established DRS, such as Germany.
- Curbside Pickup:Widely adopted in municipalities, this method collects mixed recyclables, including glass, directly from households, often leading to higher contamination rates. North American processors face significant sorting challenges with this mixed-stream input.
- Drop-off Centers:Consumers transport their glass waste to designated community sites, which can result in better quality glass than curbside collection if color separation is encouraged. These centers serve as a critical collection point in regions without comprehensive curbside programs.
- Commercial Collection:This involves waste glass collection directly from businesses like restaurants, bars, and hotels, often providing a cleaner, more consistent stream.
- Reverse Vending Machines:Automated machines that accept empty beverage containers and dispense a deposit refund, offering a high-tech solution for clean glass collection in urban environments.
The market is prioritizing methods that deliver cleaner feedstock, with Deposit Return Systems offering the most consistent quality.
End Use Industry:
This segment categorizes the primary industries consuming recycled glass, each with distinct quality requirements and volume demands.
- Packaging Industry:This sector uses recycled cullet extensively for manufacturing new bottles and jars, driven by circular economy goals and consumer preference for sustainable packaging. Demand from this industry is foundational for the entire glass recycling market.
- Building & Construction:Recycled glass finds applications in construction aggregates, insulation, and decorative elements, utilizing both high-purity and lower-grade cullet. The US EPA encourages its use in road building and other infrastructure projects.
- Automotive Manufacturing:Recycled glass is incorporated into new automotive glass and fiberglass components, contributing to sustainability targets within the vehicle production lifecycle.
- Electronics Production:Specialized recycled glass can be used in certain electronic components or as a filler material, though volumes are generally smaller compared to other sectors.
- Consumer Goods:This segment includes various applications for recycled glass in household items, art, and decorative products, often utilizing aesthetically pleasing cullet.
The Packaging Industry remains the dominant end-user; Building & Construction offers significant potential for lower-grade cullet.
Processing Technology:
This category details the various technological steps involved in transforming waste glass into furnace-ready cullet or other usable forms.
- Sorting:Advanced optical and AI-powered sorting systems are crucial for separating glass by color and removing contaminants like ceramics, stones, and metals. This technology is critical for meeting the stringent purity requirements of container glass manufacturers.
- Melting:This process involves heating cullet in furnaces to produce new glass products, requiring less energy than melting virgin raw materials like sand and soda ash. China's dual carbon goals directly incentivize increased cullet melting in glass production.
- Crushing:Mechanical crushing reduces waste glass into smaller, more manageable pieces, preparing it for subsequent sorting, washing, or direct use as aggregate.
- Purification:This stage involves further cleaning and contaminant removal using methods such as air classification, density separation, or magnetic separation to achieve high-purity cullet.
- Re-molding:This technology involves reshaping melted glass into new products, often used for specialty items or artistic applications, rather than large-scale container production.
Sorting technologies are rapidly advancing; Melting remains the core transformational process.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced deposit-return systems provide a stark contrast to the United States' more fragmented curbside collection, influencing regional cullet purity and supply dynamics. The market's expansion is driven by both stringent environmental regulations and corporate sustainability targets across various continents. This global demand for recycled glass necessitates localized collection and processing infrastructure development.
Germany
Demand for high-purity cullet in Germany is consistently strong, propelled by the EU Green Deal's circular economy mandates for packaging. The country's established deposit-return systems ensure a clean, color-separated feedstock stream. Major glass manufacturers in the Rhineland and Bavaria actively source this premium cullet for new container production.
United States
The United States market is undergoing a transformation, with demand for recycled glass increasing due to corporate ESG commitments. The US EPA encourages the use of recycled content in packaging and infrastructure projects. States like Oregon and Michigan are expanding deposit-return systems to improve feedstock quality and collection rates.
China
China's dual carbon goals are a significant driver for increased glass recycling, compelling energy-intensive industries to adopt more sustainable practices. This policy directly incentivizes glass manufacturers to use more cullet, which lowers furnace energy consumption. Industrial clusters in the Yangtze River Delta are actively investing in advanced sorting technologies.
France
Recycled content mandates from the EU Green Deal are reshaping procurement patterns for French container glass manufacturers. Strategic, long-term supply agreements for high-purity cullet are becoming common. Companies in the Grand Est region are working to enhance collection networks and processing capabilities.
Glass Recycling Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered competitive structure within the glass recycling market. Vertically integrated players control collection, processing, and often glass manufacturing, ensuring a captive supply of high-quality cullet. Technology specialists focus on advanced sorting and purification, offering their services to various market participants. Competitive moves include strategic partnerships to secure feedstock and investments in processing capacity expansion.
At the integrated end of the value chain, O-I Glass Inc. exemplifies a manufacturer with significant upstream control over its raw material stream, ensuring consistent cullet quality for its extensive container production. Ardagh Group, another prominent player, leverages its vast collection and processing network to serve large-scale demand. Veolia occupies a position as a comprehensive environmental services provider, operating across multiple stages from collection to advanced cullet processing.
| Leading Market Players |
|---|
| Veolia |
| O-I Glass Inc. |
| Strategic Materials Inc. |
| Verallia |
| Momentum Recycling |
| Ardagh Group |
| Sibelco |
| Vetropack Holding AG |
| Owens Corning |
| Others |
Cost & Logistics Intelligence
Virgin raw material prices, particularly for soda ash and sand, cascade through the glass recycling supply chain, influencing the economic viability and pricing tiers for cullet. This dynamic creates pressure on processors to optimize costs against fluctuating commodity markets.
Pricing Analysis
Capacity additions in North America are reshaping price floors for lower-grade cullet, driven by increased collection but inconsistent quality. The dominant pricing structure is contract-based long-term offtake for high-purity cullet, alongside commodity spot pricing for mixed or lower-grade materials. Price differentiation stems from purity grade, with color-separated furnace-ready cullet commanding a premium, and geographic delivery costs impacting regional pricing. Pricing pressure stems from the high cost of contaminant removal for mixed-stream feedstock. The packaging industry exhibits the least price sensitivity for high-purity cullet, while the building and construction sector remains highly sensitive for aggregates.
Supply Chain Analysis
Waste glass feedstock supply rests on a fragmented global collection infrastructure, with significant dependencies on municipal systems and deposit-return programs. Geographic supply concentration is notable in Germany due to established DRS, and increasingly in China due to dual carbon goals. Key raw material dependencies include waste glass feedstock and advanced optical sorting technology for processing. A structural risk is feedstock inconsistency, leading to higher processing costs and limiting the supply of furnace-ready cullet. Downstream distribution runs through direct supply agreements between processors and glass manufacturers, supplemented by aggregators for non-container cullet applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glass recycling market presents a geographic-arbitrage play, as European nations benefit from high-purity cullet due to stringent regulations, while North America faces higher processing costs from mixed-stream collection.
For Market Incumbents:Anticipate continued regulatory pressure for recycled content, driving the need for significant capital investment in advanced sorting technologies. Secure long-term supply agreements with collection networks to mitigate feedstock inconsistency, a persistent threat to quality. Vertically integrate collection and processing capabilities to ensure a captive supply of high-purity cullet. Invest in R&D for new end-use applications for lower-grade cullet, expanding market opportunities beyond container glass.
For New Entrants and Emerging Players:AI-powered optical sorting presents a technology-first wedge, enabling entrants to offer superior purity cullet to manufacturers. Target underpenetrated North American markets, particularly regions expanding deposit-return systems or improving curbside collection. Focus on establishing localized collection and processing hubs to reduce logistical hurdles and improve feedstock quality. A go-to-market angle involves partnering with municipalities to upgrade collection infrastructure and demonstrate economic benefits of higher-purity output.
For Investors and Strategic Acquirers:Asymmetric upside sits with technology specialists in advanced sorting and regional processors with strong collection networks, given the long-term viability driven by circular economy mandates. Acquisition targets should include firms capable of producing furnace-ready cullet from challenging feedstock streams. A signal to watch is the adoption rate of Extended Producer Responsibility (EPR) frameworks in new jurisdictions, which creates financial incentives for collection infrastructure development and boosts demand for recycled content.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Optical Sorting | Enhances cullet purity, meeting stringent manufacturer specifications and displacing virgin materials. |
| Secure Long-term Feedstock Agreements | Guarantees consistent supply of raw material, stabilizing production for glass manufacturers. |
| Expand Deposit-Return Systems (DRS) | Improves collection rates and feedstock quality, reducing processing costs for recyclers. |
| Develop New End-Use Applications | Creates revenue streams for lower-grade cullet, diversifying market demand beyond packaging. |
| Backward Integration into Collection | Provides greater control over feedstock quality and supply, optimizing material flow. |
Research Approach
Direct dialogue with glass manufacturers, recycling facility operators, packaging brand owners, and municipal waste managers informed the qualitative grounding for this analysis. This primary research was rigorously validated through comprehensive secondary data sources, including EU Green Deal reports, US EPA publications, industry association reports, and corporate sustainability filings. The analysis employed both bottom-up and top-down triangulation to ensure robust data integrity across all market segments.
Volume and value outputs from the quantitative model were derived using a multi-factor analytical framework, projecting market trajectories across the analysis window. The framework modeled segmentation dimensions such as product type, collection method, end-use industry, processing technology, and regional regulatory environment. Compound Annual Growth Rates were derived from historical trends, projected technology adoption rates, and anticipated shifts in regulatory enforcement. Key forecast inputs included recycled content mandates and virgin material pricing trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to shifts in regulatory enforcement, technological breakthroughs in virgin material production, and global economic stability. Forecasts reflect assumptions regarding sustained commitment to circular economy principles and continued investment in recycling infrastructure. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Birefringent Crystals Market
Glass
Glass Lens Market
Glass
Silica Sand for Glass Making Market
Glass
Middle-East and Africa Flat Glass Market
Glass
Glass Grade Dolomite Market
Glass
Latin America Flat Glass Market
Glass
Antibacterial Glass Market
Glass
Fiberglass Window Market
Glass
North America Flat Glass Market
Glass
Glass Block Market
Glass
Global Flat Glass Market
Glass
North America Industrial Silica Sand Market
Glass
Pharma Glass Tubing Market
Glass
3D Glass Substrate Market
Glass
Asia-Pacific Glassware Market
Glass
Middle East and Africa Glassware Market