
 North America Flat Glass Market | 2026-2036
North America Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flat Glass Market Analytics
The price-performance gap between premium solar-control coatings and commodity clear float is hardening across specification channels. Saint-Gobain leverages integrated float-coating operations to sustain margin capture in high-performance architectural segments. Guardian Glass LLC anchors its position through geographic dominance in the U.S. Midwest manufacturing corridor. Cardinal Glass Industries, Inc. differentiates via regional fabrication networks that compete on lead-time reliability for custom insulated units.
Flat glass comprises silica-sand-based soda-lime sheets produced by the float process, typically ranging from 2 mm to 25 mm in thickness, engineered for optical clarity, thermal insulation, or structural safety in buildings and vehicles. Tempered glass leads volume in automotive and safety applications where fragmentation resistance is mandatory, while coated glass commands premium positioning as energy codes tighten. Insulated glass units are displacing single-pane stock in renovation cycles, with margin pools concentrating in gas-filled, warm-edge configurations.
The U.S. Department of Energy's model energy codes and ENERGY STAR fenestration standards shape product specifications by mandating lower U-factor and solar heat gain coefficient thresholds. Canada's National Building Code and provincial adoption pathways create parallel compliance requirements that filter market access for imported glazing systems. Stakeholders must monitor code harmonization between U.S. and Canadian jurisdictions to anticipate specification convergence or divergence in cross-border projects.
Market Dynamics
The U.S. Department of Energy's progressive tightening of model energy codes is forcing a specification upgrade cycle across commercial and residential fenestration, compressing the viable product mix toward low-emissivity and solar-control coated configurations.
Growth Catalysts
- Building energy code escalation:The U.S. Department of Energy's model energy codes and ENERGY STAR fenestration standards mandate progressively lower U-factors and solar heat gain coefficients, eliminating single-pane and uncoated clear float from new construction specifications.
- Solar control coating penetration:Intense cooling loads in the southwestern United States are concentrating demand for spectrally selective coatings that reject infrared radiation while maintaining visible light transmission.
- Renovation cycle acceleration:Insulated glass units are displacing single-pane stock in building renovation cycles, particularly in older commercial and residential structures across the U.S. Midwest and Northeast.
Market Restraints
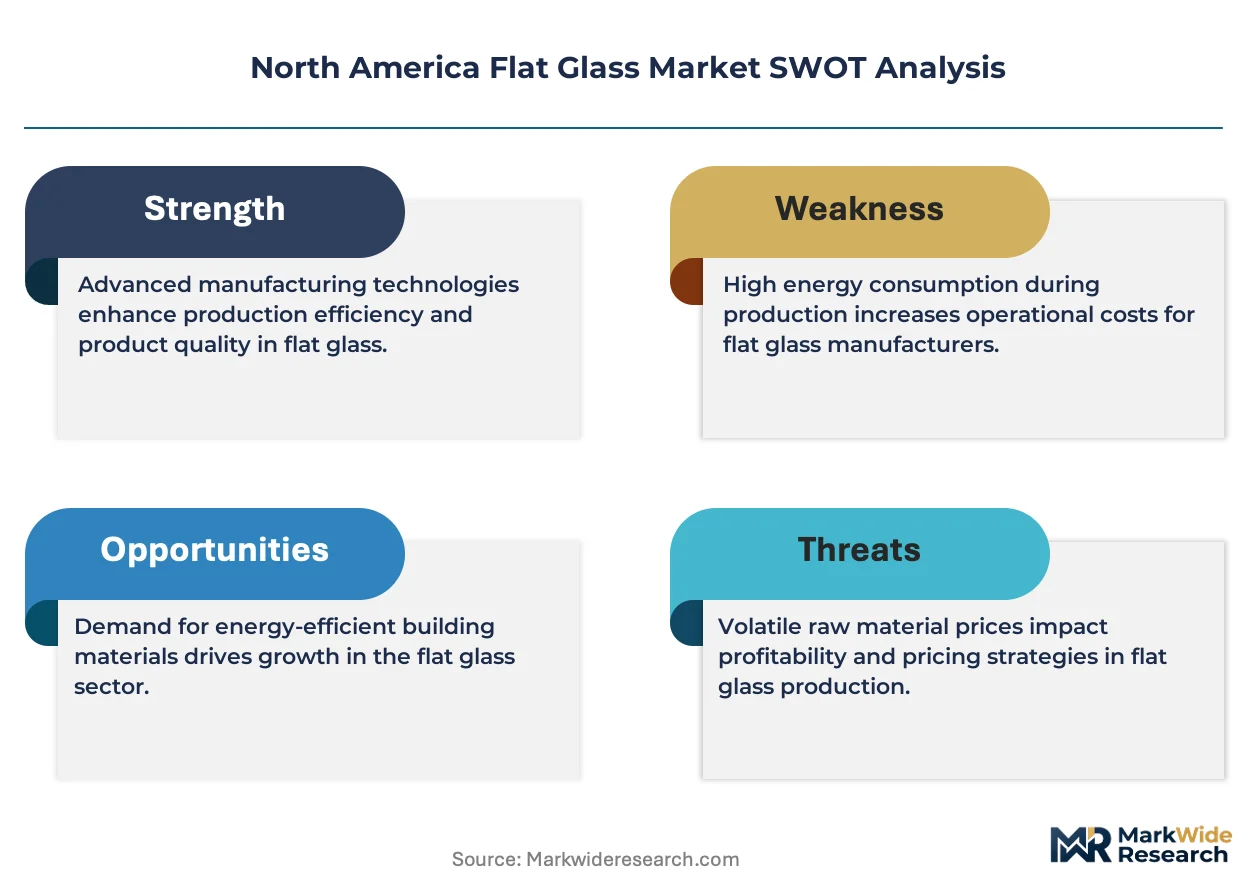
- Silica sand and soda ash cost volatility:Raw material input costs for flat glass manufacturing fluctuate with energy prices and mining logistics, compressing margin stability for non-integrated producers.
- Float line concentration:Primary flat glass production concentrates in a limited corridor of U.S. Midwest and Southeast manufacturing sites, creating geographic supply risk for western and northern construction markets.
- Natural gas price exposure:The energy-intensive float process ties manufacturing economics to regional natural gas benchmarks, particularly affecting operations in Alberta and Ontario.
Strategic Opportunities
- Warm-edge spacer technology convergence:The integration of thermally improved spacer systems with gas-filled insulated units creates premium positioning in cold-climate Canadian markets where condensation resistance is critical.
- Electrochromic smart glazing emergence:Dynamic tinting technologies are penetrating high-performance commercial segments in California and New York where daylight harvesting and glare control drive specification.
- Utility rebate program alignment:State-level efficiency incentive programs in Massachusetts, New York, and California subsidize high-performance glazing upgrades, accelerating payback calculations for building owners.
Industry Challenges
- Thermal bridging mitigation expertise:The specification and installation of warm-edge, gas-filled insulated units requires specialized fabrication knowledge that remains scarce in regional distribution networks.
- Code harmonization complexity:Divergent adoption timelines between U.S. model energy codes and Canada's National Building Code create inventory and certification friction for cross-border project suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flat Glass Market |
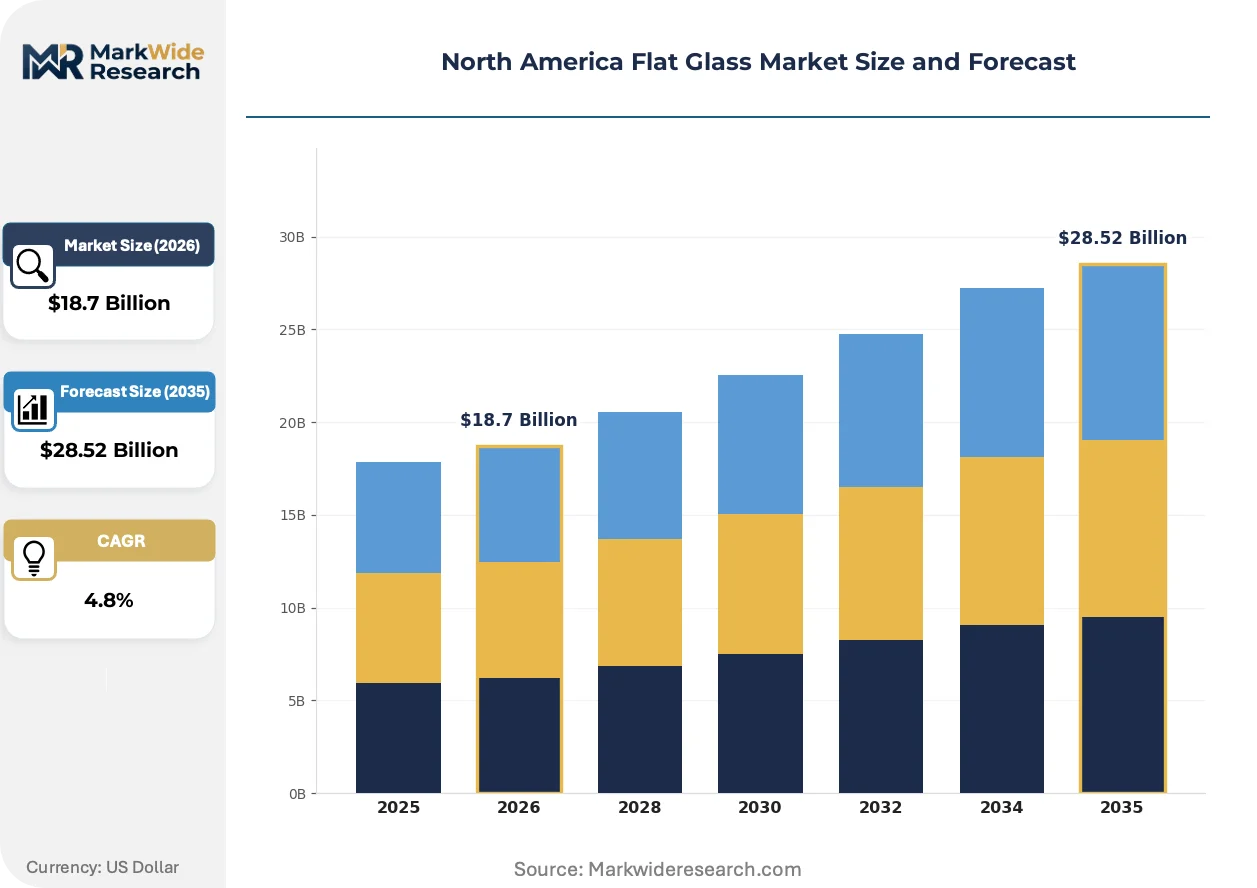
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Insulated Glass, Coated Glass Application: Architectural, Automotive, Furniture, Industrial End User: Construction, Automotive Manufacturers, Furniture Designers, Electronics Distribution Channel: Direct Sales, Retail, Wholesale, Online |
| Companies Covered | Saint-Gobain, AGC Inc., Guardian Glass LLC, Nippon Sheet Glass Co. Ltd., Sisecam Group, Vitro Architectural Glass, Cardinal Glass Industries, Inc., Schott AG, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flat Glass Market Evolving Landscape
Active coating technologies and dynamic glazing systems are compressing the performance gap between static solar control and responsive building envelopes, while procurement patterns shift toward integrated facade system sourcing.
Triple-silver low-emissivity coatings are rewriting thermal performance benchmarks for commercial curtain wall and residential window applications. Large-scale architectural glazing contractors in Texas, Arizona, and southern California are specifying these configurations for projects targeting net-zero energy certification. The technology is compressing acceptable U-factor thresholds and eliminating dual-silver products from premium specification channels.
The U.S. Department of Energy's building energy codes and ENERGY STAR certification requirements are mandating lower solar heat gain coefficients across climate zones. This regulatory pressure is eliminating uncoated clear float from new construction viability and accelerating coated glass penetration in replacement markets. Canadian provinces adopting parallel National Building Code amendments are creating synchronized compliance requirements that favor suppliers with cross-border certification capabilities.
Building envelope procurement is consolidating toward integrated facade system contractors who source glazing, framing, and installation as unified packages. This channel shift is compressing direct relationships between glass fabricators and general contractors, particularly in commercial high-rise construction in Chicago, Toronto, and Vancouver. The change is most visible in projects pursuing LEED v4.1 or Net Zero Energy Building certification where single-source accountability reduces interface risk.
North America Flat Glass Market Segmentation
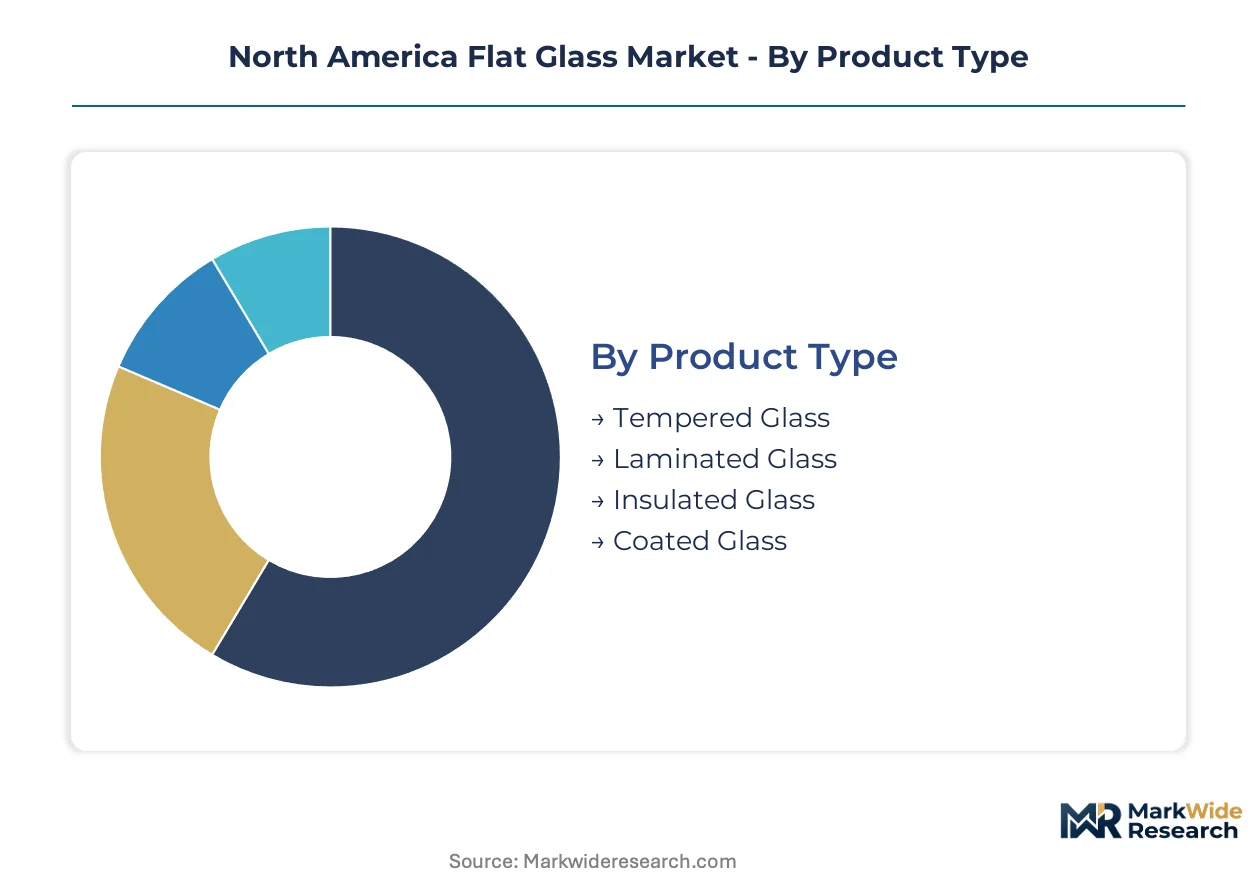
Flat glass segmentation in North America tracks divergent margin structures across fabrication technologies and specification channels. Product type splits reveal where energy code compliance concentrates value capture, while application segments expose geographic demand clusters shaped by regional construction cycles.
Product Type:
Primary flat glass fabrication concentrates in the U.S. Midwest and Southeast corridor, with coating and tempering capacity clustering near float line locations to minimize handling damage and logistics costs.
- Tempered Glass:Heat-treated soda-lime sheets undergo controlled thermal shock to create surface compression layers that fragment into granular pieces upon failure. Automotive safety glazing and commercial storefront systems in Texas and Arizona drive specification where fragmentation resistance is mandatory.
- Coated Glass:Sputtered metal oxide layers engineered for spectral selectivity, applying low-emissivity or solar-control films during float line exit. The southwestern United States concentrates demand as ENERGY STAR thermal performance mandates tighten across new construction and replacement cycles.
- Laminated Glass:Polyvinyl butyral interlayers bonded between glass plies for acoustic damping and post-breakage retention.
- Insulated Glass:Gas-filled dual or triple-pane units with warm-edge spacers targeting condensation resistance in cold-climate Canadian markets.
Coated glass absorbs the bulk of installed capacity; insulated glass is expanding most quickly as renovation cycles accelerate across the U.S. Midwest and Northeast.
Application:
End-use demand distributes unevenly across construction spending cycles, with commercial and residential building activity creating distinct specification rhythms and margin profiles.
- Architectural:Curtain wall, window, and skylight systems for commercial high-rise and residential construction. Net-zero energy certification targets in California and New York compress specification toward triple-silver low-emissivity configurations with dynamic tinting integration.
- Automotive:Windshield, side lite, and backlite glazing for passenger and commercial vehicle OEMs. Lightweighting mandates from NHTSA and EPA fuel economy standards drive laminated windshield penetration and thinner tempered side lite specification.
- Furniture:Tabletops, shelving, and decorative interior applications requiring polished edges and custom dimensions.
- Industrial:Appliance panels, solar module substrates, and specialized equipment viewing ports.
Architectural applications command the dominant share of value; automotive is climbing the fastest as electric vehicle platform launches reshape glazing area and weight requirements.
End User:
Procurement authority fragments across project delivery models, with integrated facade contractors consolidating influence in commercial segments while residential channels remain distributor-dependent.
- Construction:General contractors, glazing subcontractors, and building envelope specialists executing new build and renovation projects. ENERGY STAR fenestration standards and U.S. Department of Energy model energy code adoption in Massachusetts, New York, and California subsidize high-performance upgrades through utility rebate alignment.
- Automotive Manufacturers:OEM assembly plants and tier-1 glazing system suppliers with just-in-sequence delivery requirements. Regional manufacturing footprints in Michigan, Ohio, and Ontario concentrate demand for tempered and laminated configurations.
- Furniture Designers:Custom fabricators and mass-market producers sourcing cut-to-size tempered or polished-edge float.
- Electronics:Display cover glass and touch panel substrates requiring optical-grade flatness.
Construction end users absorb the dominant procurement volume; automotive manufacturers are gaining share fastest as platform electrification accelerates glazing specification cycles.
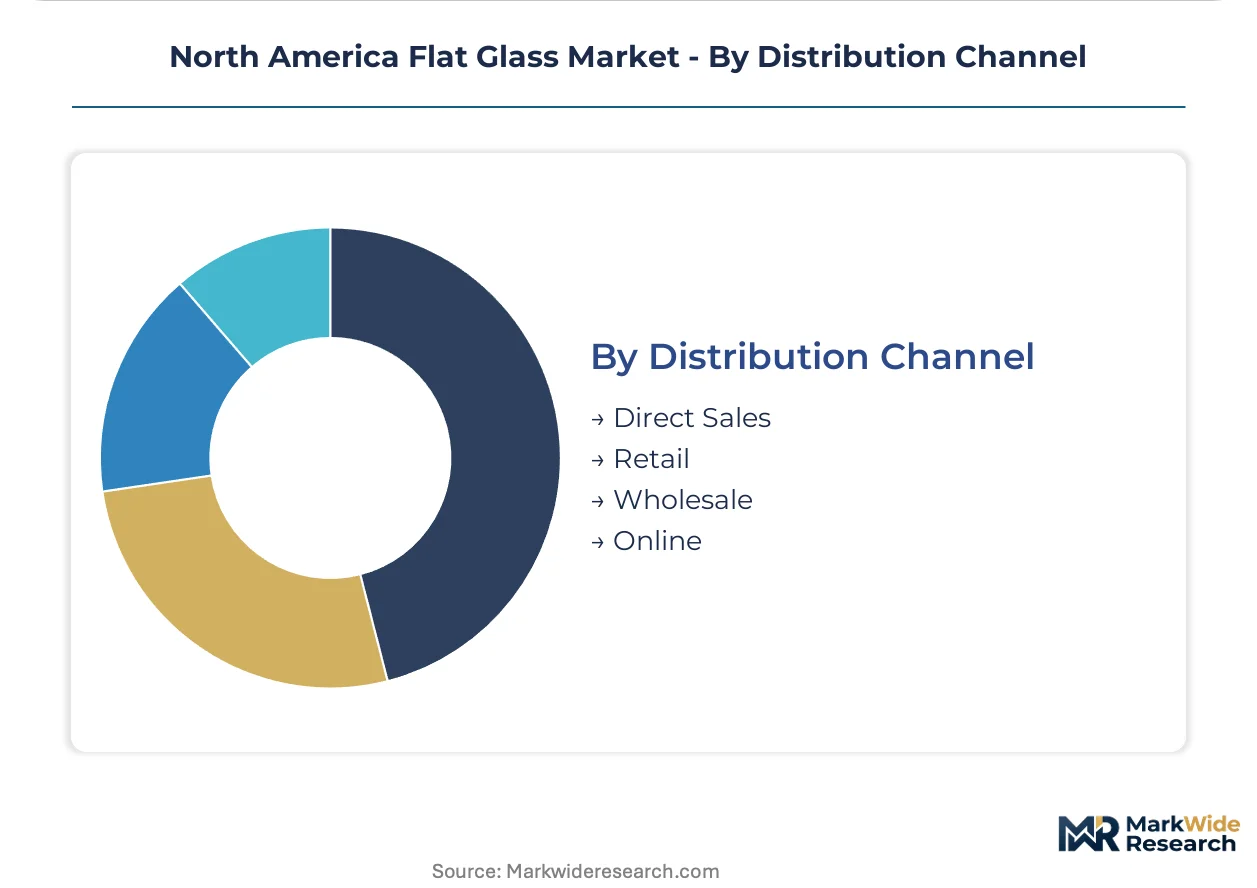
Distribution Channel:
Channel structure reflects the tension between fabrication lead-time reliability and inventory carrying costs across geographically dispersed construction markets.
- Direct Sales:Fabricator-to-contractor relationships for large commercial projects with custom insulated unit specifications. Chicago, Toronto, and Vancouver high-rise construction increasingly sources through integrated facade system contractors who consolidate glazing, framing, and installation accountability.
- Wholesale:Regional distribution networks supplying independent glazing contractors and lumberyards with standard sized tempered and laminated stock. Lead-time competition from Cardinal Glass Industries' regional fabrication networks pressures inventory depth requirements.
- Retail:Big-box home improvement chains and local glass shops serving residential replacement and repair demand.
- Online:Emerging platform-based procurement for standardized dimensions and small-batch custom orders.
Direct sales channels capture the largest project value concentration; wholesale is expanding most quickly as regional fabricators extend geographic coverage to reduce float line concentration risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Midwest manufacturing corridor anchors primary float glass capacity, with Ohio and Michigan hosting integrated coating and tempering operations that serve eastern construction markets.
United States
Southwestern states concentrate demand for spectrally selective solar control coatings as ENERGY STAR fenestration standards tighten thermal performance mandates. The U.S. Department of Energy's model energy codes eliminate single-pane specifications from new construction viability. Texas and Arizona fabrication clusters process coated glass for commercial high-rise projects targeting net-zero certification.
Canada
Cold-climate provinces drive specification of gas-filled insulated glass units with warm-edge spacer systems for condensation resistance. The National Building Code and provincial adoption pathways create compliance requirements that filter market access for imported glazing systems. Ontario and Quebec manufacturing sites in Alberta and Ontario face natural gas price exposure affecting float process economics.
Mexico
Automotive OEM assembly plants in central Mexico generate tempered and laminated glass demand for just-in-sequence delivery requirements. NAFTA successor agreements shape cross-border certification friction for glazing system suppliers. Nuevo León and Mexico City metro areas concentrate tier-1 glazing supplier footprints serving regional vehicle platform launches.
North America Flat Glass Market Competitive Landscape
Capital-heavy float line operators compete with asset-light regional fabricators across specification channels. Primary production concentrates among integrated multinationals with captive silica sand and soda ash sourcing, while downstream players compete on lead-time reliability for custom insulated units. Strategic archetypes separate into integrated float-coating operators, regional fabrication specialists, and automotive-focused tempering houses. Dominant competitive moves include backward integration into raw material supply and geographic expansion of coating capacity toward southwestern demand clusters.
Within the integrated multinational tier, Saint-Gobain and AGC Inc. exemplify capital-intensive positioning through float-coating integration. Guardian Glass LLC occupies a Midwest-focused manufacturing position. Cardinal Glass Industries, Inc. represents the regional fabrication specialist archetype competing on custom unit lead times. Nippon Sheet Glass Co. Ltd. anchors Asian-origin participation in North American architectural specification channels.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Guardian Glass LLC |
| Nippon Sheet Glass Co. Ltd. |
| Sisecam Group |
| Vitro Architectural Glass |
| Cardinal Glass Industries, Inc. |
| Schott AG |
| PPG Industries |
| Others |
Value Network & Pricing Analysis
ENERGY STAR fenestration standards gate both qualified supply and premium-tier pricing access, as fabricators lacking certified coating capacity cannot serve code-compliant new construction channels in California, New York, or Massachusetts. This regulatory filtration compresses viable supplier pools and concentrates pricing power among integrated float-coating operators with cross-border certification capabilities.
Pricing Analysis
Outcome-based pricing anchored to thermal performance certification separates triple-silver low-emissivity configurations from dual-silver and uncoated commodity stock. Price differentiation rests on U-factor achievement and solar heat gain coefficient tier, with brand premium attaching to suppliers holding Canadian Standards Association and NFRC certification. Cost compression in clear float segments is intensifying because raw material volatility and natural gas exposure squeeze non-integrated Midwest producers. Residential replacement contractors exhibit highest price sensitivity, while net-zero commercial developers in Texas and Arizona prioritize performance over unit cost.
Supply Chain Analysis
Cross-border certification requirements filter supplier access to Canadian architectural specification channels, creating qualification bottlenecks for U.S.-only fabricators. Primary float capacity concentrates in the United States, with coating and tempering operations clustering near Ohio and Michigan sites to minimize handling damage. Silica sand, soda ash, and natural gas feed the energy-intensive manufacturing process. Single-source vulnerability runs through concentrated Midwest float line geography. Distribution runs through integrated facade system contractors consolidating glazing, framing, and installation accountability in Chicago, Toronto, and Vancouver high-rise construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Float line capacity constraints in the U.S. Midwest prop pricing power for integrated producers, as geographic concentration limits supply elasticity against code-driven demand acceleration.
For Market Incumbents: Hedge against natural gas price volatility through captive fuel hedging or Alberta site diversification, while defending specification share against electrochromic smart glazing entrants by accelerating warm-edge spacer integration with gas-filled insulated units. Backward integration into silica sand mining secures margin stability against raw material volatility. For New Entrants and Emerging Players: E-commerce platform routes into standardized residential replacement glass offer lowest barrier to penetration, bypassing entrenched wholesale distribution relationships. Target southwestern U.S. solar control coating demand where specification urgency outpaces incumbent capacity expansion. Lead with utility rebate program alignment in Massachusetts and New York to accelerate customer acquisition. For Investors and Strategic Acquirers: Electrochromic smart glazing adoption in California commercial high-rises is the leading indicator that dynamic tinting technologies are crossing from premium niche toward mainstream specification. Five-to-ten year viability favors regional fabrication specialists with warm-edge expertise and cross-border Canadian certification. Monitor code harmonization progress between U.S. Department of Energy model codes and Canada's National Building Code as inflection signal for cross-border supplier consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Captive silica sand and soda ash sourcing insulates margin stability against energy-driven input volatility. |
| Warm-Edge Spacer Technology Convergence | Gas-filled insulated unit integration addresses Canadian condensation resistance requirements and premium positioning. |
| Cross-Border Certification Investment | Parallel U.S. NFRC and Canadian CSA qualification unlocks specification access in Toronto and Vancouver commercial construction. |
| Electrochromic Smart Glazing Development | Dynamic tinting penetration in California and New York net-zero projects responds to daylight harvesting mandates. |
| Regional Fabrication Network Expansion | Lead-time reliability competition with Cardinal Glass Industries pressures geographic coverage extension toward western construction markets. |
Research Methodology
Multi-period observation of ENERGY STAR adoption timelines, provincial code amendments, and float line capacity utilization anchored the trend analysis, supplemented by interviews with flat glass plant managers, glazing subcontractor procurement leads, commercial building envelope specialists, and utility rebate program administrators. Secondary validation drew from U.S. Department of Energy building energy code documentation, Natural Resources Canada trade flow data, SEC 10-K filings of publicly traded glass manufacturers, and American Architectural Manufacturers Association shipment statistics. Bottom-up fabrication capacity modeling triangulated against top-down construction spending forecasts.
Input-output matrices mapped silica sand, soda ash, and natural gas cost trajectories against coated glass pricing elasticity across climate zones, with segmentation dimensions including product type, application, end user procurement authority, and distribution channel structure. CAGRs were derived from regression analysis of historical shipment volumes and forward projection of code compliance thresholds. Industry-specific forecast inputs incorporated solar control coating penetration rates in southwestern states and renovation cycle acceleration in the U.S. Midwest and Northeast.
The model holds under steady regulatory escalation and stable natural gas pricing; deviation in float line shutdowns or abrupt code timeline acceleration would shift supply-demand balances. Forecasts reflect documented assumptions about construction spending cycles and automotive platform electrification schedules. A model refresh is warranted upon material change in U.S. Department of Energy model energy code adoption timelines or Canadian National Building Code harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Fiberglass Window Market
Glass
Middle East and Africa Glassware Market
Glass
Porous Glass Market
Glass
Glass Alternative Materials Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
France Silica Sand Market
Glass
Metallic Glass Market
Glass
Dynamic Glazing Market
Glass
Sapphire Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
Heat Resistant Glass Market
Glass
Low-E Glass Market
Glass
Recycled Glass Aggregates Market
Glass
Global Anti-Reflective Glass Market
Glass
Europe Flat Glass Market
Glass
Cellular Glass Market