
 Float Glass Market | 2026-2036
Float Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Float Glass Market Intelligence
The cyclical nature of automotive glass demand is decoupling from the more stable, long-term growth seen in the architectural sector. Saint-Gobain leverages its extensive global manufacturing footprint to serve both segments. AGC Inc. differentiates through its focus on high-performance coated glass for architectural applications. Meanwhile, Xinyi Glass dominates the solar glass segment with massive production scale.
Float glass is a sheet of glass manufactured by floating molten glass on a bed of molten metal, most commonly tin. This process ensures uniform thickness and exceptionally flat, parallel surfaces, making it the base material for most modern glass products. Coated glass products designed for energy efficiency represent the fastest-growing product type, commanding higher margins. While standard thickness glass constitutes the bulk of volume, demand for thin and ultra-thin glass for electronics and display applications is increasing.
Product standards are governed by regional frameworks, such as the CE marking requirements in Europe and national building codes in the United States. In China, GB standards for safety and energy performance in construction glass dictate market access and product specifications. Stakeholders must navigate the increasing complexity of regional energy performance mandates to maintain competitive positioning in high-value architectural segments.
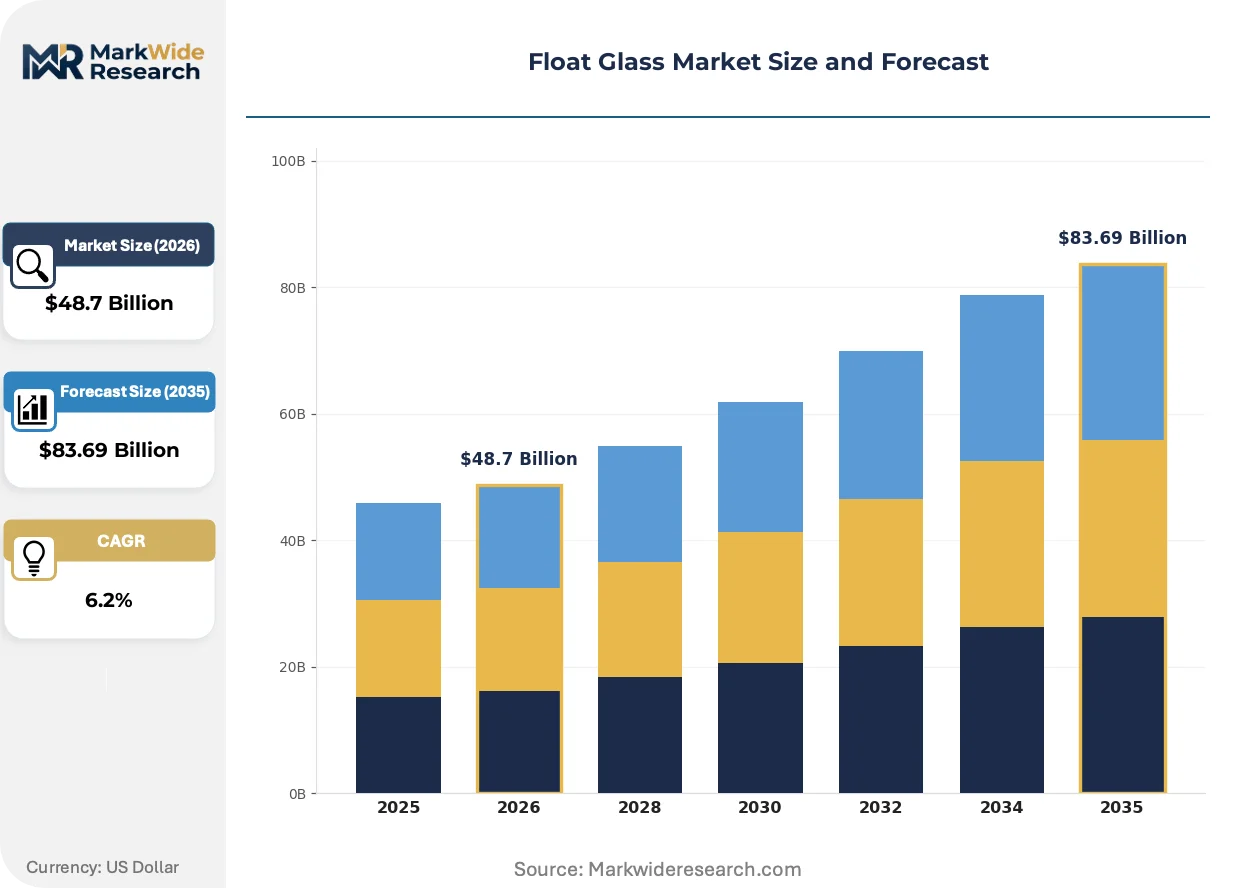
Market Dynamics
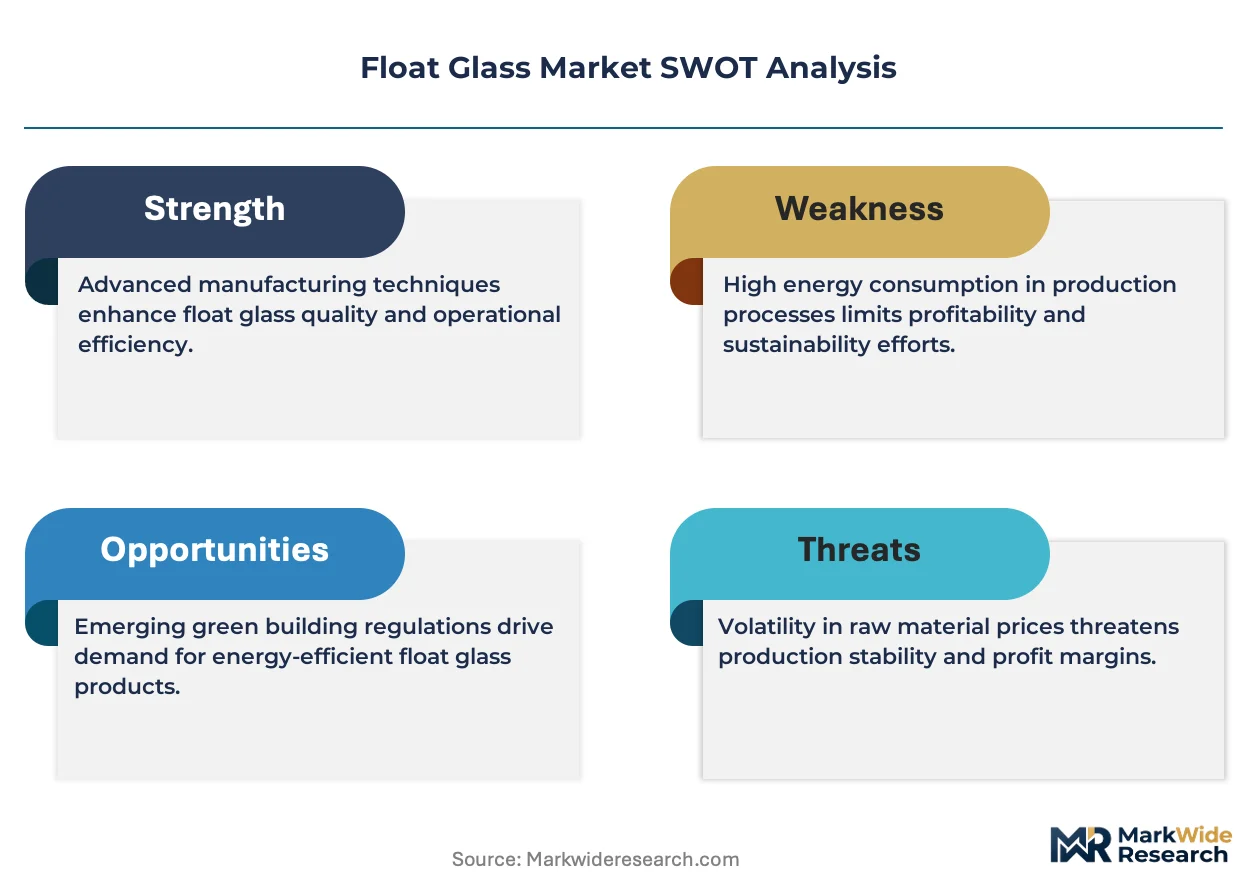
The central structural force shaping the market is the global push for building decarbonization. Mandates like the EU Green Deal and China's dual carbon goals are compelling the construction industry to adopt high-performance, energy-efficient coated float glass, shifting value away from standard products.
Growth Catalysts
- EU Green Deal:This framework's building renovation wave requires high-performance glazing to meet stricter energy efficiency targets, stimulating demand for advanced coated glass in the residential and commercial construction sectors.
- Solar Panel Expansion:Sustained investment in renewable energy infrastructure, particularly in China and India, creates large-volume demand for specialized float glass used in photovoltaic modules.
- Smart Glass Development:The integration of electrochromic and thermochromic technologies into architectural glass for dynamic tinting opens new applications in premium commercial and residential buildings.
Market Restraints
- Energy Intensity:Float glass production is highly energy-intensive, exposing manufacturers to volatile natural gas and electricity prices, which directly impacts production cost structures and margin stability.
- Raw Material Sourcing:Geographic concentration of high-purity silica sand reserves creates supply chain vulnerabilities and logistical cost pressures for manufacturers located far from primary extraction sites.
- Capital-Intensive Furnaces:The high upfront investment and long construction lead times for float glass production lines create significant barriers to entry and limit capacity expansion flexibility.
Strategic Opportunities
- Automotive Display Glass:The expansion of digital cockpits and passenger-side infotainment systems in electric vehicles creates a new, high-value opportunity for thin, durable, and precisely shaped float glass.
- Southeast Asian Infrastructure:Rapid urbanization and construction growth in countries like Vietnam and Indonesia present an underpenetrated market for architectural glass, particularly for energy-efficient building projects.
- Anti-Microbial Coatings:Post-pandemic health consciousness in public and commercial spaces provides a niche for glass with factory-applied anti-microbial coatings for applications in healthcare and hospitality.
Industry Challenges
- Complex Certification Pathways:Navigating divergent regional standards, such as Europe's CE marking and China's GB standards for safety glass, creates compliance burdens and lengthens time-to-market for new products.
- Recycling Infrastructure Gaps:The lack of widespread, efficient collection and cullet processing systems for end-of-life architectural glass limits the industry's ability to achieve higher recycled content and circular economy goals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Float Glass Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $83.69 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Annealed, Tempered, Laminated, Coated End Use: Architectural, Automotive, Furniture, Solar Panels Thickness: Thin, Standard, Thick, Ultra-Thin Application: Windows, Facades, Mirrors, Display |
| Companies Covered | Şişecam Group, Cardinal Glass Industries Inc., AGC Inc., Xinyi Glass, China Glass Holdings Limited, Saint-Gobain, Guardian Glass LLC, KIBING Group, Nippon Sheet Glass (NSG) Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Float Glass Market Strategic Shifts & Innovations
Product innovation is pivoting from thickness and clarity toward functional surface coatings that deliver specific performance outcomes. This shift is driven by regulatory pressures for energy conservation and new end-user demands for dynamic, intelligent building envelopes and vehicle interiors.
Ultra-thin glass, traditionally used in electronics, provides a lightweight and flexible substrate. Automotive and aerospace sectors are adopting this material at an accelerating pace for advanced displays and smart windows. This technology is expanding into architectural applications like interior partitions and laminated safety glass, enabling new design possibilities.
China's dual carbon goals directly influence the construction sector's material specifications. The policy mandates improved thermal performance in new buildings, accelerating the transition from single-pane to double- or triple-pane insulating glass units. The architectural glass segment is most affected, with manufacturers prioritizing investment in low-emissivity coating lines to comply.
A preference for certified sustainable materials is altering procurement criteria in large-scale architectural projects. Developers and architects now frequently specify glass with Environmental Product Declarations or high recycled content, moving beyond simple cost and performance metrics. This trend is most prominent in North America and Europe, where green building certification schemes are widespread.
Float Glass Market Segmentation
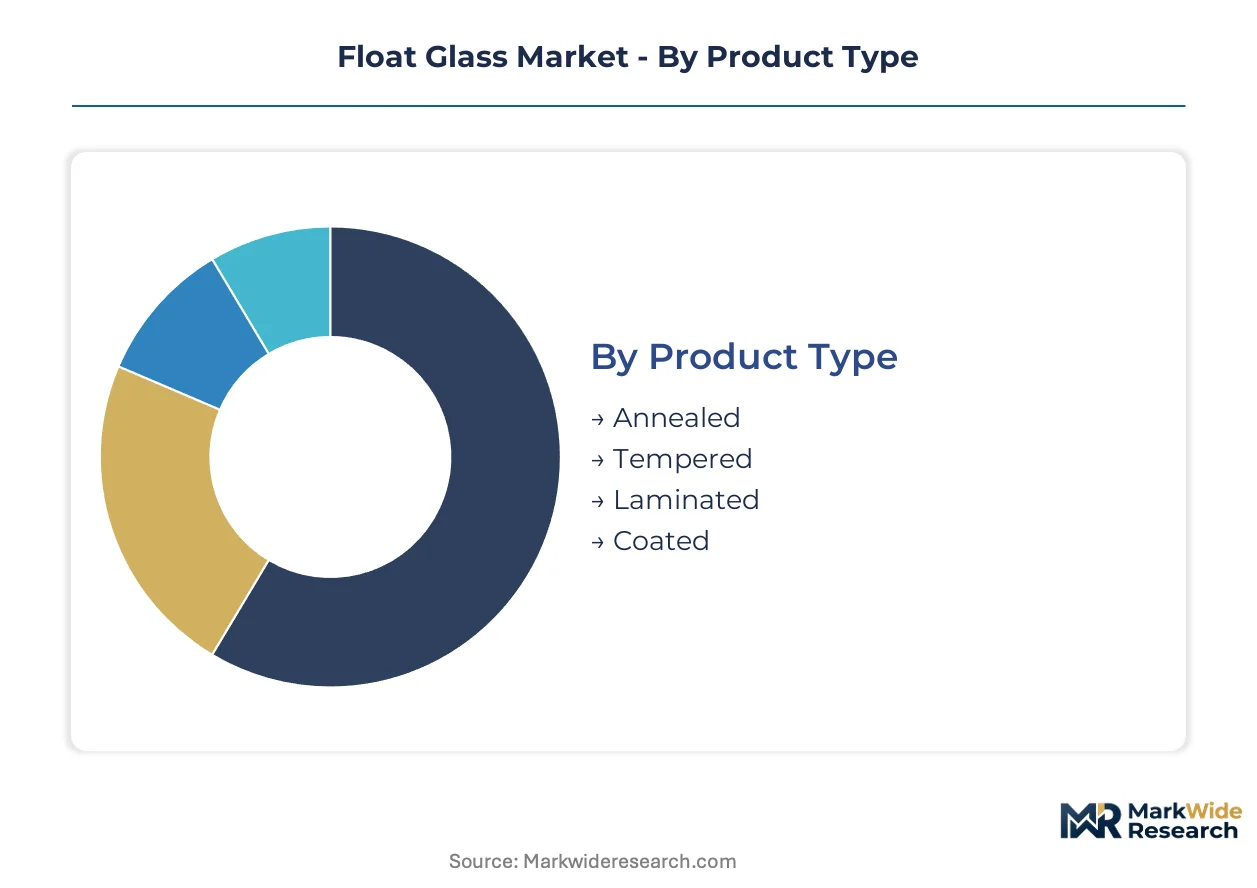
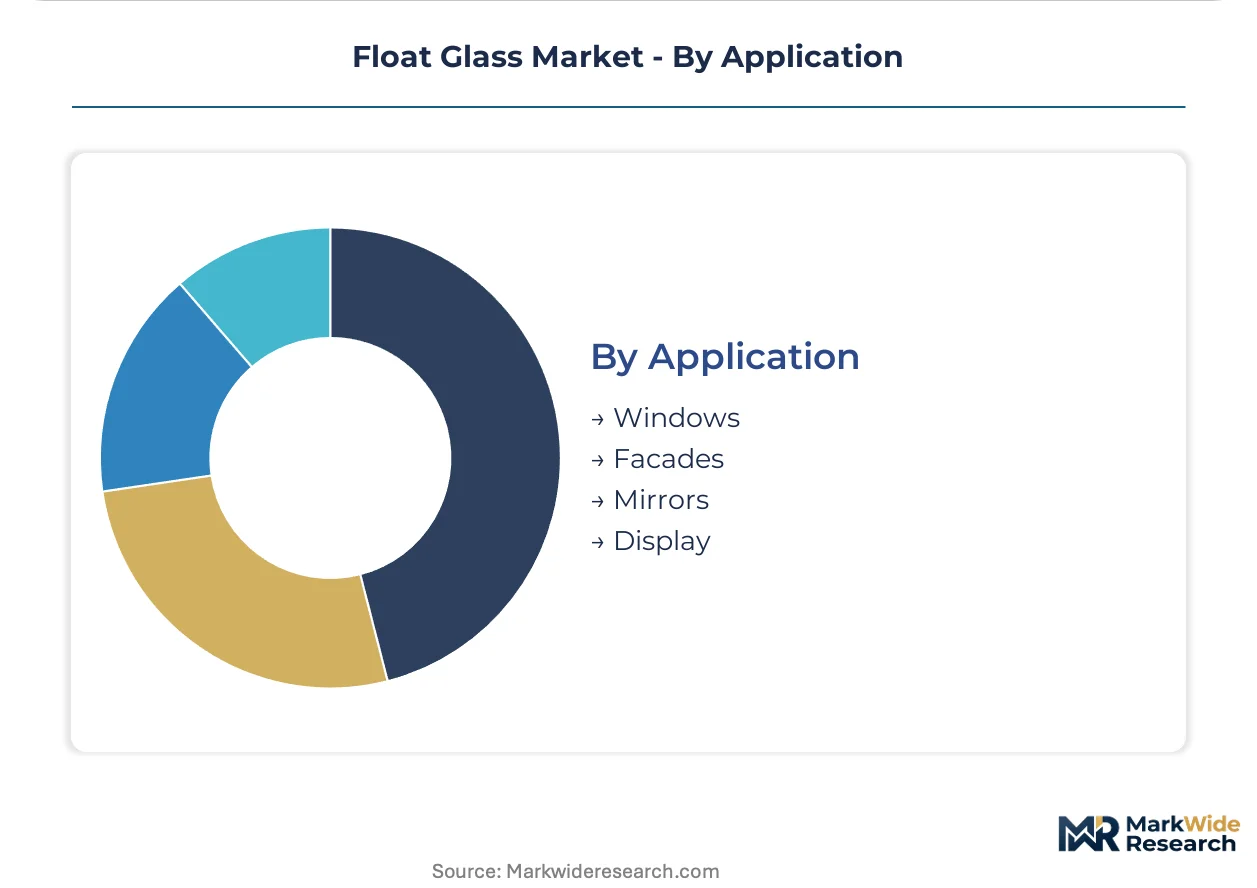
Understanding the distinct segments within the float glass market reveals varied demand patterns and technological requirements across industries. Segmentation clarifies where innovation is most impactful and where regulatory shifts create the most significant market shifts. This granular view helps stakeholders align production capabilities with evolving end-user specifications.
Product Type:
The product type segmentation highlights the tension between high-volume, cost-effective glass and specialized, value-added coated products. Standard annealed glass forms the base, while advanced treatments command premium pricing due to enhanced performance characteristics.
- Annealed:This basic float glass undergoes controlled cooling to prevent internal stresses, making it suitable for general glazing applications where safety glass is not mandated. Its demand is primarily driven by cost-sensitive construction projects in developing economies.
- Tempered:Heat-treated float glass gains significantly increased strength and shatters into small, blunt pieces upon impact, making it a critical safety component in automotive windows and shower enclosures. Demand concentrates in regions with stringent building codes and vehicle safety standards.
- Laminated:This product consists of two or more glass panes bonded by an interlayer, providing superior safety, security, and sound insulation for architectural facades and vehicle windshields. Its application is expanding in high-security buildings and premium automotive segments.
- Coated:Float glass with specialized surface layers offers enhanced thermal insulation, solar control, or anti-reflective properties, directly addressing energy efficiency mandates in modern construction. This segment represents the fastest-growing product type, driven by mandates like the EU Green Deal.
Today's leader: Annealed. Tomorrow's challenger: Coated.
End Use:
End-use categories define the primary application areas for float glass, each with unique performance demands and market dynamics. The shift towards decarbonization significantly influences material specifications across these sectors.
- Architectural:This segment consumes the largest volume of float glass for windows, doors, and facades in residential and commercial buildings, driven by global urbanization and energy efficiency regulations. Its demand is heavily influenced by building renovation waves in Europe and new construction in China.
- Automotive:Float glass is essential for windshields, side windows, and sunroofs in vehicles, with demand influenced by global vehicle production cycles and the increasing integration of display technologies. The expansion of electric vehicles is creating new opportunities for advanced glass solutions.
- Furniture:Glass is used in tabletops, shelves, and decorative elements for residential and commercial furniture, where aesthetic appeal and durability are primary considerations. This segment experiences steady demand tied to interior design trends.
- Solar Panels:Specialized float glass forms the protective front cover of photovoltaic modules, requiring high light transmittance and durability for efficient energy capture. Sustained investment in renewable energy infrastructure in China and India drives substantial volume demand.
Demand in the Architectural sector remains robust, while Solar Panels exhibit the steepest expansion trajectory.
Thickness:
The thickness of float glass dictates its mechanical properties and suitability for diverse applications, ranging from robust structural elements to delicate electronic displays. This dimension directly impacts material strength and weight.
- Thin:Glass with reduced thickness offers lightweight properties and increased flexibility, finding applications in advanced displays, automotive interior components, and specialized architectural elements. This segment gains share from the electronics industry's miniaturization trends.
- Standard:This common thickness range accounts for the bulk of float glass production, primarily used in general window glazing, mirrors, and basic architectural applications. Its widespread use underpins the overall float glass market volume.
- Thick:Heavier gauge glass provides enhanced structural integrity and acoustic performance, making it suitable for large architectural facades, balustrades, and high-security glazing. Demand for thick glass is tied to specific structural engineering requirements.
- Ultra-Thin:Glass with extreme thinness enables flexible, lightweight, and high-resolution displays for consumer electronics, automotive digital cockpits, and emerging wearable technologies. The automotive and aerospace sectors are adopting this material at an accelerating pace.
Standard thickness glass dominates volume, while Ultra-Thin glass shows significant growth in niche, high-value applications.
Application:
Applications delineate the specific functional uses of float glass products, often requiring tailored performance characteristics. Innovation in this area focuses on integrating new functionalities directly into the glass surface.
- Windows:Float glass provides transparency and thermal insulation for building fenestration, with market evolution driven by energy efficiency standards and aesthetic preferences. The building renovation wave in Europe drives demand for high-performance window glass.
- Facades:Large-scale glass panels form the exterior envelopes of modern buildings, requiring high structural integrity, solar control, and aesthetic versatility. This application is central to contemporary urban architecture.
- Mirrors:Float glass coated with a reflective layer forms mirrors for various decorative, automotive, and functional purposes, representing a mature but consistent demand segment. Its demand is tied to interior design and automotive production.
- Display:High-quality float glass serves as the substrate for screens in televisions, smartphones, tablets, and automotive infotainment systems, demanding precise optical properties and durability. The expansion of digital cockpits in electric vehicles creates new opportunities.
Windows represent a foundational application, while Display applications are undergoing rapid technological evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence in energy efficiency standards across regions creates opportunities for regulatory arbitrage, influencing manufacturing location decisions and product specialization within the float glass market. Manufacturers strategically position production to align with regional compliance demands. This shift impacts investment in advanced coating lines, driving market evolution.
China
China's dual carbon goals and sustained urban infrastructure investment fuel substantial demand for high-performance float glass. GB standards for safety and energy performance dictate market access and product specifications. The Yangtze River Delta region concentrates significant manufacturing capacity for construction glass and solar panels.
United States
The United States market is driven by national building codes and widespread green building certification schemes. Investment in infrastructure projects and commercial construction stimulates demand for both standard and specialized glass products. California, with its stringent energy regulations, represents a key hub for advanced architectural glass applications.
Germany
Germany, under the EU Green Deal, mandates high-performance glazing for its building renovation wave, stimulating demand for advanced coated glass. CE marking requirements ensure product compliance across the European Union. North Rhine-Westphalia houses a significant concentration of architectural glass fabricators and processors.
India
India's expanding renewable energy infrastructure and rapid urbanization create large-volume demand for specialized float glass in solar panels and construction. BIS standards govern product quality and safety for construction materials. Gujarat is emerging as a major hub for solar glass production facilities.
Vietnam
Rapid urbanization and construction growth in Vietnam present an underpenetrated market for architectural glass. Government initiatives supporting sustainable building practices are slowly increasing demand for energy-efficient solutions. Ho Chi Minh City leads in new commercial and residential developments, requiring diverse glass products.
Float Glass Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the float glass market. The industry exhibits a blend of highly consolidated primary float glass production and a more fragmented downstream processing sector. Strategic archetypes include large integrated producers, specialized high-performance coated glass manufacturers, and regional fabricators. Capacity expansion, particularly in the solar glass segment, and portfolio diversification into value-added coatings represent dominant competitive moves.
Within the large integrated producer archetype, France-based Saint-Gobain and Japan-based AGC Inc. exemplify global manufacturing footprints serving diverse segments. Japan-based AGC Inc. differentiates through its focus on high-performance coated glass for architectural applications. China-based Xinyi Glass anchors the solar glass segment with massive production scale and efficiency, reflecting a specialization in high-volume, cost-effective solutions.
| Leading Market Players |
|---|
| Şişecam Group |
| Cardinal Glass Industries Inc. |
| AGC Inc. |
| Xinyi Glass |
| China Glass Holdings Limited |
| Saint-Gobain |
| Guardian Glass LLC |
| KIBING Group |
| Nippon Sheet Glass (NSG) Co. Ltd |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and China's dual carbon goals gate access to qualified high-performance coated glass supply and command premium-tier pricing. These mandates compel manufacturers to invest in advanced production capabilities, creating a distinct market for energy-efficient products.
Pricing Analysis
Direct-to-OEM discount structures dominate large-volume float glass procurement for automotive and solar panel segments. Pricing stratifies across premium, standard, and economy tiers, driven by certification levels like CE marking and specific performance characteristics. Pricing softness affects standard annealed glass due to oversupply from large-scale producers. Architectural developers prioritize value-added coated glass, exhibiting lower price sensitivity than cost-focused general construction projects.
Supply Chain Analysis
CE marking requirements and GB standards gate market entry for float glass manufacturers, ensuring product compliance and safety. Geographic supply concentration for float glass production centers on China for volume and Germany/United States for advanced architectural products. The industry relies heavily on high-purity silica sand and natural gas as primary inputs. Energy price volatility represents a significant structural risk for manufacturers. Distribution runs through a blend of direct sales to large fabricators and a network of regional distributors for smaller projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The float glass market represents a geographic-arbitrage play, leveraging China's lower production costs against Europe's high-value regulatory mandates for energy efficiency.
For Market Incumbents:
Acquire specialized coating technology firms to expand capabilities in high-performance glass, mitigating the threat from niche technology entrants. Expand low-emissivity coating capacity in developing markets like Southeast Asia to capture new construction demand. Invest in R&D for next-generation smart glass solutions, enhancing product differentiation against standard offerings. Secure long-term supply agreements for critical raw materials to hedge against commodity price volatility.
For New Entrants and Emerging Players:
Enter via niche, high-value applications such as ultra-thin glass for automotive digital cockpits or anti-microbial coatings for healthcare environments. Target emerging markets in Southeast Asia with flexible, smaller-scale production lines focused on energy-efficient architectural glass. Partner with electric vehicle manufacturers to integrate advanced display glass solutions, leveraging specific design requirements. Develop innovative functional coatings that address unmet performance needs in premium commercial buildings.
For Investors and Strategic Acquirers:
Roll-up economics work for regional glass fabricators because of the fragmented downstream processing sector. Long-term viability is strong, driven by sustained global demand for energy-efficient building materials and renewable energy infrastructure. Target mid-sized firms with established advanced coating capabilities or strong regional distribution networks. The signal to watch is increased M&A activity in specialized glass processing technologies, indicating consolidation trends.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Low-Emissivity Coating Lines | Captures growing demand for energy-efficient glass in Europe and China. |
| Invest in Smart Glass R&D | Differentiates products with dynamic tinting capabilities for premium buildings. |
| Form Automotive OEM Partnerships | Secures market share in the expanding electric vehicle display segment. |
| Target Southeast Asian Construction | Penetrates under-served markets with rapid urbanization and infrastructure growth. |
| Develop Glass Recycling Infrastructure | Supports circular economy goals and reduces reliance on virgin raw materials. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, informing the float glass market analysis. This approach combined primary data from R&D directors, procurement managers, architectural specifiers, and solar panel manufacturers with secondary validation. Secondary sources included national building codes, industry association reports, corporate financial filings, and trade publications. Bottom-up and top-down triangulation ensured data integrity and comprehensive market coverage.
The forecast window was anchored to historical reference periods, establishing a consistent baseline for projection across the analysis window. The analytical framework modeled segmentation dimensions including product type, end-use, thickness, application, and regional regulatory stringency. Compound Annual Growth Rates were derived from historical growth trends and projected market drivers, reflecting anticipated shifts. Key forecast inputs included global building renovation rates and national solar energy deployment targets, influencing demand projections.
Inputs from publicly available financial reports and government energy mandates were available through the study window; gaps in granular regional production capacity data introduce uncertainty bands. Forecasts reflect assumptions regarding future energy prices and regulatory environments. A model refresh is warranted upon material change in building decarbonization policies or global trade agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Reactors Market
Glass
Ultra Violet Glass Bottles Market
Glass
Low Temperature Laminated Glass Market
Glass
Solar PV Glass Market
Glass
Asia-Pacific Silica Sand Market
Glass
Glass Recycling Market
Glass
Glazing Gel Market
Glass
North America and Australia Silica Market
Glass
Optical Lens Material Market
Glass
India Flat Glass Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Asia-Pacific Glassware Market
Glass
Global Anti-Reflective Glass Market
Glass
East Africa Flat Glass Market
Glass
Shatterproof Glass Market
Glass
Global Glass Flake Coatings Market