
 Global Laminated Glass Market | 2026-2036
Global Laminated Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Laminated Glass Market Outlook
Multi-sourcing of PVB interlayer resin is realigning as producers seek supply security after petrochemical volatility. Saint-Gobain Glass leverages captive polymer compounding in Europe to sustain margin stability across architectural contracts. Guardian Industries anchors North American automotive supply through dedicated float-glass lines optimized for windshield specifications. Xinyi Glass Holdings Limited competes on manufacturing scale, operating some of the world's largest laminated glass furnaces for export markets.
Laminated glass consists of two or more glass layers bonded with an interlayer, typically polyvinyl butyral (PVB) or ethylene-vinyl acetate (EVA), manufactured through autoclave heating and pressure cycles to achieve shatter-resistant integrity and acoustic dampening. Its primary purpose spans occupant protection in vehicle collisions, hurricane-resistant building envelopes, and forced-entry deterrence in commercial facades. Safety Glass dominates product-type revenue due to mandatory automotive and architectural codes across developed economies. The Aerospace application segment represents the fastest-growing demand pool, driven by cabin pressure integrity requirements and weight-reduction targets in next-generation aircraft programs. PVB Interlayers command the highest margin concentration as specialized acoustic and solar-control grades differentiate supplier portfolios.
The U.S. Department of Transportation's FMVSS 205/212 mandates windshield retention during impact, while the EU's Construction Products Regulation (CPR) enforces CE-marked laminated glass for structural glazing applications. China's GB 15763.3 standard and Japan's JIS R 3205 framework further fragment compliance requirements, forcing multinational suppliers to maintain parallel certification portfolios. India's BIS certification scheme for safety glass is tightening import access and accelerating local joint-venture formation. Stakeholders must monitor interlayer material transitions—particularly ionoplast formulations displacing conventional PVB in structural applications—as these chemistry shifts will determine which production assets retain competitive viability.
Market Dynamics
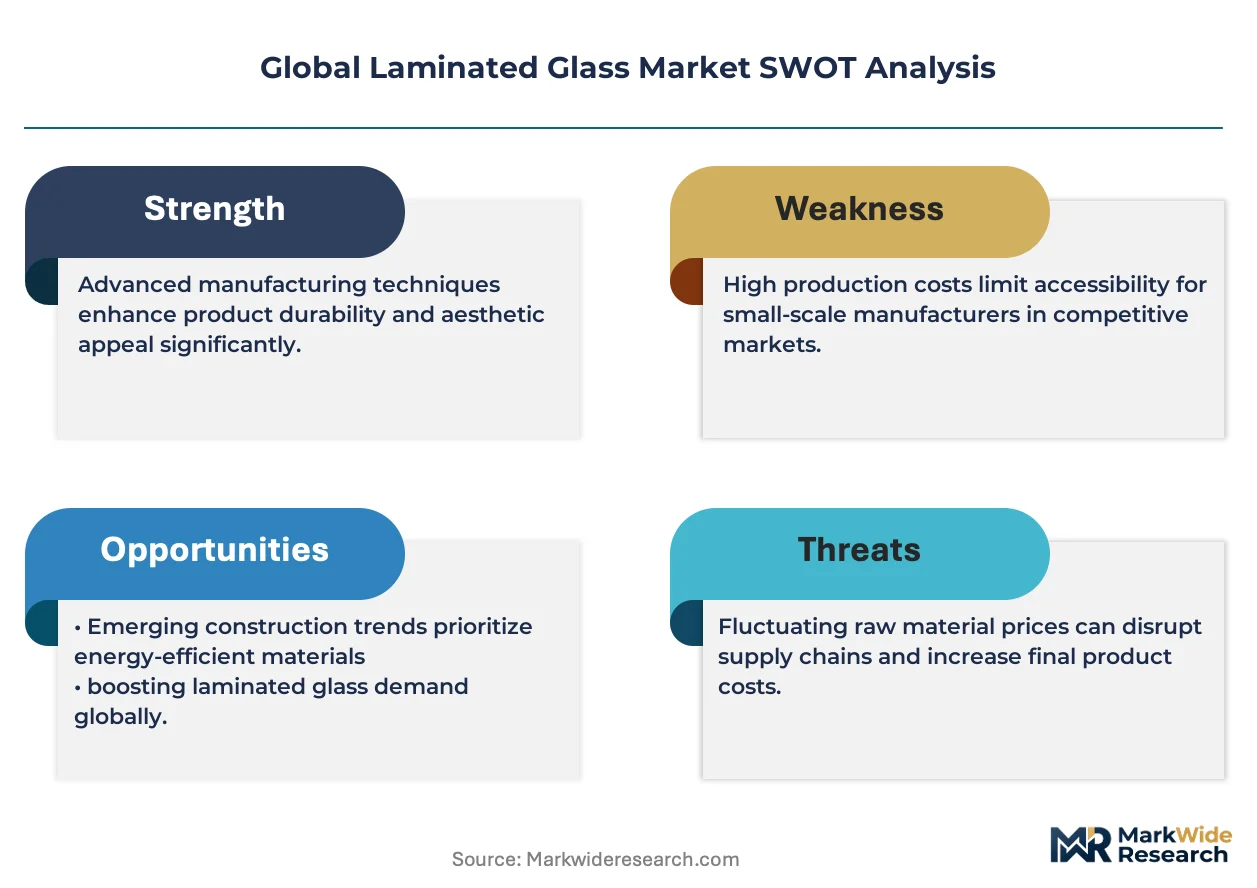
Interlayer chemistry transitions are compressing competitive margins as ionoplast formulations displace conventional PVB in structural glazing applications, forcing producers to requalify production lines or surrender high-value architectural contracts.
Growth Catalysts
- EU Green Deal carbon mandates:Building retrofit programs across Germany, France, and Italy are mandating high-performance glazing envelopes, accelerating specification of solar-control laminated glass in commercial facades.
- Automotive safety glass volumes:FMVSS 205 retention requirements and UN ECE R43 homologation standards are expanding laminated windshield fitment into mid-market vehicle segments previously served by tempered glass.
- Aerospace cabin pressure specifications:Next-generation narrowbody programs are specifying chemically strengthened laminated transparencies for weight reduction and bird-strike integrity.
Market Restraints
- Petrochemical input volatility:PVB resin pricing tracks n-butanol and polyvinyl alcohol feedstock swings, compressing interlayer margins during upstream crude disruptions.
- Float-glass supply concentration:China controls approximately 60% of global soda-lime silica float capacity, creating geographic single-point vulnerability for laminated glass substrate procurement.
- Acoustic performance ceiling:Constrained PVB damping factors at sub-20°C temperatures limit laminated glass effectiveness in Nordic and Canadian cold-climate specifications.
Strategic Opportunities
- India BIS certification tightening:Mandatory IS 2553 Part 2 compliance for architectural safety glass is blocking unqualified imports and opening joint-venture formation with domestic float-glass producers.
- Electrochromic interlayer convergence:Integration of suspended-particle device films between glass plies is creating switchable-transparency product categories for smart building retrofits.
- Direct-to-fabricator digital channels:Configurator platforms allowing architects to specify acoustic ratings, interlayer tints, and edge treatments are disintermediating traditional distributor networks in North America.
Industry Challenges
- Autoclave operator skill scarcity:Vacuum-bag assembly and pressure-cycle optimization require experienced technicians; demographic shifts in manufacturing regions are narrowing qualified labor pools.
- Parallel certification maintenance:Simultaneous compliance with FMVSS 205, EN 14449, GB 15763.3, and JIS R 3205 demands dedicated regulatory affairs capacity and extends product launch timelines.
- Legacy tempering line stranded assets:Glass processors with sunk costs in heat-strengthening furnaces face write-down pressure as laminated specifications displace tempered alternatives in hurricane-zone construction codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Laminated Glass Market |
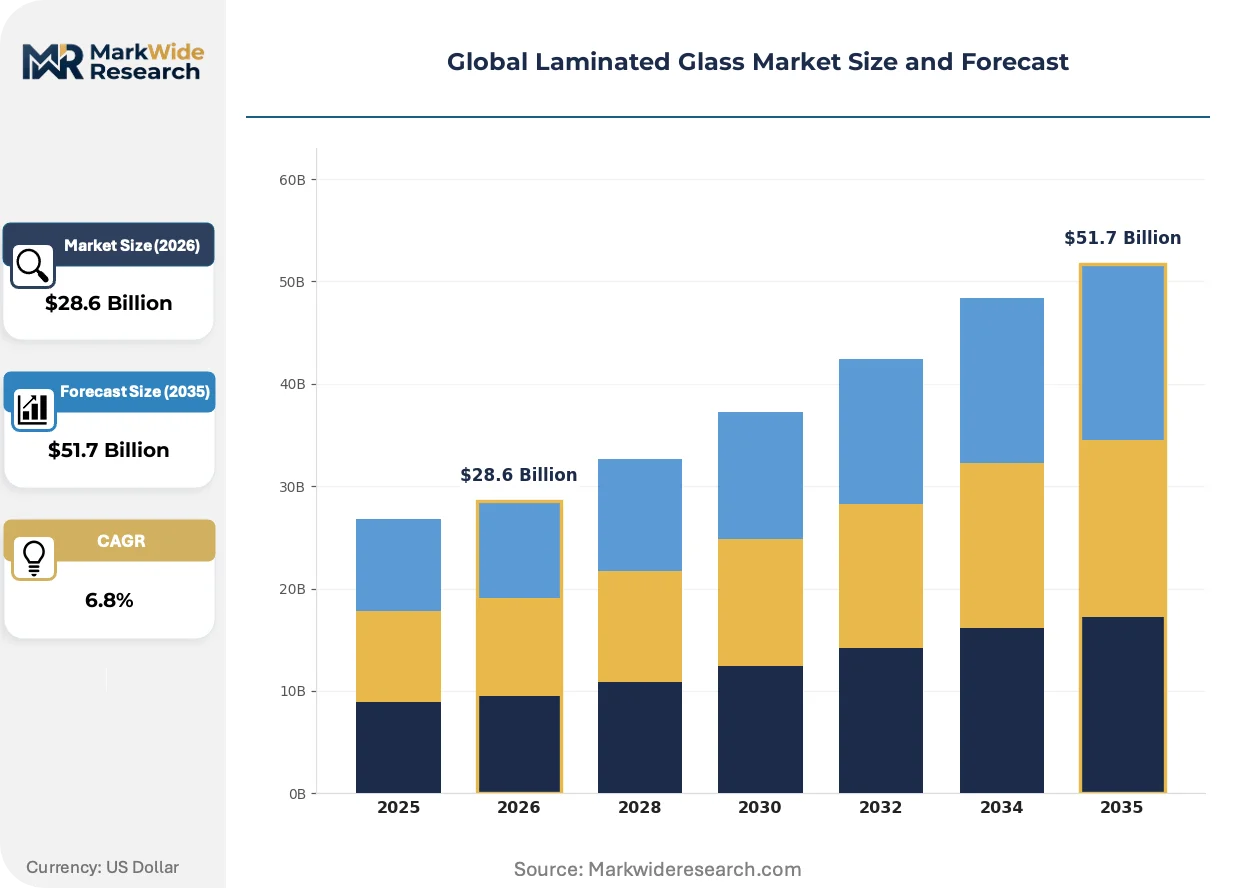
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Glass, Sound Insulation Glass, Transparent Glass, PVB Interlayers Application: Architectural, Automotive, Marine, Aerospace End User: Residential, Commercial, Industrial, Construction Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Pilkington, Guardian Industries, Saint-Gobain Glass, Nippon Sheet Glass Co. Ltd, Xinyi Glass Holdings Limited, AGC Inc., Şişecam, Fuyao Glass Industry Group Co. Ltd., Schott AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Laminated Glass Market Strategic Shifts
Ionoplast interlayer formulations are compressing the performance gap between standard PVB and structural silicone glazing, enabling heavier glass assemblies without mechanical retention hardware.
SentryGlas Plus ionoplast interlayers from Kuraray are unifying structural and safety functions in a single material layer, eliminating the need for supplemental metal edge frames in overhead glazing applications. Architectural specifiers in Singapore and Dubai are adopting these assemblies for atrium roofs and sky bridges, accepting 40% material cost premiums to achieve slimmer sightlines and reduced dead load on support steel. This chemistry shift is unifying the previously separate supply chains for safety-rated and structural-rated interlayer products, forcing compounders to reconfigure extrusion assets.
The EU Construction Products Regulation updated fire-reaction classification requirements are mandating extended burn-through resistance for high-rise facade glazing, directly elevating specification of intumescent interlayer laminates in London, Paris, and Frankfurt commercial towers. Glass processors must now maintain dual inventory of standard PVB and fire-rated interlayers, complicating production scheduling and expanding working capital requirements. Germany's DIBt approval process for these assemblies has lengthened from 12 to 18 months, compressing competitive response windows for new market entrants.
Architects and glazing contractors are consolidating procurement around performance-guaranteed supply agreements rather than spot-market sheet-glass purchasing, transferring inventory risk to processors while demanding acoustic and thermal test documentation with every delivery. This contractual shift is squeezing smaller laminators lacking in-house acoustic testing chambers and climate-simulation capabilities. The pattern is most pronounced in Scandinavian markets, where Stockholm and Oslo municipal projects now mandate 15-year performance warranties backed by third-party certification.
Global Laminated Glass Market Segmentation
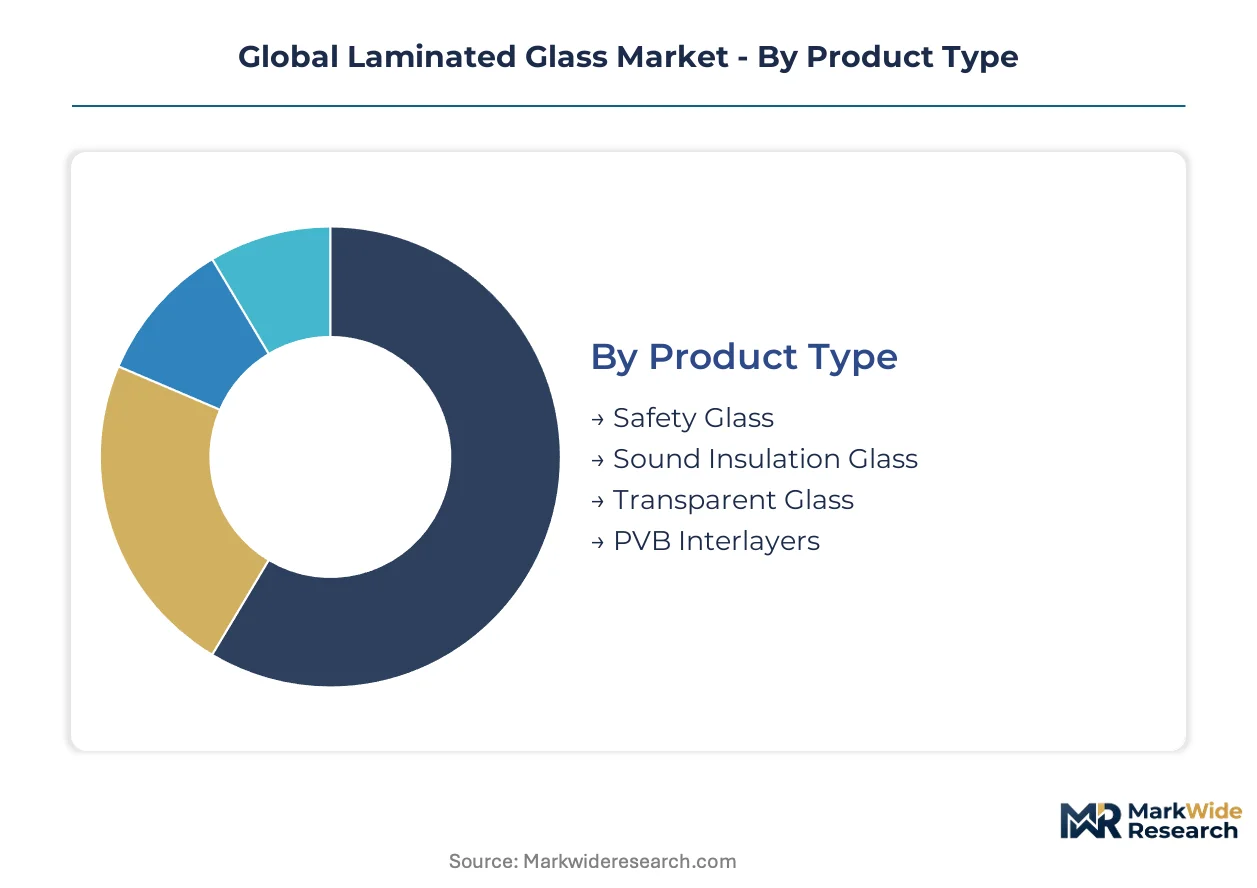
Segmentation in the laminated glass market reveals distinct procurement patterns across safety-critical versus aesthetic-driven applications. Buyers prioritize certified performance in automotive and aerospace channels while architectural segments emphasize acoustic ratings and solar-control specifications.
Product Type:
Cost tiers separate commodity-grade laminates from engineered interlayer systems commanding material premiums.
- Safety Glass:Multiple glass plies bonded with PVB or ionoplast interlayers to retain structural integrity upon impact. Automotive OEMs in Germany and the United States specify this grade for windshield retention under FMVSS 205 and UN ECE R43 homologation standards.
- PVB Interlayers:Polyvinyl butyral resin films providing shatter resistance and acoustic dampening through controlled thickness and plasticizer content. Demand concentrates in China where domestic resin compounding capacity supports high-volume architectural contracts.
- Sound Insulation Glass:Multi-layer assemblies with specialized acoustic PVB grades targeting STC ratings above 40 for urban commercial facades.
- Transparent Glass:Standard laminated configurations prioritizing optical clarity for museum displays and retail storefronts.
Volume sits with Safety Glass; growth tilts toward PVB Interlayers.
Application:
Volume scale distinguishes mature construction segments from emerging transportation platforms.
- Architectural:Curtain wall and skylight assemblies specifying laminated glass for hurricane resistance and forced-entry deterrence. Building retrofit programs across France, Italy, and Germany under the EU Green Deal mandate high-performance glazing envelopes in commercial towers.
- Aerospace:Chemically strengthened laminated transparencies for cabin pressure integrity and bird-strike resistance. Next-generation narrowbody programs in the United States and France are expanding specification of lightweight laminated systems for weight-reduction targets.
- Automotive:Windshield and sunroof laminates governed by FMVSS 205 retention requirements expanding into mid-market vehicle segments.
- Marine:Yacht and commercial vessel glazing requiring salt-corrosion resistance and ballistic protection for bridge windows.
Architectural commands current volume; aerospace climbs the fastest.
End User:
Project scale and warranty requirements differentiate procurement behavior across buyer categories.
- Commercial:Office towers, hotels, and retail complexes demanding 15-year performance warranties with third-party acoustic and thermal certification. Municipal projects in Stockholm and Oslo mandate documented climate-simulation testing for every delivery.
- Residential:High-end single-family homes and multi-unit developments specifying laminated glass for noise reduction and security in urban infill projects.
- Construction:General contractors consolidating procurement around performance-guaranteed supply agreements transferring inventory risk to processors.
- Industrial:Manufacturing facilities and warehouses utilizing laminated glass for safety partitions and observation windows.
Commercial drives specification value; residential expands most quickly.
Distribution Channel:
Customer technical sophistication determines channel selection and margin capture.
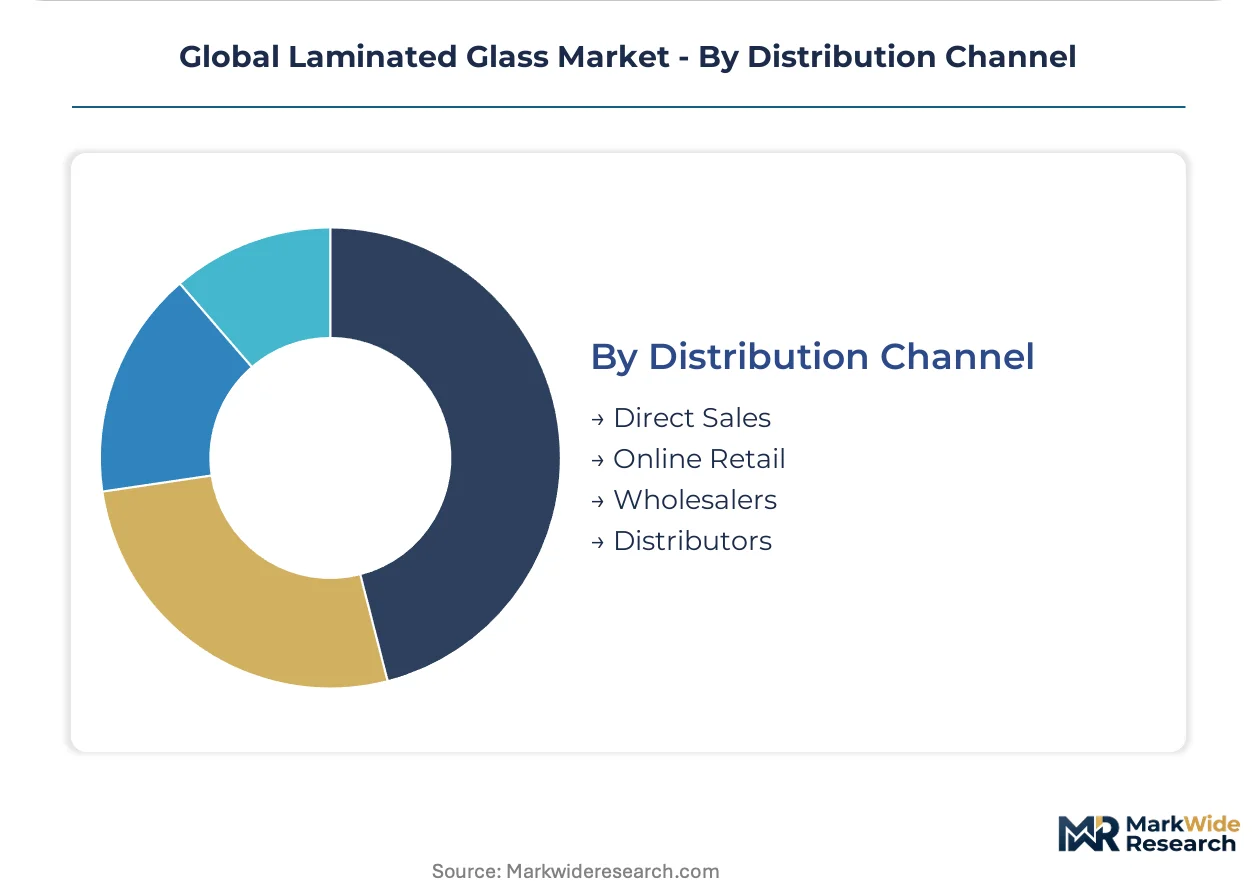
- Direct Sales:Large architectural firms and automotive OEMs engaging processors for custom specification of interlayer tints, edge treatments, and acoustic ratings. Configurator platforms in North America now enable direct-to-fabricator digital channels disintermediating traditional distributor networks.
- Distributors:Regional stocking intermediaries serving smaller glazing contractors lacking in-house testing capabilities.
- Wholesalers:Volume-based sheet-glass suppliers competing on price for standard safety-glass SKUs.
- Online Retail:Emerging channel for standardized residential replacement glass with limited customization.
Direct Sales captures premium specification; Distributors retain mid-market volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Float-glass substrate concentration in China anchors procurement patterns across the laminated glass value chain, with regional demand diverging sharply between automotive safety mandates in industrialized economies and construction-led consumption in emerging markets.
China
Domestic PVB resin compounding capacity and soda-lime silica float production dominate global substrate supply, with Xinyi Glass Holdings Limited operating mega-scale furnaces for export markets. GB 15763.3 standards enforce laminated safety glass certification for structural glazing applications. Manufacturing clusters in the Pearl River Delta and Yangtze River Delta reshape regional supply flows through dedicated export corridors.
United States
Automotive OEM demand for FMVSS 205-compliant windshields expands laminated fitment into mid-market vehicle segments previously served by tempered glass. NHTSA retention requirements govern windshield integrity during impact events. Guardian Industries anchors North American supply through float-glass lines optimized for windshield specifications in Michigan and Ohio manufacturing corridors.
Germany
EU Green Deal building retrofit programs mandate high-performance glazing envelopes in commercial towers across Berlin, Frankfurt, and Munich. DIBt approval processes for fire-rated interlayer assemblies have lengthened certification timelines. Stuttgart and Bavaria host automotive glass engineering centers serving premium OEM windshield programs.
India
Mandatory IS 2553 Part 2 BIS certification for architectural safety glass blocks unqualified imports and accelerates local joint-venture formation. CDSCO-equivalent building product regulators tighten compliance enforcement for high-rise facade applications. Maharashtra and Gujarat industrial corridors concentrate new laminator capacity to serve domestic construction demand.
Japan
JIS R 3205 framework governs laminated glass performance standards for seismic-resistant building envelopes and automotive applications. METI-indicated carbon reduction targets elevate specification of solar-control interlayers in Tokyo and Osaka commercial retrofits. Aichi Prefecture automotive clusters sustain demand for precision windshield laminates serving export vehicle programs.
Global Laminated Glass Market Competitive Environment
Capacity expansion dominates the current landscape as producers scale autoclave operations to capture aerospace and architectural contract volumes. Market structure tilts toward consolidated leadership among integrated float-glass producers with captive interlayer supply, while mid-scale laminators compete on regional certification agility. Three archetypes define positioning: integrated chemical-glass conglomerates with polymer compounding assets, automotive-dedicated specialists with OEM homologation expertise, and regional fabricators exploiting local content requirements. Competitive intensity concentrates around M&A activity targeting acoustic and fire-rated interlayer capabilities, alongside geographic expansion into India and Southeast Asia to bypass tariff exposure.
Among integrated glass-chemical conglomerates, Saint-Gobain Glass and AGC Inc. exemplify the premium-tier archetype through European and Japanese manufacturing heritage. Guardian Industries occupies a position within the North American automotive supply vector. Xinyi Glass Holdings Limited represents scale-driven competition from Chinese manufacturing bases. These three anchors demonstrate how regional regulatory specialization—FMVSS 205 in the United States, EN 14449 in Europe, GB 15763.3 in China—determines which production assets retain contract viability as ionoplast chemistry displaces conventional PVB in structural applications.
| Leading Market Players |
|---|
| Pilkington |
| Guardian Industries |
| Saint-Gobain Glass |
| Nippon Sheet Glass Co. Ltd |
| Xinyi Glass Holdings Limited |
| AGC Inc. |
| Şişecam |
| Fuyao Glass Industry Group Co. Ltd. |
| Schott AG |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM procurement consolidation around FMVSS 205-certified windshields anchors contract-based long-term offtake as the dominant pricing model, with volume commitments from Detroit and Stuttgart engineering centers dictating interlayer resin allocation across quarterly planning cycles.
Pricing Analysis
Warranty bundling separates premium architectural contracts from commodity safety-glass transactions, with Scandinavian municipal projects demanding 15-year performance guarantees backed by third-party acoustic certification while spot-market sheet-glass purchases exclude after-sales support. Three-tier pricing structure across ionoplast structural grades, acoustic PVB formulations, and standard safety laminates reflects certification complexity and raw material input differentiation. Cost compression in conventional PVB architectural grades is intensifying because Chinese resin compounding capacity expansion outpaces specification growth. Small glazing contractors exhibit highest price sensitivity due to working capital constraints, whereas aerospace OEMs prioritize bird-strike certification over unit cost.
Supply Chain Analysis
Ocean freight rate volatility from Chinese float-glass export corridors to European automotive assembly plants exerts margin pressure on just-in-time windshield programs, particularly for Bavaria and Stuttgart engineering centers dependent on Yangtze River Delta substrate shipments. Manufacturing concentration in China, Germany, and the United States shapes global laminator footprint decisions, with n-butanol and polyvinyl alcohol feedstock draws from petrochemical complexes in the US Gulf Coast and Northeast Asia. Single-source vulnerability concentrates in Chinese soda-lime silica float capacity controlling approximately sixty percent of global substrate supply. Distribution runs through regional stocking intermediaries serving mid-market glazing contractors lacking in-house acoustic testing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laminated glass market sits in an interlayer chemistry transition phase, with ionoplast formulations displacing conventional PVB in structural glazing applications and forcing asset requalification across European and North American production lines.
For Market Incumbents: Extend captive polymer compounding capabilities to sustain margin stability as petrochemical input volatility compresses interlayer margins, prioritizing backward integration into PVB resin production or joint-venture formation with domestic float-glass producers in India to preempt BIS certification barriers. Requalify autoclave lines for ionoplast extrusion to retain high-value architectural contracts against Kuraray's SentryGlas Plus penetration in Singapore and Dubai atrium specifications. For New Entrants and Emerging Players: Acoustic performance specialization offers the most penetrable wedge for mid-scale laminators lacking legacy tempering line stranded assets, targeting Nordic and Canadian cold-climate specifications where conventional PVB damping factors fail below twenty degrees Celsius. Direct-to-fabricator digital configurator platforms disintermediating traditional distributor networks in North America provide the clearest go-to-market angle for specification-grade acoustic and solar-control interlayer products. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional fabricators with BIS certification readiness in Maharashtra and Gujarat industrial corridors, where mandatory IS 2553 Part 2 compliance blocks unqualified imports and accelerates local joint-venture formation with domestic float-glass producers. Long-term viability across the analysis window hinges on interlayer chemistry transition timing, with ionoplast formulation capabilities determining which production assets retain competitive viability. The signal to monitor is DIBt approval timeline compression for fire-rated interlayer assemblies in German commercial tower retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVB Resin | Saint-Gobain Glass leverages captive polymer compounding in Europe to sustain margin stability across architectural contracts. |
| Joint Venture Formation | Local partnerships with Indian float-glass producers bypass BIS certification barriers and accelerate domestic laminator capacity deployment. |
| Autoclave Line Requalification | Ionoplast extrusion capabilities retain high-value structural glazing contracts against SentryGlas Plus penetration in Middle Eastern atrium specifications. |
| Direct-to-Fabricator Digital Channel | Configurator platforms disintermediate traditional distributor networks and capture premium specification value in North American architectural markets. |
| Fire-Rated Interlayer Inventory | Dual stock maintenance of standard PVB and intumescent grades addresses EU CPR extended burn-through resistance mandates in London and Paris commercial towers. |
Study Parameters
Document review covered trade customs data, SEC 10-K filings from listed glass manufacturers, and national standards body publications including FMVSS 205 and EN 14449 technical specifications, complemented by interviews with laminator plant managers, automotive OEM procurement leads, architectural glazing contractors, and interlayer compounder R&D directors. Bottom-up volume triangulation from regional autoclave capacity utilization was cross-referenced against top-down demand estimates derived from construction permit databases and vehicle production schedules.
Historical shipment patterns from float-glass producers were cross-referenced against panel input from procurement executives at Guardian Industries and Xinyi Glass Holdings Limited to establish baseline demand trajectories across the projection horizon. Segmentation modeling incorporated product type, application, end user, and distribution channel dimensions, with additional stratification by interlayer chemistry grade and regional regulatory cluster. CAGRs were synthesized from volume-weighted growth rates across automotive safety glass expansion, aerospace cabin pressure specifications, and EU Green Deal building retrofit programs.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to China's GB 15763.3 standard, abrupt petrochemical feedstock disruptions affecting n-butanol pricing, and accelerated ionoplast patent expirations altering competitive chemistry access. Stakeholders should weight assumptions against their own operating context and monitor interlayer material transitions as primary determinants of production asset viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Lens Market
Glass
Solar Control Glass Market
Glass
UAE Silica Sand Market
Glass
Glass Alternative Materials Market
Glass
Glass Insulator Market
Glass
Low Temperature Laminated Glass Market
Glass
Metallic Glass Market
Glass
Paper Glass Maker Market
Glass
Anti-Smudge and Anti-Streak Additives for Glass Cleaners Market
Glass
Sapphire Glass Market
Glass
Tempered Glass Market
Glass
Decorative Glass Market
Glass
East Africa Flat Glass Market
Glass
Global Scratch Resistant Glass Market
Glass
Europe Sapphire Glass Market
Glass
Middle-East and Africa Flat Glass Market