
 Solar PV Glass Market | 2026-2036
Solar PV Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Solar PV Glass Market Analysis
Project finance syndication for utility-scale solar parks is reconfiguring capital requirements for glass suppliers. Xinyi Solar Holdings leverages captive float-glass capacity to anchor cost positions across Asia-Pacific contract flows. NSG Group sustains premium positioning through specialized low-iron formulations for European module integrators. Flat Glass Group Co., Ltd. competes on volume scale from its Jiangsu manufacturing cluster.
Solar PV glass is a thermally tempered, low-iron silica panel engineered to transmit more than ninety-one percent of incident light while withstanding mechanical load, thermal cycling, and hail impact across a twenty-five-year service life. Its primary function is to protect photovoltaic semiconductor layers from environmental degradation while maximizing photon collection efficiency. Crystalline silicon technology dominates volume consumption due to entrenched supply chains and module efficiency thresholds, yet bifacial product types are capturing margin pools as dual-sided generation architectures expand. Coated glass variants command price premiums where anti-reflective surface treatments boost energy yield in high-irradiance zones.
China's MEE enforces embodied-carbon disclosure for solar glass exports under dual carbon goals, while the EU Green Deal tightens lifecycle emission benchmarks through CBAM adjustments on imported modules. The EPA in the United States and India's BIS both mandate hail-resistance and optical durability standards that filter subscale suppliers from qualification lists. Stakeholders must track how regulatory divergence on carbon accounting reshapes sourcing geography and qualification timelines.
Market Dynamics
Bifacial module penetration is restructuring procurement specifications across utility-scale solar installations, forcing glass suppliers to requalify product portfolios for dual-sided light capture and enhanced mechanical load requirements.
Growth Catalysts
- EU Green Deal carbon border adjustments:The CBAM mechanism on imported solar modules is accelerating demand for low-embodied-carbon glass formulations among European integrators seeking tariff compliance.
- Desert bifacial installations:High-albedo environments in Saudi Arabia and Arizona are pulling anti-reflective coated glass volumes as project IRR models incorporate dual-sided yield premiums.
- China's dual carbon disclosure mandate:MEE enforcement on export documentation is filtering supplier pools and concentrating contract flows toward MEE-compliant domestic manufacturers.
Market Restraints
- High-purity silica supply concentration:Premium low-iron sand deposits cluster in specific coastal regions, exposing float-glass producers to input volatility and long-haul logistics premiums.
- Float-glass furnace capex intensity:New melting capacity requires 36-48 month commissioning cycles and nine-figure capital commitments, constraining supply elasticity against demand spikes.
- Technical thickness limitations:Sub-2.0mm thermally tempered glass faces yield loss rates in mass production, capping cost-down trajectories for lightweight module designs.
Strategic Opportunities
- India PLI-linked domestic manufacturing:Production-linked incentive schemes for solar module assembly are creating captive glass demand from integrators seeking tariff shelter and BIS qualification speed.
- Perovskite tandem cell convergence:Next-generation photovoltaic architectures require modified glass surface properties and moisture barrier performance, opening formulation differentiation vectors.
- Direct utility procurement channels:Bypassing traditional module integrators, IPPs in the Middle East are issuing multi-year glass supply tenders indexed to project COD schedules.
Industry Challenges
- Optical coating technician scarcity:Magnetron sputtering and sol-gel process expertise concentrates among legacy display-industry workforces, constraining anti-reflective line expansion.
- Multi-jurisdiction certification stacking:Simultaneous BIS, IEC 61215, and UL 1703 qualification timelines extend market entry by 14-22 months for new product variants.
- Float-glass scheduling coordination:Solar-specific thickness runs disrupt furnace thermal profiles optimized for construction glass, forcing production campaign trade-offs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar PV Glass Market |
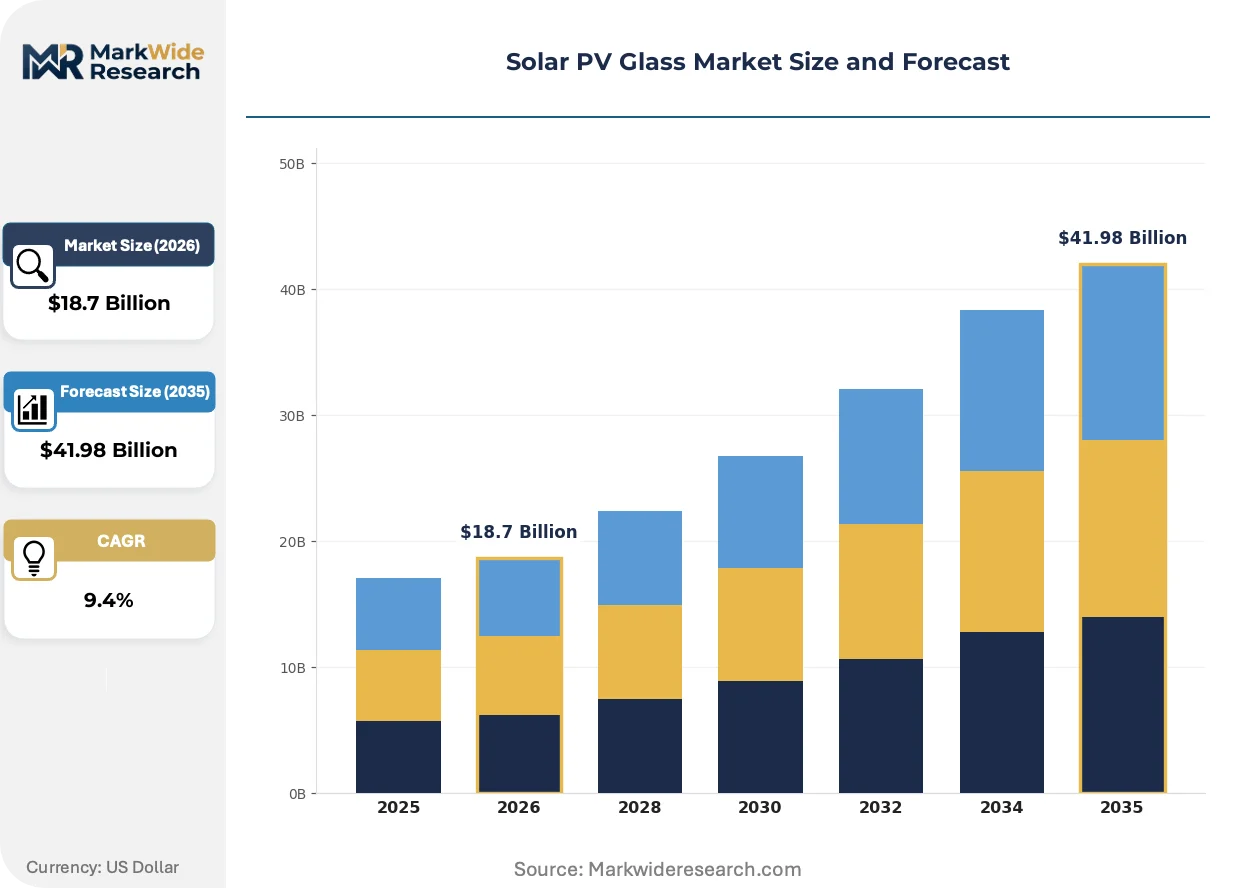
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent, Bifacial, Tinted, Coated Technology: CIGS, CdTe, Crystalline Silicon, Organic Photovoltaics Application: Residential Roofs, Commercial Roofs, Utility-Scale, Building-Integrated End User: Contractors, Installers, Manufacturers, Developers |
| Companies Covered | Dongguan CSG Solar Glass Co., Ltd., NSG Group, Xinyi Solar Holdings Ltd., First Solar, Inc., Hanwha Q CELLS, IRICO Group New Energy Co., Ltd., Qingdao Jinxin Glass Co., Ltd., Stewart Glass, Flat Glass Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar PV Glass Market Emerging Trajectories
Digital process control and inline quality verification are compressing qualification cycles while regulatory carbon accounting is rewiring sourcing geography. Demand-side contracting structures are fragmenting procurement authority across new stakeholder sets.
Inline spectral transmission monitoring is digitizing quality assurance protocols across tempering and coating lines. Tier-one module integrators in Asia-Pacific are mandating 100% lot-level optical verification, replacing statistical sampling. This digitizing of inspection workflows is compressing rejection-cycle feedback from weeks to hours and enabling predictive maintenance on furnace combustion systems.
China's MEE embodied-carbon disclosure rules are tightening export documentation requirements for solar glass shipments. Manufacturers must now submit verified lifecycle emission inventories to maintain customs clearance eligibility. European module integrators are responding by dual-sourcing from MEE-compliant Chinese suppliers and emerging Southeast Asian float-glass capacity to hedge CBAM exposure.
Long-term offtake contracting is displacing spot-market procurement among utility-scale developers. IPPs in Saudi Arabia and Arizona are locking five- to seven-year glass supply agreements indexed to polysilicon and module assembly schedules. This shift transfers inventory carrying risk upstream to glass suppliers while securing volume commitments for furnace campaign planning.
Solar PV Glass Market Segmentation
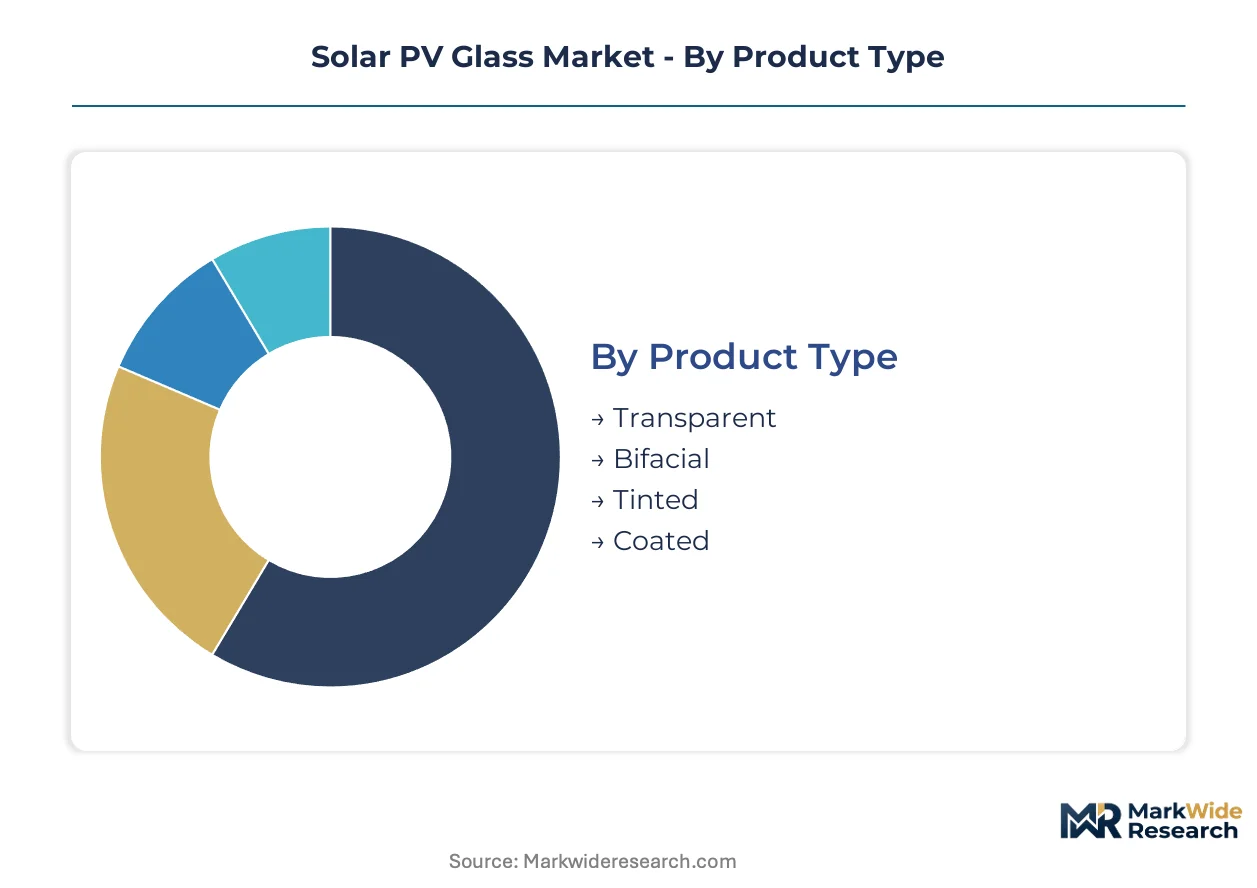
Solar PV glass segmentation reveals how product specifications, cell technologies, and installation architectures create divergent margin pools across the value chain. Procurement patterns bifurcate between commodity volume plays and premium formulations for next-generation module designs.
Product Type:
Mature transparent formulations anchor baseline procurement volumes while emerging bifacial and coated variants capture technology premiums through performance differentiation.
- Transparent:Standard low-iron soda-lime silica transmits incident light across the visible spectrum without surface modification. Utility-scale developers in India and Saudi Arabia specify transparent glass for monofacial crystalline silicon modules where cost minimization dominates procurement criteria.
- Bifacial:Thermally tempered panels engineered for dual-sided light capture with enhanced rear-side transmission and mechanical load ratings. Desert installations in Arizona and the Middle East are pulling bifacial volumes as albedo-dependent yield models justify thickness and coating premiums.
- Tinted:Iron-doped formulations reducing transmission for aesthetic integration in building-applied systems. European building-integrated photovoltaic projects specify tinted variants for facade compliance with heritage architecture guidelines.
- Coated:Anti-reflective surface treatments via magnetron sputtering or sol-gel deposition boosting photon collection efficiency. High-irradiance zones in the southwestern United States and Australia's interior mandate coated glass for energy yield optimization.
Transparent glass retains volume leadership; bifacial holds the steepest expansion curve.
Technology:
Cost tier stratification separates entrenched crystalline silicon volume from thin-film and emerging organic architectures competing on form factor and manufacturing flexibility.
- Crystalline Silicon:Dominant photovoltaic architecture requiring tempered glass with 3.2mm standard thickness for mechanical protection and moisture barrier performance. Chinese and Southeast Asian module assembly clusters consume crystalline silicon glass at scale for export markets.
- CdTe:Cadmium telluride thin-film technology deploying specialized glass substrates as active device layers rather than protective covers. First Solar's manufacturing footprint in Ohio and Malaysia drives CdTe glass substrate demand with distinct chemical durability specifications.
- CIGS:Copper indium gallium selenide flexible and rigid configurations utilizing lightweight glass or polymer barriers. Building-integrated and portable power applications in Japan and South Korea specify CIGS for weight-constrained installations.
- Organic Photovoltaics:Emerging polymer-based cells requiring barrier glass with moisture and oxygen transmission rates below 10^-3 g/m²/day. Perovskite tandem research programs in European laboratories are piloting organic-compatible glass formulations.
Crystalline silicon commands procurement volume; organic photovoltaics presents the most rapid technology climb.
Application:
Customer type fragmentation distinguishes residential self-consumption, commercial behind-the-meter, and utility-scale merchant power procurement with divergent glass specification priorities.
- Utility-Scale:Ground-mounted solar parks above 50MW capacity specifying standardized glass dimensions for automated module assembly and field installation logistics. IPPs in the Middle East and India issue multi-year offtake tenders indexed to project COD schedules.
- Commercial Roofs:Distributed generation on warehouses, retail, and industrial facilities requiring structural load compliance and rapid installation protocols. Bifacial glass penetration lags in commercial segments due to roof albedo limitations and racking cost constraints.
- Residential Roofs:Single-family and multi-family rooftop systems prioritizing aesthetic integration and weight minimization. California and Australian residential markets specify black-framed modules with reduced glass reflectivity for neighborhood compatibility.
- Building-Integrated:Architectural glass replacing conventional facade and skylight materials with semi-transparent or colored photovoltaic surfaces. EU Green Deal energy performance standards are accelerating building-integrated adoption in Germany and the Netherlands.
Utility-scale applications dominate procurement tonnage; building-integrated is gaining share fastest.
End User:
Supply concentration varies across the value chain with module manufacturers integrating glass procurement while developers and contractors source through distributor channels.
- Manufacturers:Tier-one module integrators in China and Southeast Asia purchasing glass directly from float-glass producers under long-term supply agreements. Xinyi Solar Holdings and NSG Group anchor manufacturer supply relationships through captive capacity and specialized formulations.
- Developers:Utility-scale IPPs in Saudi Arabia, Arizona, and India issuing direct glass supply tenders to secure volume commitments for project finance timelines. Developer-procured glass transfers inventory risk upstream while locking furnace campaign scheduling.
- Contractors:Engineering-procurement-construction firms sourcing glass-inclusive modules through distributor networks for commercial and residential installations. Contractor procurement concentrates on BIS and UL qualification compliance for local market access.
- Installers:Local and regional installation specialists purchasing modules through wholesale channels with limited direct glass specification influence. Installer feedback loops on field breakage rates inform manufacturer quality protocols.
Manufacturers retain direct procurement volume leadership; developers are capturing the steepest procurement authority expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and the EU Green Deal are rewiring procurement geography for solar PV glass, concentrating contract flows toward MEE-compliant manufacturers and low-embodied-carbon suppliers. Utility-scale developers in India and the Middle East are accelerating direct procurement channels to secure volume commitments for project finance timelines.
China
Domestic module assembly clusters in Jiangsu and Anhui provinces consume crystalline silicon glass at scale for export markets. The MEE enforces embodied-carbon disclosure documentation for solar glass exports, filtering supplier pools toward compliant domestic manufacturers. Float-glass producers in the Yangtze River Delta are reconfiguring furnace campaigns to accommodate solar-specific thickness runs.
United States
Utility-scale IPPs in Arizona are issuing multi-year glass supply tenders indexed to project COD schedules for desert bifacial installations. The EPA mandates hail-resistance and optical durability standards that filter subscale suppliers from qualification lists. Manufacturing activity concentrates in Ohio where CdTe substrate demand from thin-film facilities drives specialized chemical durability specifications.
India
Production-linked incentive schemes for solar module assembly are creating captive glass demand from integrators seeking tariff shelter and BIS qualification speed. The Bureau of Indian Standards enforces mechanical load and thermal cycling benchmarks that extend market entry timelines for new product variants. Gujarat and Rajasthan host the densest concentrations of utility-scale solar parks specifying standardized glass dimensions.
Germany
European module integrators are dual-sourcing from MEE-compliant Chinese suppliers and emerging Southeast Asian float-glass capacity to hedge CBAM exposure. The EU Green Deal tightens lifecycle emission benchmarks through carbon border adjustments on imported modules. Building-integrated photovoltaic projects in Bavaria specify tinted variants for facade compliance with heritage architecture guidelines.
Saudi Arabia
High-albedo desert environments are pulling anti-reflective coated glass volumes as project IRR models incorporate dual-sided yield premiums. Direct utility procurement channels are bypassing traditional module integrators with multi-year supply tenders. The Kingdom's solar manufacturing zones in the Eastern Province are anchoring regional supply chain development for Middle East project pipelines.
Solar PV Glass Market Vendor Landscape
On the supply side, the industry is consolidating around float-glass producers with captive melting capacity and specialized formulation capabilities. Three archetypes dominate: integrated glass-to-module conglomerates with furnace ownership, independent float-glass specialists supplying merchant markets, and thin-film cell manufacturers with proprietary substrate requirements. Competitive moves concentrate on backward integration into silica supply and geographic expansion through qualification stacking across multiple jurisdictions.
Among Asia-Pacific-based producers, Xinyi Solar Holdings Ltd., Flat Glass Group Co., Ltd., and IRICO Group New Energy Co., Ltd. exemplify the integrated archetype with positions spanning float-glass melting through module supply relationships. NSG Group represents the premium formulation specialist tier serving European integrators with low-iron specifications. First Solar, Inc. occupies a distinct position as a thin-film cell manufacturer with captive glass substrate demand, while Dongguan CSG Solar Glass Co., Ltd. and Qingdao Jinxin Glass Co., Ltd. sit within the merchant supply tier focused on volume scale.
| Leading Market Players |
|---|
| Dongguan CSG Solar Glass Co., Ltd. |
| NSG Group |
| Xinyi Solar Holdings Ltd. |
| First Solar, Inc. |
| Hanwha Q CELLS |
| IRICO Group New Energy Co., Ltd. |
| Qingdao Jinxin Glass Co., Ltd. |
| Stewart Glass |
| Flat Glass Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
CBAM exposure on European solar module imports compresses margin pools for non-compliant suppliers while amplifying spreads between MEE-certified Chinese glass and emerging Southeast Asian alternatives. This regulatory chokepoint simultaneously widens pricing tiers and accelerates geographic diversification in sourcing strategies.
Pricing Analysis
Anti-reflective coating sophistication creates the primary spread between commodity transparent glass and premium bifacial formulations. Three-tier pricing structure across premium coated, standard tempered, and economy transparent levels reflects certification stacking burden and optical performance variance. Cost compression in economy transparent tiers intensifies because Indian PLI-linked module integrators prioritize volume procurement over specification premiums. Utility-scale IPPs in Saudi Arabia exhibit lowest price sensitivity due to project IRR models capturing dual-sided yield premiums, while residential installers in California face acute cost pressure from permitting overhead and labor inflation.
Supply Chain Analysis
High-purity low-iron silica deposits in coastal Australia, Vietnam, and the United States anchor upstream feedstock availability for float-glass producers. Solar PV glass production draws from soda-lime silica, magnetron sputtering targets, and thermal tempering furnace infrastructure. Single-source vulnerability concentrates in Yangtze River Delta melting capacity where furnace campaign scheduling conflicts between construction and solar thickness runs create allocation bottlenecks. Distribution runs through direct long-term offtake contracts from glass manufacturers to tier-one module integrators, bypassing traditional distributor networks for utility-scale volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat industry where regulatory entrenchment in multi-jurisdiction certification stacking creates switching costs that protect qualified incumbents from rapid displacement.
For Market Incumbents: Insulate furnace utilization rates through captive module integrator relationships and MEE compliance documentation that filters competitor qualification timelines. Expand tempering capacity in Gujarat and Arizona to capture India PLI-linked demand and Arizona desert bifacial procurement. Perovskite tandem cell convergence threatens existing formulation expertise, necessitating R&D investment in moisture barrier glass architectures. For New Entrants and Emerging Players: Southeast Asian float-glass capacity expansion represents the most penetrable white-space opportunity as European integrators dual-source to hedge CBAM exposure. Target building-integrated photovoltaic segments in Germany and the Netherlands where heritage facade compliance requirements favor specialized tinted formulations over commodity transparent supply. Pursue qualification stacking through BIS and IEC 61215 concurrent pathways to compress market entry timelines against legacy competitors. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment implementation reshapes the acquisition landscape toward MEE-compliant Chinese assets and Southeast Asian greenfield capacity. Five-to-ten year viability centers on furnace ownership positions with solar-specific thickness campaign flexibility and coating line technical depth. Signal to monitor: BIS enforcement speed in India and EPA hail-resistance standard revisions that extend qualification barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Mining | Secures low-iron sand supply from Australian coastal deposits against logistics volatility. |
| Multi-Jurisdiction Certification Stacking | Compresses BIS, IEC 61215, and UL 1703 timelines to capture India and Arizona utility demand. |
| Anti-Reflective Coating Line Expansion | Addresses magnetron sputtering technician scarcity constraining premium glass output. |
| Direct IPP Offtake Contracting | Locks five-to-seven-year volume commitments from Saudi and Arizona developers. |
| Perovskite-Compatible Formulation Development | Positions for next-generation tandem cell moisture barrier requirements in European labs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs documentation, SEC filings from listed glass manufacturers, and IEA solar deployment databases. Primary interviews engaged float-glass plant managers, module integrator procurement directors, utility IPP development officers, and EPC contractor logistics heads. Secondary validation drew from Bureau of Indian Standards certification registries, MEE embodied-carbon disclosure filings, and FERC interconnection queues. Bottom-up capacity modeling and top-down demand projection triangulation anchored volume estimates.
Forecast inputs include bifacial penetration trajectories, CBAM adjustment schedules, and furnace commissioning cycles across the projection horizon. Segmentation dimensions encompass product type, cell technology architecture, installation scale tier, and end-user procurement channel. CAGRs derive from polynomial trend fitting against historical capacity utilization and polysilicon supply elasticity. Industry-specific inputs capture albedo-dependent yield model adoption in desert installations and PLI scheme uptake velocity in India.
Practitioners should monitor MEE enforcement consistency, BIS qualification backlog lengths, and perovskite tandem cell pilot scale-up for early signals requiring forecast revision. Cross-checking against IEA renewable capacity deployment benchmarks and module export customs data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Scratch Resistant Glass Market
Glass
Borosilicate Glass Market
Glass
Low Iron Glass Market
Glass
Laboratory Glass Container Market
Glass
Foam Glass Market
Glass
Antibacterial Glass Market
Glass
Technical Glass Market
Glass
Glass Lens Market
Glass
Impact Resistant Glass Market
Glass
Pharmaceutical Glass Tubing Market
Glass
Insulating Glass Market
Glass
Ultra Violet Glass Bottles Market
Glass
Glass Reactors Market
Glass
Glass Balustrade Lamination Market
Glass
Metallic Glass Market
Glass
Glass Alternative Materials Market