
 Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market | 2026-2036
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market Size, Share, and Industry Trends Forecast 2026-2036
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market Foresight
Chinese specialty compounders is rebalancing regional supply as domestic automakers specify halogen-free cable jacketing. SABIC leverages its global resin platform to serve Middle Eastern infrastructure projects requiring low-smoke specifications. Lanxess AG anchors European demand through its phosphorus-nitrogen flame retardant systems integrated into PP compounds for railway interiors.
Low smoke halogen free flame retardant polypropylene denotes a thermoplastic formulation combining polypropylene resin with metal hydroxide or intumescent char-forming additives to achieve UL 94 V-0 classification while limiting smoke density to below 200 Ds max per ASTM E662. The material serves critical fire-safety roles in enclosed spaces where toxic halogen gas release poses evacuation hazards. PP compounds dominate current volume owing to pre-compounded additive dispersion that downstream processors favor for thin-wall electrical insulation consistency. High thermal stability grades capture expanding margin pools as electric vehicle battery module housings require continuous operating temperatures above 120°C without flame retardant decomposition.
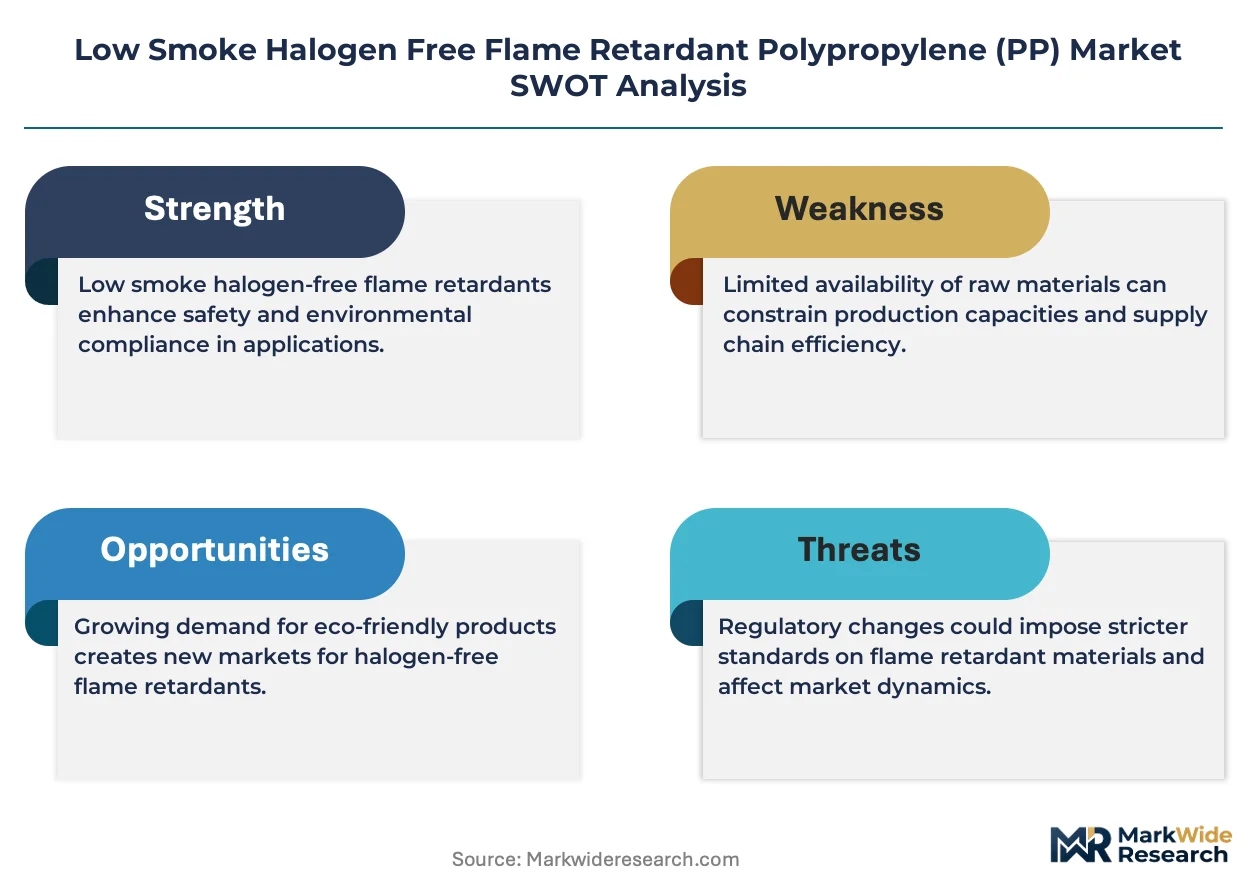
The EU's REACH regulation and RoHS directive restrict brominated and chlorinated flame retardants in electrical equipment sold across member states, directly channeling OEM procurement toward halogen-free alternatives. China's GB standards for railway and building wire, enforced by SAMR conformity assessment, mandate smoke density thresholds that only intumescent PP systems reliably satisfy. Stakeholders must monitor evolving flammability test protocols for 5G base station enclosures and energy storage cabinets, as these emerging specifications will determine which compound formulations achieve design-in status before volume procurement cycles commence.
Market Dynamics
REACH and RoHS substitution mandates are compressing the addressable market for halogenated alternatives while metal hydroxide supply concentration in China's magnesium processing belt creates input cost volatility for compounders.
Growth Catalysts
- EU Green Deal building renovation wave:Public procurement rules now prioritize low-smoke cable specifications in infrastructure tenders, channeling volume toward halogen-free PP jacketing for electrical distribution.
- Data center hyperscaler construction:Plume management and evacuation safety protocols at facilities operated by major cloud providers specify ASTM E662-compliant materials for underfloor cable trays.
- Electric vehicle platform electrification:Battery module housings and high-voltage harness routing demand continuous-use thermal performance above 120°C without additive decomposition.
Market Restraints
- Magnesium hydroxide supply concentration:Over 70% of flame retardant-grade hydrate originates from Liaoning province processing facilities, exposing compounders to energy rationing and export quota volatility.
- Loadings-driven mechanical degradation:Achieving UL 94 V-0 classification requires 60-65% additive by weight, reducing impact strength and limiting thin-wall injection molding applications.
- Intumescent system cost premium:Phosphorus-nitrogen formulations cost 40-50% more per compound kilogram than metal hydroxide alternatives, constraining adoption in cost-sensitive appliance wiring.
Strategic Opportunities
- India building wire modernization:BIS implementation of smoke density standards for commercial high-rises creates first-mover advantage for GB-compliant compounders entering through joint ventures with local cable manufacturers.
- 5G base station enclosure specifications:Telecom infrastructure operators are drafting flame retardancy protocols for outdoor cabinet housings that prioritize low-smoke performance over halogenated legacy materials.
- Phosphorus-nitrogen intumescent convergence:Combination of expandable graphite with melamine polyphosphate systems enables thinner-wall designs without sacrificing mechanical properties.
Industry Challenges
- Compounder formulation expertise scarcity:Metal hydroxide dispersion engineering and intumescent char-formation optimization require polymer scientists with 10+ years of flame retardant system experience, a talent pool concentrated at a handful of European and Japanese specialists.
- Multi-jurisdiction certification timelines:Achieving UL recognition, VDE approval, and CCC conformity assessment for a single compound grade extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market |
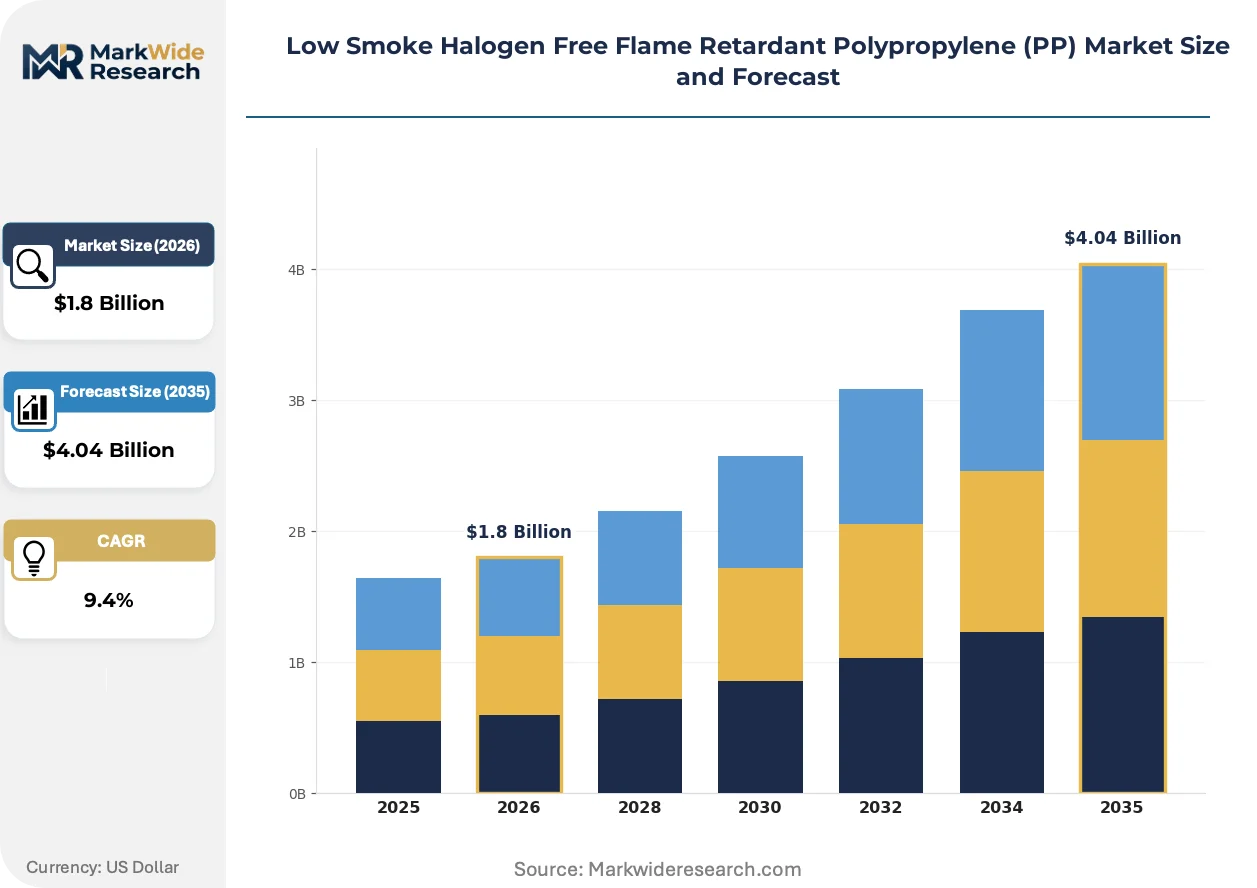
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PP Homopolymer, PP Copolymer, PP Compounds, PP Blends Application: Electrical Insulation, Automotive Interiors, Building Materials, Consumer Electronics Grade: Standard Grade, High Thermal Stability, Low Density, Impact Resistant End User: Electronics Manufacturers, Automotive Suppliers, Construction Firms, Furniture Producers |
| Companies Covered | SABIC, Lanxess AG, Borealis AG, MERICK POLYMERS CO.,LTD., LyondellBasell Industries N.V., Avient Corporation, Clariant AG, POLYROCKS CHEMICAL CO., LTD., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market Shifts & Advancements
Flame retardant PP formulation is bifurcating between commodity metal hydroxide loadings for cost-driven applications and advanced intumescent systems for performance-critical segments, with processing technology bridging the gap.
Surface-treated nano-magnesium hydroxide is integrating silane coupling agent modifications that improve dispersion at reduced loadings. Electric vehicle battery housing manufacturers in Germany and South Korea are qualifying these grades for module enclosures. This integration is compressing the performance gap between metal hydroxide and phosphorus-nitrogen systems at mid-range price points.
REACH Annex XIV authorization requirements for brominated diphenyl ethers are forcing compounders to reformulate legacy electrical insulation grades by 2026. Cable manufacturers serving EU infrastructure projects now specify halogen-free alternatives in 90% of new tenders. Railway interior applications under EN 45545-2 are experiencing the most acute substitution pressure, with smoke density specifications that only intumescent PP reliably satisfies.
Specification-driven procurement now dominates electrical infrastructure purchasing, with engineering teams mandating certified compound grades before volume negotiations commence. Distributor stocking of generic PP resins is collapsing as project-based buying consolidates around pre-approved supplier lists. This pattern is most pronounced in Middle Eastern smart city developments where master contractor frameworks lock in compound sources for multi-year construction phases.
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market Segmentation
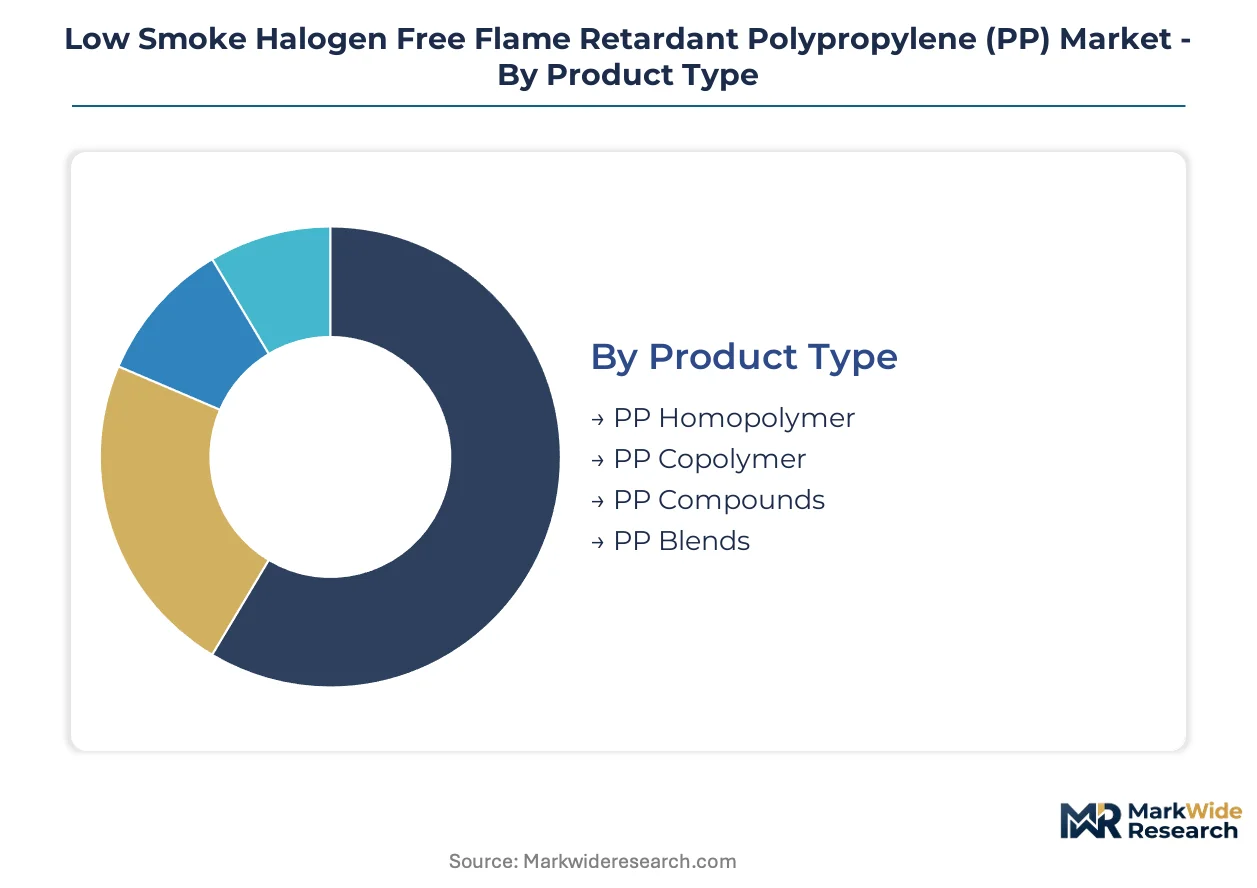
Segmentation in low smoke halogen free flame retardant PP reveals how material specifications diverge across standalone electrical insulation versus embedded automotive and construction systems. Understanding these integration patterns exposes where compounders must maintain discrete inventory versus where masterbatch approaches suffice.
Product Type:
Homopolymer grades serve primarily as standalone cable jacketing where processors demand pre-dispersed additive packages, while copolymer and blend formulations embed into complex multi-material assemblies requiring compatibility tuning.
- PP Homopolymer:High crystallinity base resin delivers superior tensile strength for thin-wall electrical insulation. Chinese appliance wiring manufacturers in Zhejiang and Guangdong provinces specify homopolymer compounds for GB-compliant building wire production, driven by SAMR enforcement of smoke density thresholds in commercial high-rises.
- PP Copolymer:Ethylene incorporation improves low-temperature ductility for automotive underhood applications. German EV battery housing suppliers are qualifying copolymer grades for module enclosures requiring continuous operation above 120°C without flame retardant decomposition.
- PP Compounds:Pre-compounded metal hydroxide or intumescent systems dominate volume through distributor channels serving injection molders lacking dispersion expertise.
- PP Blends:Elastomer-modified formulations balance impact resistance with flame retardancy for railway interior panels under EN 45545-2 specifications.
Volume placements concentrate in PP Compounds; the faster expansion belongs to PP Copolymer.
Application:
Application segmentation tracks how fire safety specifications propagate from enclosed electrical infrastructure through mobility and building systems with varying smoke toxicity exposure profiles.
- Electrical Insulation:Cable jacketing and connector housings constitute the foundational demand pool. Data center hyperscalers operating facilities in Virginia, Frankfurt, and Singapore mandate ASTM E662-compliant materials for underfloor cable trays, prioritizing evacuation safety in densely server-populated spaces.
- Automotive Interiors:Battery module housings and high-voltage harness routing require thermal stability beyond legacy metal hydroxide limits. South Korean automakers specify phosphorus-nitrogen intumescent systems for EV platforms, accepting 40-50% cost premiums to achieve thinner-wall designs.
- Building Materials:Wire and cable jacketing for commercial construction faces divergent code adoption timelines across jurisdictions.
- Consumer Electronics:Charger housings and power adapter enclosures represent cost-constrained applications where metal hydroxide loadings predominate despite mechanical trade-offs.
Electrical Insulation commands the largest volume commitment; Automotive Interiors exhibits the steepest expansion trajectory.
Grade:
Grade differentiation reflects the thermal performance hierarchy imposed by electrification trends, with standard formulations ceding ground to engineered stability tiers.
- Standard Grade:Metal hydroxide loadings of 60-65% by weight achieve UL 94 V-0 classification for ambient-temperature electrical applications. Appliance wiring manufacturers in China's eastern manufacturing corridor favor standard grades for cost-sensitive production, though impact strength limitations constrain thin-wall injection molding.
- High Thermal Stability:Phosphorus-nitrogen intumescent systems maintain flame retardancy above 120°C continuous operation. German and South Korean EV battery housing manufacturers are driving qualification programs for these grades, prioritizing additive thermal integrity over raw material cost.
- Low Density:Reduced specific gravity formulations target aerospace and weight-sensitive transportation applications where every gram compounds across production scale.
- Impact Resistant:Elastomer-toughened compounds address railway interior specifications requiring combined smoke suppression and mechanical durability under EN 45545-2.
Standard Grade retains the broadest installed base; High Thermal Stability is climbing the fastest.
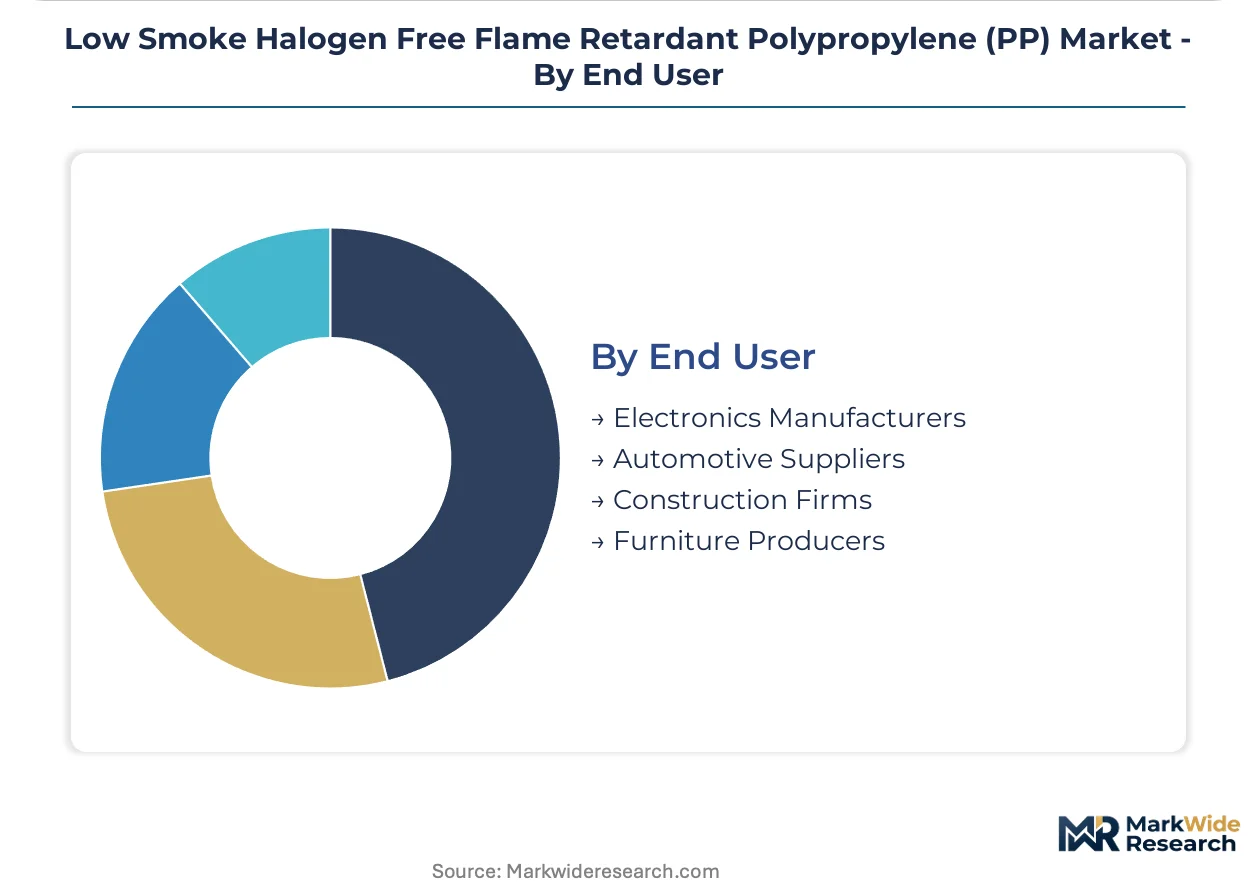
End User:
End user segmentation maps how procurement authority concentrates among specification-setting OEMs versus price-tolerant tier suppliers.
- Electronics Manufacturers:Data center equipment builders and telecom infrastructure operators wield design-in authority over compound selection. Cloud providers operating hyperscale facilities in Ashburn, Loudoun County, and Frankfurt specify certified grades before volume negotiations, collapsing distributor stocking of generic alternatives.
- Automotive Suppliers:Tier-1 wiring harness and battery housing producers translate OEM thermal performance requirements into compound specifications. Korean battery subsystem suppliers are consolidating approved vendor lists around intumescent-capable compounders.
- Construction Firms:Project-based procurement through master contractor frameworks locks in compound sources for multi-year phases, particularly in Middle Eastern smart city developments.
- Furniture Producers:Upholstery and panel applications represent fragmented demand with limited specification sophistication.
Electronics Manufacturers anchor current volume; Automotive Suppliers are gaining share fastest as EV platform electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Liaoning province's magnesium hydroxide processing belt anchors raw material supply for flame retardant compounders worldwide. Regional demand patterns diverge sharply between mature regulatory environments and rapidly industrializing manufacturing corridors.
China
Zhejiang and Guangdong appliance wiring manufacturers drive homopolymer consumption for GB-compliant building wire. SAMR enforcement of smoke density thresholds in commercial high-rises channels procurement toward intumescent systems. The eastern manufacturing corridor concentrates cable jacketing production for domestic automakers specifying halogen-free harnessing.
Germany
EV battery housing suppliers in Baden-Württemberg qualify high thermal stability grades for module enclosures above 120°C continuous operation. REACH Annex XIV authorization timelines force compounders to reformulate legacy electrical insulation grades by 2026. Railway interior applications under EN 45545-2 specifications concentrate demand in Bavaria's automotive supply cluster.
United States
Virginia data center hyperscalers mandate ASTM E662-compliant materials for underfloor cable trays across Ashburn and Loudoun County facilities. State-level building code adoption for low-smoke specifications varies, with California and New York leading enforcement. Cloud infrastructure procurement teams wield design-in authority over certified compound grades before volume negotiations.
South Korea
Battery subsystem suppliers consolidate approved vendor lists around phosphorus-nitrogen intumescent systems for EV platforms. Domestic automakers accept 40-50% cost premiums to achieve thinner-wall designs in high-voltage harness routing. The Seoul Capital Area concentrates tier-1 wiring harness production for export-oriented vehicle programs.
India
BIS implementation of smoke density standards for commercial high-rises creates entry pathways for GB-compliant compounders through joint ventures with local cable manufacturers. Maharashtra and Gujarat industrial corridors concentrate building wire modernization projects. Central government infrastructure tenders increasingly specify low-smoke cable performance in metro rail and airport expansions.
Low Smoke Halogen Free Flame Retardant Polypropylene (PP) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue high thermal stability specializations for electrification applications. The vendor base stratifies between commodity metal hydroxide compounders and intumescent system specialists with formulation expertise scarcity. Three archetypes dominate: global resin platforms with regional compounding networks, European phosphorus-nitrogen technology anchors, and Chinese integrated magnesium hydroxide processors. Competitive moves concentrate on backward integration into flame retardant additive supply and multi-jurisdiction certification acceleration.
Among global resin platforms, SABIC leverages its geographic footprint to serve infrastructure projects requiring low-smoke specifications. Lanxess AG anchors European demand through phosphorus-nitrogen flame retardant systems integrated into railway interior compounds. Borealis AG occupies a position within the integrated polyolefin producer tier, bridging standard and specialty grade supply. These three exemplify how technical compounding expertise concentrates at established European and Middle Eastern headquarters while manufacturing presence extends into Asian growth markets.
| Leading Market Players |
|---|
| SABIC |
| Lanxess AG |
| Borealis AG |
| MERICK POLYMERS CO.,LTD. |
| LyondellBasell Industries N.V. |
| Avient Corporation |
| Clariant AG |
| POLYROCKS CHEMICAL CO., LTD. |
| BASF SE |
| Others |
Supply & Pricing Matrix
Polymer scientists with 10-plus years of flame retardant system experience concentrate in European and Japanese specialist firms, creating labor-cost differentials that widen pricing-tier spreads between certified premium compounds and commodity metal hydroxide alternatives.
Pricing Analysis
Warranty-backed certification packages bundle UL recognition, VDE approval, and CCC conformity assessment into premium-tier offerings while economy grades ship with basic material data sheets unbundled from regulatory support. Three-tier pricing structure across premium, standard, and economy levels separates phosphorus-nitrogen intumescent systems from surface-treated nano-magnesium hydroxide grades from legacy metal hydroxide loadings. Cost compression in standard-grade metal hydroxide compounds is intensifying because Chinese magnesium processing belt energy rationing feeds raw material volatility into compounder margins. Appliance wiring manufacturers in China's eastern manufacturing corridor exhibit highest price sensitivity, while German EV battery housing suppliers accept substantial cost premiums for thermal stability assurance.
Supply Chain Analysis
Scrap compound reprocessing and additive recovery flows remain underdeveloped, constraining circularity in a market where formulation expertise scarcity limits secondary material qualification. Raw material supply draws from China's Liaoning province magnesium hydroxide processing belt, German phosphorus-nitrogen specialty chemical production, and Japanese intumescent additive manufacturing. Flame retardant-grade magnesium hydroxide, melamine polyphosphate systems, and silane coupling agents constitute critical input dependencies. Single-source vulnerability in Liaoning's energy-intensive hydrate processing exposes compounders to export quota disruptions and electricity rationing. Distribution runs through project-based master contractor frameworks in Middle Eastern smart city developments and pre-approved supplier lists at data center hyperscalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XIV authorization requirements for brominated diphenyl ethers erect a cost-of-compliance barrier that moats qualified halogen-free compounders against legacy reformulation laggards.
For Market Incumbents: Hedge against magnesium hydroxide supply volatility by securing captive offtake agreements with Liaoning processors or qualifying alternative hydrate sources in Israel and Turkey. Deepen backward integration into phosphorus-nitrogen additive manufacturing to defend margin position against intumescent system cost premiums eroding competitiveness in automotive interiors. For New Entrants and Emerging Players: The 40-50 percent price-point gap between premium intumescent and economy metal hydroxide grades opens white-space at mid-range thermal stability positioning. Target India's building wire modernization through joint ventures with Maharashtra and Gujarat cable manufacturers seeking GB-compliant compound partners. Lead with certified compound grades rather than generic resin distribution to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with European phosphorus-nitrogen technology anchors given EU Green Deal building renovation wave procurement rules channeling volume toward low-smoke specifications. Five-to-ten year viability favors compounders with multi-jurisdiction certification portfolios and backward integration into flame retardant additive supply. Monitor 5G base station enclosure specification drafts as inflection signal for design-in status before volume procurement cycles commence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive phosphorus-nitrogen supply secures margin control against 40-50% cost premiums. |
| Multi-Jurisdiction Certification Acceleration | Compressed UL-VDE-CCC timelines capture design-in status before hyperscaler procurement. |
| Joint Venture in India Building Wire | BIS smoke density enforcement creates first-mover advantage through local cable partnerships. |
| Surface-Treated Nano-Hydroxide Qualification | German and South Korean EV battery housing programs drive mid-tier thermal stability adoption. |
| Intumescent System R&D Convergence | Expandable graphite-melamine polyphosphate combinations enable thinner-wall railway interior panels. |
Research Methodology
Independent corroboration across technical directors at European compounders, procurement leads at German automotive Tier 1 suppliers, and regulatory affairs specialists at cable manufacturers underwrites the qualitative findings. Primary interviews with plant managers at Chinese magnesium hydroxide processors, flame retardant R&D directors at Japanese specialty chemical firms, and distribution channel partners serving Middle Eastern infrastructure projects combined with secondary validation from ECHA REACH substance dossiers, customs trade data on magnesium hydroxide flows, and SEC filings of listed compounders. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, grade, and end user segmentation.
Rate-of-change decomposition separates volume growth into substitution-driven displacement of halogenated alternatives, electrification-content expansion in automotive platforms, and regulatory enforcement intensity across jurisdictions. Segmentation dimensions modeled include product type tier, application thermal exposure profile, grade stability classification, and end user procurement authority concentration. CAGRs derived from fitted growth curves calibrated to historical substitution elasticities and announced capacity expansions. Electric vehicle battery housing thermal requirements and data center hyperscaler construction pipelines served as industry-specific demand anchors.
Inputs from ECHA substance databases and SAMR conformity assessment registries were available through the study window; gaps in real-time magnesium hydroxide spot pricing and unannounced EV platform thermal specifications introduce uncertainty bands. Forecasts reflect assumptions on REACH enforcement timelines, BIS adoption trajectories, and 5G infrastructure deployment cadence. Material deviation in named triggers—regulatory authorization delays, energy rationing severity in Liaoning, or telecom capex cycle turns—warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Corrosion Under Insulation (CUI) and Spray-On Insulation (SOI) Coatings Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
North America Tank Insulation Market
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Phenolic Insulation Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Thin Insulation Market
Insulation Materials
Americas Pipe Insulation Market