
 Global Microporous Insulation Market | 2026-2036
Global Microporous Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microporous Insulation Market Foresight
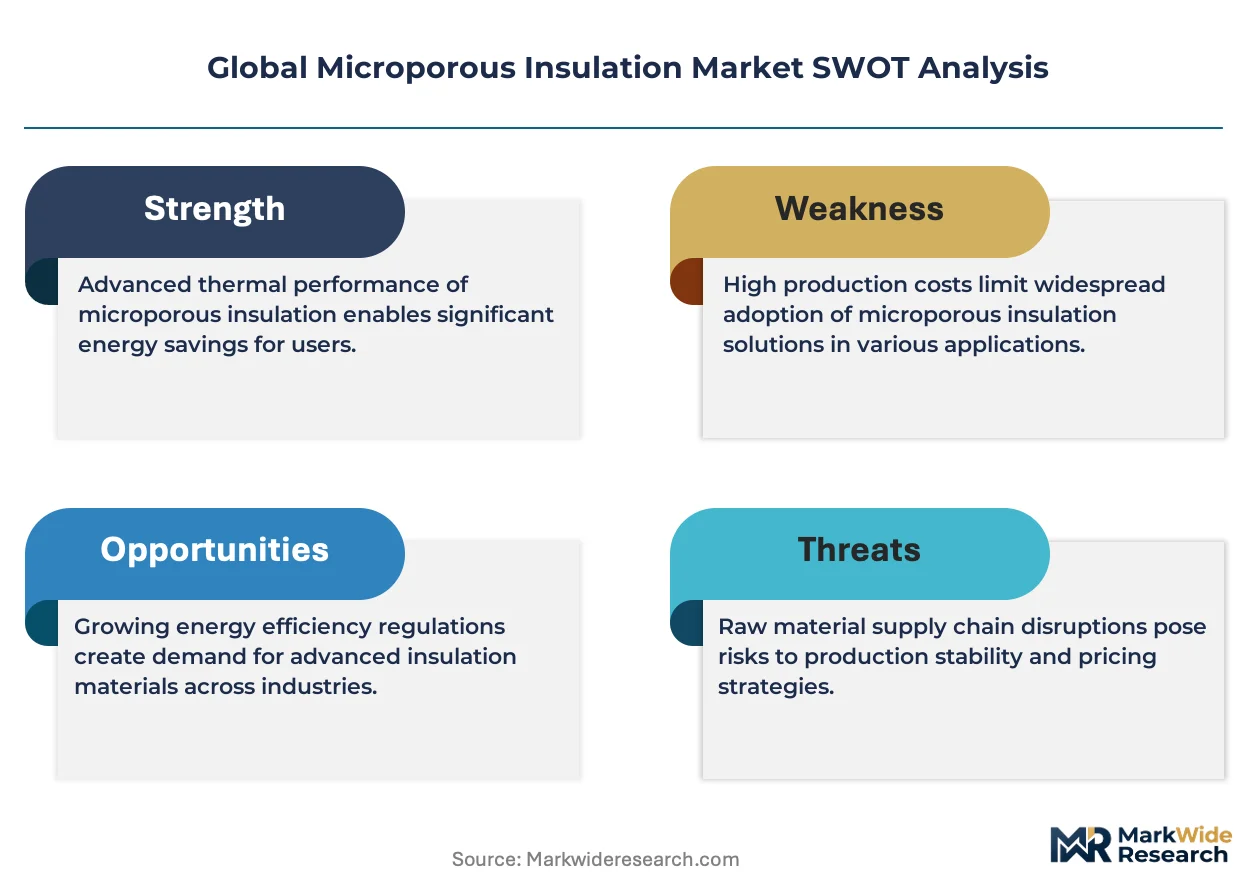
ISO 9001 and AS9100 certification cycles is collapsing the supplier base for aerospace-grade microporous insulation, leaving only qualified manufacturers in contention. Alkegen leverages its vertically integrated silica production to sustain cost advantages across blanket and panel formats. Morgan Advanced Materials anchors European supply through specialized high-temperature boards serving steel and petrochemical clients. NICHIAS Corporation dominates Asian project specifications with proprietary vacuum insulation technology refined for cryogenic LNG terminals.
Microporous insulation comprises inorganic oxide powders—predominantly fumed silica, opacifiers, and reinforcing fibers—compressed into flexible or rigid forms with pore diameters below two micrometers, achieving thermal conductivity values near 0.020 W/m·K at ambient conditions. This architecture delivers superinsulation performance where space constraints and extreme temperatures coexist, such as in industrial furnaces, spacecraft thermal protection systems, and cryogenic pipeline enclosures. Blankets and boards represent the mature volume base, while vacuum insulation panels command premium positioning due to superior thermal resistance per unit thickness. Aerogel-infused variants are gaining fastest in electronics assembly and aerospace engineering end uses where weight reduction overrides material cost.
The EPA enforces maximum achievable control technology standards that mandate thermal efficiency upgrades in American chemical manufacturing and oil & gas processing facilities, directly expanding retrofit demand. REACH and the EU F-Gas Regulation restrict legacy blowing agents and high-GWP materials, redirecting European procurement toward silica-based microporous alternatives that avoid regulated chemistries. China's GB standards and dual carbon goals impose industrial energy intensity targets that favor superinsulation in new power plant construction. Stakeholders must monitor evolving national building codes and process safety regulations to anticipate specification shifts before project design phases lock in material selections.
Market Dynamics
The microporous insulation market is experiencing a supply-side squeeze as aerospace certification requirements intensify and qualified manufacturing capacity fails to keep pace with specification demand from furnace retrofits and spacecraft programs.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on high-GWP blowing agents redirect European industrial procurement toward silica-based microporous alternatives that avoid regulated chemistries entirely.
- Cryogenic LNG infrastructure:Asian terminal expansions specify vacuum insulation panels for pipeline enclosures where space constraints and thermal performance requirements converge.
- Industrial furnace retrofits:EPA maximum achievable control technology standards mandate thermal efficiency upgrades across American chemical manufacturing and oil & gas processing facilities.
Market Restraints
- Fumed silica feedstock volatility:Precursor supply concentrates among limited specialty chemical producers, exposing insulation manufacturers to input cost swings and allocation risk.
- Aerospace-grade certification scarcity:AS9100 and ISO 9001 audit cycles collapse the supplier base for spacecraft thermal protection systems, constraining qualified production capacity.
- Conventional refractory substitution:Established ceramic fiber and mineral wool solutions retain cost advantages in temperature regimes below 800°C where space constraints are absent.
Strategic Opportunities
- Electronics assembly miniaturization:Aerogel-infused microporous formats penetrate semiconductor manufacturing and battery pack thermal management where weight reduction overrides material cost premiums.
- China's dual carbon goals:GB standards impose industrial energy intensity targets that favor superinsulation in new power plant construction and steel sector retrofits.
- Direct-to-fabricator distribution:Bypassing traditional distributor networks allows manufacturers to capture specification influence earlier in project design phases.
Industry Challenges
- Specialized technician scarcity:Installation of vacuum insulation panels and rigid microporous boards demands trained crews familiar with clean handling protocols and compression sealing techniques.
- Legacy system integration friction:Retrofitting microporous barriers into existing furnace linings requires engineered interface solutions that extend project timelines and complicate contractor coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microporous Insulation Market |
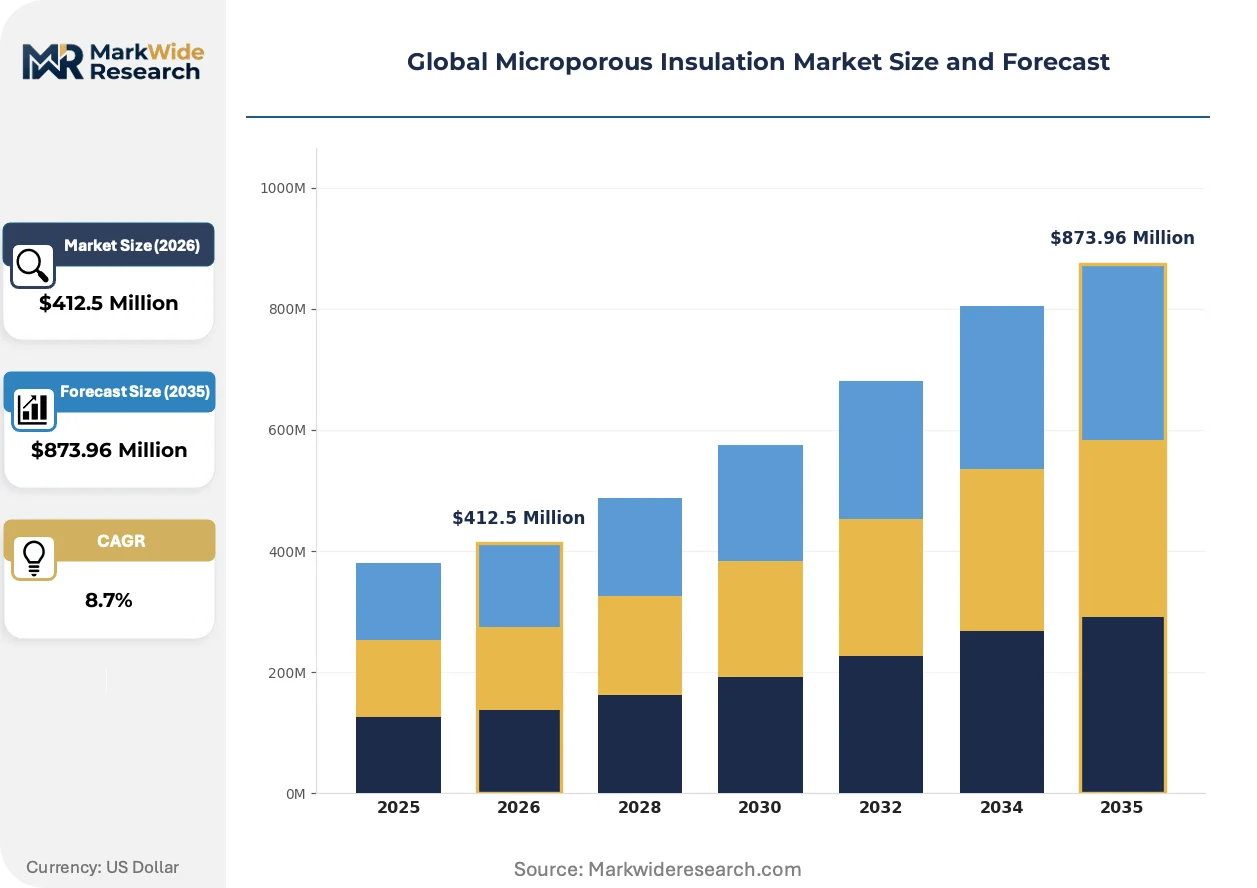
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blankets, Boards, Tubes, Panels, Sheets Technology: Vacuum Insulation, Aerogel, Polymer Composites, Ceramic Fiber, Fiberglass Application: Thermal Protection, Cryogenics, Fireproofing, Soundproofing, Energy Conservation End User: Oil & Gas Processing, Aerospace Engineering, Power Plants, Chemical Manufacturing, Electronics Assembly |
| Companies Covered | Alkegen, TECHNO-PHYSIK Engineering GmbH, Etex Group, Unicorn Insulations Ltd, Promat International NV, Johns Manville, NICHIAS Corporation, Elmelin Ltd, Morgan Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microporous Insulation Market Shifts & Advancements
Material architecture is compressing toward thinner thermal barriers without sacrificing performance, while regulatory chemistry restrictions and buyer consolidation are rewriting specification authority across the value chain.
Aerogel-infused microporous composites are miniaturizing thermal protection systems for aerospace engineering and electronics assembly applications. Satellite manufacturers specify these materials for spacecraft thermal protection where every gram carries launch cost consequences. Smartphone and electric vehicle battery pack designers adopt the same formats to manage heat flux in densely packed assemblies. The technology is miniaturizing insulation footprints from centimeters to millimeters, collapsing the historical trade-off between thermal resistance and spatial allocation.
REACH and the EU F-Gas Regulation are eliminating legacy blowing agents from European industrial insulation specifications. Chemical manufacturers and petrochemical facility operators face compliance deadlines that invalidate existing material approvals. Procurement departments redirect sourcing toward silica-based microporous alternatives that circumvent restricted chemistries entirely. German steel producers and Dutch chemical clusters lead this transition, locking in long-term supply agreements before project design phases finalize.
Specification authority is migrating from general contractors to end-user engineering departments with direct performance accountability. Oil & gas majors and aerospace primes now retain insulation selection authority rather than delegating to construction managers. This compresses distributor influence and rewards manufacturers with technical sales capabilities and application engineering support. The pattern is most visible in United States LNG export terminal projects and European carbon capture facility developments where process guarantees override first-cost considerations.
Global Microporous Insulation Market Segmentation
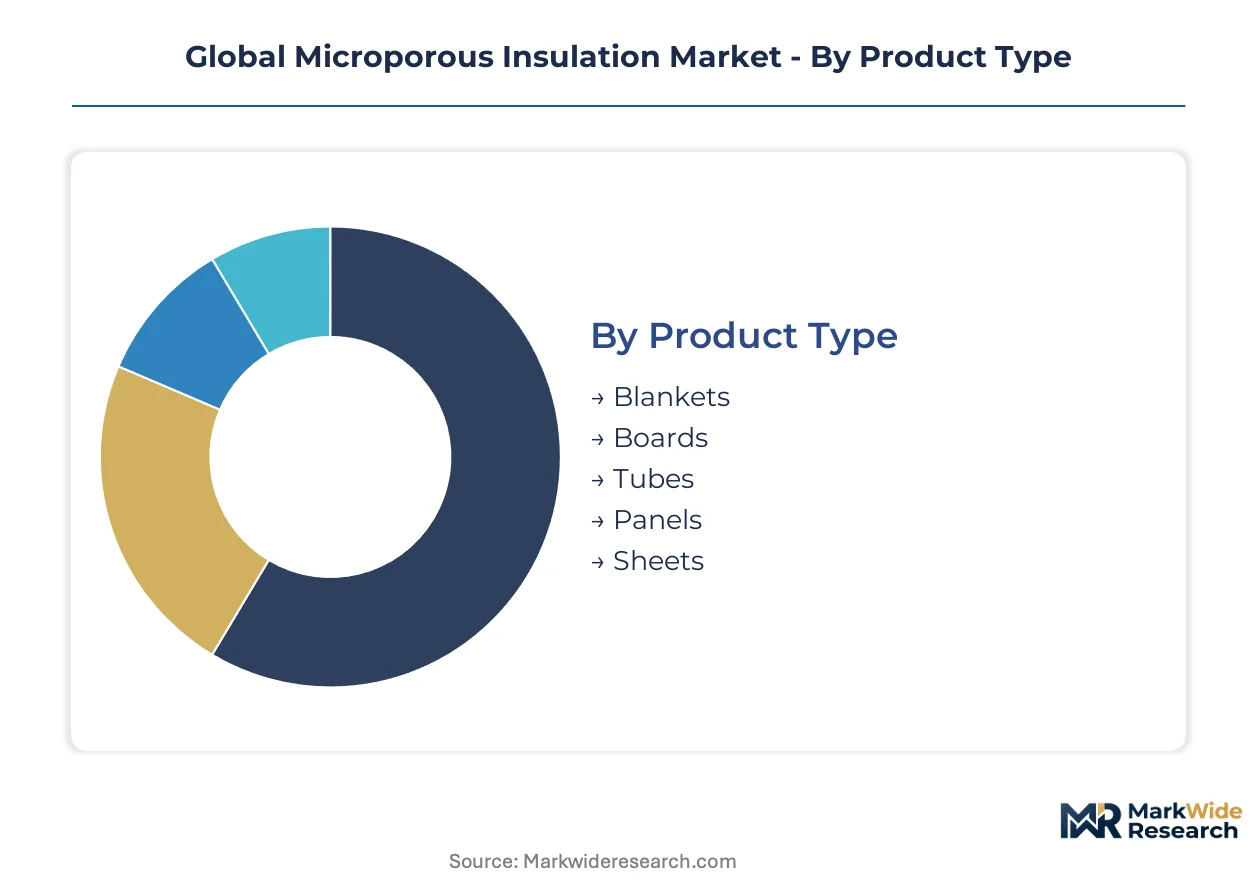
Microporous insulation segments diverge sharply in substitution vulnerability. Ceramic fiber and mineral wool threaten lower-temperature applications, while vacuum and aerogel formats defend premium niches through performance differentiation.
Product Type:
Blankets and boards face the most intense pressure from conventional refractory substitutes in sub-800°C industrial applications where space constraints are absent.
- Blankets:Flexible silica-fiber composites deliver conformable thermal barriers for furnace linings and pipeline wrapping. Demand concentrates in German steel retrofits where EU F-Gas Regulation deadlines invalidate legacy insulation specifications.
- Boards:Rigid compressed formats provide structural thermal protection for petrochemical vessel enclosures. Morgan Advanced Materials anchors European supply through specialized high-temperature boards serving Dutch chemical clusters and Ruhr industrial complexes.
- Tubes:Pre-formed cylindrical shapes reduce installation labor for pipe insulation in cryogenic LNG terminals. Asian terminal expansions specify tube formats for pipeline enclosures where space constraints dominate.
- Panels:Vacuum-insulated configurations achieve the lowest thermal conductivity per unit thickness. NICHIAS Corporation dominates Asian project specifications with proprietary vacuum technology refined for cryogenic applications.
- Sheets:Thin planar formats address electronics thermal management and aerospace weight constraints. Aerogel-infused sheet variants penetrate semiconductor manufacturing where heat flux management overrides material cost premiums.
Blankets retain volume leadership; sheets hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium vacuum and aerogel systems from commodity ceramic fiber alternatives.
- Vacuum Insulation:Evacuated microporous cores eliminate gas conduction, achieving thermal conductivity below 0.005 W/m·K. LNG infrastructure projects in Japan and South Korea specify vacuum panels for cryogenic pipeline enclosures.
- Aerogel:Silica-based gel structures infuse microporous matrices with nanoscale porosity. Satellite manufacturers specify aerogel composites for spacecraft thermal protection where launch cost penalties attach to every gram.
- Polymer Composites:Organic binders reinforce microporous matrices for moderate-temperature applications. Automotive battery pack designers adopt polymer-composite formats for electric vehicle thermal management systems.
- Ceramic Fiber:Alumina-silica blends compete directly with microporous alternatives in furnace applications below 1000°C. Established ceramic fiber solutions retain cost advantages where space constraints are absent.
- Fiberglass:Glass wool derivatives occupy the economy tier of industrial insulation specifications. Fiberglass substitutes threaten microporous penetration in American chemical manufacturing retrofits where EPA MACT standards drive thermal efficiency upgrades.
Vacuum insulation commands the premium tier; aerogel is climbing the fastest.
Application:
Application maturity varies by regulatory enforcement intensity and end-use performance requirements.
- Thermal Protection:High-temperature barriers for industrial furnaces, spacecraft, and process equipment. Aerospace engineering programs in the United States and Germany expand procurement of high-performance thermal barriers for re-entry vehicle heat shields.
- Cryogenics:Ultra-low-temperature insulation for LNG storage, transport, and regasification. Asian terminal expansions specify vacuum insulation panels where space constraints and thermal performance requirements converge.
- Fireproofing:Passive fire protection for structural steel and industrial enclosures. Fireproofing applications face substitution from intumescent coatings in commercial building codes.
- Soundproofing:Acoustic attenuation in industrial environments and transportation equipment. Soundproofing represents a secondary benefit rather than primary specification driver.
- Energy Conservation:Industrial process efficiency and building envelope thermal performance. China's GB standards impose industrial energy intensity targets that favor superinsulation in new power plant construction.
Thermal protection retains volume leadership; cryogenics holds the steepest expansion curve.
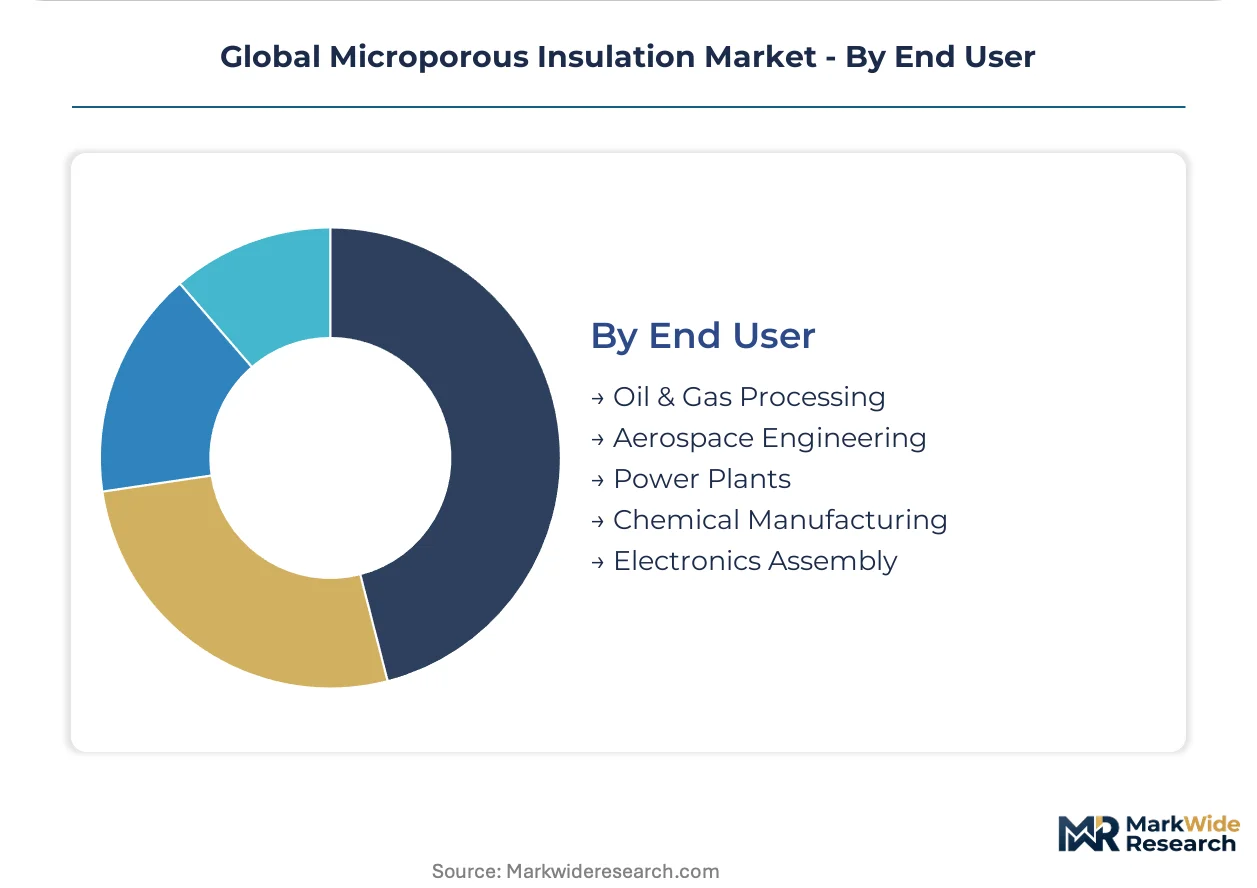
End User:
Customer concentration in oil & gas and aerospace creates specification authority migration toward engineering departments with direct performance accountability.
- Oil & Gas Processing:Refinery and petrochemical facility retrofits and new construction. EPA maximum achievable control technology standards mandate thermal efficiency upgrades across American oil & gas processing facilities.
- Aerospace Engineering:Spacecraft thermal protection, hypersonic vehicle insulation, and satellite systems. AS9100 and ISO 9001 certification cycles collapse the supplier base for aerospace-grade microporous insulation.
- Power Plants:Boiler insulation, turbine enclosures, and flue gas treatment systems. China's dual carbon goals impose industrial energy intensity targets that favor superinsulation in new power plant construction.
- Chemical Manufacturing:Reactor vessel insulation, process piping, and storage tank thermal protection. REACH and EU F-Gas Regulation redirect European chemical manufacturing procurement toward silica-based microporous alternatives.
- Electronics Assembly:Semiconductor manufacturing equipment, battery pack thermal management, and smartphone components. Electronics assembly miniaturization drives aerogel-infused microporous penetration where weight reduction overrides material cost premiums.
Oil & gas processing retains volume leadership; electronics assembly holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation deadlines and EPA MACT enforcement are redrawing procurement geography for microporous insulation, concentrating specification authority in jurisdictions with binding emissions compliance timelines.
United States
EPA maximum achievable control technology standards mandate thermal efficiency upgrades across chemical manufacturing and oil & gas processing facilities. Gulf Coast petrochemical clusters in Texas and Louisiana drive blanket and board procurement for furnace retrofits. Houston-area engineering firms retain direct specification authority for LNG export terminal insulation packages.
Germany
Ruhr industrial complexes and Dutch chemical clusters anchor European demand for high-temperature boards. REACH compliance deadlines invalidate legacy insulation specifications, redirecting procurement toward silica-based microporous alternatives. Bavarian aerospace engineering programs expand procurement of AS9100-certified thermal barriers for spacecraft applications.
China
GB standards and dual carbon goals impose industrial energy intensity targets favoring superinsulation in new power plant construction. Yangtze River Delta steel producers and Shandong Peninsula chemical manufacturers specify vacuum insulation panels for furnace retrofits. State-owned energy groups consolidate procurement authority for ultra-supercritical boiler projects.
Japan
METI efficiency standards and cryogenic infrastructure investments drive vacuum insulation panel adoption. Osaka-Kobe industrial corridor LNG terminals specify NICHIAS Corporation technology for pipeline enclosures where space constraints dominate. Satellite manufacturers in Tokyo and Nagoya procure aerogel-infused formats for thermal protection systems.
South Korea
Ulsan petrochemical complexes and Incheon LNG import facilities specify vacuum insulation for cryogenic applications. Government-backed hydrogen economy initiatives create demand for superinsulation in liquefaction and storage infrastructure. Busan shipyards integrate microporous barriers into LNG carrier cargo containment systems.
Global Microporous Insulation Market Competitive Landscape
Player mix skews toward integrated material specialists and application-engineering fabricators competing on certification depth rather than commodity scale. The supplier base compresses as aerospace-grade AS9100 and ISO 9001 audit cycles eliminate unqualified manufacturers. Three archetypes dominate: vertically integrated silica producers with captive feedstock control, specialized high-temperature board fabricators serving European industrial clusters, and vacuum insulation technology holders with cryogenic project expertise. Competitive moves concentrate on backward integration into fumed silica precursors and direct-to-fabricator distribution bypassing traditional distributor networks.
Among integrated material specialists, Alkegen exemplifies the feedstock-anchored archetype through in-house silica production sustaining cost advantages across blanket and panel formats. Morgan Advanced Materials occupies a position within the European high-temperature board tier, anchoring supply to German steel and Dutch petrochemical clients. NICHIAS Corporation represents the vacuum insulation technology specialist archetype, with Japanese origin evident in its cryogenic LNG terminal project dominance. These three illustrate how competitive positioning stratifies across feedstock control, regional engineering depth, and proprietary vacuum technology.
| Leading Market Players |
|---|
| Alkegen |
| TECHNO-PHYSIK Engineering GmbH |
| Etex Group |
| Unicorn Insulations Ltd |
| Promat International NV |
| Johns Manville |
| NICHIAS Corporation |
| Elmelin Ltd |
| Morgan Advanced Materials |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German steel producers and fumed silica suppliers lock in feedstock access while providing price visibility against volatile spot markets. These structures concentrate procurement power among AS9100-certified manufacturers who can guarantee volume continuity to aerospace primes and LNG terminal developers.
Pricing Analysis
Certification level creates the primary spread between aerospace-grade AS9100 panels and commodity furnace blankets. Project-based contracting dominates, with price differentiation hinging on ISO 9001 audit depth and after-sales technical support bundling. Cost compression in standard-grade formats is intensifying as ceramic fiber substitutes erode market share below 800°C applications. Chemical manufacturing buyers exhibit highest price sensitivity, while spacecraft thermal protection programs prioritize performance guarantees over unit economics.
Supply Chain Analysis
Inventory cycles for vacuum insulation panels extend 16-20 weeks due to clean-handling protocols and compression sealing requirements. Feedstock supply concentrates in Germany, the United States, and Japan, where specialty chemical producers control fumed silica precursor output. Manufacturing draws from opacifier imports and reinforcing fiber feedstocks, exposing producers to tariff exposure on Chinese-origin raw materials. Distribution runs through direct-to-fabricator channels that bypass traditional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microporous insulation market sits in early-cycle expansion as EU F-Gas Regulation deadlines force specification switches away from legacy blowing agents. Penetration into electronics assembly and battery thermal management remains underdeveloped relative to industrial furnace applications.
For Market Incumbents: Fortify AS9100 certification depth to defend aerospace supply positions against emerging aerogel specialists. Backward integration into fumed silica precursors anchors cost position against feedstock volatility. Expand technical sales teams in Houston and Rotterdam to capture specification authority before project design phases finalize.
For New Entrants and Emerging Players: Differentiate on aerogel-infused sheet formats for semiconductor and electric vehicle battery pack applications where weight reduction commands premium pricing. Target South Korean hydrogen liquefaction infrastructure as the most penetrable cryogenic segment. Pursue direct engagement with Tokyo and Nagoya satellite manufacturers to bypass established distributor relationships.
For Investors and Strategic Acquirers: Capital is best deployed toward vacuum insulation technology holders with demonstrated cryogenic LNG terminal execution. The five-to-ten year viability window favors manufacturers with proprietary compression sealing IP and trained installation network control. Monitor Japanese METI efficiency standard revisions as the signal for accelerated Asian infrastructure procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fumed Silica | Captive feedstock supply insulates Alkegen and Morgan from specialty chemical allocation risk. |
| AS9100 Certification Investment | Aerospace-grade audit cycles collapse supplier base, concentrating margin with qualified manufacturers. |
| Direct-to-Fabricator Distribution | Bypassing distributor networks captures specification influence earlier in Houston and Rotterdam project phases. |
| Aerogel Composite R&D Partnership | Collaboration with satellite manufacturers accelerates penetration of millimeter-thin thermal protection formats. |
| Cryogenic Installation Training Programs | Specialized crew certification addresses technician scarcity constraining vacuum panel deployment in Asian LNG terminals. |
Research Methodology
A standing panel of plant engineers at German steel complexes, procurement leads at Gulf Coast petrochemical facilities, aerospace thermal protection specialists, and LNG terminal EPC contractors provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against customs data, SEC filings from listed insulation manufacturers, ECHA REACH registration databases, and EPA MACT compliance records. Bottom-up volume modeling triangulated against top-down industry association estimates.
Consistency checks validated segment-level outputs against external benchmarks including hyperscaler capex disclosures for data center cooling applications and national energy efficiency program targets. The analytical framework modeled product type, technology tier, application thermal regime, and end-user industry concentration across the projection horizon. CAGRs were derived from regression analysis of historical procurement patterns and regulatory deadline impacts, incorporating fumed silica price indices and aerospace program award timelines as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas enforcement or accelerated Chinese dual carbon implementation would require recalibration. Forecasts reflect documented assumptions regarding certification cycle durations and feedstock supply continuity. Specific risks that could revise projections include ceramic fiber substitution acceleration below 800°C and aerospace program budget reprioritization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Extruded Polyolefin Foam Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Phase Change Materials Market
Insulation Materials
Expanded Perlite Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Global High Temperature Insulation Materials Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Americas Pipe Insulation Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Beryllium Oxide Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Passive Fire Protection Materials Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market