
 Mineral Wool Board Insulation Market | 2026-2036
Mineral Wool Board Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Wool Board Insulation Market Outlook
Commercial building owners and industrial facility operators is reorganizing procurement priorities toward fire-resistant thermal envelopes. ROCKWOOL International A/S dominates melt-spinning technology for high-temperature board grades across European infrastructure projects. Owens Corning Corporation leverages its glass wool heritage to compete in hybrid mineral wool systems for North American commercial retrofits. Johns Manville Corporation anchors its position through in-house production of binder chemistries that meet stringent smoke-toxicity protocols.
Mineral wool board insulation consists of fibers spun from molten rock or slag, bonded with phenolic or bio-based resins, and formed into rigid panels with densities typically ranging from 80 to 200 kg/m³ for load-bearing and acoustic applications. Its primary purpose is to provide non-combustible thermal barriers in building envelopes and industrial equipment where fire safety ratings are mandatory. Board-form products command premium positioning in commercial and industrial applications where dimensional stability under compression and direct mechanical fastening are required. Rigid-form mineral wool captures the deepest margin pools in specification-driven projects, while semi-rigid boards serve retrofit contractors seeking faster installation cycles in residential and agricultural buildings.
The EU Green Deal and F-Gas Regulation are tightening embodied-carbon thresholds for building materials, pushing specifiers toward mineral wool with recycled slag content and lower-process-energy credentials. REACH compliance and CE marking under the Construction Products Regulation govern market access for imported board products, creating compliance barriers for non-European suppliers. ECHA evaluations of formaldehyde-based binders are forcing reformulation investments across the supply base. Stakeholders must monitor evolving carbon-border adjustment mechanisms and national building-code harmonization to anticipate specification shifts before tender cycles close.
Market Dynamics
EU Green Deal energy performance mandates are forcing specification upgrades from legacy fiberglass to fire-rated mineral wool systems across commercial building envelopes, compressing tender cycles and concentrating procurement authority with sustainability-certified contractors.
Growth Catalysts
- Passive house certification:Nordic building codes now mandate ultra-low thermal bridging, driving premium mineral wool board specification in Denmark, Sweden, and Finland where density-graded products dominate envelope design.
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon restrictions are eliminating foam insulation alternatives in cold-chain and industrial applications, redirecting specification toward stone wool's non-combustible thermal barrier properties.
- Slag recycling infrastructure:Steel industry byproduct supply chains in Germany and France now deliver consistent blast furnace slag feedstock, lowering embodied-carbon credentials for domestic board manufacturers competing on EPD transparency.
Market Restraints
- Phenolic resin cost volatility:Formaldehyde and phenol feedstock prices fluctuate with crude oil indices, compressing margin stability for binder-dependent rigid board grades during energy price spikes.
- ECHA binder evaluations:REACH assessments of formaldehyde-based chemistries are forcing multimillion-euro reformulation investments, creating compliance barriers for mid-tier suppliers without captive R&D infrastructure.
- Aerogel blanket substitution:Silica aerogel products are capturing specification in ultra-thin envelope applications where space constraints outweigh mineral wool's cost advantage, particularly in historic building retrofits.
Strategic Opportunities
- Carbon-border adjustment positioning:CBAM implementation is disadvantaging imported insulation with high process-energy footprints, creating procurement preference for EU-manufactured slag-wool boards with verified low-carbon production.
- Industrial heat-recovery integration:Data center and district heating projects in the Netherlands require combined fire-thermal-acoustic performance, opening specification for multi-functional board systems beyond traditional envelope use.
- CE marking harmonization:Construction Products Regulation streamlining is reducing national technical approval fragmentation, enabling standardized board portfolios to scale across Germany, France, and Benelux without redundant testing.
Industry Challenges
- Smoke-toxicity certification timelines:EN 13501-1 Euroclass A1 testing protocols require extended laboratory scheduling, delaying product launches and compressing revenue recognition into subsequent tender cycles.
- Mechanical fastening skill gaps:Installation of high-density load-bearing boards demands certified contractor training that outpaces workforce development programs in Poland and Romania, creating execution risk on fast-track commercial retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Wool Board Insulation Market |
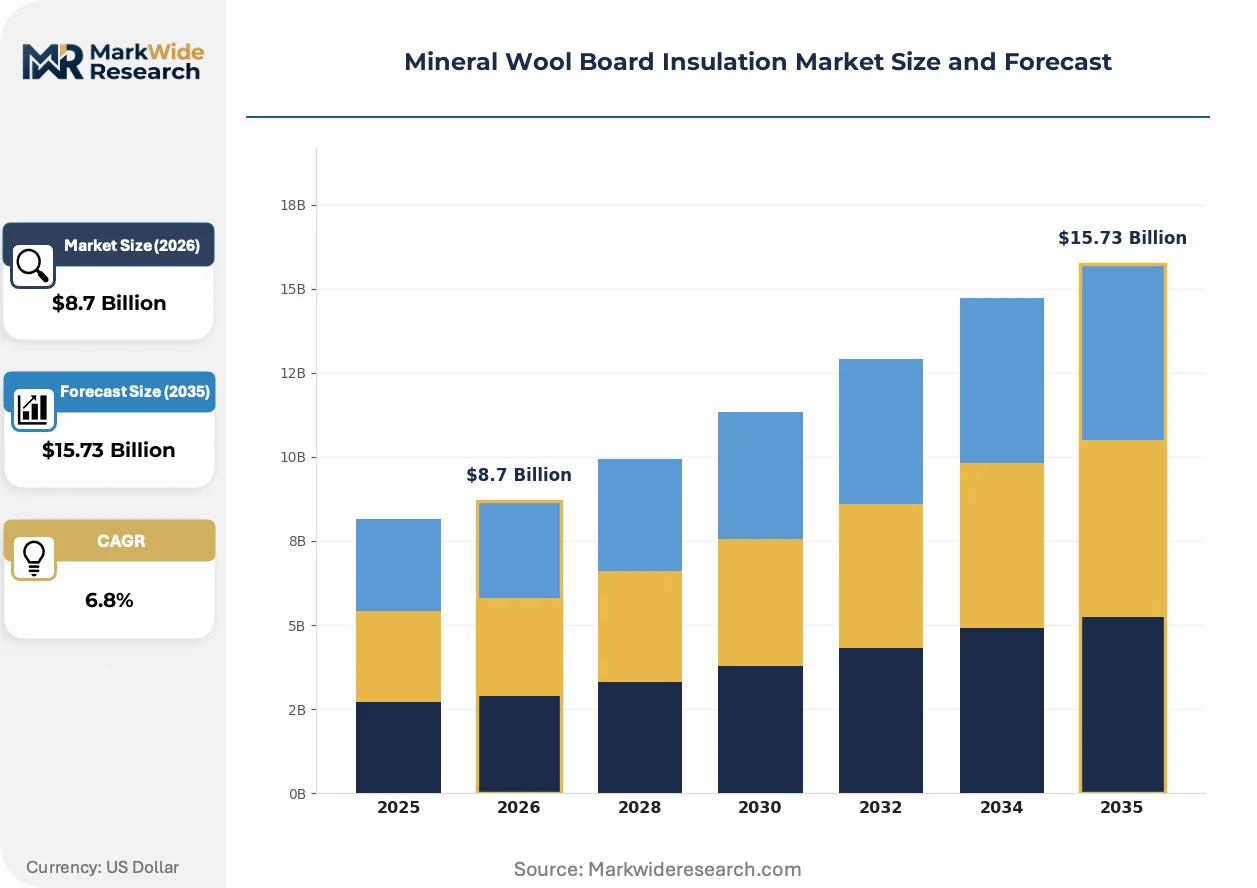
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batt, Board, Roll, Loose Fill Application: Residential, Commercial, Industrial, Agricultural Form: Rigid, Semi-Rigid, Flexible, Pre-Compressed End User: Contractors, Builders, DIY Consumers, Insulation Manufacturers |
| Companies Covered | Knauf Insulation GmbH, Kingspan Group plc, ROCKWOOL International A/S, URSA Insulation, S.L., Paroc Group Oy Ab, Owens Corning Corporation, Johns Manville Corporation, Fletcher Building Limited, Compagnie de Saint-Gobain S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Wool Board Insulation Market Strategic Shifts
Bio-based binder chemistry and digital specification tools are compressing traditional competitive advantages rooted in legacy manufacturing scale, while embodied-carbon transparency becomes the primary tender evaluation criterion.
Basalt fiber reinforcement is miniaturizing the density gradient required for structural mineral wool boards, enabling thinner panels to achieve equivalent compressive strength. Passive house developers in Austria and Switzerland are specifying these reduced-thickness systems to maximize net internal area. The technology is miniaturizing the envelope thickness-to-performance ratio that previously favored thicker, lower-density glass wool alternatives.
EU Green Deal carbon performance benchmarks are mandating Environmental Product Declarations for all publicly procured building materials. Member state implementation varies, with France's RE2020 regulation already enforcing embodied-carbon caps that disqualify high-process-energy insulation. Commercial retrofit tenders in Paris and Lyon now require third-party-verified EPDs as mandatory bid documents, filtering supplier pools.
Contractor-direct specification is consolidating purchasing authority away from merchant distributors in the German commercial building sector. Large envelope contractors in Munich and Hamburg now maintain approved manufacturer lists based on joint EPD development and logistics integration, bypassing traditional wholesale channels. This concentration is most visible in healthcare and education verticals where framework agreements lock in multi-project supply.
Mineral Wool Board Insulation Market Segmentation
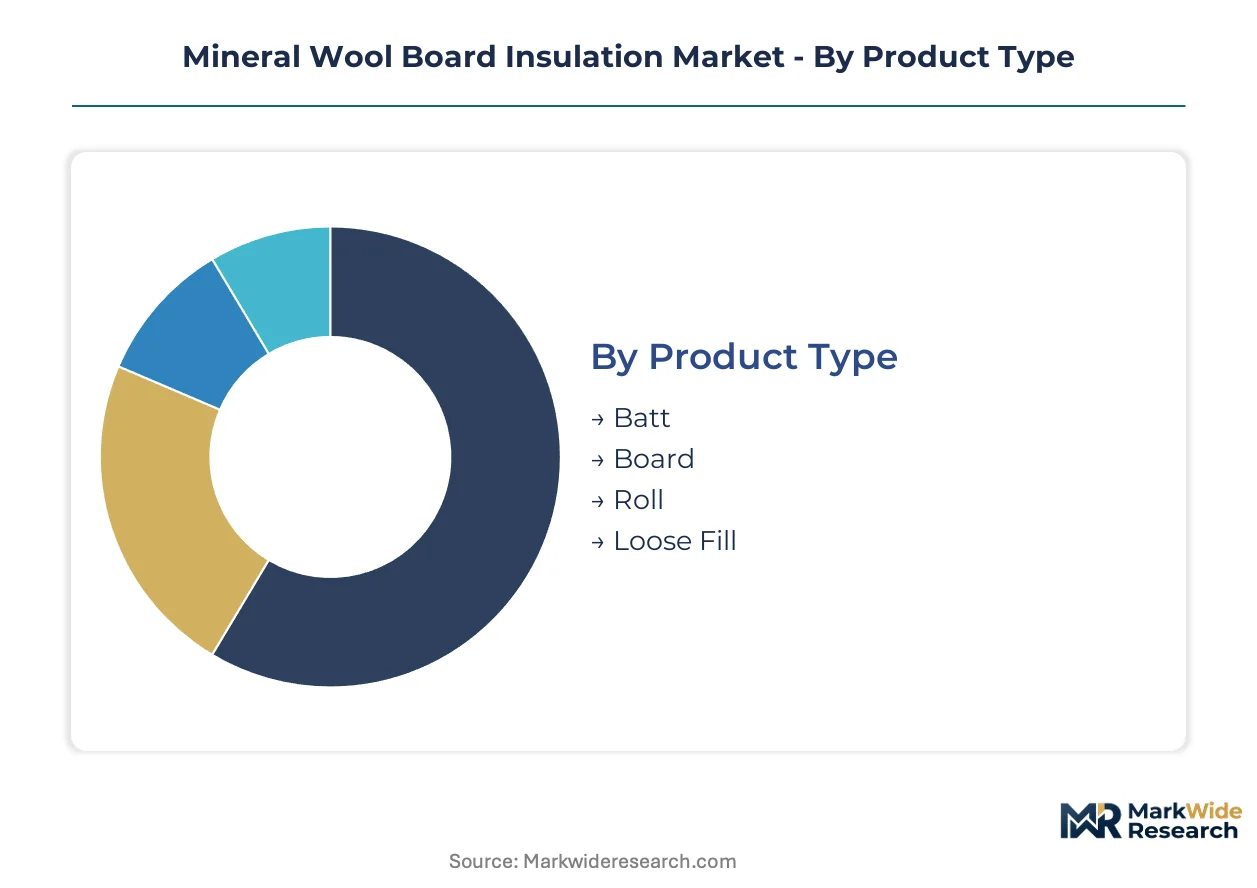
Segmentation in mineral wool board insulation reveals how specification authority, installation method, and regulatory compliance reshape procurement patterns. Board-form products command premium positioning where dimensional stability and fire ratings are mandatory, while other product types serve distinct cost-performance trade-offs across building envelopes.
Product Type:
Margin pools concentrate in rigid board formats where specification-driven projects reward compressive strength and Euroclass A1 certification.
- Board:Rigid panels spun from molten rock or slag with densities of 80-200 kg/m³ deliver non-combustible thermal barriers for commercial envelopes. Passive house certification in Denmark and Sweden drives premium specification where direct mechanical fastening and load-bearing performance are required.
- Batt:Flexible, semi-rigid slabs designed for friction-fit installation between timber or metal studs dominate residential wall cavities. German and French commercial retrofits favor batt formats for faster installation cycles where fire-rated cavity barriers are mandated under EU Green Deal energy performance standards.
- Roll:Continuous blanket formats suit attic and loft applications requiring rapid coverage of irregular joist spacing.
- Loose Fill:Blown-in granular material addresses inaccessible cavities and top-up insulation in existing residential buildings.
The dominant share belongs to Board, while Batt is closing the gap fastest.
Application:
Commercial building envelopes generate the deepest margin pools where fire-thermal-acoustic multi-performance requirements justify premium mineral wool specification.
- Commercial:Office, healthcare, and education verticals in Germany and France specify fire-rated board systems under tightening EU Green Deal energy performance mandates. Framework agreements with large envelope contractors in Munich and Hamburg now lock in multi-project supply based on joint EPD development.
- Industrial:Data centers and district heating projects in the Netherlands demand combined fire-thermal-acoustic performance for heat-recovery integration. F-Gas Regulation phase-down redirects specification from foam alternatives toward stone wool's non-combustible properties in cold-chain applications.
- Residential:Single-family and multi-family construction favors batt and roll formats for cost-sensitive thermal envelope upgrades.
- Agricultural:Livestock housing and crop storage facilities prioritize moisture-resistant semi-rigid boards for condensation control.
Commercial captures the dominant share, with Industrial climbing the fastest on data center and district heating project pipelines.
Form:
Density gradient and compressive strength separate pricing tiers, with rigid formats capturing specification-driven premiums and semi-rigid formats serving retrofit volume.
- Rigid:High-density boards with structural load-bearing capacity meet EN 13501-1 Euroclass A1 requirements for commercial facades and industrial equipment. Basalt fiber reinforcement is miniaturizing density requirements, enabling thinner panels to achieve equivalent compressive strength for Austrian and Swiss passive house developers maximizing net internal area.
- Semi-Rigid:Medium-density formats balance dimensional stability with cutability for faster contractor installation in residential and agricultural retrofits. Polish and Romanian contractors favor these formats where certified installation training for high-density boards remains scarce.
- Flexible:Low-density blankets conform to irregular substrates in historic building renovations where space constraints limit rigid board use.
- Pre-Compressed:Vacuum-packed boards reduce transport volume and expand on-site for remote project logistics.
Rigid holds the dominant share, while Semi-Rigid is gaining share fastest on retrofit contractor preference.
End User:
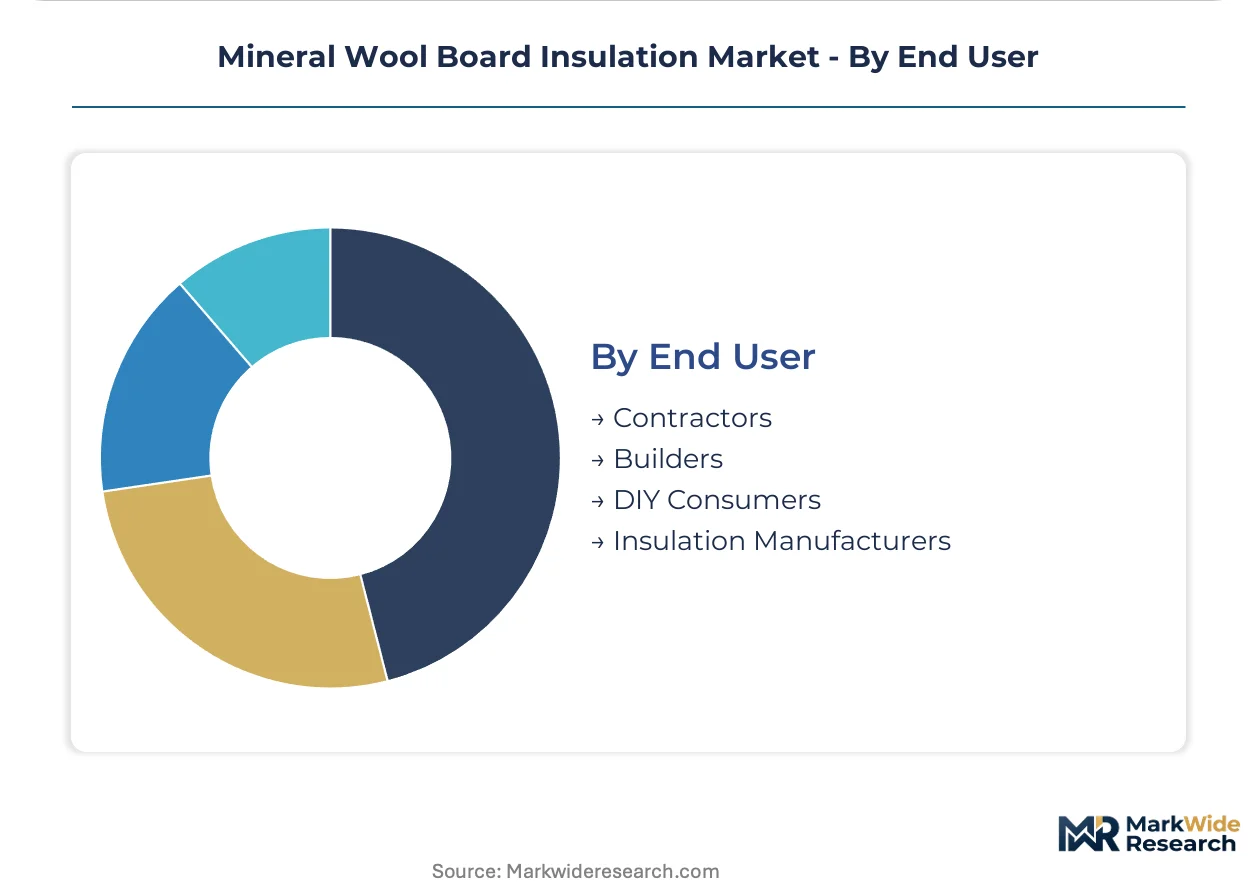
Procurement authority is consolidating with sustainability-certified contractors who maintain approved manufacturer lists based on EPD transparency and logistics integration.
- Contractors:Large envelope contractors in Germany now bypass traditional wholesale channels through direct framework agreements. Healthcare and education verticals concentrate purchasing authority with contractors who specify based on verified embodied-carbon credentials under France's RE2020 regulation.
- Builders:Regional construction firms serving residential and light commercial projects select mineral wool based on cost-per-R-value and local availability.
- DIY Consumers:Home improvement retailers stock batt and roll formats for attic upgrades and minor renovation projects.
- Insulation Manufacturers:Downstream producers source mineral wool feedstock for composite panel lamination and specialized system integration.
Contractors command the dominant share, with Builders showing the steepest expansion trajectory on multi-family residential pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German mineral wool board manufacturers export premium fire-rated systems across Benelux and into Scandinavian retrofit markets, with slag-recycling infrastructure anchoring supply-side competitiveness against imports from Eastern European production bases.
Germany
Commercial building retrofit programs in Munich and Hamburg concentrate procurement authority with sustainability-certified envelope contractors. The EU Green Deal's energy performance mandates compress tender cycles, forcing specification upgrades from legacy fiberglass to mineral wool systems with verified Environmental Product Declarations. Blast furnace slag feedstock from Ruhr steel operations lowers embodied-carbon credentials for domestic board manufacturers competing on EPD transparency.
France
Healthcare and education verticals in Paris and Lyon now require third-party-verified EPDs as mandatory bid documents under RE2020 regulation. The ECHA evaluation of formaldehyde-based binders is forcing reformulation investments across the supply base, creating compliance barriers for mid-tier suppliers without captive R&D infrastructure. Large envelope contractors maintain approved manufacturer lists based on joint EPD development and logistics integration.
Sweden
Passive house certification mandates ultra-low thermal bridging, driving premium density-graded mineral wool board specification across envelope design. Nordic building codes concentrate demand in Stockholm and Malmö construction clusters where fire-thermal-acoustic multi-performance requirements justify premium positioning. Basalt fiber reinforcement enables thinner panels to achieve equivalent compressive strength for developers maximizing net internal area.
Netherlands
Data center and district heating projects in Amsterdam and Rotterdam require combined fire-thermal-acoustic performance for heat-recovery integration. The F-Gas Regulation phase-down eliminates foam insulation alternatives in cold-chain applications, redirecting specification toward stone wool's non-combustible thermal barrier properties. Contractor-direct specification is consolidating purchasing authority away from merchant distributors.
Poland
Fast-track commercial retrofits in Warsaw and Kraków face execution risk from mechanical fastening skill gaps for high-density load-bearing boards. CE marking harmonization under the Construction Products Regulation is reducing national technical approval fragmentation, enabling standardized board portfolios to scale across the market. Semi-rigid formats gain preference where certified installation training for high-density boards remains scarce.
Mineral Wool Board Insulation Market Competitive Environment
Player mix skews toward vertically integrated European specialists with captive slag supply and in-house binder chemistry capabilities. The competitive structure concentrates around three archetypes: Nordic stone wool specialists leveraging melt-spinning technology for high-temperature grades, North American glass wool heritage players competing in hybrid systems, and diversified building materials conglomerates with multi-insulation portfolios. Capacity expansion and strategic partnerships dominate competitive moves, with firms securing long-term slag supply agreements and joint EPD development with major envelope contractors.
Within the Nordic specialist tier, ROCKWOOL International A/S and Paroc Group Oy Ab represent archetypal positions anchored in melt-spinning expertise for infrastructure-grade board systems. Owens Corning Corporation exemplifies the glass wool heritage model, while Johns Manville Corporation occupies a position defined by in-house binder chemistry capabilities. Knauf Insulation GmbH and Kingspan Group plc sit within the diversified building materials conglomerate archetype, leveraging multi-product portfolios and distribution scale.
| Leading Market Players |
|---|
| Knauf Insulation GmbH |
| Kingspan Group plc |
| ROCKWOOL International A/S |
| URSA Insulation, S.L. |
| Paroc Group Oy Ab |
| Owens Corning Corporation |
| Johns Manville Corporation |
| Fletcher Building Limited |
| Compagnie de Saint-Gobain S.A. |
| Others |
Value Chain & Pricing Dynamics
Long-term slag offtake contracts with Ruhr steel mills lock in feedstock access and price visibility for German board manufacturers competing on EPD transparency under EU Green Deal mandates. These arrangements insulate domestic producers from phenolic resin volatility while compressing margin pools for importers exposed to carbon-border adjustment penalties.
Pricing Analysis
Next-generation basalt-reinforced boards command premium positioning against legacy glass wool and standard-density stone wool alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects Euroclass A1 certification grade and volume scale. Cost compression in economy-grade batt formats is intensifying because phenolic resin feedstock tracks crude oil indices. Residential retrofit contractors exhibit highest price sensitivity, while passive house developers in Denmark and Sweden prioritize performance over unit cost.
Supply Chain Analysis
Blast furnace slag availability from German and French steel production anchors raw material security for domestic board manufacturers. Supply chains draw from molten rock quarries in Scandinavia, phenolic resin production in Belgium and the Netherlands, and bio-based binder R&D clusters in Austria. Single-source vulnerability concentrates in formaldehyde feedstock channels facing ECHA evaluation disruption. Distribution runs through contractor-direct framework agreements that bypass traditional merchant wholesale in Munich and Hamburg healthcare verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mineral wool board specification is shifting toward platform-economics logic where EPD interoperability and contractor-approved manufacturer lists create winner-take-most dynamics. This ecosystem consolidation rewards early movers who embed carbon-accounting tools into joint development programs with large envelope contractors.
For Market Incumbents:Consolidate position through captive slag supply agreements with steel producers in the Ruhr and Lorraine basins, insulating margin pools from carbon-border adjustment exposure. Deepen backward integration into bio-based binder chemistry ahead of ECHA formaldehyde restrictions. Lock in multi-project framework agreements with Munich and Hamburg envelope contractors before CE marking harmonization opens specification to standardized imports.
For New Entrants and Emerging Players:Differentiate on embodied-carbon transparency by securing third-party EPD verification for slag-wool boards with recycled content above competitor baselines. Target Polish and Romanian commercial retrofit contractors where certified installation training for high-density boards remains scarce and semi-rigid formats dominate. Pursue go-to-market partnerships with national distributors lacking direct contractor relationships in Warsaw and Kraków fast-track projects.
For Investors and Strategic Acquirers:Mid-tier slag-wool specialists with captive steel-industry feedstock contracts and in-house binder R&D capabilities represent priority acquisition targets. Long-term viability hinges on positioning ahead of EU Green Deal procurement mandates that filter supplier pools by verified EPD compliance. Watch for inflection when France's RE2020 embodied-carbon caps expand to additional member states, compressing tender cycles for non-compliant imports.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint EPD Development | Partnerships with Munich envelope contractors lock in multi-project supply under EU Green Deal mandates. |
| Bio-Based Binder Reformulation | Investment ahead of ECHA formaldehyde evaluations creates compliance moat against mid-tier competitors. |
| Slag Supply Agreement | Long-term offtake with Ruhr steel mills secures low-carbon feedstock credentials for CBAM positioning. |
| Contractor Certification Program | Training networks in Poland and Romania address skill gaps for high-density board installation. |
| Basalt Fiber Reinforcement Scale-Up | Thinner panel technology captures passive house specification in Austria and Switzerland. |
Study Parameters
Cross-validation between primary interviews with envelope contractors and secondary analysis of CE marking databases anchors the qualitative findings in this study. Plant managers at German and French board manufacturers, procurement leads at Dutch data center developers, technical R&D directors at binder chemistry suppliers, and sustainability officers at steel industry slag providers contributed operational perspective. Secondary sources include customs and trade data for mineral wool imports, ECHA substance evaluation records, Construction Products Regulation harmonization documents, and national building code amendments across Germany, France, Sweden, the Netherlands, and Poland. Bottom-up volume estimates triangulate against top-down market sizing from production capacity disclosures.
Sensitivity analysis across density grade, application vertical, and regional regulatory cluster shapes the analytical framework over the projection horizon. Segmentation dimensions modeled include product format, compressive strength tier, end-use industry, and contractor certification status. CAGRs derive from trend extrapolation of specification shifts and capacity expansion pipelines. Industry-specific forecast inputs encompass blast furnace slag supply forecasts from European steel production and F-Gas Regulation phase-down timelines redirecting cold-chain insulation specification.
The analysis sits within stated boundaries; outcomes outside EU Green Deal implementation pace or ECHA binder evaluation timelines would require recalibration. Forecasts reflect assumptions about CE marking harmonization progress and carbon-border adjustment enforcement scope. Practitioners should keep alternative scenarios live as national building-code adoption rates and slag recycling infrastructure investment levels evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Microporous Insulation Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
Fire Retardant Flexible Cable Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
North America Extruded Polystyrene (XPS) Insulation Material Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Flame-Retardant Foams and Insulation Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
US Industrial Insulation Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Moistureproof Glass Wool Market