
 Fireproofing Materials Market | 2026-2036
Fireproofing Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Fireproofing Materials Market Analysis
Multi-source procurement of cementitious binders and intumescent chemistries is shifting toward vertically integrated supply among top-tier fireproofing formulators. Sika leverages its construction chemicals platform to bundle passive fire protection with waterproofing and structural repair systems. Isolatek International sustains dominance in spray-applied cementitious fireproofing for steel structures across North American commercial and infrastructure projects. BASF competes through backward integration into acrylic and epoxy resin feedstocks that underpin intumescent coating performance.
Fireproofing materials encompass coatings, boards, sprays, and wraps engineered to insulate structural steel, concrete, and timber from thermal degradation during fire events, typically rated by fire-resistance duration measured in hours under standardized furnace testing. Cementitious materials occupy the largest volume share due to low material cost and established application protocols in commercial buildings and industrial facilities, though intumescent coatings are gaining specification share where architectural exposure of steel members demands thinner, lighter protection. Passive fire protection technology leads the technology dimension because it requires no activation energy and integrates directly into building envelopes, while fire-resistant boards command premium positioning in retrofit and modular construction where field application constraints limit spray or trowel methods.
Fire safety engineers and building code officials in the United States reference NFPA 251 and UL 263 test standards enforced by local authorities having jurisdiction, while the European Union's Construction Products Regulation mandates CE marking under harmonized EN 13381 standards for structural fire protection. India's BIS certification and China's GB 14907 standard for fire-retardant coatings for steel structures create parallel compliance pathways that shape product formulation and testing investment. Stakeholders must monitor divergence between regional fire-test protocols and the pace of green-building code integration, where embodied carbon of cementitious systems faces emerging scrutiny against bio-based or lower-carbon intumescent alternatives.
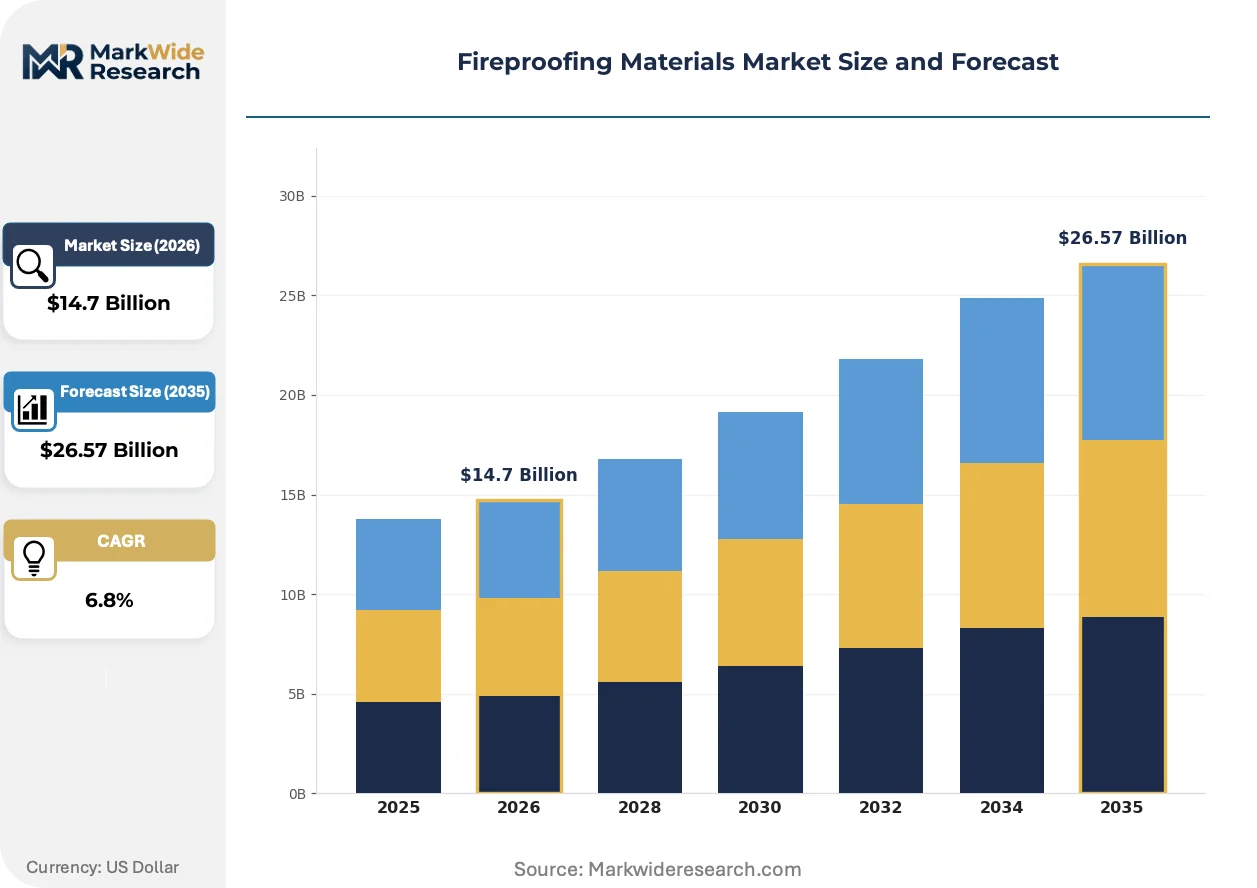
Market Dynamics
Urban high-rise construction in China, India, and the United States is tightening flame-spread requirements under national fire safety codes, forcing cementitious and intumescent formulators to certify products across divergent test protocols simultaneously.
Growth Catalysts
- EU Construction Products Regulation:CE marking mandates under EN 13381 standards are accelerating specification of passive fire protection in commercial steel structures across Germany, France, and Italy.
- China's GB 14907 standard:Fire-retardant coating certification for steel structures is driving volume demand from state-funded infrastructure and transit-oriented development projects.
- Intumescent chemistry advancement:Thinner film builds achieving equivalent fire-resistance ratings are penetrating architectural exposed-steel applications where cementitious bulk is aesthetically prohibitive.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and epoxy resin prices fluctuate with crude oil indices, compressing margin stability for intumescent coating producers.
- Portland cement embodied carbon:Green-building codes in California and the EU are scrutinizing cementitious systems against lower-carbon alternatives, creating compliance friction.
- Spray-applicator labor scarcity:Certified cementitious spray technicians concentrate in legacy construction markets, limiting deployment speed in emerging geographies.
Strategic Opportunities
- India's BIS certification expansion:Untapped penetration in tier-2 and tier-3 cities offers first-mover advantage for intumescent systems in commercial mid-rise construction.
- Modular construction fire boards:Factory-applied passive protection in offsite manufacturing addresses field-application constraints and labor shortages.
- NFPA 251/UL 263 harmonization pressure:Convergence between US and EU test standards would reduce dual-certification costs for multinational formulators.
Industry Challenges
- Multi-jurisdiction certification timelines:Parallel testing under NFPA 251, EN 13381, and GB 14907 stretches product launch cycles by 18-24 months.
- Applicator training infrastructure:Field quality control for spray-applied cementitious systems depends on scarce certified technicians, creating execution risk on large commercial projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fireproofing Materials Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intumescent Coatings, Cementitious Materials, Fire-Resistant Boards, Spray-Applied Fireproofing Application: Commercial Buildings, Industrial Facilities, Residential Structures, Infrastructure Projects Technology: Passive Fire Protection, Active Fire Protection, Fire-Resistive Glazing, Fireproof Insulation End User: Construction Companies, Architects, Building Owners, Fire Safety Engineers |
| Companies Covered | Sika, Etex Group, 3M, Carboline, PPG Industries, Akzo Nobel, Isolatek International, Jotun Group, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fireproofing Materials Market Emerging Trajectories
Formulation chemistry and application methodology are converging to address embodied carbon scrutiny while maintaining fire-resistance performance. Three developments are restructuring competitive advantage.
Hybrid intumescent-cementitious systems are consolidating specification share in high-rise commercial towers. These dual-technology coatings combine the thin-film aesthetics of intumescent chemistry with the thermal mass of mineral fillers. Developers in New York and London are specifying them for exposed steel atriums where architectural visibility conflicts with traditional cementitious bulk. The technology is consolidating formerly separate procurement decisions into single-source contracts.
REACH authorization processes for halogenated flame retardants are tightening feedstock availability for legacy intumescent formulations. ECHA substance evaluations are forcing reformulation toward phosphorus-nitrogen chemistries with higher raw material costs. European coating producers are responding by accelerating bio-based binder research, while US formulators face divergent EPA TSCA review timelines that complicate transatlantic product alignment.
Specification authority is migrating from general contractors to fire safety engineers retained by institutional asset owners. Large pension funds and REITs in Canada and Australia now mandate third-party fire-resistance verification before capital commitment. This shift compresses the influence of traditional distribution channels and elevates technical documentation and testing transparency as primary competitive differentiators.
Fireproofing Materials Market Segmentation
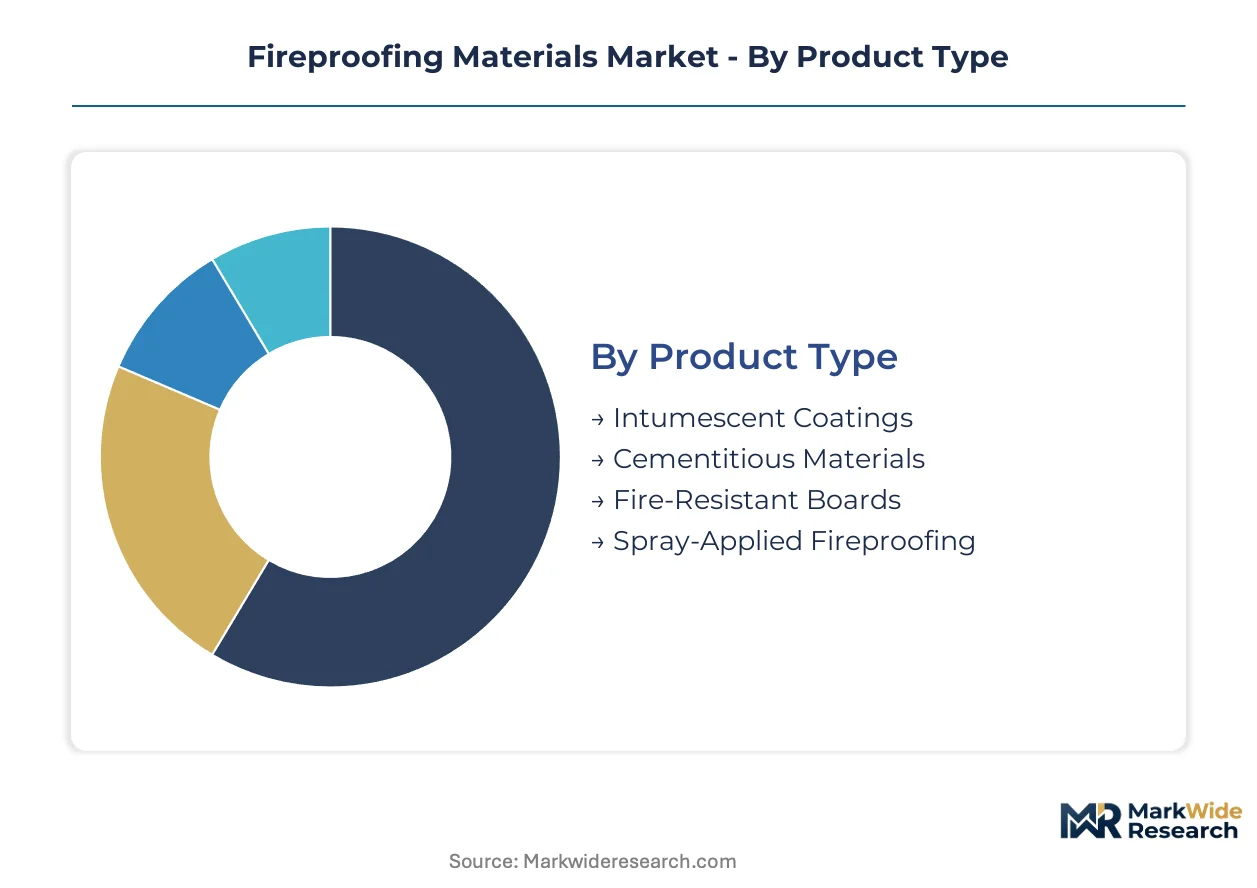
Fireproofing materials segment along four dimensions that determine specification authority, margin structure, and certification burden. Product type governs raw material exposure and embodied carbon profiles. Application context dictates fire-resistance rating requirements and labor intensity. Technology choice separates capital-light passive systems from activation-dependent active protection. End-user identity shapes procurement channel and technical documentation demands.
Product Type:
Cementitious materials dominate volume flows while intumescent coatings command premium positioning through thinner film builds and architectural acceptability.
- Cementitious Materials:Portland cement-based sprays and trowel-applied compounds mineralize under heat to insulate structural steel. Demand concentrates in China's state-funded infrastructure and US commercial high-rises where low material cost outweighs aesthetic exposure concerns. Embodied carbon scrutiny under California's green-building codes and EU Green Deal frameworks is forcing formulators toward supplementary cementitious material blends.
- Intumescent Coatings:Acrylic and epoxy resin systems expand into char layers when exposed to flame, achieving equivalent fire ratings at one-tenth the thickness of cementitious alternatives. Specification is accelerating in London and New York exposed-steel atriums where architectural visibility prohibits bulk protection. REACH authorization pressures on halogenated flame retardants are accelerating phosphorus-nitrogen chemistry migration.
- Fire-Resistant Boards:Calcium silicate and gypsum-based panels provide factory-controlled passive protection for modular construction and retrofit applications where field spray application is constrained.
- Spray-Applied Fireproofing:Wet and dry-mix cementitious systems applied through specialized pumping equipment dominate North American commercial construction certification protocols.
Today's leader: Cementitious Materials. Tomorrow's challenger: Intumescent Coatings.
Application:
Commercial building specifications generate the highest certification density per project, while infrastructure projects offer volume concentration through multi-year procurement windows.
- Commercial Buildings:High-rise office towers and mixed-use developments require fire-resistance ratings spanning one to four hours under NFPA 251, EN 13381, and GB 14907 protocols simultaneously. China's tier-1 cities and India's Mumbai-Delhi corridor are tightening enforcement as urban density increases.
- Industrial Facilities:Petrochemical plants and power generation assets demand specialized hydrocarbon fire testing beyond standard cellulosic curves. The US Gulf Coast and Germany's Rhine-Ruhr industrial belt sustain specification volume for cementitious and epoxy intumescent systems rated for jet fire exposure.
- Residential Structures:Mid-rise timber and light-gauge steel construction in Australia and Canada is expanding specification of fire-resistant boards where sprinkler activation cannot guarantee structural integrity.
- Infrastructure Projects:Transit tunnels, airports, and bridges in China's state-funded buildout specify cementitious sprays for steel reinforcement protection in underground and elevated conditions.
Commercial Buildings anchor current revenue. Industrial Facilities offer the steepest expansion trajectory through hydrocarbon fire testing specialization.
Technology:
Passive systems integrate directly into building envelopes without activation energy, while active protection requires continuous power and maintenance infrastructure.
- Passive Fire Protection:Cementitious sprays, intumescent coatings, and fire boards provide ever-present thermal insulation through material properties alone. Germany's CE marking enforcement under EN 13381 and India's BIS certification expansion are accelerating specification across commercial steel structures.
- Active Fire Protection:Sprinkler systems, fire suppression gases, and water mist require detection, power, and maintenance to function. These systems complement rather than replace passive protection in high-value commercial and industrial assets.
- Fire-Resistive Glazing:Laminated glass assemblies with intumescent interlayers maintain transparency while achieving rated fire separation in atrium barriers and stairwell enclosures.
- Fireproof Insulation:Mineral wool and ceramic fiber systems provide thermal barrier functions in industrial process equipment and marine applications where coating adhesion is problematic.
Passive Fire Protection commands specification authority. Fire-Resistive Glazing is gaining share fastest through architectural transparency demands.
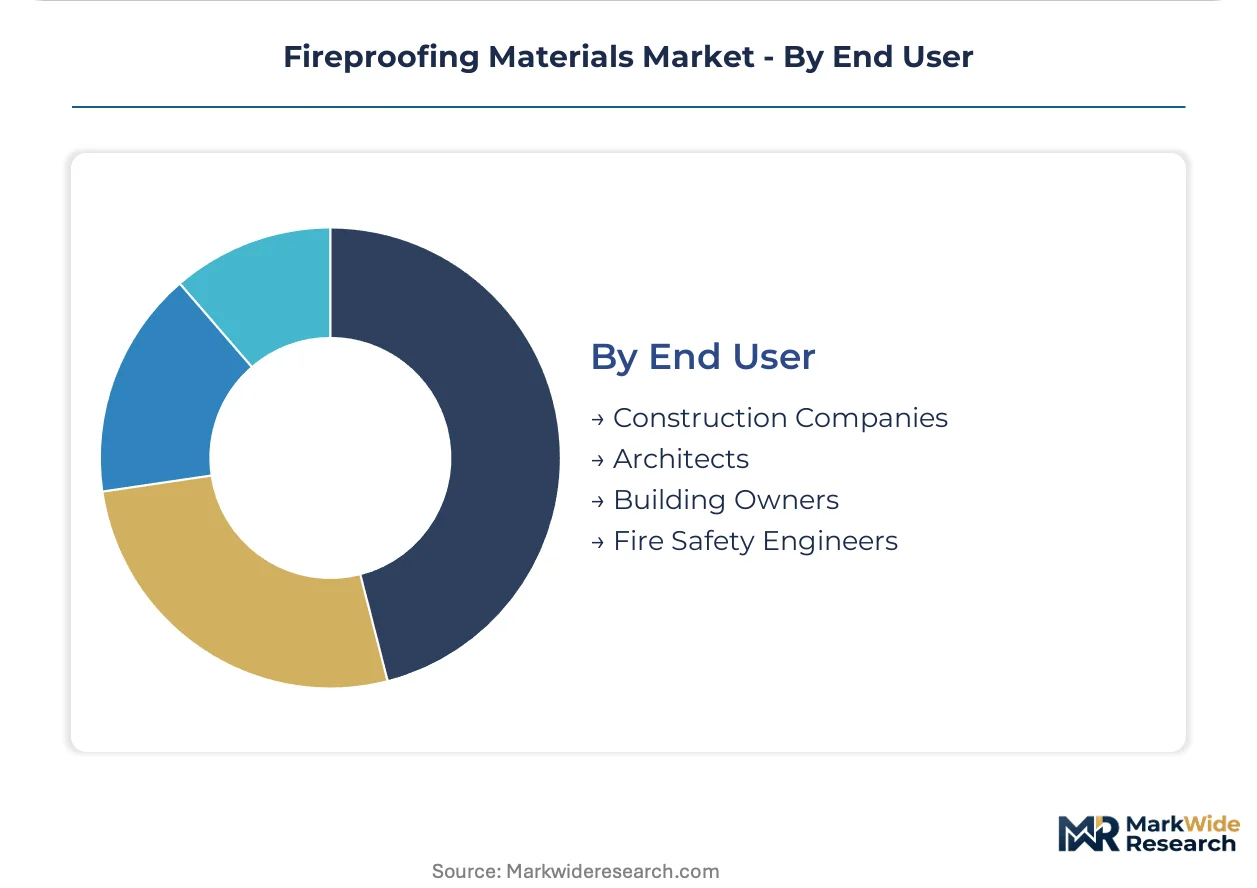
End User:
Procurement authority is migrating from general contractors toward technically credentialed stakeholders who carry liability for fire-resistance performance.
- Construction Companies:General contractors in the United States and United Kingdom retain specification influence on commodity cementitious applications where proven applicator relationships reduce execution risk. Labor scarcity for certified spray technicians is compressing their operational flexibility.
- Architects:Design professionals in Australia and Canada increasingly mandate intumescent coatings for exposed steel where aesthetic outcomes determine project awards. Their specification authority rises with project complexity and visibility.
- Building Owners:Institutional asset owners including Canadian pension funds and Australian REITs now require third-party fire-resistance verification before capital commitment, elevating technical documentation demands.
- Fire Safety Engineers:These specialists interpret NFPA 251, UL 263, and EN 13381 test results to certify compliance for authorities having jurisdiction. Their retained involvement is expanding as liability for fire performance concentrates with asset owners.
Construction Companies retain volume influence. Fire Safety Engineers are capturing specification authority through verification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as formulators relocate manufacturing to jurisdictions with streamlined certification pathways. Compliance cost differentials between the EU Construction Products Regulation and national fire codes in Asia-Pacific are accelerating capacity migration toward export-oriented production zones.
United States
Commercial high-rise construction in New York and Chicago drives specification volume for spray-applied cementitious systems. NFPA 251 and UL 263 standards enforced by local authorities having jurisdiction mandate third-party fire-resistance verification. The US Gulf Coast petrochemical corridor sustains demand for epoxy intumescent coatings rated for hydrocarbon fire exposure.
Germany
Industrial facility modernization across the Rhine-Ruhr belt requires structural steel protection under EN 13381 harmonized standards. ECHA REACH authorization processes for halogenated flame retardants are forcing phosphorus-nitrogen chemistry migration. Bavarian chemical producers are consolidating backward integration into acrylic resin feedstocks.
China
State-funded infrastructure buildout in tier-1 cities specifies cementitious sprays for transit tunnels and elevated bridges. GB 14907 standard certification for fire-retardant coatings creates compliance barriers for imported formulations. The Yangtze River Delta manufacturing cluster hosts captive production for both domestic consumption and Southeast Asian export.
India
Commercial mid-rise construction in Mumbai and Delhi-NCR is tightening enforcement under expanded BIS certification requirements. Tier-2 and tier-3 cities present penetration opportunities for intumescent systems as code adoption spreads. Gujarat-based formulators are establishing distribution networks to address applicator training gaps in emerging markets.
United Kingdom
Post-Grenfell regulatory reforms mandate enhanced fire-resistance documentation for high-rise residential and commercial assets. London exposed-steel atrium projects specify hybrid intumescent-cementitious systems where architectural visibility conflicts with traditional bulk protection. Midlands manufacturing facilities serve cross-border demand from Irish and French construction markets.
Fireproofing Materials Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular construction and lower-carbon formulation niches. The market structures around three capability clusters: construction chemicals platforms with bundled passive fire protection, specialized cementitious spray applicators with certified technician networks, and resin-integrated coating formulators with captive feedstock control. Dominant competitive moves include backward integration into acrylic and epoxy chemistries and geographic expansion through local certification partnerships.
Among Swiss construction chemicals platforms, Sika exemplifies the bundled-systems archetype. Isolatek International occupies a position within North American cementitious spray specialists. BASF anchors the resin-integrated tier through upstream control over intumescent coating feedstocks. These three represent divergent strategic postures rather than direct positional competition.
| Leading Market Players |
|---|
| Sika |
| Etex Group |
| 3M |
| Carboline |
| PPG Industries |
| Akzo Nobel |
| Isolatek International |
| Jotun Group |
| BASF |
| Others |
Supply Flow & Price Mechanics
EU Construction Products Regulation mandates for CE marking under EN 13381 standards are forcing commercial developers to qualify multiple coating suppliers simultaneously, compressing procurement timelines and amplifying price competition among certified formulators.
Pricing Analysis
Petrochemical feedstock volatility in acrylic and epoxy resins passes directly through to intumescent coating price schedules, with formulators indexing contracts to crude oil benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates UL 263-certified systems from basic GB 14907-compliant alternatives and uncertified commodity sprays. Cost compression in cementitious tiers is intensifying because Portland cement embodied carbon scrutiny under EU Green Deal frameworks raises compliance expenditure. General contractors in North American commercial construction exhibit highest price sensitivity, while institutional asset owners in London and New York prioritize fire-resistance documentation over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from pension funds and REITs mandate qualified backup suppliers for all passive fire protection categories, stretching certification timelines and consolidating procurement around multi-product construction chemicals platforms. Manufacturing concentrates in China, Germany, and the United States, with the Yangtze River Delta hosting captive resin production for intumescent feedstocks. Raw material dependencies center on Portland cement clinker, phosphorus-nitrogen flame retardant precursors, and acrylic resin monomers. Single-source vulnerability in halogenated flame retardant supply chains under REACH authorization pressure elevates reformulation risk. Distribution runs through specialized construction chemicals distributors with certified applicator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fireproofing materials function as a stable compounder anchored by irreversible regulatory tightening in structural fire safety codes across major construction markets.
For Market Incumbents: Lock in specification authority by accelerating backward integration into phosphorus-nitrogen flame retardant feedstocks before REACH authorization constraints tighten further. Cementitious specialists must defend against hybrid intumescent-cementitious displacement by embedding supplementary cementitious material blends that satisfy California and EU embodied carbon thresholds. Capacity addition in India's Gujarat corridor addresses applicator training gaps and preempts emerging entrant consolidation. For New Entrants and Emerging Players: Bio-based binder chemistry for intumescent systems offers a technology-first wedge into European commercial mid-rise construction where ECHA substance evaluations are forcing incumbent reformulation. India's tier-2 and tier-3 cities present the most penetrable geography, with BIS certification expansion creating first-mover windows before established players extend distribution. Factory-applied fire boards for modular construction provide a channel bypass around scarce certified spray technician networks. For Investors and Strategic Acquirers: Asymmetric upside sits with resin-integrated coating formulators with captive phosphorus-nitrogen chemistry supply and multi-jurisdiction certification portfolios. Long-term viability over a decade-plus horizon rests on regulatory divergence between EU REACH processes and US EPA TSCA timelines, which rewards players with parallel testing infrastructure. Acquisition target archetype: regional cementitious spray specialists with certified technician density in underpenetrated Indian or Southeast Asian markets. The signal to watch is harmonization pressure between NFPA 251 and EN 13381 standards, which would compress dual-certification cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Flame Retardant Feedstocks | REACH authorization timelines for halogenated chemistries reward captive phosphorus-nitrogen supply. |
| Modular Construction Fire Board Capacity | Factory-applied passive protection bypasses field applicator scarcity in high-growth Asian markets. |
| Multi-Jurisdiction Certification Investment | Parallel NFPA 251, EN 13381, and GB 14907 testing reduces launch cycle friction for multinational formulators. |
| Supplementary Cementitious Material Blends | EU Green Deal embodied carbon thresholds favor Portland cement reduction in commercial specifications. |
| Certified Applicator Training Infrastructure | Scarcity of qualified spray technicians in India and Southeast Asia creates execution risk for volume deployment. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with fire safety engineers, construction chemicals procurement leads, certified spray applicators, and regulatory compliance officers with secondary validation. Primary fieldwork drew from customs and trade flow data, national fire code enforcement records from Germany's DIBt and India's BIS, and construction project databases tracking passive fire protection specification. Secondary sources included EN 13381 test laboratory disclosures, SEC 10-K filings from listed construction chemicals producers, and EU Construction Products Regulation notification databases. Bottom-up project pipeline analysis and top-down construction spend allocation were triangulated against formulator shipment data.
Granularity-level modeling disaggregated volume and value across product type, application context, technology choice, and end-user identity dimensions, with additional segmentation by regional regulatory cluster and certification tier. CAGRs were derived from regression against construction spend forecasts and fire code adoption curves, with cross-validation against historical specification elasticity. Industry-specific forecast inputs incorporated cement clinker price trajectories, REACH authorization timelines for halogenated flame retardants, and modular construction penetration rates in commercial building.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization timing, petrochemical feedstock volatility, and green-building code stringency evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Global Insulation Coating Materials Market
Insulation Materials
North America Expanded Polypropylene Foam Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Industrial Insulation Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Global High-Performance Insulation Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Polypropylene Foams Market
Insulation Materials
Global Calcium Silicate Insulation Market
Insulation Materials
Dielectric Fluid Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
EV Battery Thermal Insulation Materials Market
Insulation Materials
Low Temperature Insulation Materials Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
Global Insulation Market