
 Rock Wool Insulation Board Market | 2026-2036
Rock Wool Insulation Board Market Size, Share, and Industry Trends Forecast 2026-2036
Rock Wool Insulation Board Market Insights
Modular insulation kits bundling rigid boards with complementary fixings and vapor barriers is expanding buyer choice across specification-driven projects. Rockwool International A/S leverages its vertically integrated stone wool production network to sustain premium positioning in European commercial builds. Owens Corning competes through fiberglass-rock wool hybrid systems that anchor its presence in North American industrial insulation. Johns Manville specializes in medium-density batts for residential structures, occupying a distinct tier between commodity loose fill and high-performance rigid boards.
Rock wool insulation board consists of spun mineral fibers derived from basalt or diabase, bonded with phenolic resin and formed into rigid panels with thermal conductivity typically ranging from 0.035 to 0.040 W/mK; manufacturers achieve densities between 80 and 200 kg/m³ depending on end-use structural load requirements. The material primarily serves fire-resistant thermal envelope applications where non-combustibility ratings under ISO 1182 prove critical for regulatory compliance. Rigid boards command the dominant margin pool across product types due to their specification in high-rise commercial facades and industrial process equipment. Medium thickness segments between 50 and 100 millimeters represent the fastest-growing configuration as building codes tighten minimum insulation values without requiring structural modifications for extra-thick installations. Acoustic treatment applications in transportation infrastructure and entertainment venues are displacing traditional fiberglass where fire safety codes restrict polymer-based alternatives.
The EU Green Deal and national implementations of the Energy Performance of Buildings Directive through Germany's KBA and France's ANSM-aligned building regulators mandate progressive reductions in primary energy demand, directly stimulating specification of higher-density rock wool products. REACH compliance for binder chemistries and evolving CE marking requirements under the Construction Products Regulation shape market access conditions for both European producers and importers serving the regional construction supply chain. Stakeholders must monitor divergence between national transpositions of EU-wide efficiency targets and emerging local content preferences in public procurement frameworks.
Market Dynamics
Deep renovation mandates across Northern Europe are compressing specification cycles and forcing insulation contractors to pre-certify complete thermal envelope systems rather than bid discrete material lots.
Growth Catalysts
- EU Green Deal implementation:Germany's KBA and France's national building regulators enforce progressive primary energy reductions that mandate thicker rigid board specifications in commercial retrofits.
- Urban corridor concentration:Aging building stock in London, Berlin, and Paris corridors generates concentrated retrofit demand where fire-rated assemblies prove non-negotiable.
- Acoustic specification migration:Transportation infrastructure and entertainment venues specify mineral fiber over fiberglass where ISO 1182 non-combustibility ratings restrict polymer-based alternatives.
Market Restraints
- Basalt feedstock volatility:Energy-intensive smelting operations tie production economics to regional electricity pricing, compressing margins when carbon border adjustments phase in.
- REACH compliance friction:ECHA scrutiny of phenolic binder chemistries forces reformulation investments that disadvantage smaller importers lacking captive R&D infrastructure.
- Polymer foam substitution:Extruded polystyrene and polyisocyanurate boards compete on thermal conductivity in applications where fire ratings permit combustible materials.
Strategic Opportunities
- Modular kit bundling:Contractors in the United Kingdom and Germany specify pre-engineered packages combining rigid boards, fixings, and vapor barriers that reduce on-site labor and warranty risk.
- CE marking convergence:Construction Products Regulation harmonization creates pathway for standardized products to access multiple EU national markets without redundant testing.
- Industrial process equipment:High-temperature insulation for petrochemical and power generation assets represents underserved specification tier between commodity batts and specialty ceramic fibers.
Industry Challenges
- Certification timeline compression:CE marking and national building code updates require continuous retesting as binder formulations evolve to meet REACH restrictions.
- Installation skill scarcity:Deep renovation projects demand certified contractors capable of executing multi-layer vapor-open assemblies without thermal bridging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rock Wool Insulation Board Market |
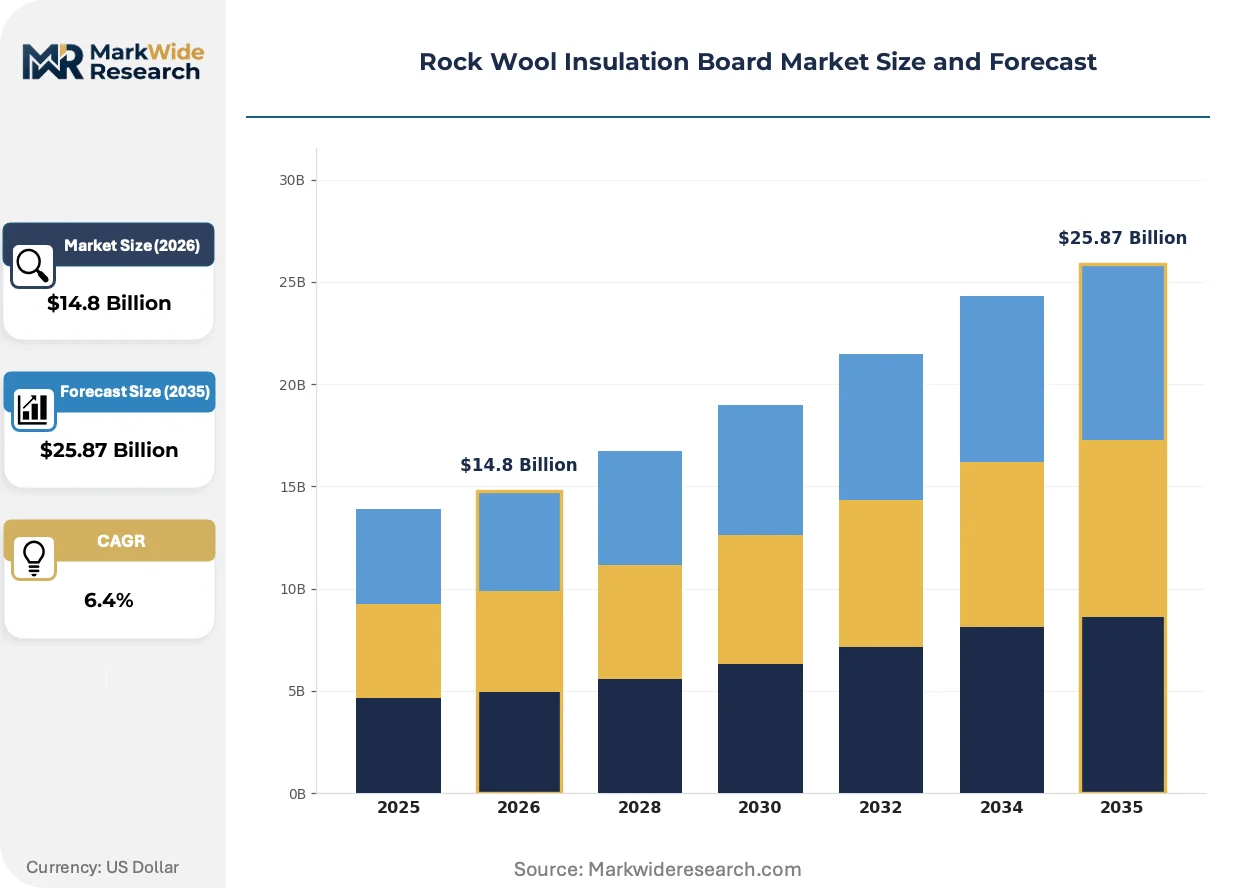
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Boards, Batts, Loose Fill, Blankets Application: Commercial Buildings, Industrial Insulation, Residential Structures, Acoustic Treatment Thickness: Low (up to 50 mm), Medium (50-100 mm), High (100-150 mm), Extra Thick (over 150 mm) End User: Contractors, Architects, Building Owners, Engineers |
| Companies Covered | Rockwool International A/S, Owens Corning, Johns Manville, Knauf Insulation, Saint-Gobain, Paroc Group, Kingspan Group plc, CertainTeed Corporation, Thermafiber, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rock Wool Insulation Board Market Trends and Innovations
Mineral fiber manufacturing is pivoting toward bio-based binder systems and automated panel finishing that reduce embodied carbon while accelerating production throughput for specification-driven projects.
Water-repellent additive integration is consolidating specification preference in rainscreen and cavity wall applications where moisture management determines long-term thermal performance. German facade engineers specify factory-applied coatings that eliminate field-applied membranes, compressing installation schedules by 30-40% on high-rise commercial envelopes. This consolidation is compressing the addressable market for untreated boards in above-grade exterior applications.
France's ANSM-aligned building regulators and Germany's KBA have transposed Energy Performance of Buildings Directive requirements into enforceable primary energy caps that trigger automatic insulation upgrades at renovation trigger points. Industrial consequence includes mandatory thickness calculators that specify rock wool over competing materials when fire separation requirements apply. Multi-family residential and healthcare verticals face the steepest compliance ramps, with Paris and Berlin municipalities requiring pre-submitted thermal bridge calculations.
Specification authority is migrating from general contractors to facade consultants and energy modelers who bundle insulation into performance-guaranteed envelope packages. Distributors in the United Kingdom and Netherlands respond by hiring in-house technical sales engineers capable of running hygrothermal simulations. This shift is most visible in London's commercial retrofit corridor, where developer-procured insulation now flows through specialist envelope contractors rather than traditional merchant builders.
Rock Wool Insulation Board Market Segmentation
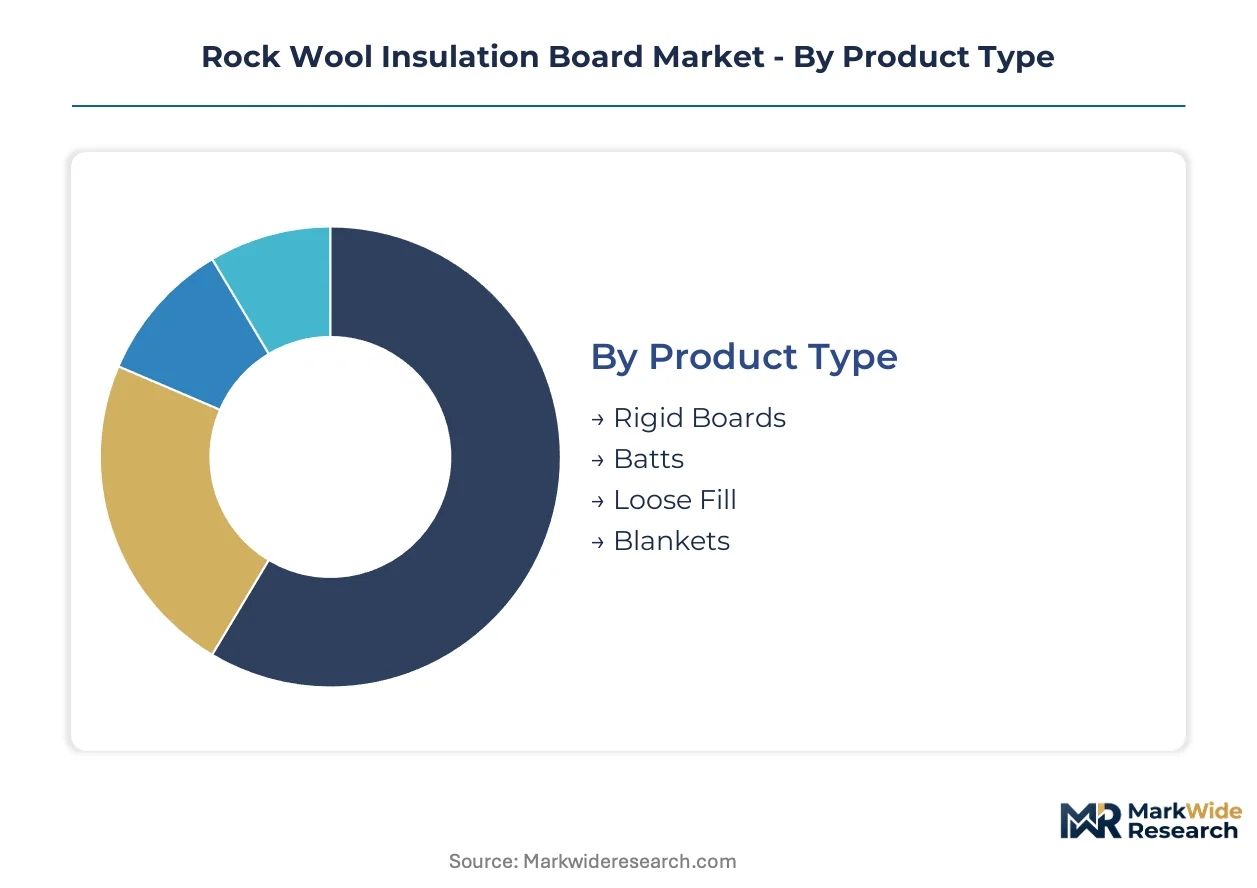
Rock wool insulation board procurement hinges on specification authority residing with distinct professional cohorts across project phases. Product selection varies sharply by thermal performance requirements, fire rating mandates, and installation constraints that differ across building types and renovation intensities.
Product Type:
Buyers select product formats based on structural load requirements and installation labor economics, with density and rigidity determining suitability for specific envelope positions.
- Rigid Boards:High-density panels formed from resin-bonded mineral fibers achieve densities between 80 and 200 kg/m³ for load-bearing facade applications. German and French commercial developers specify these for high-rise retrofits where non-combustibility ratings under ISO 1182 are mandatory and thermal bridging must be eliminated.
- Batts:Medium-density flexible slabs suit cavity wall and framed construction where compression resistance matters less than conformability around irregular substrates. Johns Manville dominates residential tier positioning between commodity loose fill and specification-grade rigid boards.
- Loose Fill:Granulated mineral fiber blown into attics and closed cavities offers lowest installed cost for residential top-up insulation where fire ratings are secondary.
- Blankets:Flexible rolls with reinforcing mesh suit industrial pipe and vessel wrapping where thermal cycling demands compliant insulation layers.
Volume sits with Rigid Boards; growth tilts toward Batts as residential energy retrofit programs accelerate across Northern Europe.
Application:
End-use segmentation tracks regulatory pressure intensity, with fire safety codes and energy performance standards creating divergent material specifications across building categories.
- Commercial Buildings:High-rise facades and flat roofs demand the thickest rigid board configurations to meet primary energy caps under Germany's KBA and France's ANSM-aligned building codes. London, Berlin, and Paris corridors concentrate retrofit demand where aging stock requires deep renovation with fire-rated assemblies.
- Industrial Insulation:Petrochemical and power generation assets specify medium-to-high density boards for process equipment and ductwork where temperatures exceed residential ranges. Owens Corning anchors North American presence through fiberglass-rock wool hybrid systems in this segment.
- Residential Structures:Single-family and multi-family buildings drive batt and loose fill consumption where cost sensitivity dominates and fire separation requirements are less stringent than commercial codes.
- Acoustic Treatment:Transportation infrastructure and entertainment venues specify mineral fiber over fiberglass where ISO 1182 non-combustibility ratings restrict polymer-based alternatives in tunnels, rail stations, and performance halls.
Commercial Buildings command the dominant revenue pool; Acoustic Treatment expands most quickly as rail and transit investments multiply across urban corridors.
Thickness:
Thermal conductivity targets and structural modification constraints determine thickness selection, with building code minimums forcing step-ups in specification without always permitting extra-thick installations.
- Low (up to 50 mm):Thin boards serve interior partition fire-stopping and limited thermal upgrade scenarios where space is constrained and structural loads are minimal.
- Medium (50-100 mm):This configuration gains share fastest as EU Energy Performance of Buildings Directive implementations mandate thicker envelopes without requiring structural reinforcement for ultra-thick systems. German facade engineers prioritize this band for high-rise commercial retrofits.
- High (100-150 mm):Deep energy renovation projects in Northern European urban corridors specify these thicknesses for exterior wall assemblies where thermal bridge calculations are pre-submitted to municipalities.
- Extra Thick (over 150 mm):Specialized applications in passive house construction and industrial process equipment employ these dimensions where thermal performance overrides installation complexity and material cost.
Medium thickness configurations dominate new specification; Extra Thick boards climb fastest in deep renovation mandates across Paris and Berlin municipalities.
End User:
Procurement authority migration from general contractors to technical specialists is reshaping which professional cohorts influence material selection and brand preference.
- Contractors:Installation firms increasingly source through specialist envelope contractors rather than traditional merchant builders as warranty risk concentrates in performance-guaranteed assemblies. UK and German distributors respond by hiring in-house technical sales engineers.
- Architects:Design professionals specify rigid boards in early-stage documentation where facade aesthetics and thermal bridge-free detailing determine material selection before contractor involvement.
- Building Owners:Developer-procured insulation in London's commercial retrofit corridor flows through owner-directed envelope packages that bundle boards with fixings and vapor barriers.
- Engineers:Energy modelers and facade consultants now run hygrothermal simulations that override contractor preferences, particularly in multi-family residential and healthcare verticals facing steepest compliance ramps.
Contractors retain the highest transaction volume; Engineers gain specification influence fastest as performance-guaranteed envelope packages disperse decision-making authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Northern Europe while consumption pulls strongest from aging urban building stock across Germany, France, and the United Kingdom. Basalt smelting economics tie manufacturing locations to regional electricity pricing and carbon border adjustment exposure. Deep renovation mandates in London, Berlin, and Paris corridors generate specification intensity unmatched elsewhere.
Germany
Commercial retrofit volumes in Berlin and Hamburg drive rigid board demand as KBA-enforced primary energy caps mandate thicker thermal envelopes. The country's national building regulator transposes EU Energy Performance of Buildings Directive requirements into binding renovation triggers at property transactions. Rhine-Ruhr industrial corridors host specification consultants who bundle insulation into performance-guaranteed facade packages.
France
ANSM-aligned building codes in Île-de-France impose automatic insulation upgrades when multi-family residential properties change hands. Paris municipalities require pre-submitted thermal bridge calculations that favor mineral fiber over combustible alternatives in high-rise envelopes. Deep renovation intensity concentrates in Lyon and Marseille corridors where aging social housing stock faces compliance deadlines.
United Kingdom
London's commercial retrofit corridor generates concentrated demand for modular insulation kits combining rigid boards with factory-applied water-repellent coatings. Building safety regulations post-Grenfell restrict combustible materials in external wall systems, reinforcing mineral fiber specification. Manchester and Birmingham follow with lagged but accelerating renovation mandates.
United States
Industrial process insulation in Gulf Coast petrochemical clusters sustains demand for medium-density boards where temperature cycling exceeds residential ranges. EPA and OSHA thermal safety standards shape material selection in power generation and chemical processing assets. Midwest manufacturing corridors exhibit growing specification of hybrid mineral-fiber systems for combined thermal-acoustic performance.
China
Dual carbon goals and GB standards for building energy efficiency accelerate specification in Yangtze River Delta commercial construction. MIIT industrial policy supports domestic basalt fiber production capacity expansion to reduce import dependence. Beijing-Tianjin-Hebei corridor faces tightening envelope standards for both new build and existing building retrofits.
Rock Wool Insulation Board Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct specification tiers. Market structure tilts toward consolidation at the premium rigid board segment while remaining fragmented in commodity batt and loose fill categories. Three archetypes dominate: vertically integrated stone wool producers with captive mineral supply, hybrid insulation system providers bridging fiberglass and mineral fiber technologies, and regional specialists serving contractor-direct distribution channels. Capacity expansion and modular kit bundling represent the dominant competitive moves as warranty risk concentrates in performance-guaranteed envelope systems.
Within the vertically integrated tier, Rockwool International A/S anchors premium positioning through in-house basalt processing networks. Owens Corning occupies the hybrid system vector, bridging mineral fiber and fiberglass competencies across North American industrial segments. Johns Manville exemplifies the specialist archetype, concentrating on medium-density formats for residential structures. These three represent distinct strategic postures rather than direct overlap, with each anchoring a separate specification tier and geographic emphasis.
| Leading Market Players |
|---|
| Rockwool International A/S |
| Owens Corning |
| Johns Manville |
| Knauf Insulation |
| Saint-Gobain |
| Paroc Group |
| Kingspan Group plc |
| CertainTeed Corporation |
| Thermafiber, Inc. |
| Others |
Pricing and Supply Chain Analysis
Captive basalt smelting networks in Germany and Denmark anchor supply positions for premium rigid board producers while insulating them from electricity price volatility that compresses margins for toll-dependent competitors. This upstream control translates directly into pricing power across specification-driven commercial retrofit corridors where REACH-compliant binder formulations command systematic premiums over import alternatives.
Pricing Analysis
Margin tightening in medium-density batts reflects polymer foam substitution in residential applications where fire ratings permit combustible materials. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked rigid boards with factory-applied water-repellent coatings from untreated commodity boards and loose fill. Cost-down pressure on standard-grade products accelerates because German distributors bundle pre-engineered kits that eliminate field-applied membranes. Residential contractors exhibit highest price sensitivity; facade consultants specifying high-rise commercial envelopes demonstrate lowest.
Supply Chain Analysis
Certified insulation installer shortages in Germany, France, and the United Kingdom constrain throughput at deep renovation sites despite adequate raw material availability. Manufacturing concentrates in Denmark, Germany, and Poland where basalt deposits and grid access support energy-intensive fiber spinning operations. Production draws from phenolic resin binders, basalt feedstock, and water-repellent chemical additives. Single-source vulnerability sits with specialized binder chemistries facing ECHA scrutiny. Distribution runs through specialist envelope contractors displacing traditional merchant builders in London and Berlin corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH binder restrictions and CE marking requirements under the Construction Products Regulation erect barrier-to-entry moats favoring incumbents with captive R&D infrastructure.
For Market Incumbents: Cement specification authority by embedding energy modelers and facade consultants into early-stage project development before contractor involvement solidifies. Deepen backward integration into bio-based binder development to preempt REACH-driven reformulation cycles that disadvantage smaller competitors. Defend against polymer foam substitution in residential tiers by accelerating modular kit bundling that reduces on-site labor costs. For New Entrants and Emerging Players: The price-point gap between premium CE-marked rigid boards and economy loose fill creates entry space for mid-tier batt producers serving residential retrofit programs in Northern Europe. Target France's ANSM-aligned multi-family residential compliance deadlines where aging social housing stock faces automatic upgrade triggers at property transactions. Pursue contractor-direct distribution partnerships with UK specialist envelope firms hiring technical sales engineers. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified building materials conglomerates seeking mineral fiber exposure. Long-term viability hinges on regulatory tightening persistence rather than cyclical construction demand. Target vertically integrated stone wool specialists with captive basalt processing and established CE marking dossiers. Monitor divergence between national transpositions of EU Energy Performance of Buildings Directive as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Binders | REACH compliance investments preempt ECHA restrictions on phenolic chemistries. |
| Modular Insulation Kit Bundling | German facade engineers specify pre-engineered packages compressing installation schedules. |
| CE Marking Harmonization Investment | Construction Products Regulation convergence enables multi-country market access without redundant testing. |
| Technical Sales Engineer Recruitment | UK and Netherlands distributors hire simulation-capable staff to serve migrating specification authority. |
| Factory-Applied Coating Capacity Addition | Water-repellent additive integration eliminates field membranes in rainscreen applications. |
Research Methodology
Trade association filings, EU Construction Products Regulation databases, and national building code transposition documents formed the secondary backbone for market sizing and regulatory mapping. Primary interviews with facade consultants, energy modelers, insulation contractors, and technical sales engineers at distribution firms validated specification trends and procurement patterns. Bottom-up project pipeline analysis across London, Berlin, and Paris corridors combined with top-down construction spend forecasts to triangulate volume estimates.
Historical trendline analysis tracked rigid board, batt, and loose fill shipments across product type, application, and thickness configurations over the analysis window. Segmentation modeling incorporated building category, end-user professional cohort, and regional regulatory cluster dimensions. CAGRs derived from regression analysis against renovation mandate intensity and primary energy cap trajectories. Forecast inputs included basalt smelting capacity expansion announcements and certified installer pipeline data from German and French trade bodies.
Inputs from ECHA regulatory filings and KBA enforcement calendars were available through the study window; gaps in real-time contractor pricing data introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding REACH implementation timelines and national building code adoption rates. Basalt feedstock cost volatility, carbon border adjustment phase-in, and installer certification bottlenecks represent material revision triggers. Material deviation in named regulatory enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Acoustic Materials Market
Insulation Materials
Global Glass Insulation Market
Insulation Materials
Fire Protective Materials Market
Insulation Materials
Syntactic Foam Market
Insulation Materials
Wire Insulation and Jacketing Compounds Market
Insulation Materials
Recyclable Thermal Insulation Packs Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Hot Insulation Materials Market
Insulation Materials
Japan Industrial Insulation Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Global PVC Foam Sheet Market
Insulation Materials
Microencapsulated Paraffin Phase Change Materials Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Global Insulation Materials Market