
 Low Iron Glass Market | 2026-2036
Low Iron Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Low Iron Glass Market Foresight
REACH compliance in Europe is hardening the cost-of-entry calculus for low iron glass suppliers seeking access to construction and solar markets. Compagnie de Saint-Gobain S.A. leverages its vertical integration from raw silica to coated finished products across multiple continents. AGC Inc. anchors its position through sustained R&D intensity in thin-film photovoltaic substrates. Schott AG differentiates via specialized melting technology for electronics-grade low iron substrates.
Low iron glass contains less than 0.05% iron oxide, typically manufactured through float glass processes with refined silica sand selection to achieve superior optical clarity and minimal green tint. Its primary purpose serves applications where maximum light transmission matters: solar energy conversion, high-performance architectural glazing, and display electronics. Flat glass dominates volume shipments across solar panel and architectural channels, while coated glass captures disproportionate margin pools through anti-reflective and conductive layer value-addition. Solar energy end-use represents the fastest-expanding demand segment as module manufacturers prioritize conversion efficiency gains.
The EPA enforces emissions standards affecting float glass furnace operations in the United States, while China's MEE implements dual carbon targets that reshape energy-intensive glass manufacturing economics. India's BIS certification requirements for construction materials create compliance gateways for imported low iron glass products. Stakeholders must monitor evolving carbon border adjustment mechanisms and furnace fuel-switching mandates that will restructure production cost curves and regional supply competitiveness.
Market Dynamics
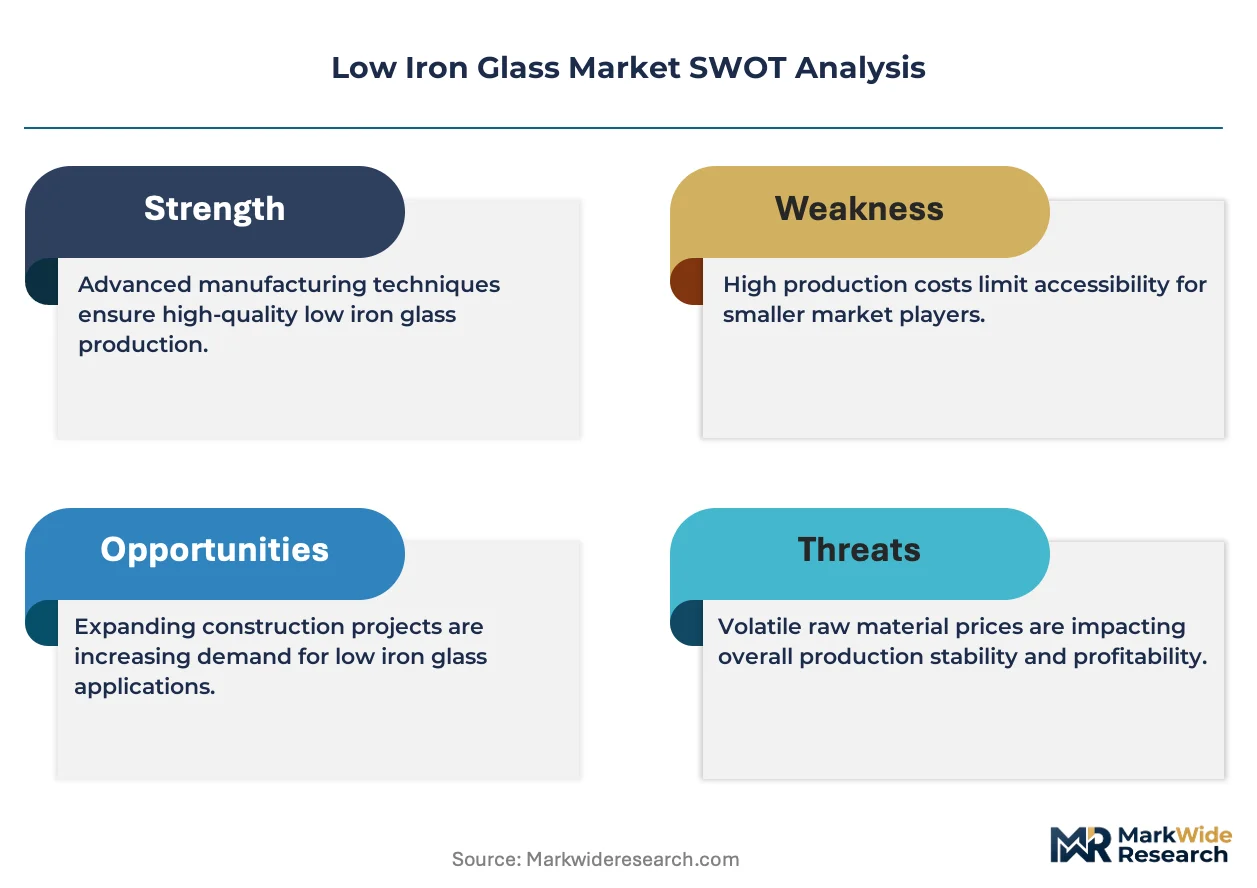
China's dual carbon goals and the EU Green Deal are compressing embodied carbon thresholds for construction materials, forcing float glass manufacturers to reconfigure furnace fuel sources and raw material sourcing strategies.
Growth Catalysts
- EU Green Deal carbon border adjustments:The Carbon Border Adjustment Mechanism tightens cost competitiveness for imported high-carbon glass, accelerating substitution toward low iron variants in German and French solar installations.
- Photovoltaic efficiency imperatives:Module manufacturers in India and China prioritize light transmission gains above 91% to maximize energy conversion ratios in utility-scale deployments.
- REACH compliance hardening:ECHA enforcement on heavy metal content in architectural glazing creates procurement preference shifts toward certified low iron supply chains.
Market Restraints
- High-purity silica sand scarcity:Ultra-low iron ore deposits concentrate in limited geographies, exposing float glass producers to input cost volatility and long-term offtake contract renegotiations.
- Furnace fuel-switching capex:Natural gas-to-hydrogen or electric melting conversions require 8-12 year payback periods, freezing capacity expansion decisions at European and North American plants.
- Thin-film cadmium telluride competition:First Solar's CdTe technology achieves comparable conversion efficiency without low iron glass superstrates, threatening crystalline silicon module demand.
Strategic Opportunities
- Building-integrated photovoltaics penetration:Façade architects in Germany and the Netherlands specify low iron glass for aesthetic transparency in commercial retrofits, opening non-module revenue streams.
- India PLI scheme for solar manufacturing:Domestic content bonus credits incentivize integrated low iron glass-to-module production clusters in Gujarat and Tamil Nadu.
- Anti-reflective coating convergence:Nanostructured surface treatments combined with low iron substrates enable 94%+ transmission, commanding premium positioning in concentrated solar power applications.
Industry Challenges
- Melting engineer talent scarcity:Specialized furnace operation expertise for low iron batch chemistry concentrates at legacy plants in Belgium and Japan, constraining greenfield operational readiness.
- BIS certification timeline compression:India's Bureau of Indian Standards testing protocols for construction-grade low iron glass extend 14-18 months, delaying market entry for new suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Iron Glass Market |
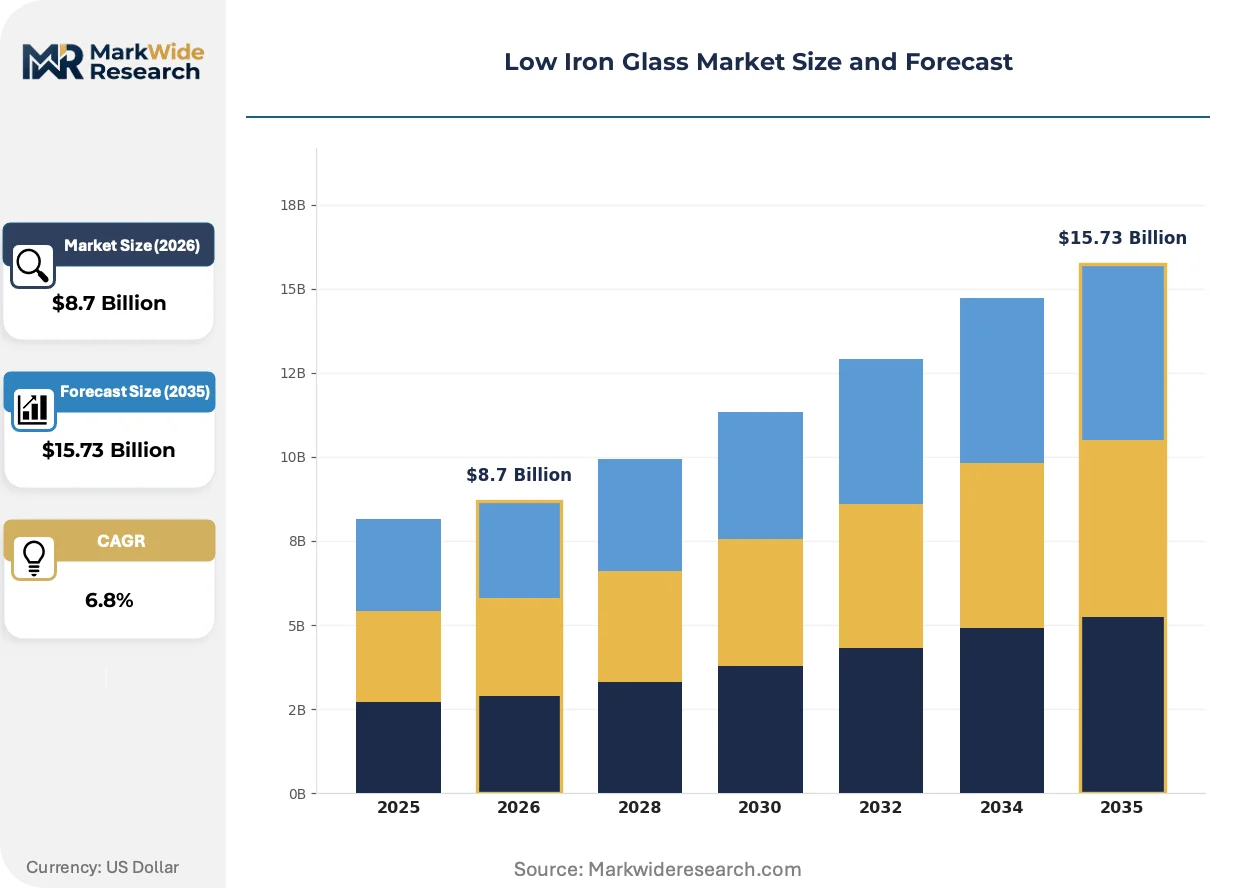
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Glass, Laminated Glass, Insulated Glass, Coated Glass End User: Construction, Automotive, Electronics, Solar Energy Application: Architectural, Automotive Glazing, Electronics Housing, Solar Panels Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Compagnie de Saint-Gobain S.A., AGC Inc., Xinyi Glass Holdings Limited, Guardian Glass, Nippon Sheet Glass Co., Ltd., Vitro, Schott AG, Corning Incorporated, Taiwan Glass Ind. Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Iron Glass Market Shifts & Advancements
Float glass manufacturing is experiencing simultaneous pressure from decarbonization mandates and photovoltaic efficiency targets, compressing process innovation cycles and redefining supplier qualification criteria.
Machine vision-based defect detection is automating quality assurance in low iron glass production lines. Solar panel manufacturers in China now mandate 100% surface inspection for micro-inclusions and thickness variation. This technology is automating the elimination of manual grading bottlenecks that previously constrained throughput at high-purity float plants.
REACH Annex XVII restrictions on nickel compounds in coated glass are forcing reformulation of anti-reflective layer chemistries. ECHA's 2023 update tightens occupational exposure limits during sputtering processes. German architectural glass processors are accelerating qualification of alternative metal oxide stacks to maintain CE marking compliance.
Direct module manufacturer procurement is displacing traditional flat glass distributor channels for solar-grade low iron supply. Long-term offtake agreements now span 5-7 years with price-volume collars. This pattern concentrates most visibly in China and India, where vertically integrated solar companies secure captive glass capacity through equity stakes or joint ventures.
Low Iron Glass Market Segmentation
Segmentation in low iron glass markets reveals how purity specifications, coating technologies, and procurement channels fragment competitive positioning. Manufacturers configure production lines around transmission thresholds and end-use certification requirements rather than generic glass grades.
Product Type:
Upgrade cycles in photovoltaic and architectural applications drive replacement demand toward higher-transmission variants as module efficiency targets tighten.
- Flat Glass:Manufactured through float processes with refined silica selection achieving iron oxide content below 0.05%. Solar panel manufacturers in China and India specify this substrate for crystalline silicon modules where base transmission exceeds 91% before coating.
- Coated Glass:Receives anti-reflective or conductive layer deposition through magnetron sputtering or sol-gel processes. German concentrated solar power developers and Dutch building-integrated photovoltaic architects pay premiums for nanostructured surface treatments pushing transmission past 94%.
- Laminated Glass:Combines low iron plies with interlayer films for safety and acoustic performance in high-rise façades.
- Insulated Glass:Integrates low iron panes into sealed units for thermal performance in commercial building envelopes.
Flat glass sits at the top of the volume ranking, with coated glass climbing the fastest.
End User:
Cost tier differentiation separates premium-certified supply chains from commodity-grade alternatives across regulated construction and unregulated industrial channels.
- Solar Energy:Module manufacturers prioritize light transmission gains to maximize energy conversion ratios in utility-scale deployments across China, India, and Germany. Long-term offtake agreements now span 5-7 years with direct procurement displacing traditional distributor relationships.
- Construction:Façade architects in Germany and the Netherlands specify low iron substrates for aesthetic transparency in commercial retrofits. EU Green Deal embodied carbon rules and REACH compliance harden procurement preference shifts toward certified supply chains.
- Electronics:Display and semiconductor equipment manufacturers demand electronics-grade substrates with specialized melting technology.
- Automotive:Premium vehicle glazing applications require optical clarity for heads-up display systems and panoramic roofs.
Solar energy commands the steepest expansion trajectory, while construction maintains the largest installed base.
Application:
Customer type fragmentation separates project-driven architectural procurement from continuous manufacturing demand in electronics and solar channels.
- Solar Panels:Crystalline silicon module production concentrates in China and India where vertically integrated manufacturers secure captive glass capacity. First Solar's cadmium telluride technology achieves comparable conversion efficiency without low iron superstrates, creating competitive pressure.
- Architectural:Commercial retrofit specifications in Germany and the Netherlands favor low iron glazing for daylighting optimization. Building-integrated photovoltaics penetration opens non-module revenue streams as façade systems integrate generation function.
- Automotive Glazing:Electric vehicle manufacturers specify low iron glass for weight reduction and optical performance in premium segments.
- Electronics Housing:Semiconductor and display equipment requires specialized substrates with minimal thermal expansion and high chemical durability.
Solar panels lead volume absorption, with architectural applications gaining share fastest in European commercial construction.
Distribution Channel:
Supply concentration among float glass producers with furnace assets in Belgium, Japan, and China shapes how channels capture margin.
- Direct Sales:Module manufacturers in China and India now procure 100% of solar-grade requirements through long-term contracts with price-volume collars. This pattern concentrates where vertically integrated solar companies secure captive capacity through equity stakes or joint ventures.
- Distributors:Construction-grade low iron glass moves through regional flat glass distributors for project-based architectural procurement. India's BIS certification timeline compression extends 14-18 months, delaying market entry for new supplier relationships.
- Online Retail:Specialty low iron glass for hobbyist electronics and small-scale solar projects.
- Others:Consortium purchasing for large infrastructure developments and government procurement frameworks.
Direct sales dominates solar channel volume, with distributor relationships contracting fastest as procurement consolidates among module manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized melting engineers concentrate in Belgium and Japan, constraining greenfield operational readiness for low iron glass production worldwide. Regional demand patterns follow photovoltaic deployment clusters and embodied carbon regulation stringency.
China
Vertically integrated solar manufacturers in Jiangsu and Anhui provinces drive procurement volume for crystalline silicon module substrates. The Ministry of Ecology and Environment enforces dual carbon targets that reshape energy-intensive glass manufacturing economics. Float glass producers in the Yangtze River Delta region are reconfiguring furnace fuel sources to meet compressed embodied carbon thresholds.
Germany
Façade architects in Berlin and Frankfurt specify low iron substrates for commercial retrofit daylighting optimization. The EU Green Deal Carbon Border Adjustment Mechanism tightens cost competitiveness for imported high-carbon glass alternatives. Concentrated solar power developers in Bavaria pay premiums for nanostructured surface treatments pushing transmission past 94%.
India
Module manufacturers in Gujarat and Tamil Nadu prioritize light transmission gains above 91% for utility-scale photovoltaic deployments. The Bureau of Indian Standards certification protocols for construction-grade low iron glass extend 14-18 months, delaying market entry. The PLI scheme for solar manufacturing incentivizes integrated low iron glass-to-module production clusters in these states.
United States
First Solar's cadmium telluride technology in Ohio achieves comparable conversion efficiency without low iron glass superstrates, creating competitive pressure. The EPA enforces emissions standards affecting float glass furnace operations nationwide. Specialty glass producers in the Midwest and Southeast face 8-12 year payback periods for natural gas-to-hydrogen furnace conversions.
Japan
Electronics-grade substrate demand from display and semiconductor equipment manufacturers anchors premium pricing. METI oversees industrial standards that favor specialized melting technology for high-purity applications. Legacy furnace operation expertise concentrates at established plants in the Chubu and Kansai regions, constraining capacity expansion.
Low Iron Glass Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across furnace assets and coating capabilities. The market structure concentrates among float glass producers with active furnace infrastructure in Belgium, Japan, and China. Three archetypes dominate: vertically integrated building materials conglomerates, photovoltaic substrate specialists, and electronics-grade purity providers. Competitive moves center on long-term offtake contracting with price-volume collars and equity stakes in captive glass capacity.
Among diversified conglomerates with multinational furnace networks, Compagnie de Saint-Gobain S.A. exemplifies the building materials archetype spanning raw silica to finished products. AGC Inc. and Schott AG occupy positions on the specialty substrate vector, with the former anchoring thin-film photovoltaic R&D intensity and the latter representing electronics-grade melting technology differentiation. These three entities collectively illustrate how purity specifications and end-use certification requirements fragment competitive positioning beyond generic glass grades.
| Leading Market Players |
|---|
| Compagnie de Saint-Gobain S.A. |
| AGC Inc. |
| Xinyi Glass Holdings Limited |
| Guardian Glass |
| Nippon Sheet Glass Co., Ltd. |
| Vitro |
| Schott AG |
| Corning Incorporated |
| Taiwan Glass Ind. Corp. |
| Others |
Supply & Pricing Matrix
Captive integration into high-purity silica sand deposits anchors supply security and pricing power for float glass manufacturers serving photovoltaic and architectural channels. China's dual carbon enforcement and the EU Green Deal carbon border adjustments are compressing cost curves for furnace fuel switching, reshaping how producers defend margin positions across transmission-grade tiers.
Pricing Analysis
Coated versus unbundled substrate sales split the market into divergent margin pools. Unprocessed flat glass trades on long-term offtake contracts with price-volume collars spanning five to seven years, while anti-reflective and conductive layer deposition commands premium positioning based on transmission thresholds exceeding 94%. Certification grade under BIS protocols and REACH compliance tiers drive price differentiation between solar-grade and architectural supply chains. Cost compression in standard flat glass is intensifying because First Solar's cadmium telluride technology bypasses low iron superstrates entirely. Module manufacturers in China and India exhibit highest price sensitivity due to vertical integration pressures, while concentrated solar power developers in Germany show lowest sensitivity for nanostructured surface treatments.
Supply Chain Analysis
Freight cost exposure concentrates around bulk silica sand movements from Australia and high-purity ore deposits in limited geographies to float plants in China, Belgium, and Japan. The supply chain draws from ultra-low iron silica deposits, natural gas or hydrogen furnace fuels, and magnetron sputtering equipment for coating lines. Single-source vulnerability in specialized melting engineer talent pools constrains greenfield operational readiness. Distribution runs through direct procurement channels displacing traditional flat glass distributors, particularly where vertically integrated solar companies secure captive capacity through equity stakes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low iron glass market functions as a stable compounder anchored by photovoltaic deployment acceleration under China's dual carbon goals and the EU Green Deal. Module efficiency imperatives above 91% transmission create durable demand tailwinds.
For Market Incumbents: Acquire furnace operation expertise concentrated in Belgium and Japan to secure melting engineer talent pools against greenfield constraints. Expand backward integration into high-purity silica sand offtake contracts to hedge input cost volatility. Defend against First Solar's cadmium telluride substitution threat by deepening anti-reflective coating R&D partnerships with concentrated solar power developers. For New Entrants and Emerging Players: Capture building-integrated photovoltaics penetration in German and Dutch commercial retrofit markets where aesthetic transparency specifications favor new supply relationships. Target India's PLI scheme incentive windows for integrated glass-to-module clusters in Gujarat and Tamil Nadu. Pursue joint venture structures with established float glass producers to bypass BIS certification timeline compression. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized melting technology concentrates in legacy plants with constrained capacity expansion. Frame five-to-ten year viability around solar energy conversion efficiency gains and embodied carbon regulation tightening. Prioritize acquisition targets with electronics-grade purity capabilities and existing REACH certification. Watch cadmium telluride efficiency improvements as inflection signal for crystalline silicon module demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Fuel-Switching Investment | Natural gas-to-hydrogen conversions align with MEE dual carbon enforcement in China's Yangtze River Delta. |
| Backward Integration into Silica Sand | Captive ore deposits insulate against ultra-low iron scarcity and long-term offtake renegotiation exposure. |
| Anti-Reflective Coating Partnership | Nanostructured surface treatments enable 94%+ transmission premiums in German concentrated solar power. |
| BIS Certification Fast-Track | Accelerated testing protocols reduce India's 14-18 month construction-grade approval barriers for new entrants. |
| Direct Procurement Contracting | Long-term offtake agreements with price-volume collars displace distributor channels in China and India. |
Research Methodology
Multiple input streams — primary interviews with float glass plant managers, solar module procurement leads, and façade architects; secondary validation through customs data, SEC filings, and ECHA regulatory updates; plus technical R&D director surveys — were reconciled to construct segment-level demand estimates. Bottom-up capacity assessments at furnace assets in Belgium, Japan, and China were triangulated against top-down photovoltaic deployment projections. Stakeholder roles engaged included melting engineers, BIS certification specialists, and EU Green Deal compliance officers.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled encompassed product type purity tiers, end-use certification requirements, coating technology complexity, and regional regulatory stringency clusters. CAGRs were derived from installed base replacement cycles and efficiency upgrade trajectories. Forecast inputs incorporated furnace fuel-switching capex payback periods and machine vision quality assurance adoption curves.
Underlying measurement precision varies by segment; solar energy end-use carries tighter precision than emerging electronics housing applications due to more transparent procurement data. Forecasts reflect assumptions around photovoltaic deployment continuity and carbon border adjustment implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Decorative Glass Market
Glass
United States Flat Glass Market
Glass
Impact Resistant Glass Market
Glass
Global Anti-Reflective Glass Market
Glass
Global Glassware Market
Glass
Global Silicone Structural Glazing Market
Glass
Crystalware and Glassware Market
Glass
Europe Flat Glass Market
Glass
Laboratory Glassware Market
Glass
Glass Prepreg Market
Glass
UAE Silica Sand Market
Glass
Global Laminated Glass Market
Glass
Mirrored Glass Market
Glass
Solar Reflective Glass Market
Glass
Glass Forming Machine Market
Glass
Float Glass Market