
 Europe Flat Glass Market | 2026-2036
Europe Flat Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Flat Glass Market Intelligence
CE marking under the Construction Products Regulation is redrawing competitive boundaries for flat glass suppliers serving the European Economic Area. Saint-Gobain S.A. leverages its integrated float glass and coating technology platform to dominate premium architectural specifications across Western Europe. Guardian Glass anchors its position through captive raw material access and advanced low-emissivity product lines tailored to Nordic and Central European climates. Euroglas GmbH specializes in high-volume tempered and laminated outputs for automotive OEM supply chains concentrated in Germany and Eastern Europe.
Flat glass consists of soda-lime silica sheets produced primarily through the float process, where molten glass flows across a tin bath to achieve uniform thickness and optical clarity for architectural glazing, automotive windshields, and display substrates. Low-E glass commands expanding share as energy efficiency mandates tighten across European building codes, while tempered glass sustains its volume lead through safety-critical applications in construction and transportation. Laminated glass differentiates on acoustic and security performance, capturing premium positioning in urban commercial developments and electric vehicle panoramic roof systems.
The EU Green Deal, REACH chemicals framework, and national building regulations such as Germany's EnEV and France's RE2020 environmental code collectively mandate progressive reductions in building operational energy, directly translating to upgraded glazing specifications in renovation and new construction. ECHA oversight of substances used in glass coatings and interlayers shapes formulation choices and supplier qualification timelines. Stakeholders must track the interplay between evolving EPBD implementation timelines and automotive lightweighting requirements to align capacity investments with the most durable demand pools.
Market Dynamics
EU Green Deal implementation is compressing renovation timelines across member states, forcing simultaneous upgrades to building envelopes and glazing specifications that previously cycled independently. This regulatory synchronization is restructuring demand patterns for flat glass producers serving construction value chains.
Growth Catalysts
- Building energy performance mandates:Germany's EnEV and France's RE2020 environmental code mandate progressive thermal efficiency upgrades, directly expanding specification of low-emissivity and triple-glazing configurations in renovation projects.
- Automotive lightweighting:Electric vehicle manufacturers across Germany, France, and Italy are specifying thinner, chemically-strengthened glass substrates to offset battery weight while maintaining structural integrity for panoramic roof systems.
- Industrial cluster concentration:Float glass production facilities anchored in Belgium, Germany, and Italy provide feedstock proximity to automotive OEM assembly plants and major metropolitan construction markets.
Market Restraints
- Natural gas price volatility:Float glass melting operations depend heavily on natural gas, exposing producers to input cost swings driven by European energy market dislocations and supply security concerns.
- Raw material supply concentration:High-purity silica sand and soda ash sourcing concentrates among limited suppliers in specific geographies, creating vulnerability to logistics disruptions or export restrictions.
- Coating chemistry constraints:ECHA oversight of substances used in sputtered and pyrolytic coatings extends qualification timelines and restricts formulation flexibility for performance glass lines.
Strategic Opportunities
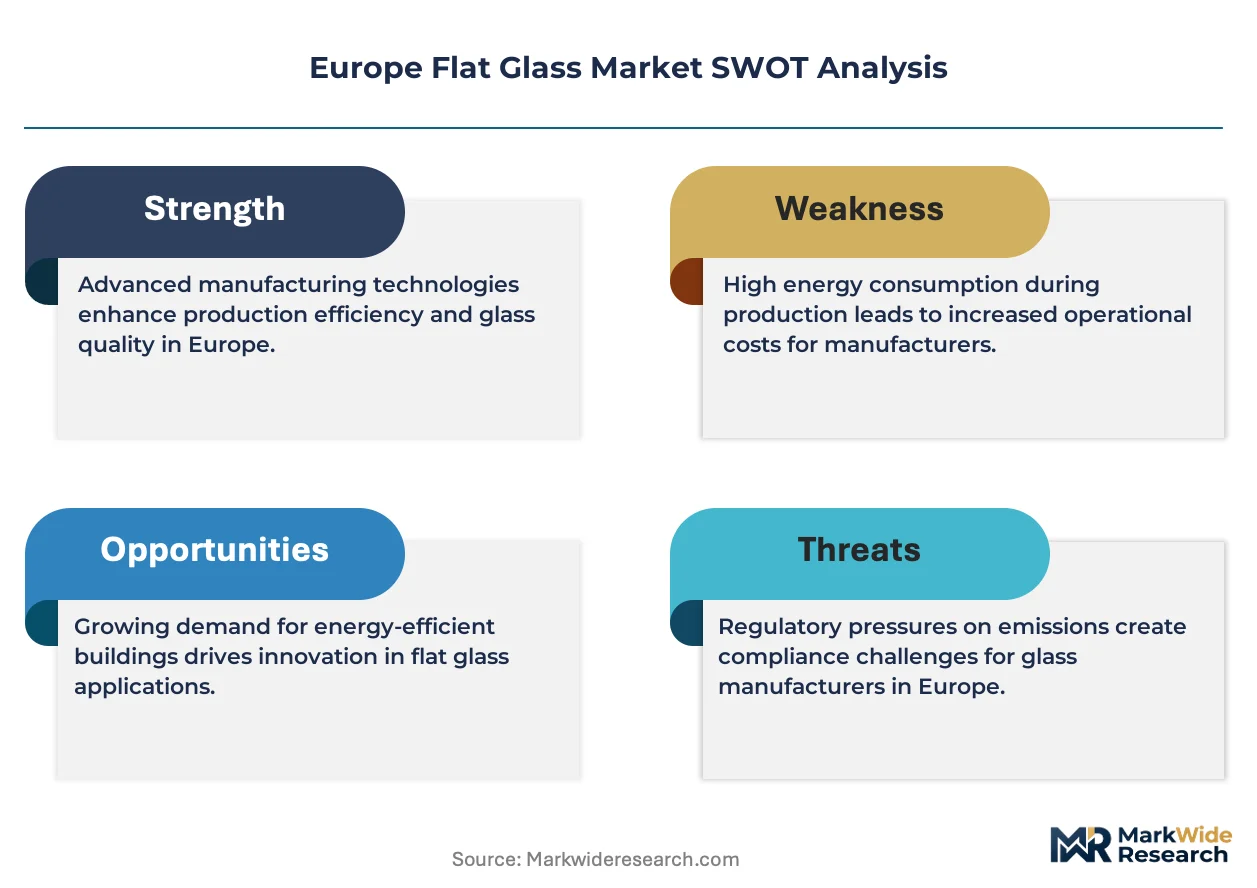
- Building-integrated photovoltaics:Semi-transparent photovoltaic glazing represents an emerging application where flat glass substrates serve dual structural and energy-generation functions in commercial facades.
- Eastern European renovation wave:Poland, Czech Republic, and Romania present underpenetrated markets where EU cohesion funds are accelerating building stock modernization and glazing replacement cycles.
- Circular glass recovery:End-of-life building glass recycling infrastructure remains fragmented, creating first-mover advantage for producers establishing closed-loop cullet supply agreements with demolition contractors.
Industry Challenges
- Specialized coating technician scarcity:Vacuum deposition and chemical vapor deposition processes require skilled operators that competing semiconductor and solar industries also target, tightening labor markets.
- CE marking certification timelines:Construction Products Regulation compliance for novel glazing assemblies involves extended testing protocols that delay product commercialization and revenue recognition.
- Float line conversion capex:Shifting production between architectural thicknesses and automotive specifications requires substantial furnace and tin bath modifications that strain capital allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Flat Glass Market |
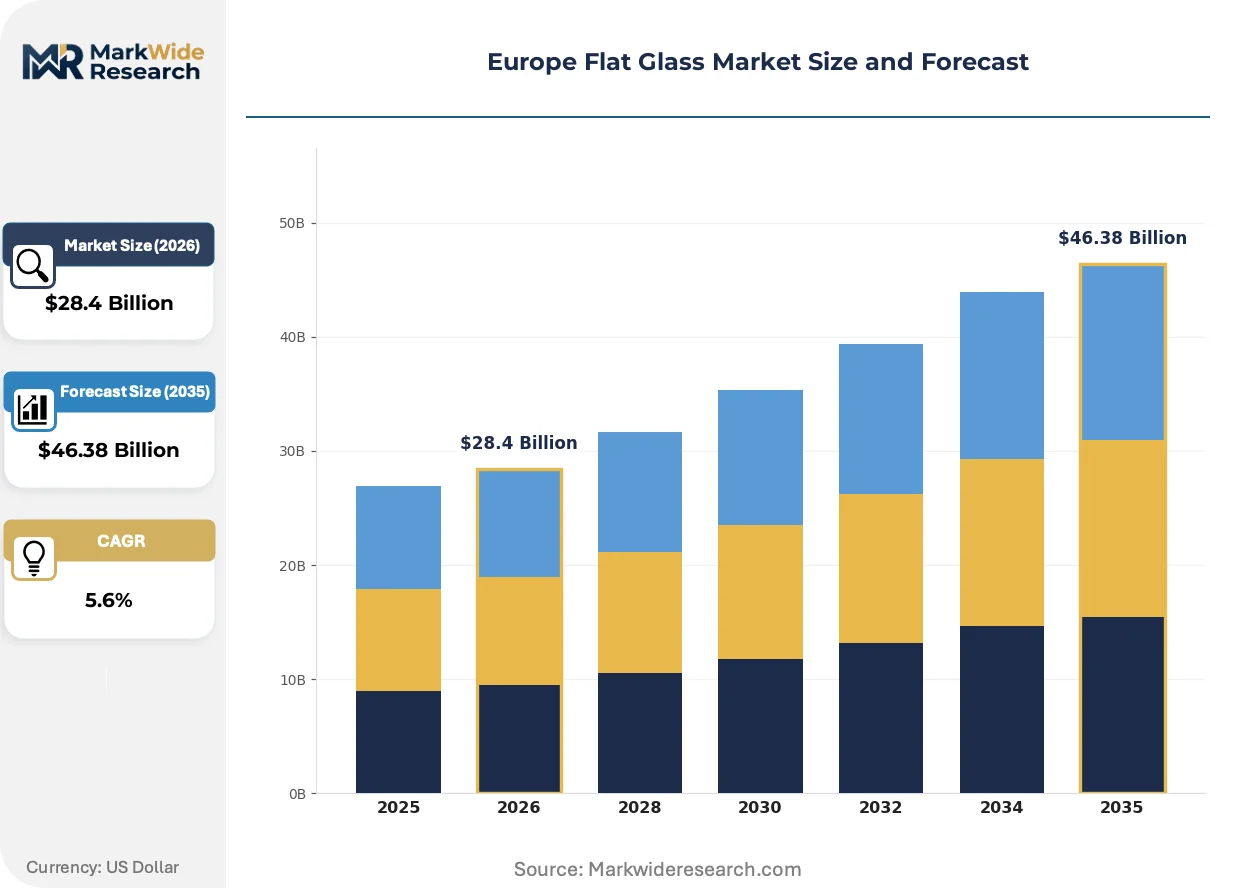
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $46.38 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Coated Glass, Low-E Glass Application: Construction, Automotive, Electronics, Furniture End User: Architects, Contractors, Manufacturers, Retailers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Guardian Glass, Euroglas GmbH, Saint-Gobain S.A., Schott AG, Nippon Sheet Glass Co., Ltd., AGC Inc., Şişecam Group, Cardinal Glass Industries, NSG Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Flat Glass Market Strategic Shifts & Innovations
Electrochromic and thermochromic glazing technologies are transitioning from premium commercial installations toward broader residential and transportation applications, compressing traditional static low-E product lifecycles. These active control systems are forcing recalibration of R&D priorities across European flat glass value chains.
Vacuum-insulated glass units are decomposing the thermal performance hierarchy that separated triple-glazing from double-glazing markets. Scandinavian window manufacturers are adopting these ultra-thin, high-R-value assemblies for heritage building renovations where frame depth constraints prohibit conventional multi-pane solutions. This technology is decomposing the traditional trade-off between thermal performance and architectural aesthetics that governed specification decisions for decades.
REACH chemicals framework revisions are tightening scrutiny of fluorinated compounds used in hydrophobic and oleophobic surface treatments for automotive and display glass. Industrial consequences include accelerated reformulation programs and supplier qualification delays for coating chemical providers. Automotive glazing divisions serving German OEMs are most affected, responding by shifting toward sol-gel and plasma-enhanced chemical vapor deposition alternatives with simpler substance registration pathways.
Consolidation among European fenestration fabricators is compressing buyer concentration at the distribution tier, altering negotiation leverage for volume contract terms. Independent window and door manufacturers in France and Italy are being absorbed by building materials conglomerates seeking vertical control over specification channels. This pattern is most visible in commercial construction verticals where project-scale procurement now flows through fewer, larger intermediaries with standardized technical requirements.
Europe Flat Glass Market Segmentation
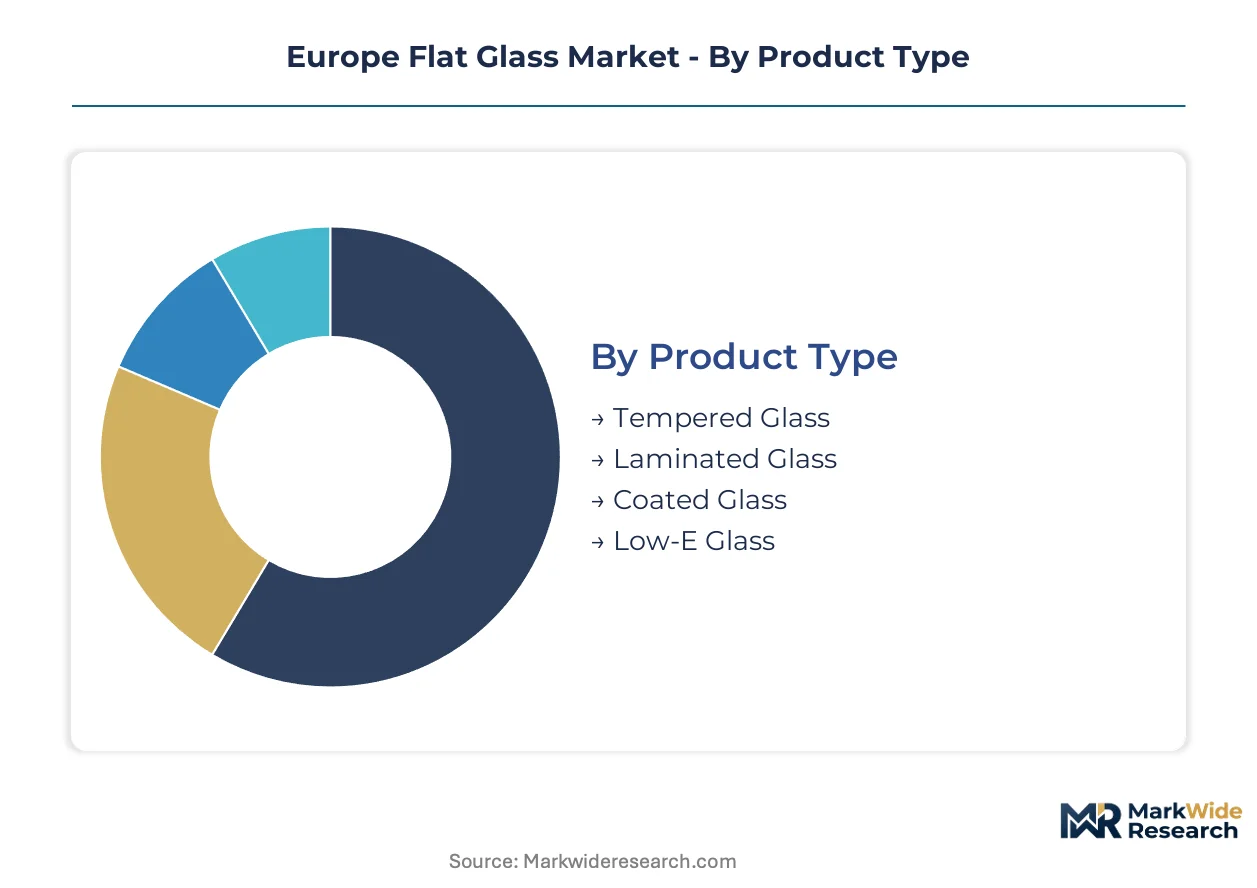
Flat glass segmentation in Europe reflects divergent technical requirements across building codes, automotive specifications, and fabrication workflows. Product categories align with distinct regulatory pathways under CE marking and REACH, while application segments track renovation cycles versus OEM production schedules.
Product Type:
Domestic float production in Belgium, Germany, and Italy supplies architectural grades, while specialized coated variants increasingly serve export markets to Nordic and Eastern European construction projects.
- Tempered Glass:Heat-treated soda-lime silica with compressive surface layers that shatter into granular fragments rather than sharp shards. German automotive OEMs in Bavaria and Baden-Württemberg specify tempered side and rear windows for crash safety compliance, though natural gas price volatility compresses margin on high-volume furnace runs.
- Coated Glass:Sputtered or pyrolytic metal oxide layers applied to float substrates for solar control and aesthetic effects. Italian facade contractors in Milan and Rome favor reflective coatings for commercial towers, but ECHA substance reviews extend qualification timelines for new formulation introductions.
- Laminated Glass:Polyvinyl butyral interlayers bond glass plies for acoustic damping and post-breakage retention. French acoustic regulations in dense urban zones sustain specification for residential and hospital projects.
- Low-E Glass:Microscopically thin silver layers reduce thermal emissivity for building envelope efficiency. Mandatory under Germany's EnEV and France's RE2020 for new construction and major renovations.
Tempered glass holds the largest share; momentum sits with Low-E configurations as EU Green Deal implementation tightens.
Application:
Construction absorbs the majority of flat glass volume, though automotive and electronics segments command premium pricing tiers due to tighter dimensional tolerances and coating complexity.
- Construction:Architectural glazing for facades, curtain walls, and residential windows. German renovation cycles in the Rhine-Ruhr corridor and new commercial development in Paris La Défense concentrate demand for high-performance insulating units.
- Automotive:Windshields, side windows, and panoramic roof systems for passenger and commercial vehicles. Electric vehicle production clusters in Stuttgart, Wolfsburg, and Turin specify chemically-strengthened thin glass for battery weight offset.
- Electronics:Display substrates for industrial monitors, automotive infotainment, and medical equipment. Cleanroom fabrication requirements limit supplier qualification to Belgian and German coating specialists.
- Furniture:Tabletops, shelving, and interior partition systems. Italian design manufacturers in Lombardy drive specification for acid-etched and colored decorative variants.
Construction dominates volume; automotive applications are climbing the fastest as lightweighting mandates intensify.
End User:
Specification authority concentrates with architects and contractors in commercial construction, while manufacturers control automotive and electronics procurement through multi-year supply agreements.
- Architects:Design-phase specification of glazing performance criteria, thermal transmittance targets, and aesthetic treatments. French and Dutch practices increasingly mandate whole-life carbon assessments for material selection.
- Contractors:Procurement execution and installation coordination for building envelope packages. German general contractors face compressed renovation timelines under EU Green Deal national implementation plans.
- Manufacturers:Fenestration fabricators, automotive Tier 1 suppliers, and electronics assembly operations. Consolidation among French and Italian window manufacturers is reducing buyer fragmentation.
- Retailers:DIY channels and small-scale residential replacement glazing. Polish and Romanian retail networks are expanding as home improvement spending rises.
Architects and contractors jointly control the largest specification share; manufacturers are gaining procurement leverage through volume consolidation.
Distribution Channel:
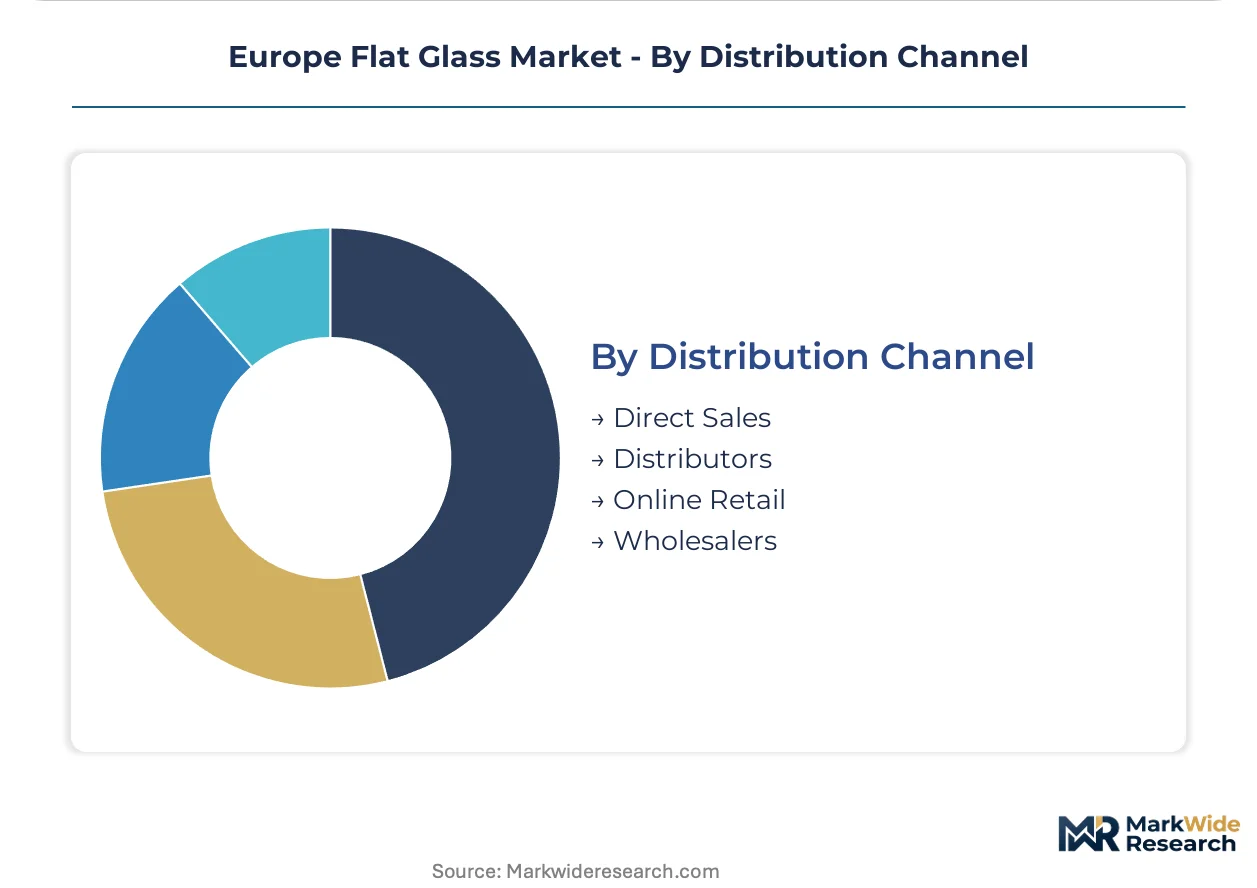
Direct sales relationships dominate automotive and large commercial projects, while distributor networks sustain fragmented residential and small-contractor access across dispersed geographies.
- Direct Sales:Producer-to-fabricator relationships for high-volume, specification-intensive orders. Saint-Gobain and Guardian Glass maintain dedicated account teams for major German automotive OEMs and French construction groups.
- Distributors:Regional stocking intermediaries serving independent window manufacturers and glazing contractors. Networks concentrate in Northern Italy and the Benelux for cross-border supply efficiency.
- Wholesalers:Bulk volume handlers supplying large construction merchants and retail chains. Eastern European markets in Poland and Czech Republic show expanding wholesale infrastructure.
- Online Retail:Emerging channel for standardized cut-to-size and replacement glazing. Limited penetration outside residential DIY segments due to freight fragility and specification complexity.
Direct sales capture the highest value per ton; distributor networks are expanding most quickly into Eastern European catchment areas.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal national implementation plans are synchronizing renovation timelines across member states, compressing demand cycles for high-performance glazing in building envelopes. Member states deploy cohesion funds and national efficiency programs to accelerate building stock modernization. Industrial float glass capacity concentrates near automotive assembly clusters and metropolitan construction corridors.
Germany
Renovation cycles in the Rhine-Ruhr corridor and Bavarian commercial development sustain demand for triple-glazing and low-emissivity configurations. Germany's EnEV mandates progressive thermal efficiency upgrades for new construction and major renovations. Stuttgart and Wolfsburg automotive clusters specify chemically-strengthened thin glass for electric vehicle panoramic roof systems.
France
Paris La Défense commercial towers and dense urban residential zones drive specification of laminated acoustic glass. France's RE2020 environmental code mandates whole-life carbon assessments and upgraded glazing performance in new buildings. Milan-facing facade contractors in Lyon and Marseille favor reflective coated variants for commercial developments.
Italy
Lombard design manufacturers and Milan commercial construction sustain demand for acid-etched and colored decorative glass. EU Green Deal implementation compresses renovation timelines for building envelope upgrades. Turin automotive production clusters intersect with float glass feedstock from nearby Italian melting facilities.
Belgium
Float glass production facilities anchor supply chains serving cross-border markets in the Benelux and Northern France. REACH chemicals framework oversight shapes coating formulation choices for architectural and automotive applications. Antwerp and Ghent industrial zones concentrate melting capacity with river transport access to German and French construction markets.
Poland
EU cohesion funds accelerate building stock modernization in Warsaw and Krakow, expanding glazing replacement cycles. National building regulations align with EPBD implementation timelines for progressive efficiency upgrades. Emerging wholesale distribution networks serve independent window manufacturers across Eastern European catchment areas.
Europe Flat Glass Market Key Industry Players
Player mix skews toward integrated multinationals with captive float capacity and coating technology platforms. Market structure concentrates around three to four producers commanding premium architectural specifications and automotive supply chains. Strategic archetypes include integrated float-to-coating specialists, automotive-focused tempering and laminating fabricators, and regional distributors with specification influence. Dominant competitive moves encompass furnace technology licensing partnerships and selective capacity expansion into Eastern European renovation markets.
Among France-based integrated producers, Saint-Gobain S.A. exemplifies the float-to-coating archetype with architectural specification dominance across Western Europe. Guardian Glass anchors the premium low-emissivity tier through advanced product lines tailored to Nordic and Central European climates. Euroglas GmbH occupies a position within the automotive supply chain specialist tier, serving OEM production clusters concentrated in Germany and Eastern Europe.
| Leading Market Players |
|---|
| Guardian Glass |
| Euroglas GmbH |
| Saint-Gobain S.A. |
| Schott AG |
| Nippon Sheet Glass Co., Ltd. |
| AGC Inc. |
| Şişecam Group |
| Cardinal Glass Industries |
| NSG Group |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day float glass order backlogs in Germany and Belgium concentrate pricing power with integrated producers possessing captive melting capacity, while natural gas price indexation clauses in annual supply contracts transmit input volatility directly to architectural glazing quotes across the Rhine-Ruhr corridor.
Pricing Analysis
Cost-plus contracts indexed to TTF natural gas benchmarks dominate long-term supply agreements between Belgian float producers and German fenestration fabricators. Three-tier pricing structure across premium low-E, standard coated, and uncoated architectural grades separates specification-intensive commercial projects from commodity residential replacement volume. Cost compression in standard float tiers is intensifying because Eastern European capacity additions expand regional supply availability. Independent window manufacturers in Poland and Czech Republic exhibit highest price sensitivity, while Paris La Défense commercial developers prioritize thermal performance over unit cost differentials.
Supply Chain Analysis
Inventory cycles stretching eight to twelve weeks for soda ash and high-purity silica sand expose flat glass producers to logistics disruptions across North Sea and Baltic shipping lanes. Melting capacity concentrates in Belgium, Germany, and Italy, drawing from Norwegian coastal silica deposits and Turkish soda ash refineries. Single-source vulnerability characterizes specialty coating chemical supply, where ECHA substance registrations limit qualified interlayer and sputtering target vendors. Distribution runs through direct sales relationships for automotive OEM supply chains and regional distributor networks serving fragmented residential glazing contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around CE marking and ECHA substance compliance creates defensive moats for established European flat glass producers, as qualification timelines and coating chemistry registrations lock out unqualified competitors from premium architectural specifications.
For Market Incumbents: Shield market position by deepening captive cullet recycling infrastructure in demolition-heavy German renovation corridors and accelerating low-E coating capacity conversion ahead of France RE2020 implementation deadlines. Vertical integration into pyrolytic coating chemistry formulation reduces ECHA registration dependency and protects margin from specialty chemical supplier concentration. For New Entrants and Emerging Players: Anchor in Eastern European renovation markets where EU cohesion fund deployment outpaces established distributor coverage, particularly Warsaw and Krakow commercial building envelope upgrades. Building-integrated photovoltaics glazing represents the most penetrable white-space segment, with semi-transparent photovoltaic substrates commanding premium positioning absent entrenched supplier relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from building materials conglomerates seeking to divest non-core glass fabrication assets amid fenestration consolidation pressure. Long-term viability hinges on coating technology differentiation and circular cullet supply agreements rather than commodity float capacity. Watch for inflection signals in German EnEV enforcement intensity and natural gas price stabilization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Float Line Coating Conversion | Enables low-E capacity expansion serving Germany's EnEV-mandated renovation wave. |
| Circular Cullet Recovery Partnerships | Secures feedstock advantage through demolition contractor agreements in dense urban zones. |
| Eastern European Distribution Expansion | Captures EU cohesion fund-driven glazing replacement cycles in Poland and Czech Republic. |
| Automotive Lightweighting R&D Alliance | Develops chemically-strengthened thin glass for Stuttgart and Wolfsburg electric vehicle programs. |
| Building-Integrated Photovoltaics Pilot | Positions semi-transparent photovoltaic glazing for Paris and Milan commercial facade specifications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with plant managers at Belgian and German float facilities, procurement leads at French fenestration fabricators, and specification directors at Milan and Paris architectural practices. Secondary validation drew from ECHA substance registration databases, EU Green Deal national implementation progress reports, and customs trade data tracking soda ash and silica sand import flows. Bottom-up volume estimates from coating line utilization rates were triangulated against top-down construction spending projections across the analysis window.
Across the modeling period, segmentation dimensions included product type, application vertical, end-user specification authority, and distribution channel structure. CAGRs were derived from regression analysis against building permit issuance, automotive production schedules, and energy efficiency regulatory tightening trajectories. Forecast inputs incorporated natural gas price scenario bands and EPBD implementation timeline assumptions for member state renovation program acceleration.
Material uncertainties — energy market dislocations, ECHA substance restriction expansions, and EU cohesion fund allocation shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and automotive lightweighting adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Glass Grade Dolomite Market
Glass
United States Flat Glass Market
Glass
Crystalware and Glassware Market
Glass
East Africa Flat Glass Market
Glass
Insulated Glass Market
Glass
Low-E Glass Market
Glass
Global Anti-Reflective Glass Market
Glass
Asia-Pacific Flat Glass Market
Glass
Pharma Glass Tubing Market
Glass
Glass Lens Market
Glass
Shatterproof Glass Market
Glass
Glass Lined Equipment Market
Glass
Paper Glass Maker Market
Glass
Glass Mason Jars Market
Glass
Asia Pacific Flexible Glass Market
Glass
Mexico Flat Glass Market