
 Impact Resistant Glass Market | 2026-2036
Impact Resistant Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Impact Resistant Glass Market Outlook
Multi-ply laminated specifications with enhanced interlayer bonding is rotating the market upward as architects and vehicle OEMs trade basic tempered units for engineered safety assemblies. Saint-Gobain leverages captive interlayer chemistry capabilities across its European float lines. AGC Inc. anchors Asian supply through integrated soda ash-to-glass operations in Japan and Southeast Asia. Guardian Industries dominates North American architectural specification channels with tempered-laminated hybrid portfolios.
Impact resistant glass consists of monolithic or composite assemblies engineered to absorb kinetic energy through controlled fracture patterns, typically incorporating polyvinyl butyral or ionoplast interlayers between annealed or heat-strengthened lites, with thickness configurations ranging from 6 mm to 15 mm depending on threat-level ratings. Its primary purpose spans occupant retention in automotive rollover events, forced-entry delay in commercial facades, and debris containment in hurricane-zone construction. Laminated glass captures the dominant value share as building codes in coastal US jurisdictions mandate missile-impact ratings for exterior glazing. Tempered glass competes on cost in automotive side-lite applications where fragment control suffices. Polycarbonate segments serve aerospace transparencies where weight reduction overrides optical clarity premiums.
FDA oversight of glass packaging for pharmaceutical applications intersects with NHTSA Federal Motor Vehicle Safety Standard 205 and ECE R43 in shaping product-level certification requirements across automotive and medical end uses. OSHA workplace safety directives and evolving International Building Code wind-borne debris provisions further segment demand by installation geography and liability exposure. Stakeholders must monitor interlayer material cost volatility and regional code harmonization timelines to calibrate capacity allocation between architectural and transportation verticals.
Market Dynamics
Automotive OEMs are forcing laminated glass thickness upward as rollover safety standards harden, compressing tempered glass share in windscreen applications while architectural codes in hurricane zones mandate multi-ply configurations for debris resistance.
Growth Catalysts
- ECE R43 Evolution:The UN R43 standard revision tightens windscreen integrity benchmarks, compelling European OEMs to adopt thicker interlayer bonding in premium vehicle glazing.
- Coastal Building Codes:Missile-impact rating mandates in US hurricane-zone jurisdictions drive laminated glass specification for commercial facades and residential construction.
- Interlayer Chemistry Advances:Ionoplast formulations with enhanced shear modulus are displacing conventional PVB in high-threat automotive and architectural applications.
Market Restraints
- Butyral Resin Volatility:Polyvinyl butyral feedstock costs fluctuate with acetic acid and polyvinyl alcohol supply, compressing laminator margins during price spikes.
- Float Line Concentration:High-quality annealed glass substrate supply concentrates among integrated European and Asian producers, creating bottleneck risk for independent laminators.
- Polycarbonate Substitution:Aerospace and weight-critical automotive segments increasingly specify transparent polycarbonate transparencies where optical clarity trade-offs are acceptable.
Strategic Opportunities
- Indian Infrastructure Buildout:Metro rail expansion and commercial real estate growth in Mumbai and Delhi create specification channels for laminated safety glazing.
- Smart Glass Convergence:Integration of electrochromic and suspended particle device layers with impact-resistant substrates opens premium architectural retrofit markets.
- IRA Clean Energy Credits:US federal incentives for energy-efficient building envelopes accelerate demand for high-performance laminated glazing in commercial construction.
Industry Challenges
- Interlayer Bond Certification:Extended qualification timelines for new adhesive chemistries under ECE R43 and NHTSA FMVSS 205 delay product launches by 18-24 months.
- Laminated Tempering Integration:Combining heat-strengthened lites with compliant interlayers requires capital-intensive furnace reconfiguration at existing float operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impact Resistant Glass Market |
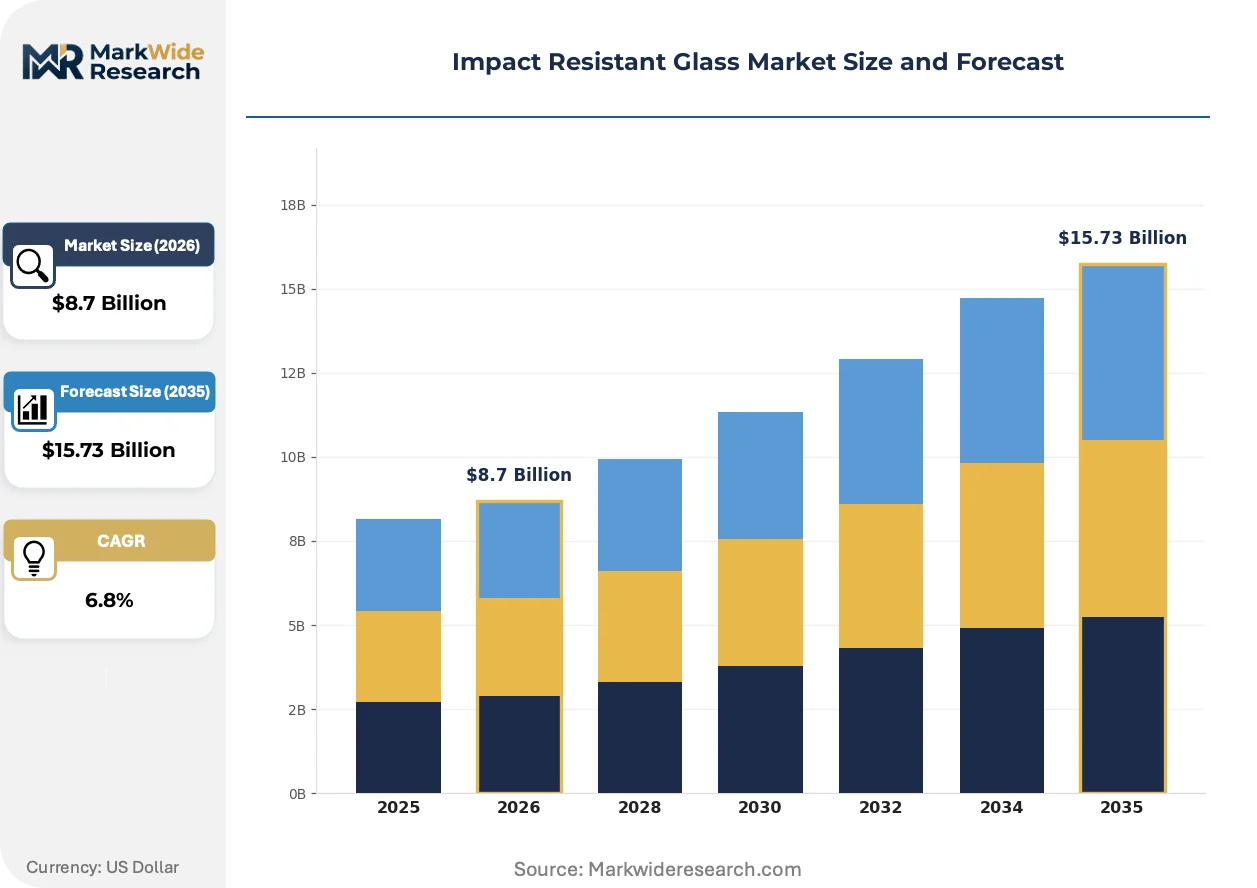
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Laminated Glass, Tempered Glass, Acrylic Application: Automotive, Construction, Electronics, Aerospace Thickness: 6 mm, 10 mm, 12 mm, 15 mm End User: Architects, Manufacturers, Vehicle OEMs, Retailers |
| Companies Covered | Saint-Gobain, AGC Inc., Nippon Sheet Glass Co., Ltd., Guardian Industries, Vitro, Sisecam Group, Central Glass, Taiwan Glass, CGS Holding Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impact Resistant Glass Market Strategic Shifts
Material science breakthroughs are compressing interlayer thickness while maintaining energy absorption, enabling lighter automotive glazing assemblies without sacrificing rollover integrity ratings.
Structural ionoplast interlayers are miniaturizing from conventional 1.52 mm configurations to sub-millimeter gauges while retaining penetration resistance. German premium OEMs in Stuttgart and Munich assembly corridors are qualifying these reduced-thickness laminates for panoramic roof applications. This compression is miniaturizing the weight penalty differential between laminated and monolithic tempered alternatives in side-lite positions.
REACH restrictions on phthalate plasticizers are forcing reformulation of conventional PVB interlayers across European laminator operations. The industrial consequence is accelerated qualification of non-phthalate ionoplast alternatives with superior moisture stability. Automotive windscreen applications in Germany face the tightest compliance timelines, with OEMs requiring full supply chain certification by 2026.
Specification authority is consolidating among facade engineering consultants who bundle glazing performance guarantees with structural calculations. This channel shift displaces direct architect-manufacturer relationships in US commercial construction, particularly in Miami-Dade County where hurricane code enforcement is most stringent. Procurement teams now prioritize single-source accountability over component-level supplier diversity.
Impact Resistant Glass Market Segmentation
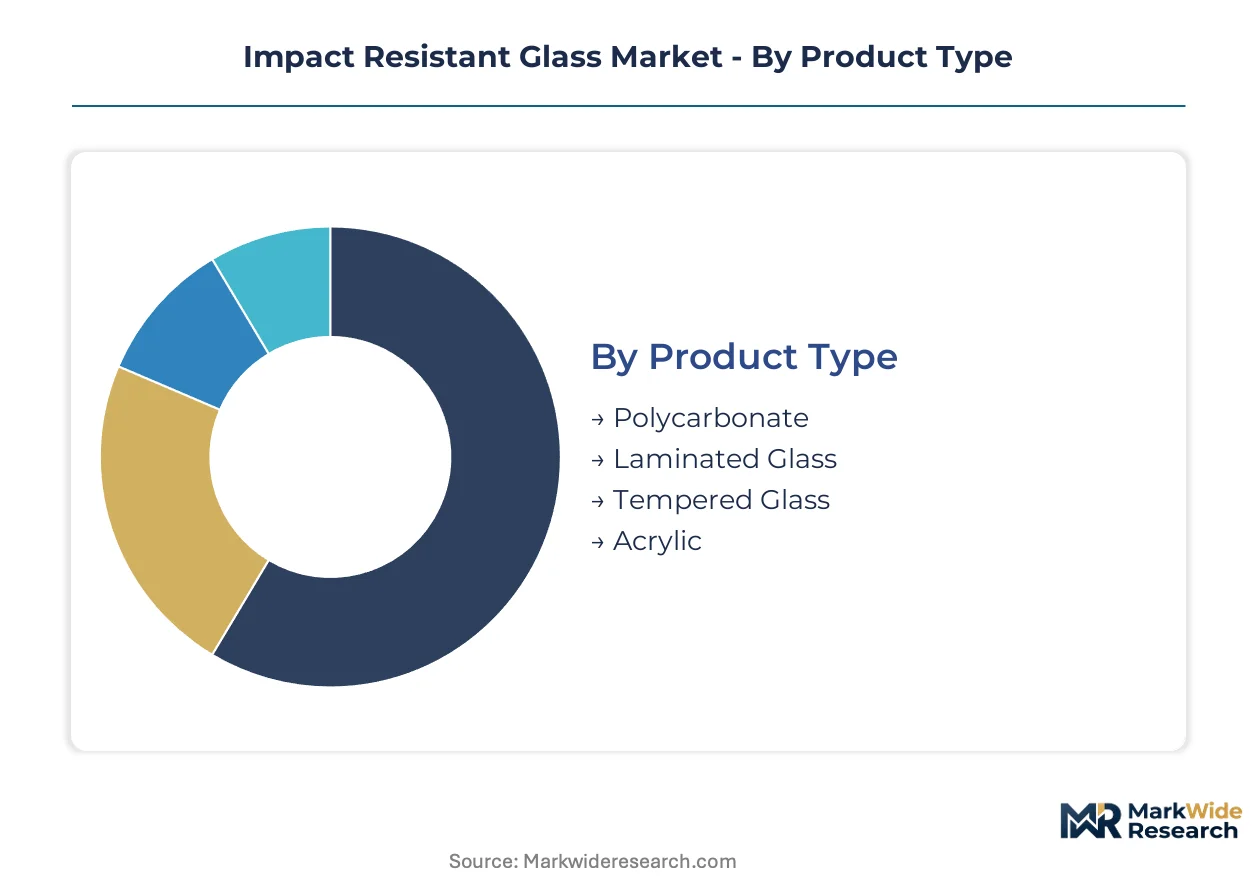
Impact resistant glass segmentation reveals divergent substitution economics across material chemistries and end-use specifications. Product-level differentiation determines whether laminators capture premium architectural contracts or cede volume to polycarbonate and acrylic alternatives.
Product Type:
Polycarbonate and acrylic alternatives exert the strongest substitution pressure on conventional glass formulations in weight-critical and optical-flexibility applications.
- Laminated Glass:Multi-ply assemblies bond annealed or heat-strengthened lites with PVB or ionoplast interlayers. German premium vehicle production clusters specify thicker configurations for rollover integrity under ECE R43. Coastal US building codes mandate missile-impact ratings that only laminated constructions satisfy.
- Tempered Glass:Monolithic units undergo controlled thermal treatment to create surface compression and edge tension. Automotive side-lite applications absorb volume where fragment control suffices and cost sensitivity dominates OEM sourcing decisions.
- Polycarbonate:Transparent thermoplastic sheets deliver ballistic resistance at half the weight of glass equivalents. Aerospace transparencies specify these units where optical clarity trade-offs are operationally acceptable.
- Acrylic:Polymethyl methacrylate formulations compete on cost in display protection and non-structural glazing. Retail fixture manufacturers specify these for impact resistance without load-bearing requirements.
Laminated glass anchors the volume base while polycarbonate gains share at the steepest rate in aerospace and weight-critical automotive niches.
Application:
Automotive and construction verticals concentrate specification authority among distinct buyer types with divergent certification requirements.
- Automotive:Windscreen and panoramic roof applications drive interlayer thickness upward as NHTSA FMVSS 205 and ECE R43 tighten rollover safety benchmarks. Stuttgart and Munich assembly corridors qualify reduced-thickness ionoplast laminates to minimize weight penalties.
- Construction:Commercial facades and residential glazing in hurricane zones absorb multi-ply laminated configurations. Miami-Dade County enforcement creates specification channels where missile-impact ratings are mandatory.
- Electronics:Display protection and device enclosure applications prioritize optical clarity and scratch resistance. Touchscreen manufacturers specify chemically strengthened glass or hybrid laminates.
- Aerospace:Cockpit transparencies and cabin window assemblies demand weight-optimized solutions. Transparent polycarbonate and advanced acrylic formulations displace glass in military and commercial aviation programs.
Construction commands the installed value base while automotive applications expand most quickly through regulatory-driven thickness upgrades.
Thickness:
Specification thickness maps directly to threat-level ratings and end-use liability exposure across transportation and architectural codes.
- 6 mm:Entry-level laminated and tempered units serve interior partitions and non-structural automotive applications. Cost-sensitive procurement favors these specifications where impact ratings are discretionary.
- 10 mm:Mid-range configurations balance penetration resistance with weight constraints. European OEMs specify these for side-lite positions where ECE R43 fragment control suffices.
- 12 mm:Enhanced interlayer bonding at this gauge meets large missile-impact ratings for coastal US commercial construction. Facade engineering consultants specify these for single-source accountability guarantees.
- 15 mm:Maximum threat-level ratings require these heavy-gauge assemblies. Automotive windscreens for premium German OEMs and hurricane-zone structural glazing absorb this specification tier.
10 mm and 12 mm specifications dominate current volume while 15 mm gauges climb fastest through code harmonization and safety standard escalation.
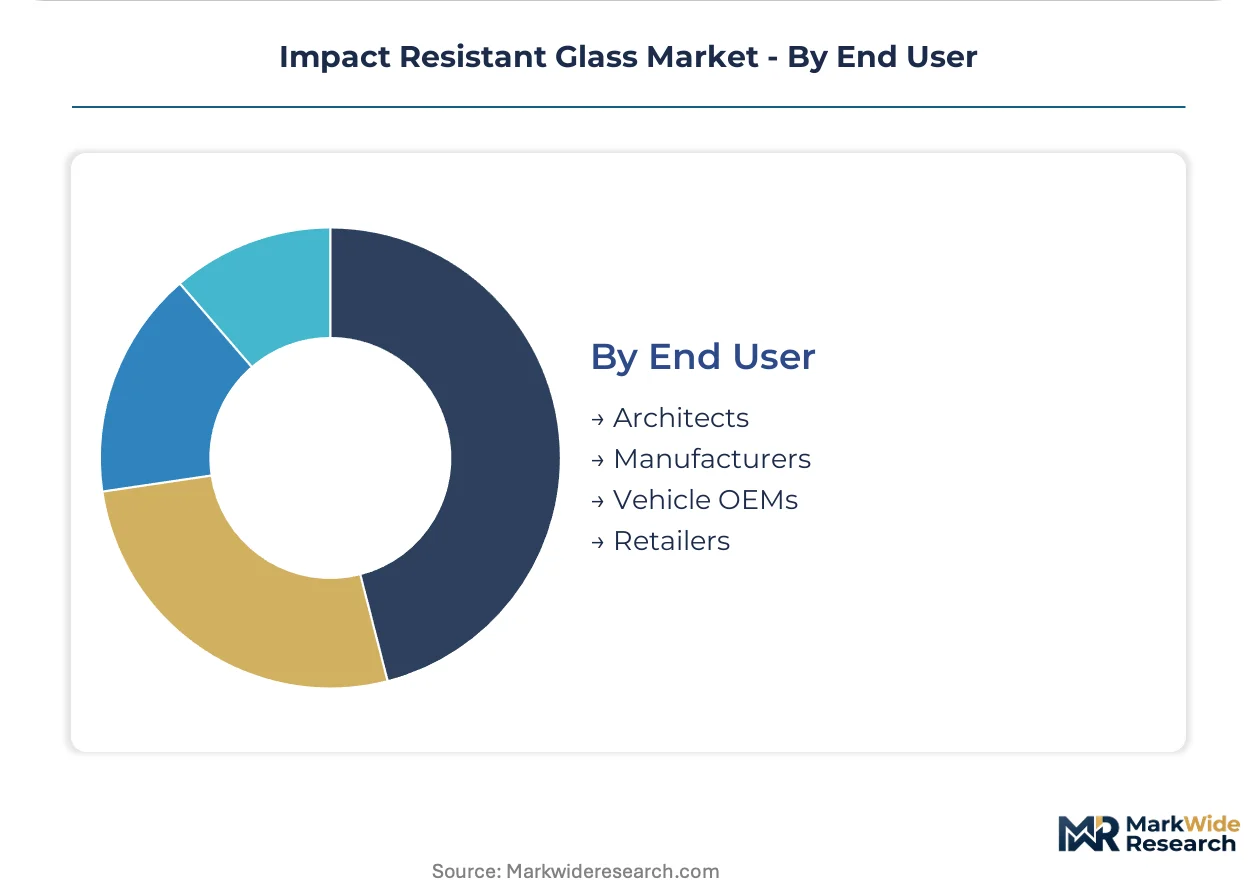
End User:
Procurement authority consolidates among specification professionals who bundle performance guarantees with structural liability.
- Vehicle OEMs:German premium manufacturers in Stuttgart and Munich corridors drive interlayer chemistry qualification timelines. These buyers require full supply chain certification under REACH phthalate restrictions.
- Architects:Design professionals specify glazing performance indirectly through facade engineering consultants. Miami-Dade County projects channel decisions through bundled structural calculation providers.
- Manufacturers:Independent laminators and integrated float-line operators compete on interlayer bonding capability. Float line concentration in Europe and Asia creates substrate supply bottlenecks for non-integrated producers.
- Retailers:Fixture and display manufacturers source acrylic and tempered alternatives for cost-driven applications. These buyers prioritize optical clarity and surface hardness over penetration resistance.
Vehicle OEMs anchor the premium specification base while facade engineering consultants gain procurement influence fastest in US commercial construction channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply by end-use vertical. Automotive OEMs in Germany absorb premium interlayer costs without volume elasticity, while US residential contractors in hurricane zones negotiate aggressively on laminated glass specifications. Indian infrastructure buyers prioritize cost over performance tiers.
United States
Miami-Dade County enforcement drives missile-impact rating mandates for commercial facades and residential construction. NHTSA FMVSS 205 shapes automotive windscreen certification timelines. Float-glass production clusters along the Ohio River corridor supply substrate to independent laminators serving coastal building codes.
Germany
Premium vehicle OEMs in Stuttgart and Munich assembly corridors specify thicker interlayer bonding for rollover integrity. ECE R43 standard revisions tighten windscreen performance benchmarks under UN regulatory harmonization. REACH phthalate restrictions force interlayer chemistry reformulation across laminator operations by 2026.
China
Metro rail expansion in Shanghai and Beijing absorbs laminated safety glazing for platform barriers and station architecture. GB standards for architectural glass align with international impact-resistance protocols. Yangtze River Delta float-line concentration creates substrate supply advantages for domestic laminators.
India
Commercial real estate growth in Mumbai and Delhi generates specification channels for laminated safety glazing in high-rise construction. BIS certification requirements for architectural glass harden quality benchmarks. Gujarat-based fabricators expand capacity to serve infrastructure buildout in western states.
Japan
Automotive production around Toyota City and Yokohama maintains steady demand for precision-laminated windscreens. METI industrial standards govern interlayer bonding quality for transportation applications. Integrated soda ash-to-glass operations in Chubu region anchor supply chain control for regional OEMs.
Impact Resistant Glass Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the impact resistant glass value chain. Integrated float-line operators with captive interlayer chemistry capabilities command premium architectural specifications, while independent laminators compete on volume throughput for standard automotive applications. Three archetypes dominate: vertically integrated multinational glass groups, regional substrate specialists with bonding capabilities, and independent fabricators sourcing annealed glass from merchant markets. Competitive moves concentrate on interlayer chemistry licensing partnerships and furnace reconfiguration for heat-strengthened lite integration.
Among European integrated producers, Saint-Gobain exemplifies the captive interlayer chemistry archetype through control of float-line and laminating operations. AGC Inc. anchors Asian supply positioning with integrated soda ash-to-glass infrastructure. Guardian Industries occupies a position within North American architectural specification channels through tempered-laminated hybrid portfolios.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Nippon Sheet Glass Co., Ltd. |
| Guardian Industries |
| Vitro |
| Sisecam Group |
| Central Glass |
| Taiwan Glass |
| CGS Holding Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between float-line operators and premium German OEMs lock in both PVB and ionoplast interlayer supply access and price visibility across multi-year vehicle platform lifecycles. These arrangements insulate laminators from butyral resin volatility while binding capacity allocation to Stuttgart and Munich assembly corridors under ECE R43 compliance timelines.
Pricing Analysis
ECE R43 dictates the pricing tier structure across European automotive glazing, separating premium ionoplast laminates from standard PVB configurations and economy tempered alternatives. Price differentiation centers on certification grade and interlayer chemistry, with REACH phthalate restrictions compressing margins on conventional PVB formulations. Cost compression in standard PVB tiers is intensifying because acetic acid feedstock volatility feeds through laminator P&Ls. US residential contractors in hurricane zones exhibit the sharpest price sensitivity, while German premium OEMs absorb interlayer premiums without volume elasticity.
Supply Chain Analysis
Inventory lead times for high-quality annealed glass substrate stretch 8-12 weeks at independent laminators, creating working capital intensity that favors integrated float-line operators. Supply concentrates in Germany, Japan, and China, where Saint-Gobain, AGC Inc., and Yangtze River Delta producers control captive soda ash-to-glass infrastructure. Raw material dependencies span butyral resin, polyvinyl alcohol, and ionoplast polymer feedstocks. Single-source vulnerability concentrates in European float-line capacity, where furnace reconfiguration for heat-strengthened lite integration requires capital commitments that non-integrated players cannot match. Distribution runs through facade engineering consultants in US commercial construction and direct OEM supply agreements in European automotive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among facade engineering consultants who bundle performance guarantees with structural liability, fragmenting direct architect-manufacturer relationships and compressing supplier margins in US commercial construction.
For Market Incumbents: Fortify interlayer chemistry capabilities through captive bonding operations or exclusive licensing partnerships with ionoplast formulators, defending against polycarbonate substitution in aerospace and weight-critical automotive segments. Prioritize furnace reconfiguration for heat-strengthened lite integration to capture premium architectural specifications under Miami-Dade County enforcement timelines. For New Entrants and Emerging Players: After-sales technical service and recertification support for existing laminated installations represents a service-layer gap where incumbents under-serve, creating entry points for regional fabricators in Indian metro rail expansion and Delhi-Mumbai commercial corridor buildout. Target mid-tier automotive side-lite applications where fragment control suffices and cost sensitivity dominates OEM sourcing decisions, leveraging Gujarat-based substrate access to undercut integrated European producers on landed cost. For Investors and Strategic Acquirers: Regional substrate specialists with compliant bonding capabilities and established BIS or GB certification pathways present the most attractive acquisition target archetype for exposure to Indian and Chinese infrastructure buildout. Long-term viability hinges on regulatory harmonization timelines rather than technology displacement risk. The signal to watch is ECE R43 revision adoption rates across Asian OEMs, which would accelerate ionoplast qualification demand and reward early chemistry-positioned assets.| Strategic Initiative | Industry Significance |
|---|---|
| Ionoplast Chemistry Licensing | Secures premium automotive qualification under ECE R43 and REACH phthalate restrictions. |
| Furnace Reconfiguration Investment | Enables heat-strengthened lite integration for Miami-Dade County missile-impact ratings. |
| Long-term Supply Agreement | Locks in butyral resin access against acetic acid volatility for laminator margin stability. |
| Smart Glass Convergence Partnership | Integrates electrochromic layers with impact-resistant substrates for architectural retrofit markets. |
| Regional Certification Investment | Accelerates BIS and GB pathway completion for Indian and Chinese infrastructure capture. |
Study Parameters
A standing panel of automotive glazing procurement directors, facade engineering consultants, laminator operations managers, and interlayer chemistry specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from NHTSA FMVSS 205 filings, ECE R43 regulatory submissions, customs trade data for float-glass and interlayer materials, SEC 10-K disclosures from integrated glass groups, and Miami-Dade County product approval databases. Bottom-up volume estimates triangulated against top-down value projections from construction spending and automotive production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, application, thickness configuration, and end-user procurement authority. CAGRs were derived from regression analysis of historical price-volume relationships and forward regulatory timeline assumptions. Industry-specific forecast inputs included ECE R43 revision adoption curves and IRA clean energy credit qualification rates for commercial building envelope retrofits.
Material uncertainties — interlayer material cost volatility, regional code harmonization delays, and polycarbonate substitution acceleration in aerospace — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and OEM platform lifecycle timing that could shift with macroeconomic conditions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
UAE Silica Sand Market
Glass
Europe Glass Insulators Market
Glass
Global Flat Glass Market
Glass
Solar Reflective Glass Market
Glass
Glass Mat Thermoplastic Market
Glass
Patterned Glass Market
Glass
Global Energy Efficient Glass Market
Glass
Global Ultra-Thin Glass Market
Glass
Double Glazing Glass Market
Glass
Global Laminated Glass Market
Glass
Foam Glass Market
Glass
Glazing Gel Market
Glass
Silica Sand Market
Glass
Heat Resistant Glass Market
Glass
Global Vacuum Insulated Glass Market
Glass
North America Glass Insulators Market