
 Global Silicone Structural Glazing Market | 2026-2036
Global Silicone Structural Glazing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicone Structural Glazing Market Foresight
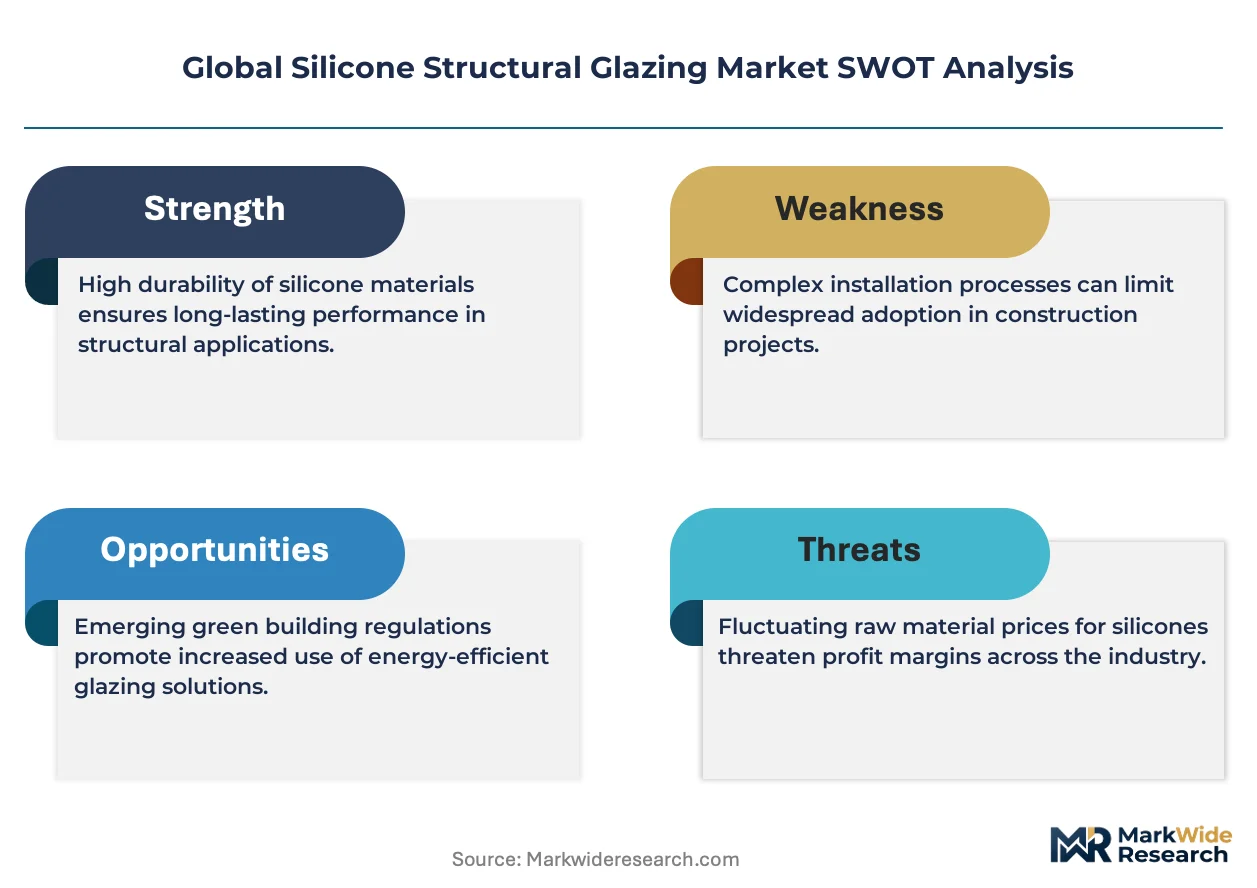
Multi-source procurement of silicone polymers is realigning how facade manufacturers secure feedstock for structural glazing systems. Dow leverages captive silicone production to control formulation consistency across regional plants. Sika AG competes through specialized adhesive portfolios tailored to high-rise wind-load specifications. Wacker Chemie AG anchors European supply chains with integrated organosilicon manufacturing from chlorosilane precursors through finished sealants.
Silicone structural glazing comprises elastomeric adhesive systems formulated from polydimethylsiloxane polymers that cure to form load-bearing bonds between glass panels and metal framing, typically achieving tensile strengths exceeding 0.5 MPa and accommodating thermal movement through elastic recovery. Two-part silicone dominates commercial tower installations where accelerated cure rates compress construction schedules, while point-fixed glazing technology captures premium margins in cultural center projects requiring unobstructed sightlines. Neutral cure silicone formulations displace acetoxy systems in aluminum-framed applications where acetic acid byproducts risk substrate corrosion.
REACH compliance in Europe mandates disclosure of cyclic siloxane content, redirecting formulation R&D toward low-D4/D5 polymer architectures. The EU Green Deal performance standards and China's GB building energy codes collectively pressure manufacturers to certify thermal transmittance improvements through glazing interface design. Stakeholders must track evolving fire-resistance classifications under EN 13501-1 and corresponding test protocol updates that determine market access for curtain wall assemblies.
Market Dynamics
Curtain wall specification is tilting toward high-performance thermal envelopes as architects face intensifying energy code enforcement across multiple jurisdictions. This structural pressure is compressing qualification timelines for structural glazing systems while elevating performance thresholds for bond durability and movement accommodation.
Growth Catalysts
- EU Green Deal building performance standards:Member states are mandating near-zero energy building envelopes, accelerating silicone structural glazing specification for commercial towers seeking compliance certification.
- Megacity construction clusters:Urban densification in China sustains volume procurement of structural silicone systems for super-tall envelope assemblies.
- Two-part silicone cure technology:Accelerated curing formulations compress high-rise construction schedules, enabling faster enclosure completion in temperate-climate building seasons.
Market Restraints
- Organosilicon feedstock concentration:Chlorosilane precursor production clusters in select industrial regions, exposing formulation plants to upstream supply disruption.
- Cyclic siloxane regulatory friction:REACH-mandated D4/D5 disclosure requirements redirect R&D expenditure toward low-cyclic polymer architectures.
- Acetoxy silicone substitution pressure:Neutral cure systems displace acid-cure formulations in aluminum-framed applications where corrosion risk limits specification freedom.
Strategic Opportunities
- Point-fixed glazing in cultural infrastructure:Unobstructed sightline requirements in museum and performing arts projects command premium margins for specialized structural silicone applications.
- GB building energy code convergence:China's national standards are tightening thermal transmittance requirements, creating specification pull for high-performance glazing interface design.
- Fire-resistance certification differentiation:EN 13501-1 classification upgrades present positioning space for manufacturers with tested curtain wall assembly portfolios.
Industry Challenges
- Qualified installation labor scarcity:Proper structural silicone application demands certified facade technicians, constraining project velocity in markets with thin specialist pools.
- Multi-jurisdiction certification timelines:Harmonizing test protocols across REACH, GB standards, and ASTM requirements extends product launch cycles for regional formulation variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicone Structural Glazing Market |
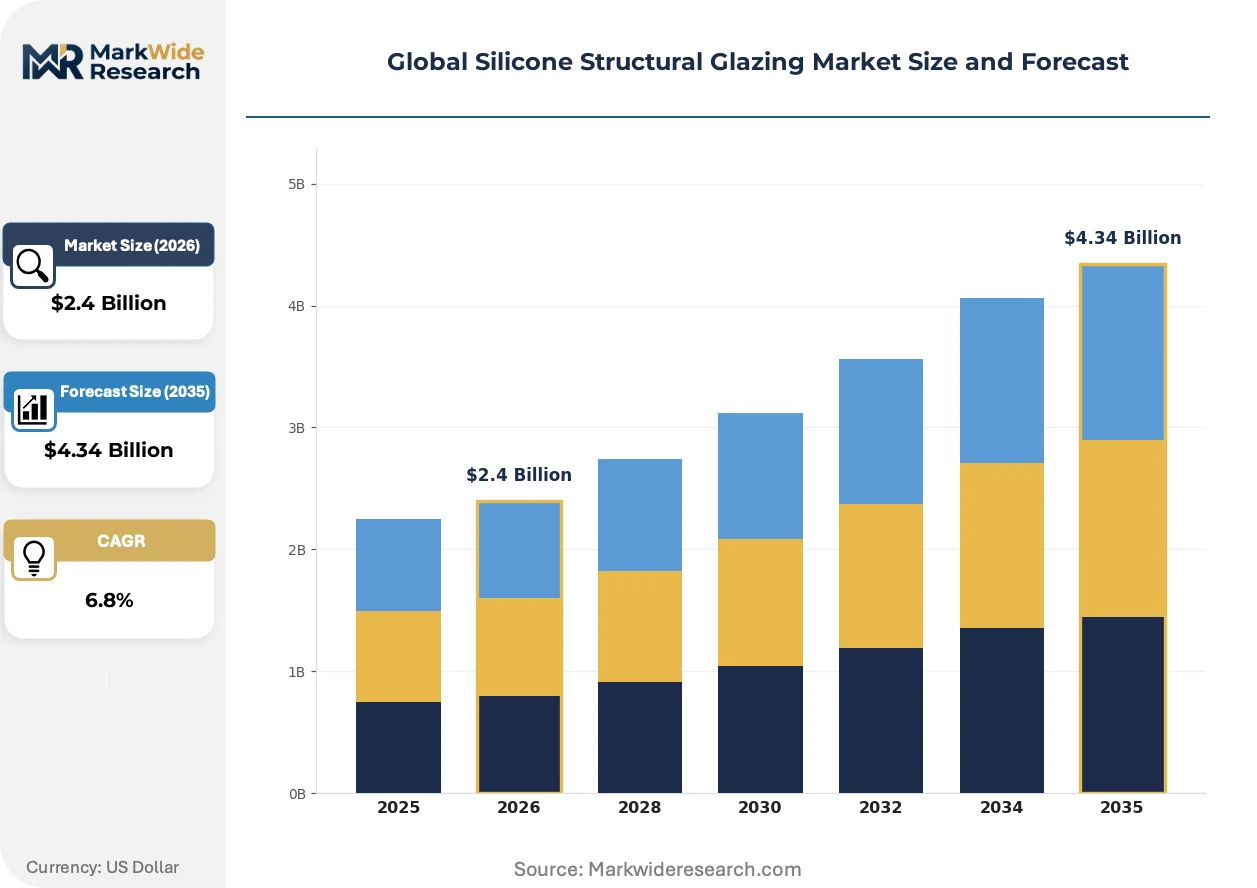
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Part Silicone, One-Part Silicone, Neutral Cure Silicone, Acetoxy Silicone, Modified Silicone Application: Commercial Complexes, Institutional Buildings, Sports Arenas, Cultural Centers, Government Facilities End User: Construction Contractors, Facade Engineering Firms, Architectural Designers, Glazing Specialists, Property Developers Technology: Structural Silicone Glazing, Point-Fixed Glazing, Flush Glazing, Captive Glazing, Spider Glazing |
| Companies Covered | Dow, Saint-Gobain, Sika AG, 3M Company, PPG Industries, Nippon Sheet Glass Co. Ltd., Asahi Glass Co. Ltd., Wacker Chemie AG, Arkema SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicone Structural Glazing Market Shifts & Advancements
Silicone structural glazing is experiencing accelerated specification evolution as envelope performance targets tighten and installation economics compress. Three intersecting developments are redefining competitive positioning.
Neutral cure silicone formulations are expanding into aluminum-intensive curtain wall systems where acetic acid byproduct corrosion risk previously constrained acetoxy system specification. Building envelope consultants in Germany and the Netherlands are specifying neutral cure as default for anodized aluminum framing. This chemistry shift is expanding into North American commercial tower projects as warranty providers recognize substrate compatibility advantages.
REACH cyclic siloxane disclosure mandates are redirecting European formulation R&D toward low-D4/D5 polymer architectures. ECHA regulatory pressure is forcing manufacturers to requalify sealant portfolios under revised substance evaluation protocols. High-rise residential towers in France and Belgium face the tightest compliance timelines as national building codes incorporate REACH substance restrictions into envelope certification requirements.
Specification authority is migrating from general contractors to specialized facade consultants who control technical submittal approval. This channel concentration compresses supplier access to decision-makers while elevating performance documentation requirements. The shift is most visible in London and Singapore commercial tower markets where envelope specialist firms dominate high-value project procurement.
Global Silicone Structural Glazing Market Segmentation
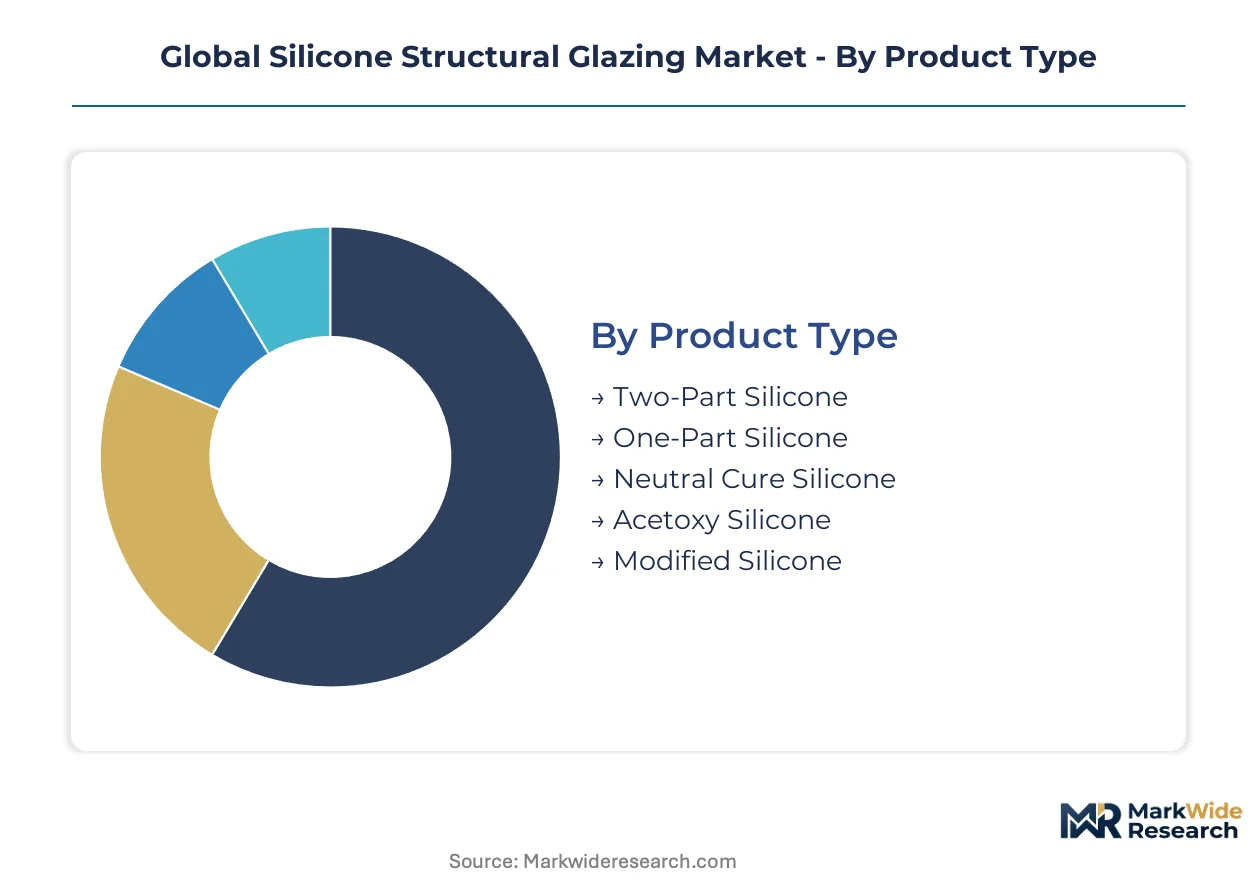
Segmentation in silicone structural glazing reveals how formulation chemistry, installation method, and project typology interact to determine procurement patterns. Distinct technical requirements across commercial towers, cultural infrastructure, and institutional envelopes create specialized demand pockets that suppliers must address through targeted product positioning.
Product Type:
Volume procurement concentrates in two-part systems for accelerated cure schedules, while premium margins attach to specialized chemistries addressing substrate compatibility and regulatory compliance.
- Two-Part Silicone:Base-and-catalyst systems cure through chemical reaction independent of atmospheric moisture, enabling rapid bond development critical for high-rise construction sequencing. Megacity commercial towers in China specify two-part formulations to compress enclosure timelines during temperate building seasons.
- Neutral Cure Silicone:Alkoxy-based cure chemistry releases alcohol byproducts rather than acetic acid, eliminating corrosion risk on anodized aluminum framing. German and Dutch facade consultants specify neutral cure as default for aluminum-intensive curtain wall systems.
- One-Part Silicone:Moisture-cure systems in cartridges suit smaller-scale applications and repair work where mixing equipment is impractical.
- Acetoxy Silicone:Acid-cure formulations retain cost advantage in non-aluminum substrates but face specification decline where corrosion warranties apply.
- Modified Silicone:Hybrid polymers blend silicone durability with modified organic characteristics for specialized movement accommodation requirements.
Mature deployment sits with acetoxy systems in legacy building stock. Newer deployment is concentrated in neutral cure formulations as aluminum framing dominates contemporary commercial envelope specification.
Application:
Project typology determines performance certification requirements and margin structure, with cultural and institutional assets commanding premium specification over standardized commercial development.
- Commercial Complexes:Office towers and mixed-use developments drive baseline volume demand for structural glazing systems. China's super-tall construction clusters sustain procurement of high-movement-capable silicone formulations certified to GB energy codes.
- Cultural Centers:Museums, concert halls, and exhibition spaces demand point-fixed and flush glazing technologies that maximize transparent sightlines. These projects command premium margins for specialized structural silicone applications with enhanced optical clarity requirements.
- Institutional Buildings:Universities and healthcare facilities prioritize durability certification and extended warranty terms over first-cost optimization.
- Sports Arenas:Large-span roof and facade assemblies require high-elongation formulations accommodating structural deflection under crowd loading.
- Government Facilities:Public procurement emphasizes tested assembly certification under national fire-resistance protocols.
Specification authority concentrates with facade engineering firms in cultural center projects. Procurement velocity runs highest through construction contractors in commercial complex development.
End User:
Channel concentration is shifting toward specialized facade consultants who control technical submittal approval, compressing direct supplier access to decision-makers.
- Facade Engineering Firms:Technical specialists dominate high-value project specification in London and Singapore commercial tower markets. These firms demand extensive performance documentation and assembly testing records.
- Construction Contractors:Volume procurement leverage rests with tier-one contractors managing megacity developments in China and the UAE.
- Architectural Designers:Early-stage design influence determines aesthetic and performance parameters later enforced through specification.
- Glazing Specialists:Certified installation labor scarcity constrains project velocity in markets with thin technician pools.
- Property Developers:Return-driven procurement emphasizes envelope energy performance certification for asset valuation and lease premiums.
Technical decision-making authority is migrating toward facade engineering firms. Execution responsibility remains concentrated with construction contractors and glazing specialists.
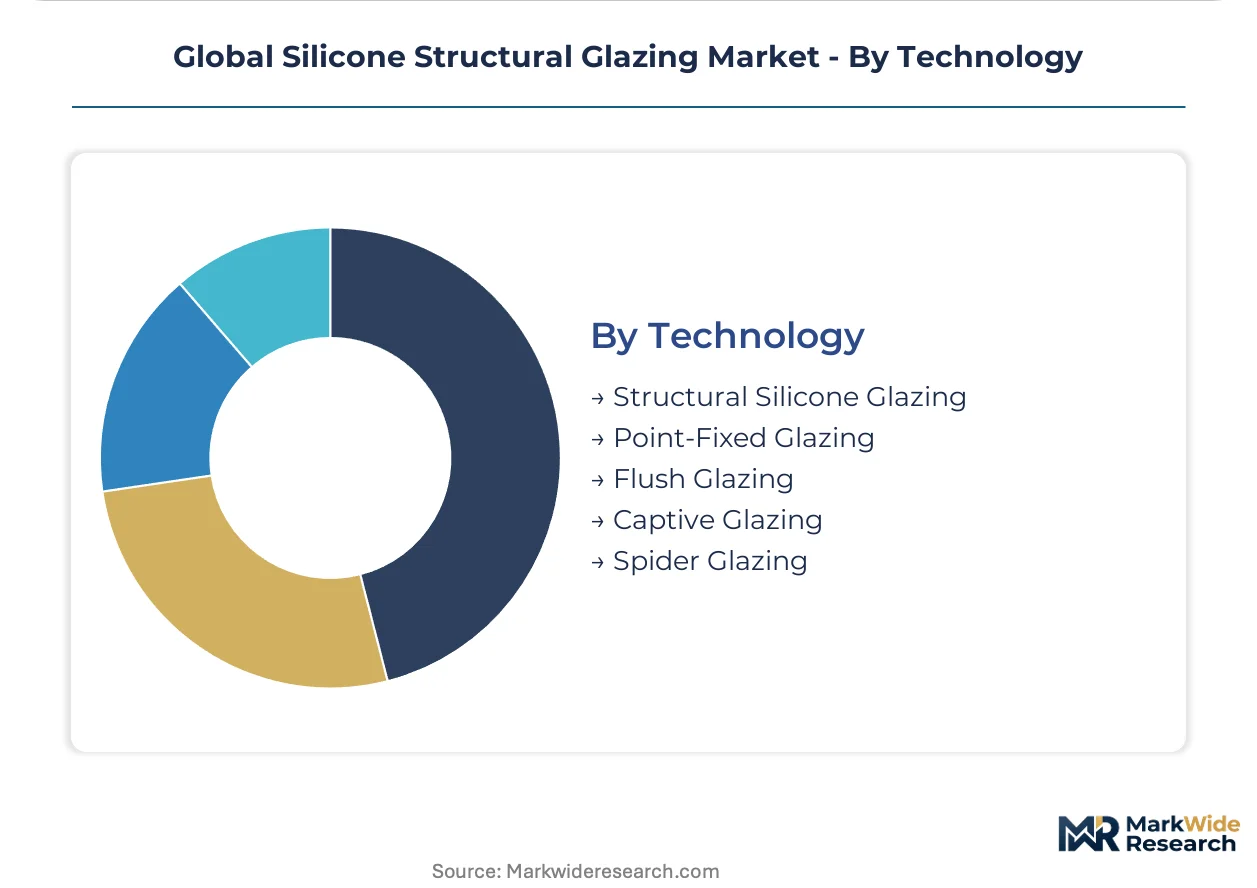
Technology:
Installation methodology determines silicone formulation requirements, with structural bonding systems representing volume demand and point-fixed approaches capturing premium positioning.
- Structural Silicone Glazing:Continuous adhesive bonding between glass and metal framing achieves load-bearing capacity with tensile strengths exceeding 0.5 MPa. This technology dominates commercial tower specification where thermal movement accommodation and wind-load resistance are critical.
- Point-Fixed Glazing:Mechanical point supports combined with silicone gasketing enable maximum transparency in cultural infrastructure. Museum and performing arts projects in France and Belgium specify these systems for unobstructed sightlines.
- Flush Glazing:Frameless appearance systems require precision silicone application for weathersealing without visible framing elements.
- Captive Glazing:Pressure-plate-retained systems with silicone secondary seals suit high-wind-load applications.
- Spider Glazing:Tension cable and rod systems with point-fixed glass connections demand specialized silicone compatibility with stainless steel hardware.
Structural silicone glazing anchors volume deployment across commercial developments. Point-fixed and spider glazing systems are expanding most quickly in premium cultural infrastructure segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chlorosilane precursor production clusters in Germany's Ruhr industrial corridor anchor European silicone polymer supply chains. This feedstock geography shapes regional formulation capabilities and constrains capacity expansion elsewhere.
China
Megacity construction in Shanghai, Shenzhen, and Guangzhou sustains volume procurement of two-part structural silicone systems for super-tall commercial towers. GB building energy codes tighten thermal transmittance requirements annually, pressuring facade designers toward high-performance glazing interfaces. The Yangtze River Delta concentration of curtain wall fabricators consumes the majority of domestic silicone structural glazing output.
Germany
Facade engineering firms in Berlin and Frankfurt specify neutral cure silicone as default for aluminum-intensive curtain wall systems. REACH cyclic siloxane disclosure mandates redirect formulation R&D toward low-D4/D5 polymer architectures at Wacker Chemie's Burghausen operations. The Bavarian industrial corridor hosts integrated organosilicon manufacturing from chlorosilane precursors through finished sealants.
United States
Commercial tower development in New York, Chicago, and Los Angeles drives specification of structural silicone systems certified to ASTM standards. Curtain wall consultants increasingly demand extended warranty terms and assembly testing records for high-wind-load applications. The Southeast construction corridor from Atlanta to Miami represents the fastest-expanding regional demand cluster for neutral cure formulations.
United Arab Emirates
Dubai's super-tall residential and hospitality projects specify point-fixed glazing systems for unobstructed sightlines and thermal performance certification. MOHAP building product registration requirements extend qualification timelines for European and Asian sealant suppliers. The Dubai Design District concentration of facade engineering specialists controls technical submittal approval for premium developments.
France
Cultural infrastructure projects in Paris and Lyon command premium margins for specialized structural silicone applications with enhanced optical clarity requirements. ANSM enforcement of REACH substance restrictions into national building codes tightest compliance timelines for high-rise residential towers. The Île-de-France cluster of museum and performing arts developments sustains demand for point-fixed and spider glazing technologies.
Global Silicone Structural Glazing Market Competitive Landscape
Capacity expansion dominates the current landscape as formulation manufacturers secure captive silicone polymer supply. The vendor base concentrates among integrated chemical conglomerates and specialized adhesive producers, creating tiered competition between scale-driven supply and specification-driven premium positioning. Three archetypes define the field: integrated silicone polymer producers with backward control over chlorosilane feedstock, specialized construction adhesive formulators with facade engineering relationships, and diversified materials conglomerates leveraging cross-divisional building envelope expertise. Geographic expansion and portfolio diversification represent the dominant competitive vectors as participants seek qualification in tightening regulatory jurisdictions.
Within the integrated chemical tier, Dow exemplifies captive silicone production control across regional formulation plants. Sika AG occupies a position representing specialized adhesive portfolios tailored to high-rise wind-load specifications. Wacker Chemie AG anchors European supply chain security through integrated organosilicon manufacturing. These three entities collectively represent the competitive archetypes shaping procurement patterns: feedstock-integrated scale, specification-driven specialization, and regional supply security.
| Leading Market Players |
|---|
| Dow |
| Saint-Gobain |
| Sika AG |
| 3M Company |
| PPG Industries |
| Nippon Sheet Glass Co. Ltd. |
| Asahi Glass Co. Ltd. |
| Wacker Chemie AG |
| Arkema SA |
| Others |
Supply & Pricing Matrix
EU Green Deal mandated energy performance upgrades are forcing facade consultants to specify certified structural glazing systems with extended warranty coverage, compelling manufacturers to bundle installation support and performance guarantees into base pricing while absorbing qualification costs.
Pricing Analysis
Warranty bundling separates premium formulations from commodity-grade alternatives, with tier-one suppliers including 20-year performance guarantees and on-site technical supervision while economy-tier competitors sell unbundled product-only contracts. Price differentiation hinges on certification grade—REACH-compliant low-D4/D5 formulations command substantial premiums over standard silicone—and volume scale, with megacity procurement in China extracting favorable terms through concentrated demand. Cost compression in the mid-tier segment is intensifying because neutral cure R&D investments are being amortized across narrower production runs. Construction contractors managing standardized commercial towers exhibit the highest price sensitivity, whereas facade engineering firms specifying cultural infrastructure projects prioritize optical clarity and fire-resistance certification over first-cost optimization.
Supply Chain Analysis
Reverse logistics for silicone structural glazing remain underdeveloped, with spent sealant removal and substrate refurbishment typically handled by demolition contractors rather than manufacturer-led recovery programs. Chlorosilane precursor production concentrates in Germany, China, and the United States, with Wacker Chemie's Burghausen operations and Dow's Midland facilities anchoring regional supply security. Finished sealant formulation draws from polydimethylsiloxane polymers, methyltrimethoxysilane crosslinkers, and fumed silica reinforcing agents. Single-source vulnerability sits with European manufacturers dependent on Ruhr corridor chlorosilane feedstock, where energy cost volatility and regulatory inspection backlogs create disruption risk. Distribution runs through specialized facade material distributors who maintain technical sales support capabilities, with direct procurement relationships concentrated among tier-one construction contractors in China and the UAE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as feedstock security determines formulation consistency and regulatory compliance speed. Captive chlorosilane production represents the critical upstream lever that separates integrated competitors from formulation-dependent challengers.
For Market Incumbents: Acquire captive chlorosilane production assets or secure long-term offtake agreements with German and Chinese precursor manufacturers to insulate against supply disruption. Expand neutral cure formulation capacity in Southeast Asia to serve Dubai's super-tall construction cluster while REACH compliance timelines tighten in Europe. Substitute technology pressure from modified silicone hybrids and pre-formed gasket systems demands accelerated R&D in low-cyclic polymer architectures to maintain specification authority with facade consultants. For New Entrants and Emerging Players: Digital specification platforms that aggregate facade engineering firm submittal requirements offer a direct route to bypass entrenched distributor relationships and capture technical documentation share. White-space targets include point-fixed glazing applications in Middle Eastern cultural infrastructure, where MOHAP registration barriers filter out commodity competitors, and fire-resistance certified systems for French high-rise residential towers facing ANSM enforcement deadlines. A go-to-market angle anchored in rapid-cure two-part silicone customization for compressed construction schedules in China's temperate building seasons can dislodge incumbent share. For Investors and Strategic Acquirers: Re-rating potential sits with specialized adhesive formulators possessing tested EN 13501-1 curtain wall assembly portfolios given the EU Green Deal's acceleration of near-zero energy building envelope mandates. Long-term viability over the next decade rests on securing qualification in tightening regulatory jurisdictions rather than scale-driven cost position alone. The acquisition target archetype combines regional formulation expertise with established facade engineering firm relationships in London or Singapore. The signal to watch is GB building energy code revision announcements, which tighten thermal transmittance thresholds and force asset obsolescence among non-compliant sealant portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Precursors | Captive feedstock supply insulates Wacker Chemie and Dow from energy cost volatility in Germany's Ruhr corridor. |
| Neutral Cure Formulation Expansion | Alkoxy-based chemistry penetration into aluminum-intensive curtain wall systems displaces acetoxy alternatives in German and Dutch specifications. |
| Fire-Resistance Assembly Certification | EN 13501-1 tested portfolios unlock specification access for French high-rise residential towers under ANSM enforcement. |
| Facade Engineering Firm Partnership Programs | Technical documentation and submittal support capabilities secure channel control in London and Singapore commercial tower markets. |
| Point-Fixed Glazing Technology Development | Specialized silicone applications for museum and performing arts projects in Dubai and Paris command premium margin positioning. |
Research Methodology
Independent corroboration across plant managers at chlorosilane production facilities, procurement leads at curtain wall fabricators, distribution channel partners in European facade material supply, and technical R&D directors at sealant formulation companies underwrites the qualitative findings. Primary interviews with these stakeholders were combined with secondary validation from customs and trade data, SEC 10-K filings of integrated chemical conglomerates, and national building code revision documents from ECHA and China's standardization administration. Bottom-up volume estimates derived from megacity construction project tracking were triangulated against top-down silicone polymer consumption figures reported by regional chemical industry associations.
Comparable-period anchoring linked the projection horizon to historical installation rates across commercial tower, cultural infrastructure, and institutional building typologies. The analytical framework modeled segmentation across product type (two-part, neutral cure, one-part, acetoxy, modified silicone), application (commercial complexes, cultural centers, institutional buildings, sports arenas, government facilities), end user channel (facade engineering firms, construction contractors, architectural designers, glazing specialists, property developers), and technology methodology (structural silicone glazing, point-fixed glazing, flush glazing, captive glazing, spider glazing). CAGRs were derived from elasticity-adjusted demand curves incorporating GB building energy code stringency indices and EU Green Deal implementation timelines. Industry-specific forecast inputs included curtain wall fabrication capacity utilization rates in the Yangtze River Delta and facade consultant specification authority concentration indices in London and Singapore.
The model holds under continued enforcement of REACH cyclic siloxane disclosure requirements and stable chlorosilane feedstock availability; deviation in ECHA substance restriction expansion or German energy cost spikes would shift volume and value trajectories. Forecasts reflect documented assumptions regarding megacity construction sustainability in China and commercial tower development velocity in the United States. Practitioners should monitor ANSM and MOHAP regulatory announcement calendars for early signals of qualification timeline compression or assembly testing protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Foam Glass Market
Glass
Silica Sol Market
Glass
Ultra Violet Glass Bottles Market
Glass
Glass Vials Market
Glass
Global Vacuum Insulated Glass Market
Glass
Metallic Glass Market
Glass
3D Glass Market
Glass
Glass Insulator Market
Glass
East Africa Flat Glass Market
Glass
Global Energy Efficient Glass Market
Glass
Low Temperature Laminated Glass Market
Glass
Global Ultra-Thin Glass Market
Glass
Spherical Silica Market
Glass
Coated Glass Market
Glass
Silica Sand for Glass Making Market
Glass
Recycled Glass Market