
 Glass Prepreg Market | 2026-2036
Glass Prepreg Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Prepreg Market Analysis
AS9100 certification is bifurcating the competitive landscape into qualified aerospace suppliers and generalist composite producers. Hexcel Corporation leverages decades of qualification heritage to sustain premium positioning in structural aerocomposites. Owens Corning anchors volume supply through vertical integration from glass fiber melt to prepreg formulation. Toray Industries differentiates via carbon-glass hybrid prepregs for intermediate stiffness applications.
Glass prepreg consists of woven or unidirectional E-glass or S-glass reinforcement pre-impregnated with thermoset resin, typically supplied with controlled volatile content and tack level for automated layup or hand placement. The material delivers predictable fiber volume fraction, reduced void content, and streamlined processing for structural laminates requiring consistent mechanical performance. Epoxy resin systems dominate aerospace and wind energy segments due to superior mechanical properties and hot-wet performance retention. Phenolic prepregs occupy niche insulation and fire-resistant applications where low smoke toxicity governs specification. Filament winding and prepreg layup processes attract capital investment as blade lengths exceed 80 meters and pressure vessel designs thicken.
FAA airworthiness directives and EASA certification requirements mandate extensive qualification databases for structural prepreg changes, elevating barriers for new entrants. EPA emissions standards and REACH substance restrictions shape resin formulation decisions, pushing suppliers toward reduced styrene and bisphenol-A alternatives. MEE enforcement of dual carbon goals in China redirects glass fiber capacity toward domestic wind blade supply chains. Stakeholders must monitor qualification timeline compression against regulatory chemistry constraints as next-generation blade designs and urban air mobility platforms advance toward production.
Market Dynamics
AS9100 qualification requirements are compressing supplier access for aerospace structural applications while REACH substance restrictions simultaneously reshape resin chemistry portfolios across European supply chains.
Growth Catalysts
- Wind blade scaling:Turbine lengths exceeding 80 meters now require filament-wound spar caps and thick-section laminates that only glass prepreg processes can deliver with consistent void control.
- Urban air mobility platforms:Electric vertical takeoff aircraft programs in the United States and Germany are qualifying glass-epoxy primary structures under FAA and EASA certification frameworks.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment is redirecting domestic glass fiber melt capacity toward captive wind blade supply chains, reducing import dependency.
Market Restraints
- Epoxy resin cost volatility:Bisphenol-A and amine hardener feedstock prices fluctuate with crude oil derivatives, compressing formulation margins for non-integrated suppliers.
- Qualification database concentration:Aerospace OEMs maintain approved supplier lists locked to specific resin-fiber combinations, freezing out new entrants for 5-7 year program cycles.
- Thermoplastic composite substitution:Continuous fiber-reinforced thermoplastics from Lanxess and Celanese are displacing glass prepreg in automotive underbody panels and battery enclosures.
Strategic Opportunities
- Hydrogen pressure vessels:Type IV composite tanks for fuel cell trucks and buses require thick-wound glass-epoxy liners with permeation resistance, opening filament winding capacity expansion.
- India PLI scheme:Production-linked incentives for renewable energy equipment are attracting glass fiber and prepreg investments to Gujarat and Tamil Nadu manufacturing corridors.
- Fire-resistant phenolic formulations:Rail interior panels and marine bulkheads under IMO SOLAS regulations are creating specification pull for low-smoke toxicity prepregs outside traditional aerospace.
Industry Challenges
- Autoclave capacity scarcity:Large-diameter pressure vessels and wind blade root sections require outsize curing equipment with 12-month lead times and specialized technician crews.
- Resin out-time management:Cold chain logistics for frozen prepreg shipments face temperature excursion risks that invalidate tack levels and shelf life certifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Prepreg Market |
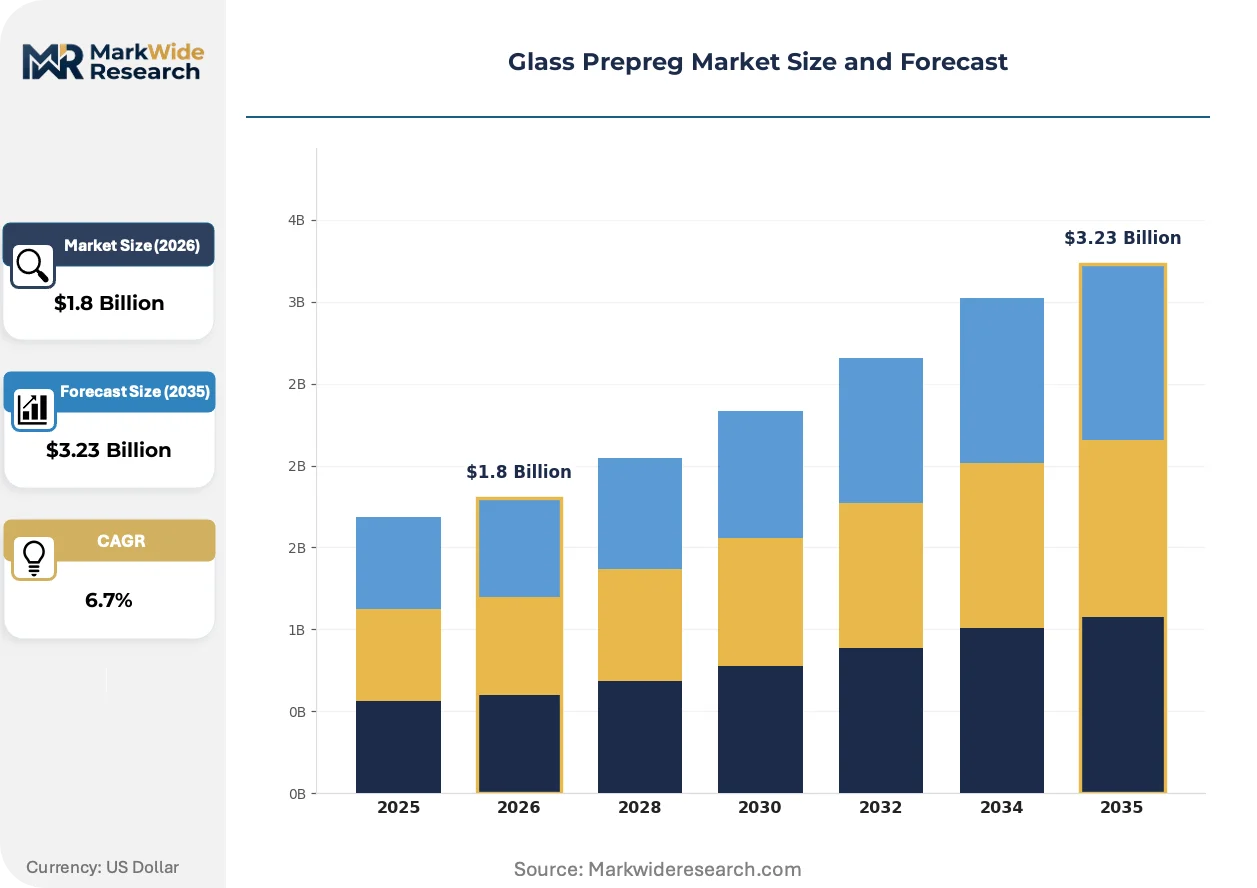
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Phenolic, Polyester, Others End User: Aerospace, Automotive, Marine, Wind Energy Manufacturing Process: Hand Layup, Vacuum Infusion, Filament Winding, Prepreg Layup Application: Structural Components, Insulation, Electrical, Sporting Goods |
| Companies Covered | Owens Corning, SGL Carbon SE, Hexcel Corporation, Axiom Materials, Inc., Teijin Limited, Toray Industries, Inc., Solvay S.A., Mitsubishi Chemical Corporation, Gurit Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Prepreg Market Emerging Trajectories
Digital thread integration and automated fiber placement are compressing layup cycle times while regulatory chemistry constraints force resin reformulation investments.
Out-of-autoclave curing systems are bifurcating the aerospace prepreg landscape between qualified autoclave-dependent suppliers and emerging oven-cure specialists. Tier 2 aerostructures manufacturers in Mexico and Poland are adopting vacuum-only cure cycles to bypass capital-intensive pressure vessel investments. This technology divergence is compressing pricing premiums for traditional autoclave-qualified material sets.
REACH Annex XVII restrictions on bisphenol-A and styrene emissions are forcing European formulators toward bio-based epoxy alternatives and phenolic resin systems. ECHA substance evaluation timelines are extending qualification cycles by 18-24 months for new chemistry introductions. Wind blade producers in Denmark and Spain are accelerating partnerships with resin suppliers holding early SVHC screening data.
Consolidated procurement through tier-one aerostructures integrators is displacing direct airline and lessor relationships for composite material sourcing. Airbus and Boeing are mandating supplier-managed inventory programs at final assembly lines in Toulouse, Mobile, and Tianjin. This channel compression is most visible in North American and Chinese aerospace clusters where just-in-time delivery penalties exceed material cost differentials.
Glass Prepreg Market Segmentation
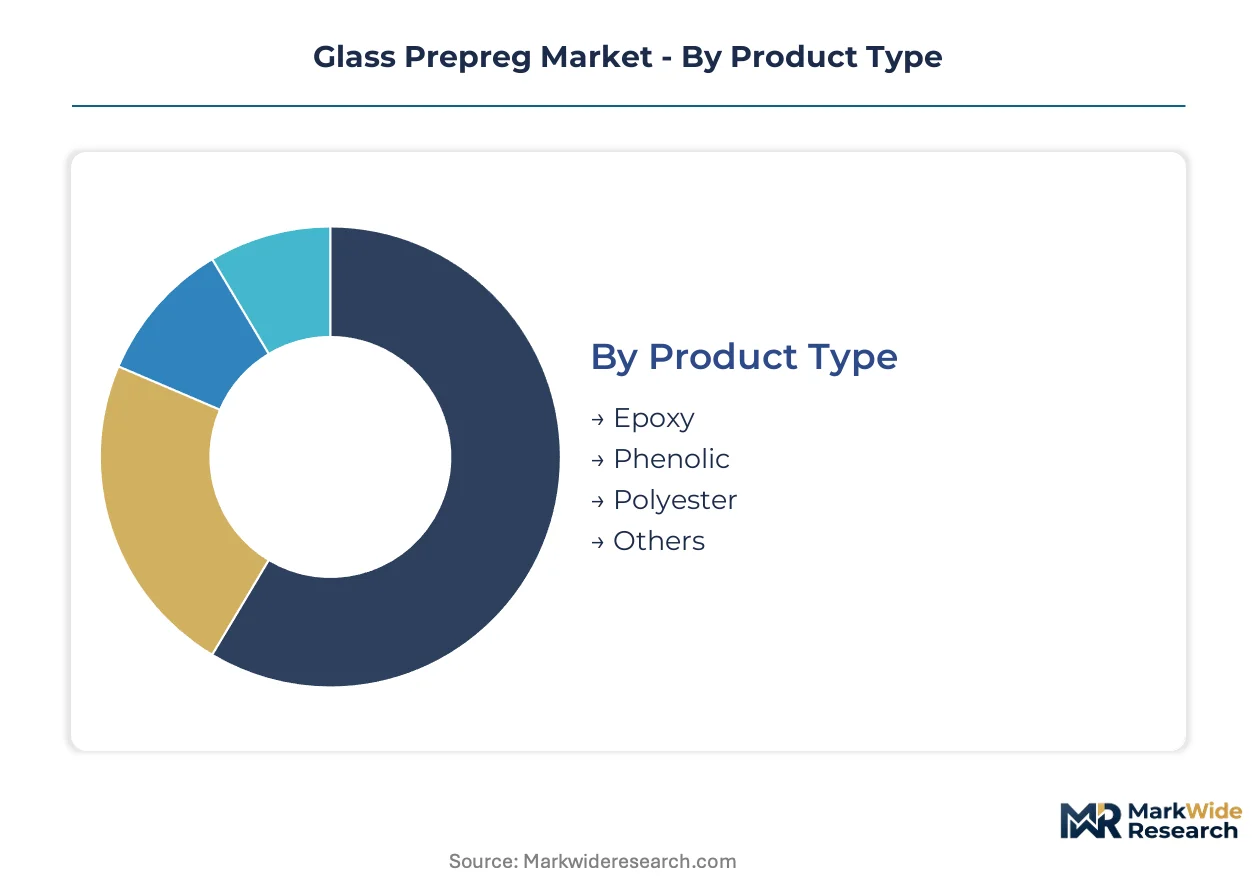
Glass prepreg segmentation reflects divergent qualification requirements across aerospace, wind energy, and emerging mobility platforms. Resin chemistry choices and manufacturing process selection determine supplier access to premium versus commodity application tiers.
Product Type:
Epoxy formulations dominate export-oriented supply chains serving aerospace OEMs, while phenolic systems concentrate in domestic fire-protection markets with localized certification paths.
- Epoxy:Delivers superior hot-wet mechanical retention and fatigue resistance required for primary aerostructures and wind blade spar caps. Demand concentrates in Germany and the United States where FAA and EASA qualification databases lock in approved resin-fiber combinations for 5-7 year program cycles.
- Phenolic:Provides low smoke toxicity and fire resistance for rail interiors and marine bulkheads under IMO SOLAS regulations. Applications cluster in domestic European supply chains serving IMO-compliant shipyards and rail integrators in France and Italy.
- Polyester:Cost-driven formulations for non-structural marine and construction applications with limited qualification overhead.
- Others:Bio-based and cyanate ester alternatives emerging under REACH Annex XVII pressure.
Epoxy commands the established base. The steepest expansion runs through phenolic as rail and marine fire regulations tighten.
End User:
Customer segmentation tracks capital intensity and certification burden, with aerospace requiring decade-long qualification investments versus wind energy's volume-scale procurement.
- Wind Energy:Blade manufacturers in Denmark and Spain drive filament-wound spar cap demand as turbine lengths exceed 80 meters. MEE dual carbon enforcement in China redirects domestic glass fiber capacity toward captive supply chains, reducing import dependency for rotor blade production.
- Aerospace:OEM qualification databases at Airbus and Boeing freeze resin-fiber specifications for multi-year program cycles, elevating barriers for new entrants.
- Automotive:Underbody panels and battery enclosures face thermoplastic substitution from Lanxess and Celanese continuous fiber systems.
- Marine:Hull laminates and superstructures utilize hand layup and vacuum infusion processes with lower capital barriers.
Wind Energy captures volume leadership. Aerospace maintains margin concentration through qualification lock-in.
Manufacturing Process:
Process selection bifurcates between capital-intensive autoclave curing for aerostructures and out-of-autoclave methods gaining traction in tier-2 manufacturing clusters.
- Prepreg Layup:Automated fiber placement and hand layup of pre-impregnated tapes deliver controlled fiber volume fraction for primary structures. Mexico and Poland tier-2 manufacturers adopt vacuum-only cure cycles to bypass 12-month autoclave lead times.
- Filament Winding:Computer-controlled fiber placement produces thick-wound pressure vessels and wind blade root sections with consistent void control.
- Hand Layup:Labor-intensive process for prototype and repair applications with limited automation.
- Vacuum Infusion:Resin transfer method for large marine and wind components requiring lower tooling investment.
Prepreg layup anchors aerospace value capture. Filament winding scales fastest through hydrogen pressure vessel demand.
Application:
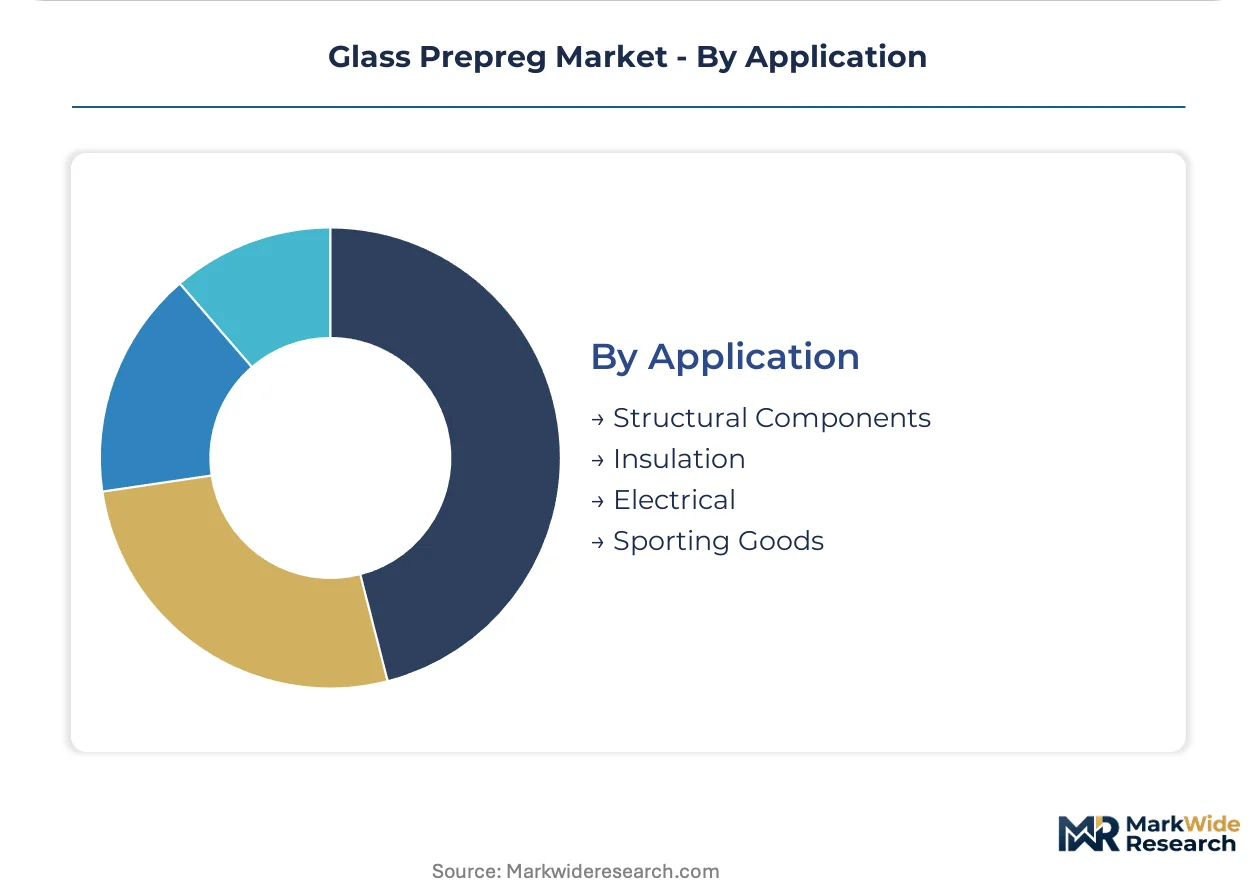
Application segmentation maps directly to regulatory jurisdiction, with structural components governed by FAA and EASA airworthiness directives versus electrical and insulation applications under IEC and national electrical codes.
- Structural Components:Wing skins, fuselage panels, and pressure vessels require AS9100 certification and extensive mechanical property databases. Urban air mobility platforms in the United States and Germany are qualifying glass-epoxy primary structures under emerging FAA and EASA frameworks.
- Insulation:Phenolic prepregs serve rail and marine fire barriers under IMO SOLAS and national rail safety regulations.
- Electrical:Printed circuit board substrates and electrical insulation laminates conform to IEC standards and national electrical codes.
- Sporting Goods:Bicycles, hockey sticks, and recreational equipment utilize commodity-grade prepregs with minimal qualification overhead.
Structural Components concentrate revenue and qualification investment. Insulation applications expand through regulatory-driven specification pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE dual carbon enforcement is redirecting domestic glass fiber capacity toward captive wind blade supply chains, while India's PLI scheme for renewable energy equipment attracts manufacturing investments to Gujarat and Tamil Nadu corridors.
China
Domestic wind turbine blade production scales past 80-meter lengths, demanding filament-wound spar caps with consistent void control. MEE enforcement of dual carbon goals redirects glass fiber melt capacity toward captive supply chains, reducing import dependency. Manufacturing clusters in Jiangsu and Shandong provinces concentrate blade fabrication for Goldwind and Envision Energy programs.
United States
Urban air mobility platforms in California and Texas qualify glass-epoxy primary structures under emerging FAA certification frameworks. EPA emissions standards shape resin formulation decisions, pushing suppliers toward reduced styrene alternatives. Aerospace manufacturing corridors in Wichita and Seattle sustain demand for AS9100-qualified structural prepregs.
Germany
Wind blade producers in northern Germany accelerate partnerships with resin suppliers holding early SVHC screening data. REACH Annex XVII restrictions on bisphenol-A force formulators toward bio-based epoxy alternatives. Industrial clusters in Hamburg and Bremen concentrate filament winding capacity for offshore turbine components.
India
Production-linked incentives for renewable energy equipment attract glass fiber and prepreg investments to Gujarat and Tamil Nadu manufacturing corridors. BIS certification requirements for structural composites elevate barriers for imported material sets. Blade fabrication hubs in Ahmedabad and Chennai scale toward 100-meter turbine lengths.
Spain
Wind energy OEMs in the Basque Country and Galicia drive demand for thick-section laminates requiring controlled fiber volume fraction. ECHA substance evaluation timelines extend qualification cycles for new chemistry introductions. Composite manufacturing clusters around Bilbao specialize in pressure vessel and blade root section production.
Glass Prepreg Market Vendor Landscape
Listed leaders compete with private specialists across qualification heritage and vertical integration depth. The vendor base separates into aerospace-certified suppliers with decade-long OEM databases and volume-driven wind energy specialists with captive fiber supply. Three archetypes dominate: integrated fiber-to-prepreg manufacturers, resin formulators with qualification partnerships, and regional blade fabricators with backward integration. Competitive moves concentrate on autoclave capacity expansion and out-of-autoclave curing technology licensing.
Among North American-listed suppliers, Hexcel Corporation and Owens Corning occupy distinct positioning vectors. Hexcel exemplifies the qualification-anchored archetype through decades of aerospace heritage. Owens Corning represents vertical integration from glass fiber melt through prepreg formulation. Toray Industries sits within the hybrid-materials tier, differentiating via carbon-glass combinations for intermediate stiffness applications.
| Leading Market Players |
|---|
| Owens Corning |
| SGL Carbon SE |
| Hexcel Corporation |
| Axiom Materials, Inc. |
| Teijin Limited |
| Toray Industries, Inc. |
| Solvay S.A. |
| Mitsubishi Chemical Corporation |
| Gurit Holding AG |
| Others |
Supply Flow & Price Mechanics
Eighty-meter wind blade production scales in China and Germany are compressing unit economics for filament-wound spar caps while simultaneously elevating price floors for aerospace-qualified material sets. This scale divergence locks in divergent margin structures across certification tiers.
Pricing Analysis
Certification level (AS9100 versus general industrial grade) creates the primary spread between premium and commodity pricing tiers. Contract-based long-term offtake agreements dominate aerospace procurement, while spot-market spot purchasing governs wind energy volume buyers. Price differentiation rests on qualification database access and resin chemistry compliance with REACH and EPA standards. Cost compression in non-integrated epoxy formulation is intensifying because bisphenol-A feedstock volatility squeezes margin. Wind energy procurement teams exhibit highest price sensitivity; aerospace OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are extending lead times for frozen prepreg shipments requiring cold chain integrity. Geographic supply concentration centers on China, Germany, and the United States, with Jiangsu and Shandong provinces anchoring captive wind blade feedstock. Raw material dependencies draw from E-glass fiber melt capacity, epoxy resin formulation, and amine hardener supply. Single-source vulnerability around qualified aerospace resin-fiber combinations poses structural risk. Distribution runs through tier-one aerostructures integrators managing supplier-managed inventory at final assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urban air mobility certification frameworks and MEE dual carbon enforcement are accelerating demand inflections across aerospace and wind energy segments simultaneously.
For Market Incumbents: Compound qualification heritage through AS9100 database expansion into emerging eVTOL programs while accelerating out-of-autoclave curing technology licensing to tier-2 manufacturers in Mexico and Poland. Thermoplastic substitution from Lanxess and Celanese threatens automotive glass prepreg positions; backward integration into epoxy resin formulation secures margin control against feedstock volatility. For New Entrants and Emerging Players: Differentiate on fire-resistant phenolic formulations for rail interior panels under IMO SOLAS regulations, where qualification timelines compress versus aerospace. India PLI scheme corridors in Gujarat and Tamil Nadu offer the most penetrable geography for greenfield filament winding capacity. Target hydrogen pressure vessel liner applications through permeation-resistant glass-epoxy partnerships with fuel cell truck OEMs. For Investors and Strategic Acquirers: Resin formulators with early SVHC screening data and established ECHA substance evaluation track records represent the priority acquisition archetype. Long-term viability hinges on regulatory chemistry adaptation capacity across REACH Annex XVII constraint cycles. Watch ECHA substance evaluation timeline extensions as the inflection signal for qualification-capable supplier scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Expansion | Locks in aerospace OEM supplier status for multi-year program cycles at Airbus and Boeing. |
| Out-of-Autoclave Technology Licensing | Enables tier-2 manufacturers in Mexico and Poland to bypass 12-month autoclave lead times. |
| Backward Integration into Epoxy Resin | Secures margin control against bisphenol-A and amine hardener feedstock price volatility. |
| Hydrogen Pressure Vessel Partnership | Opens filament winding capacity expansion for Type IV composite tank permeation resistance. |
| REACH-Compliant Bio-Based Formulation | Positions suppliers ahead of ECHA Annex XVII restrictions on conventional resin chemistry. |
Methodological Framework
Initial hypotheses were tested against primary input from composite manufacturing plant managers, aerospace procurement leads at tier-1 aerostructures integrators, wind blade fabrication engineers, resin formulation R&D directors, and cold chain logistics specialists, then refined through secondary validation against customs and trade data, SEC 10-K filings from listed suppliers, FAA and EASA certification databases, and ACC industry reports. Bottom-up demand modeling across end-use segments triangulated with top-down supply capacity assessments.
Variance decomposition across the projection horizon isolates volume drivers by resin chemistry type, manufacturing process selection, end-use industry concentration, and regional regulatory framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate filament winding capacity buildout timelines and urban air mobility certification pathway progression.
The analysis sits within stated boundaries; outcomes outside sustained MEE dual carbon enforcement, stable epoxy feedstock pricing, and current FAA-EASA certification timelines would require recalibration. Model assumptions reflect stated regulatory trajectories and technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Solar Reflective Glass Market
Glass
Laboratory Glassware Market
Glass
Paper Glass Maker Market
Glass
Glass Like Carbon Market
Glass
Europe Glass Insulators Market
Glass
Glass Insulator Market
Glass
Ultra Violet Glass Bottles Market
Glass
Borosilicate Glass Market
Glass
Global Self-Cleaning Glass Market
Glass
Crystalware and Glassware Market
Glass
Mexico Flat Glass Market
Glass
Impact Resistant Glass Market
Glass
Insulated Glass Market
Glass
Flexible Glass Market
Glass
Cellular Glass Market
Glass
Global Energy Efficient Glass Market