
 Low Calorie Rice Market | 2026-2036
Low Calorie Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Rice Market Analytics
The EU Green Deal is pivoting European import standards toward lower glycemic staple grains, creating procurement pressure across Mediterranean and Nordic retail chains. Ricegrowers Limited leverages integrated milling and varietal breeding programs to sustain premium positioning in Australian and Southeast Asian channels. Daawat Foods Ltd. anchors its portfolio through basmati-specific low calorie formulations that dominate South Asian diaspora markets in the United Kingdom and Canada. ITC Limited competes through extensive rural sourcing networks and health-food retail partnerships across Indian metropolitan centers.
Low calorie rice denotes milled or parboiled grain products engineered to reduce caloric density per serving through modified starch structure, resistant starch enrichment, or controlled amylose-to-amylopectin ratios, typically achieving fifteen to sixty percent fewer digestible carbohydrates than conventional white rice while maintaining culinary texture. The primary commercial purpose centers on enabling carbohydrate-controlled diets for diabetes management, weight regulation, and metabolic wellness protocols without displacing culturally embedded dietary patterns. Basmati rice commands premium shelf positioning in health food stores and online retail channels where origin-linked glycemic credibility supports margin extraction. Brown rice variants occupy the fastest-expanding manufacturing segment as resistant starch fortification technologies mature and clean-label positioning resonates with European and North American buyers. Pouch packaging dominates household and meal kit segments due to portion-control convenience and extended shelf stability, though bulk containers sustain institutional food service procurement economies.
The FDA regulates nutritional labeling claims and resistant starch health assertions through substantiation requirements that shape product development timelines and marketing compliance costs for exporters targeting United States distribution. EFSA evaluates novel food ingredient approvals and glycemic response substantiation within the European Union, while India's FSSAI enforces fortification standards and packaged food labeling rules that directly affect domestic formulation and export certification pathways. Stakeholders must monitor evolving resistant starch measurement methodologies and jurisdiction-specific health claim thresholds to align R&D investment with enforceable market access conditions.
Market Dynamics
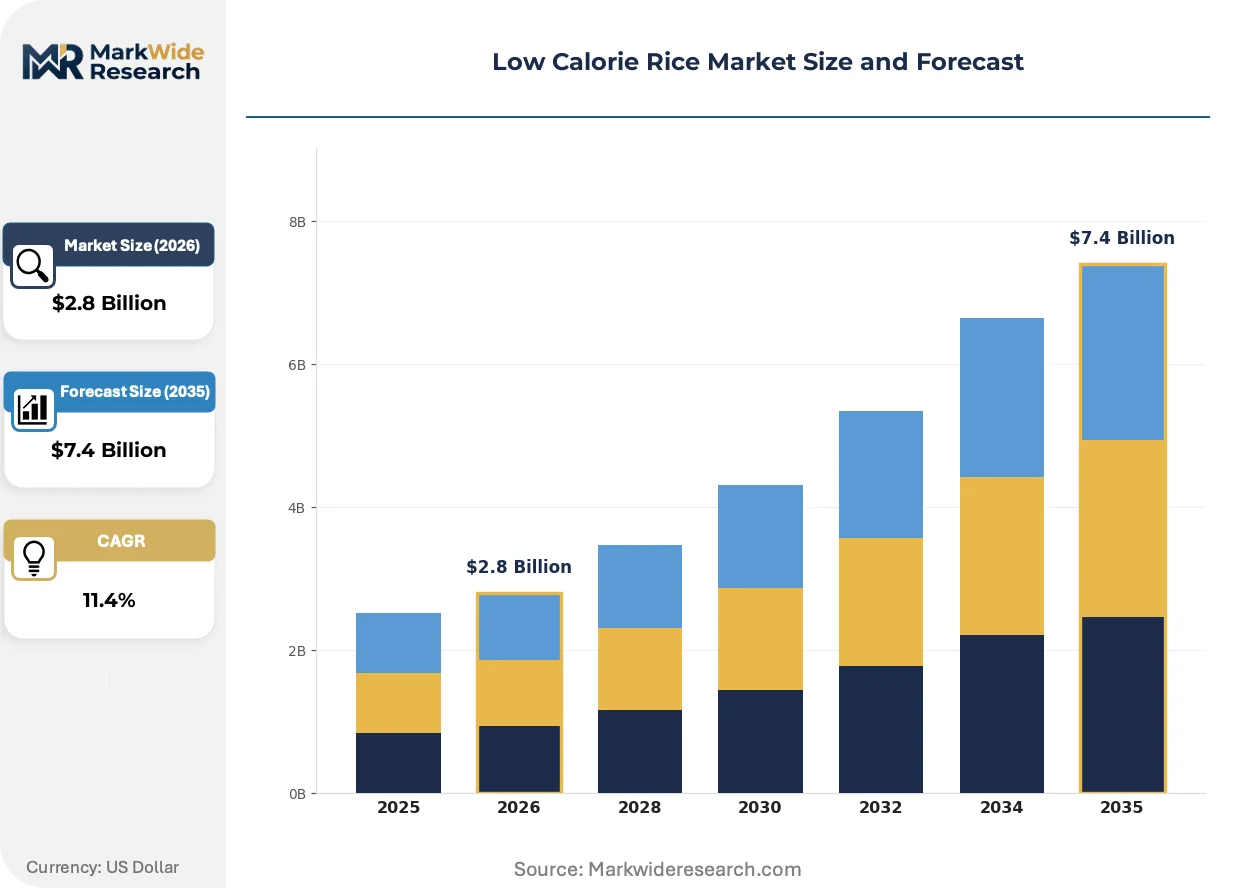
The EU Green Deal is compressing formulation timelines for exporters seeking shelf access across Mediterranean retail chains. Resistant starch measurement methodologies remain unsettled across FDA and EFSA jurisdictions, forcing parallel certification tracks.
Growth Catalysts
- Diabetes management protocols:South Korean and Japanese household consumers are integrating low calorie rice into clinical dietary regimens, creating pull-through from endocrinology clinics into mainstream retail.
- Resistant starch fortification:Clean-label positioning of brown rice variants is electrifying manufacturing investment across European and North American processing facilities.
- Ayurvedic wellness convergence:India's urban centers are merging glycemic index awareness with traditional medicine frameworks, expanding addressable demand beyond clinical populations.
Market Restraints
- Input cost volatility:Specialized amylose-rich germplasm and modified atmosphere packaging materials face agricultural commodity price swings that compress processor margins.
- Technical limitation:Current resistant starch enrichment technologies cap caloric reduction at sixty percent without unacceptable texture degradation in parboiled formats.
- Regulatory friction:EFSA novel food approval pathways for emerging starch modification processes extend time-to-market by eighteen to thirty-six months relative to conventional milled rice.
Strategic Opportunities
- Meal kit channel expansion:Pouch packaging formats are penetrating subscription food service platforms where portion-control convenience commands premium positioning.
- Institutional procurement reform:Nordic healthcare and correctional food service systems are piloting glycemic-controlled staple grain contracts under national wellness mandates.
- Technology convergence:Near-infrared spectroscopy for rapid amylose detection is merging with blockchain traceability to create origin-verified low GI certification systems.
Industry Challenges
- Skill gap in resistant starch analytics:Laboratory capacity for standardized RS3 measurement remains concentrated in contract research organizations, creating bottlenecks for quality assurance teams.
- Legacy milling infrastructure retrofit:Conventional parboiling facilities require seven-figure capital deployment to achieve temperature-controlled retrogradation cycles necessary for resistant starch formation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Rice Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Rice, Brown Rice, Basmati Rice, Jasmine Rice End Use: Household, Food Services, Food Processing, Meal Kits Packaging Type: Bags, Boxes, Bulk Containers, Pouches Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Grocery Stores |
| Companies Covered | Ricegrowers Limited, Nestiva, Chaman Lal Setia Exports Ltd., SDLG Radiant Pvt. Ltd., Sugar Watchers Low GI Staples, First Choice Food Products Pvt Ltd., Daawat Foods Ltd., ITC Limited, SunRice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Rice Market Evolving Landscape
Modified starch architectures and rapid glycemic testing protocols are compressing product development cycles. Regulatory divergence between caloric measurement methodologies is forcing dual-track formulation strategies.
High-amylose rice breeding programs are electrifying varietal development pipelines. Australian and Southeast Asian research stations are accelerating germplasm exchange to compress generational selection timelines. This molecular approach is enabling caloric reduction without the textural penalties associated with post-harvest processing.
EFSA's evolving substantiation requirements for glycemic response claims are reshaping clinical trial investment patterns. European importers now demand parallel glucose tolerance study data alongside traditional compositional analysis. Basmati-specific formulations targeting South Asian diaspora markets in the United Kingdom and Canada face the steepest compliance cost escalation.
Direct-to-patient prescription models are emerging through endocrinology practices in Seoul and Tokyo. Clinicians are issuing rice variety recommendations alongside pharmaceutical protocols, bypassing traditional retail discovery. This channel compression is most visible in subscription services tied to continuous glucose monitoring data platforms.
Low Calorie Rice Market Segmentation
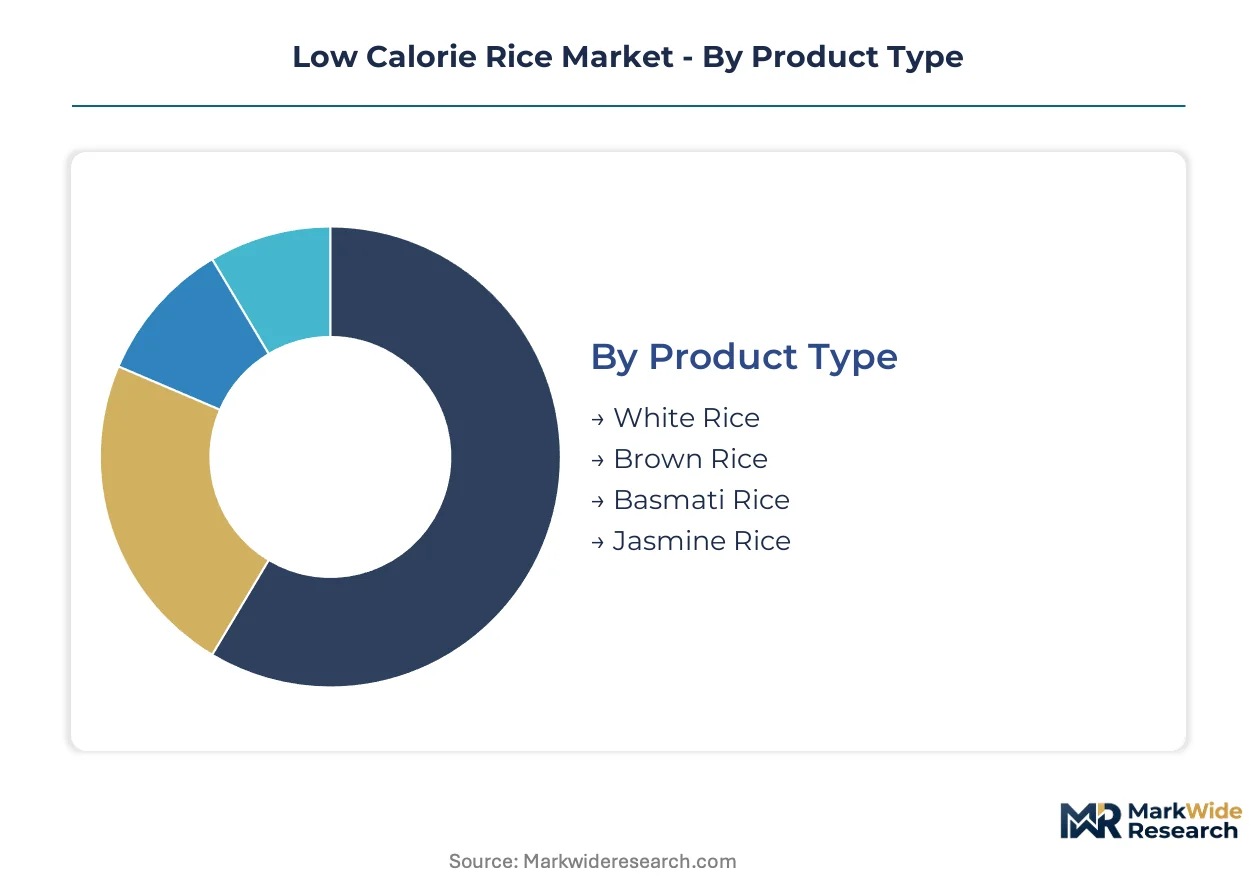
Low calorie rice manufacturers navigate four intersecting dimensions that determine formulation priorities, margin capture, and channel access. Product type dictates starch modification investment and glycemic positioning. End use shapes portion engineering and certification requirements.
Product Type:
Volume leadership sits with modified white rice variants, while premium positioning clusters around heritage-origin basmati with verified amylose ratios.
- White Rice:Milled grains undergo controlled retrogradation or resistant starch enrichment to achieve fifteen to sixty percent caloric reduction. Household demand in South Korea and Japan drives clinical dietary integration through endocrinology clinic recommendations.
- Basmati Rice:Origin-linked aromatic varieties command premium shelf positioning where glycemic credibility supports margin extraction in health food stores and online retail channels serving South Asian diaspora communities in the United Kingdom and Canada.
- Brown Rice:Resistant starch fortification technologies mature fastest in this segment as clean-label positioning resonates with European and North American buyers seeking minimally processed alternatives.
- Jasmine Rice:Southeast Asian aromatic varieties target Southeast Asian export markets where texture preservation competes with caloric reduction specifications.
Today's leader: White Rice. Tomorrow's challenger: Brown Rice.
End Use:
Procurement authority fragments across direct household purchasing, institutional food service contracts, and integrated meal kit platforms with divergent specification requirements.
- Household:Portion-controlled pouch formats dominate as diabetes management protocols in Seoul and Tokyo integrate rice variety selection into clinical dietary regimens.
- Meal Kits:Subscription food service platforms command premium positioning where convenience and glycemic control converge, though penetration remains concentrated in North American and European urban centers.
- Food Services:Nordic healthcare and correctional systems pilot glycemic-controlled staple grain contracts under national wellness mandates, creating procurement reform pressure.
- Food Processing:Ingredient buyers seek standardized resistant starch content for RTE product formulations, facing measurement methodology inconsistencies across FDA and EFSA jurisdictions.
Household consumption anchors current revenue. Meal kit channels are climbing the fastest.
Packaging Type:
Cost-to-convenience tradeoffs separate commodity bulk procurement from precision-portioned premium formats.
- Pouches:Modified atmosphere packaging extends shelf stability while enabling single-serve portion control for subscription platforms and health-conscious household segments.
- Bulk Containers:Institutional food service procurement economies sustain this format despite limited caloric claim verification capabilities at point of use.
- Bags:Conventional retail packaging serves mainstream supermarket channels where price sensitivity limits resistant starch fortification investment.
- Boxes:Premium presentation formats align with gift-oriented purchasing in Asian markets and health food store merchandising requirements.
Premium-mid-economy pricing stratification follows packaging sophistication.
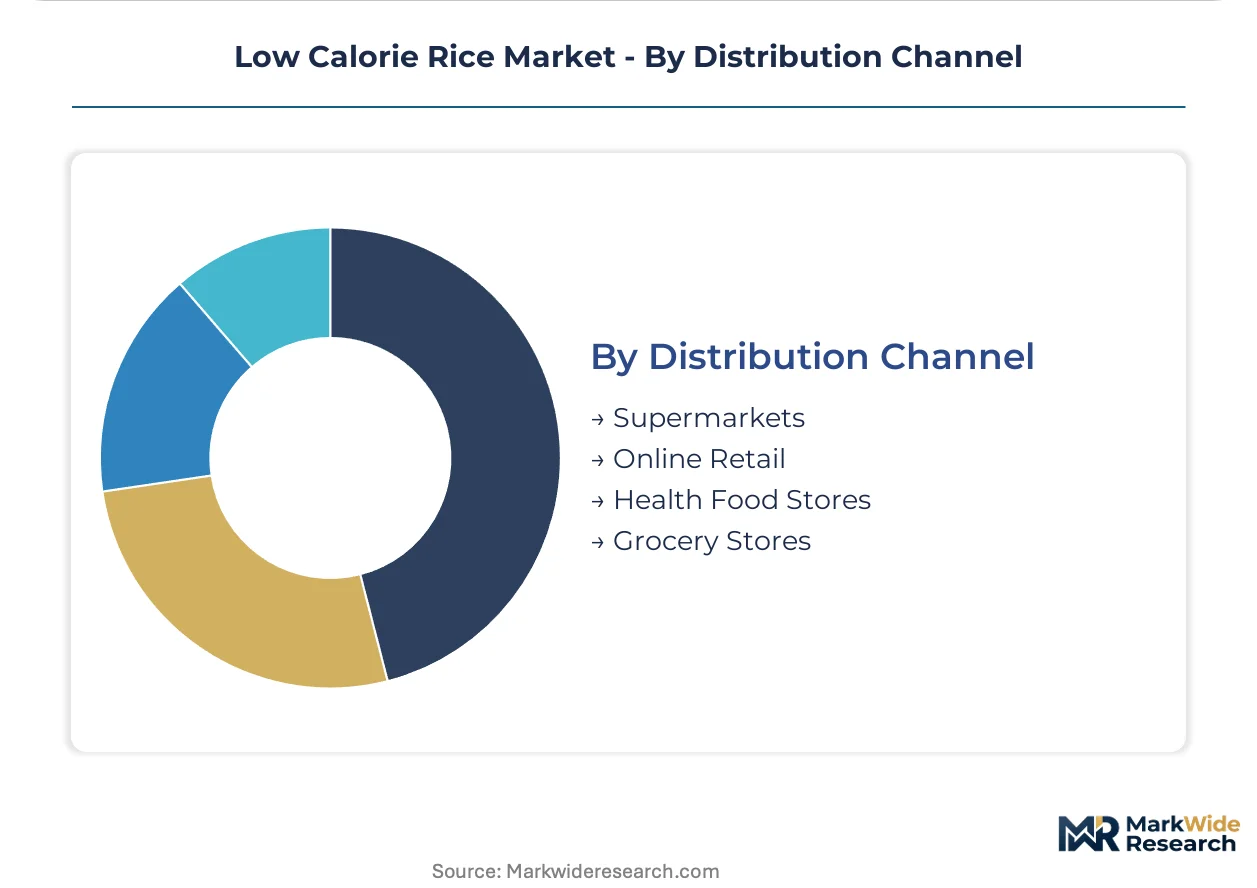
Distribution Channel:
Channel selection determines regulatory compliance burden and health claim substantiation requirements.
- Health Food Stores:Origin-verified low GI certification systems command shelf access where EFSA glycemic response substantiation requirements reshape clinical trial investment patterns.
- Online Retail:Direct-to-patient prescription models through continuous glucose monitoring data platforms compress traditional retail discovery in Seoul and Tokyo metropolitan areas.
- Supermarkets:Mediterranean and Nordic retail chains face EU Green Deal procurement pressure for lower glycemic staple grains.
- Grocery Stores:Conventional mass-market channels prioritize price positioning over resistant starch content verification.
Health food stores extract maximum margin. Online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized agronomists and food biochemists cluster in research corridors stretching from Australia's Riverina to India's Punjab. Their expertise in amylose breeding and resistant starch analytics anchors regional production capabilities. Talent pipelines from Seoul National University and Tokyo University of Agriculture feed quality assurance teams across Northeast Asian processing hubs.
India
Ayurvedic wellness convergence in Mumbai and Delhi-NCR expands household demand beyond clinical diabetes populations. FSSAI fortification standards and packaged food labeling rules reshape domestic formulation pathways. Processing clusters in Haryana and Punjab integrate near-infrared spectroscopy into mill operations for rapid amylose verification.
Japan
Endocrinology clinics in Tokyo and Osaka prescribe specific rice varieties alongside pharmaceutical protocols, compressing traditional retail discovery. METI wellness mandates accelerate institutional procurement reform for glycemic-controlled staples. Kansai region processors pioneer modified atmosphere packaging for subscription meal platforms.
South Korea
Continuous glucose monitoring data platforms in Seoul drive direct-to-patient prescription models bypassing supermarkets. MFDS substantiation requirements for resistant starch claims extend product development timelines. Busan-Ulsan logistics hubs handle bulk import consolidation for specialized amylose-rich germplasm.
Australia
Integrated breeding programs in the Riverina sustain premium positioning across Southeast Asian export channels. EFSA novel food approval pressures force parallel certification tracks for European-bound shipments. Sydney and Melbourne headquarters coordinate blockchain traceability pilots for origin-verified low GI certification.
United Kingdom
South Asian diaspora demand in London and Birmingham concentrates premium basmati positioning in health food retail. EU Green Deal procurement standards reshape Mediterranean and Nordic import specifications. Midlands distribution centers manage cross-channel logistics for resistant starch-enriched brown rice variants.
Low Calorie Rice Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. Vertically integrated millers controlling germplasm breeding and parboiling infrastructure extract premium positioning through origin verification. Asset-light formulators rely on contract manufacturing and brand equity in subscription channels. Three archetypes dominate: integrated agricultural processors, diaspora-focused heritage brands, and clean-label specialists. Competitive intensity centers on backward integration into amylose-rich seedstock and strategic partnerships with continuous glucose monitoring platforms.
Within the integrated processing tier, Ricegrowers Limited and SunRice exemplify Australian-origin agricultural conglomerates with captive breeding infrastructure. Daawat Foods Ltd. occupies a heritage-brand position leveraging basmati-specific formulations for South Asian diaspora channels. ITC Limited anchors the scale-driven segment through extensive rural sourcing networks across Indian metropolitan centers. These three represent contrasting strategic postures: agricultural integration versus brand equity versus distribution density.
| Leading Market Players |
|---|
| Ricegrowers Limited |
| Nestiva |
| Chaman Lal Setia Exports Ltd. |
| SDLG Radiant Pvt. Ltd. |
| Sugar Watchers Low GI Staples |
| First Choice Food Products Pvt Ltd. |
| Daawat Foods Ltd. |
| ITC Limited |
| SunRice |
| Others |
Value Network & Pricing Analysis
Specialized amylose-rich germplasm indices and modified atmosphere packaging resin benchmarks cascade through milling and fortification stages into three distinct pricing tiers that separate origin-certified basmati from commodity white rice variants.
Pricing Analysis
Certification-bundled versus unbundled product offerings split the market into subscription meal-kit premiums and conventional retail transactions. Three-tier pricing structure across premium, standard, and economy levels reflects glycemic index verification costs and resistant starch content thresholds. Cost compression in economy-tier conventional white rice is intensifying because input volatility in specialized seedstock compresses processor margins. Institutional food service buyers exhibit highest price sensitivity while health food store channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Direct-to-patient prescription channels through endocrinology clinics in Seoul and Tokyo handle concentrated demand from diabetes management protocols, bypassing traditional wholesale distribution. Supply concentration spans India's Punjab and Haryana processing belts, Australia's Riverina breeding corridors, and Thailand's aromatic rice export hubs. The chain draws from specialized high-amylose germplasm, modified atmosphere packaging films, and blockchain traceability infrastructure. Single-source vulnerability in resistant starch measurement laboratory capacity creates quality assurance bottlenecks. Distribution runs through health food retail, subscription platforms, and institutional procurement reform pilots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as household consumers in South Korea and Japan shift from price-driven volume purchasing toward glycemic-verified premium specifications.
For Market Incumbents: Anchor premium positioning through captive control over high-amylose seedstock breeding programs and origin-verified certification systems. Defensive consolidation requires retrofitting legacy parboiling infrastructure for temperature-controlled retrogradation cycles. Threat from asset-light formulators in subscription channels demands channel control through continuous glucose monitoring platform partnerships. For New Entrants and Emerging Players: Direct-to-patient digital prescription routes through endocrinology clinics in Seoul and Tokyo offer the most penetrable entry vector. White-space targets include Nordic healthcare institutional procurement reform pilots and South Asian diaspora meal-kit channels in the United Kingdom and Canada. A go-to-market angle centered on clean-label brown rice resistant starch fortification bypasses incumbent white rice volume dominance. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated millers controlling germplasm breeding and parboiling infrastructure. Long-term viability across the projection horizon favors agricultural processors with backward integration into amylose-rich seedstock rather than brand-dependent formulators. The inflection signal to watch is EFSA novel food approval acceleration for emerging starch modification processes.| Strategic Initiative | Industry Significance |
|---|---|
| High-Amylose Germplasm Breeding Program | Captive seedstock supply locks in caloric reduction specifications without texture degradation penalties. |
| Blockchain Traceability Integration | Origin-verified low GI certification commands shelf access in EU Green Deal-compliant Mediterranean retail chains. |
| Resistant Starch Analytics Laboratory Buildout | In-house RS3 measurement capacity eliminates contract research organization bottlenecks for quality assurance teams. |
| Continuous Glucose Monitoring Partnership | Direct-to-patient prescription models through Seoul and Tokyo clinics compress traditional retail discovery cycles. |
| Modified Atmosphere Packaging Scale-Up | Single-serve pouch formats penetrate subscription meal-kit platforms where portion-control convenience extracts premium positioning. |
Research Methodology
Bottom-up household and institutional procurement modeling reconciled against top-down milling capacity and germplasm breeding tracking forms the analytical core of this study. Primary interviews with rice mill operations managers, endocrinology clinic procurement officers, health food store category buyers, and FSSAI regulatory affairs specialists combined with secondary validation from customs trade databases, EFSA novel food approval registers, FSSAI fortification standard filings, and continuous glucose monitoring platform partnership disclosures. Triangulation between demand-side adoption metrics and supply-side processing capacity ensures cross-verified volume and value estimates.
Historical trendline analysis of resistant starch fortification technology maturation and glycemic index certification penetration established baseline growth parameters. Segmentation modeling across product type, end use, packaging format, and distribution channel dimensions generated discrete growth trajectories. CAGRs were derived from elasticity-adjusted adoption curves through the projection horizon. Industry-specific forecast inputs include EFSA substantiation timeline probabilities and MFDS resistant starch claim approval patterns.
Regulatory approval delays, agricultural commodity price volatility in specialized germplasm, and resistant starch measurement methodology standardization failures are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding institutional procurement reform velocity and clean-label positioning resonance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Bioengineered Food Market