
 North America Snack Pellets Market | 2026-2036
North America Snack Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
North America Snack Pellets Market Analytics
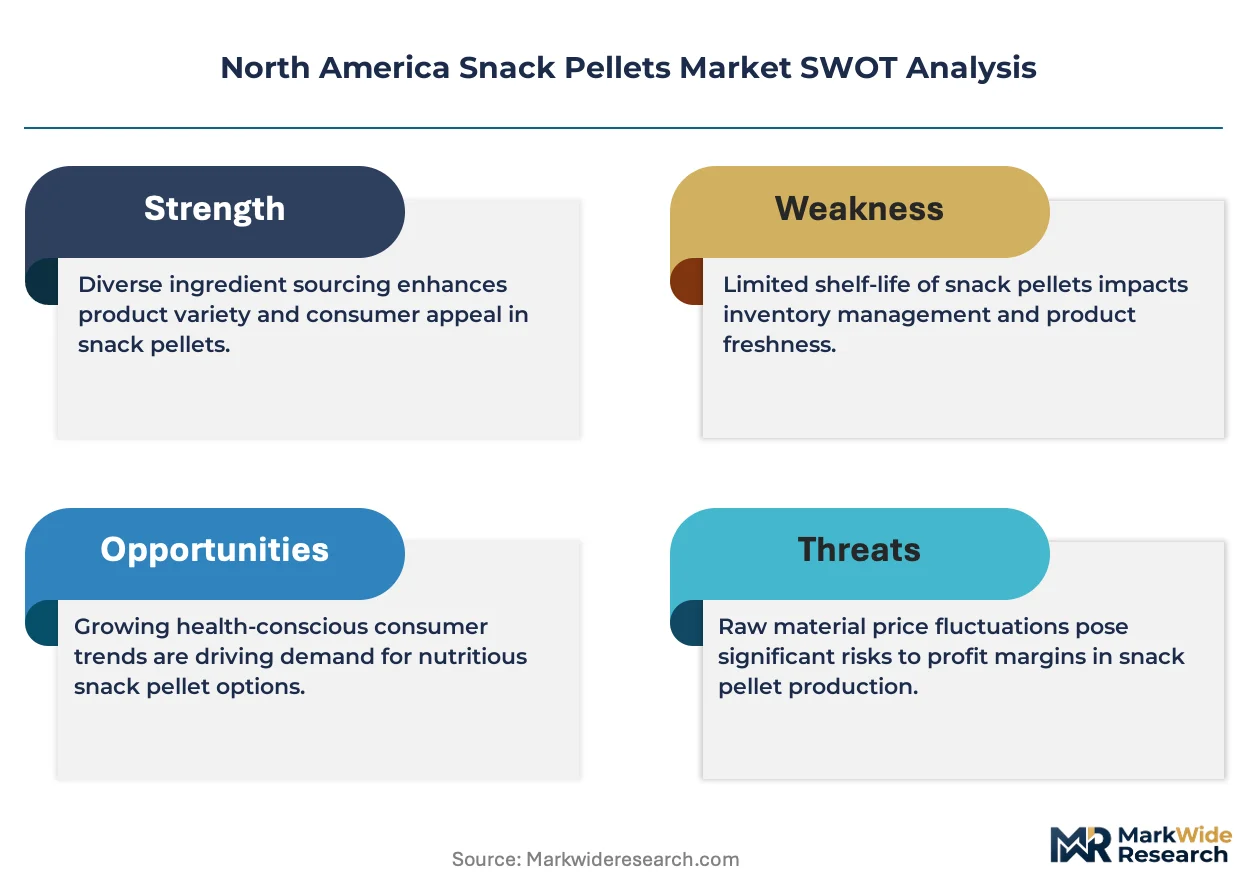
Foodservice channel demand is rebalancing toward pellet-based snack platforms as quick-service chains and cinema concessionaires prioritize operational consistency and extended holding times. J.R. Short Milling Co leverages its Midwest milling infrastructure to anchor supply security for corn-based and multigrain pellet formulations. Calbee competes through specialized texture capabilities spanning crispy, puffed, and baked profiles tailored to North American palates. Balance Foods Inc sustains private-label partnerships that control significant distributor shelf space across convenience store networks.
Snack pellets are semi-finished extruded products manufactured from starch-based doughs—potato, corn, rice, or multigrain blends—that undergo high-pressure extrusion followed by drying to create shelf-stable intermediates later fried or baked by end users. The extrusion process typically operates at barrel temperatures between 120°C and 180°C with moisture content precision between 22% and 28% to achieve uniform expansion and texture reproducibility. Potato-based formulations occupy mature volume positions in retail and private label channels where consumer familiarity supports stable turnover. Multigrain segments lead growth trajectory as clean-label positioning and fiber content claims attract health-oriented retail buyers and foodservice operators reformulating menus. Puffed textures command premium positioning in cinema and entertainment venues where sensory differentiation justifies higher price points.
The FDA governs ingredient declarations, allergen labeling, and nutritional content claims for snack pellets distributed across the United States, while Health Canada and PMRA enforce parallel standards for products entering Canadian provinces. USDA guidelines on whole grain content and the FDA's evolving sodium reduction targets shape formulation decisions, compelling manufacturers to reformulate base recipes or risk exclusion from institutional foodservice contracts. Stakeholders must monitor pending FDA guidance on acrylamide mitigation strategies and state-level packaging regulations in California and New York, as these will determine which extrusion technologies and ingredient systems qualify for continued market access.
Market Dynamics
Foodservice operators across the United States and Canada are rebalancing procurement toward shelf-stable intermediates that compress kitchen labor and equipment requirements. This operational pivot concentrates demand around extrusion facilities in the Great Lakes corridor.
Growth Catalysts
- Clean-label reformulation mandates:The FDA's updated Nutrition Facts labeling requirements and trans fat restrictions compel manufacturers to develop multigrain formulations with cleaner ingredient decks.
- Cinema and entertainment venue expansion:Puffed texture pellets command premium positioning in cinema concessionaires where sensory differentiation supports higher price realization.
- Midwest extrusion infrastructure:Processing hubs in Illinois, Michigan, and Ohio provide integrated grain supply chains and high-capacity extrusion lines that anchor supply security.
Market Restraints
- Acrylamide mitigation uncertainty:Pending FDA guidance on acrylamide reduction strategies creates formulation risk and may disqualify certain extrusion technologies from market access.
- Input cost volatility:Corn and potato starch prices fluctuate with agricultural commodity cycles, compressing margin predictability for pellet manufacturers.
- State-level packaging fragmentation:Divergent regulations in California and New York impose compliance complexity that raises operational overhead for interstate distribution.
Strategic Opportunities
- Canadian foodservice penetration:Health Canada and PMRA standards align closely with U.S. frameworks, enabling streamlined cross-border expansion for compliant manufacturers.
- Private-label convenience store channels:Distributor shelf space controlled through captive partnerships offers volume scaling outside branded retail competition.
- Fiber-forward positioning:USDA whole grain content guidelines create formulation pathways for health-oriented retail buyers seeking fiber content claims.
Industry Challenges
- Extrusion technician scarcity:Precision moisture control between 22% and 28% and barrel temperature management at 120°C to 180°C require specialized operators in short supply across the Great Lakes manufacturing corridor.
- Legacy equipment integration:Foodservice operators adopting pellet platforms must reconfigure frying or baking lines, creating capex friction and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Snack Pellets Market |
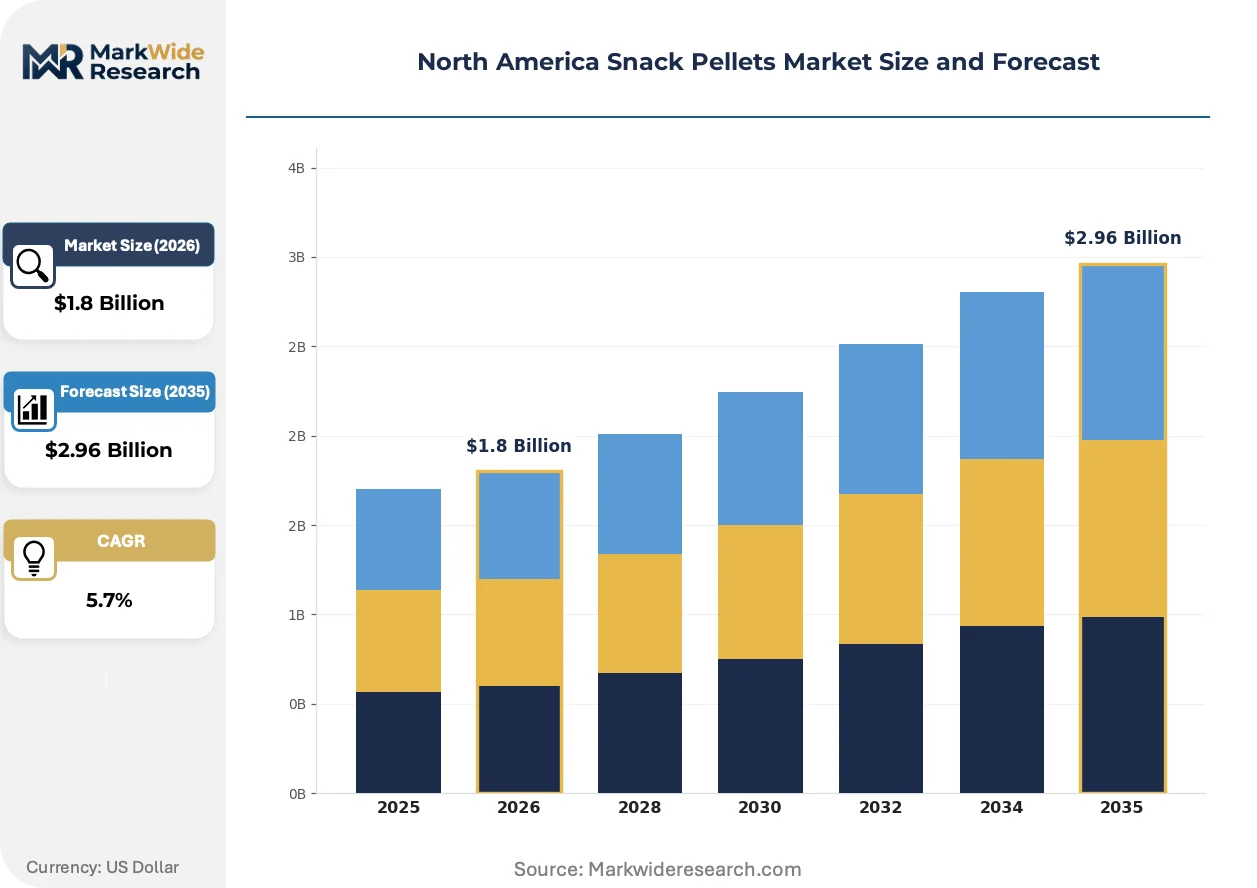
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato-based, Corn-based, Rice-based, Multigrain End User: Retail, Foodservice, Private Label, Industrial Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Distributors Texture: Crispy, Chewy, Puffed, Baked |
| Companies Covered | Balance Foods Inc, J.R. Short Milling Co, LC America, Inc., Calbee, BACH SNACKS SAL, GRUPO MICHEL, Crum Snack USA, Festida Foods Ltd, Heartland Harvest, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Snack Pellets Market Evolving Landscape
Extrusion technology and regulatory compliance frameworks are converging to reshape how starch-based intermediates reach foodservice and retail channels. Three developments dominate the transformation trajectory.
Advanced die-design extrusion is unifying texture reproducibility across crispy, puffed, and baked profiles within single production lines. Quick-service chains and cinema concessionaires are adopting these systems to reduce SKU complexity and inventory overhead. This capability compression is unifying what previously required separate equipment investments, flattening capital barriers for mid-scale operators.
The FDA's evolving sodium reduction targets are forcing base recipe reformulation across institutional foodservice contracts. Manufacturers must adjust ingredient systems or face exclusion from school, hospital, and corporate dining procurement pools. Potato-based formulations in retail channels face the steepest adaptation requirements due to established consumer taste expectations.
Buyer concentration among national quick-service chains is compressing switching cycles and demanding extended holding-time guarantees. Regional distributors are losing share to direct manufacturer relationships that promise supply security and technical support. This channel consolidation is most visible in the U.S. Great Lakes states where processing capacity concentrates and logistics costs favor large-contract structures.
North America Snack Pellets Market Segmentation
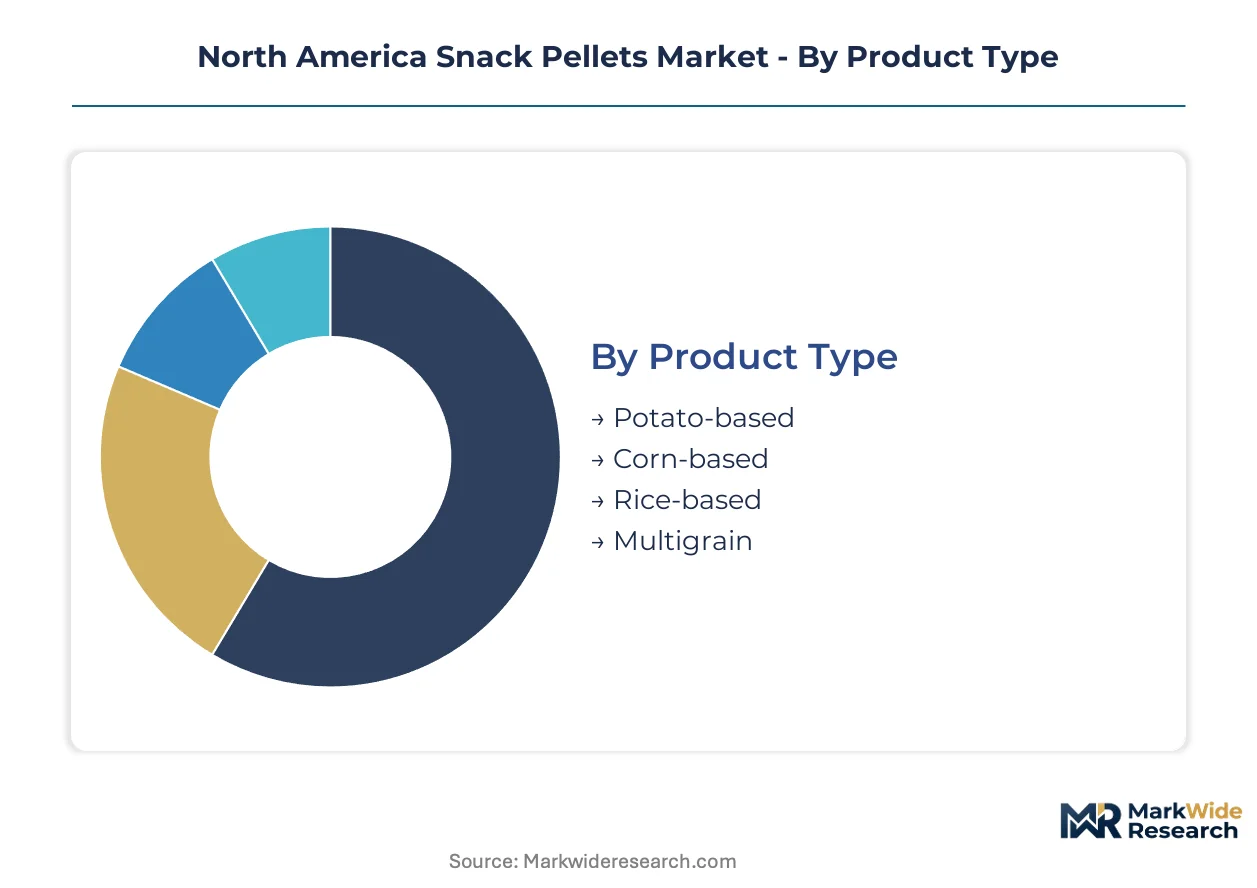
Segmentation in the North America Snack Pellets Market reveals how formulation choices, channel strategies, and texture specifications align with distinct buyer economics across the United States and Canada. Manufacturers calibrate production lines to serve divergent operational requirements between retail shelf-stable demands and foodservice extended-holding protocols.
Product Type:
Buyers differentiate by raw material cost exposure, clean-label positioning latitude, and extrusion equipment compatibility.
- Multigrain:Blends incorporating corn, rice, and ancient grains enable fiber content claims that satisfy USDA whole grain guidelines and FDA nutrition labeling requirements. Demand concentrates in health-oriented retail channels across California and New York where clean-label premiums justify formulation complexity. Reformulation activity accelerates as trans fat restrictions eliminate legacy recipes.
- Potato-based:Starch-dominant formulations deliver familiar taste profiles with established consumer acceptance in mass retail. The segment anchors volume in private-label partnerships controlled by distributors across the Great Lakes corridor, though sodium reduction targets force base recipe adaptation.
- Corn-based:Cost-efficient extrusion feedstock leveraged by J.R. Short Milling Co's Midwest infrastructure for supply security.
- Rice-based:Neutral flavor platform enabling regional seasoning customization for ethnic snack applications.
Potato-based pellets lead volumes today; multigrain formulations are gaining share fastest.
End User:
Procurement patterns diverge sharply between buyers optimizing for brand control versus those prioritizing operational flexibility.
- Foodservice:Quick-service chains and cinema concessionaires demand extended holding-time guarantees and texture reproducibility across frying or baking lines. Operational pivots toward shelf-stable intermediates compress kitchen labor requirements and equipment footprints. Direct manufacturer relationships displace regional distributors in the U.S. Great Lakes states where processing capacity concentrates.
- Retail:Branded and private-label packaged goods requiring stable turnover velocity and established consumer familiarity. Potato-based formulations dominate shelf positioning where price sensitivity limits premium experimentation.
- Private Label:Distributor-controlled shelf space in convenience store networks enables volume scaling outside branded competition.
- Industrial:Intermediate buyers integrating pellets into composite snack products or co-manufacturing arrangements.
Retail channels anchor current revenue; foodservice procurement is expanding most quickly.
Distribution Channel:
Channel selection determines margin structure, inventory velocity, and compliance burden exposure.
- Distributors:Consolidated relationships with national quick-service chains and cinema networks demand supply security commitments and technical support capabilities. Channel concentration is most pronounced in Illinois, Michigan, and Ohio where logistics costs favor large-contract structures.
- Convenience Stores:Captive private-label partnerships controlled through Balance Foods Inc sustain significant shelf space with localized assortment strategies.
- Supermarkets:Mass retail velocity requirements favor potato-based formulations with proven consumer acceptance.
- Online Retailers:Direct-to-consumer experimentation with premium multigrain and puffed texture assortments.
Distributor networks dominate transaction volumes today; convenience store channels are climbing the fastest.
Texture:
Texture specification drives capital equipment requirements, die-design complexity, and price realization potential.
- Puffed:High-expansion extrusion requiring precise moisture control between 22% and 28% and barrel temperatures at 120°C to 180°C. Calbee specializes in these systems for cinema and entertainment venues where sensory differentiation commands premium positioning. Acrylamide mitigation uncertainty creates formulation risk pending FDA guidance.
- Crispy:Standard extrusion profile serving broad retail and foodservice applications with reproducible frying outcomes.
- Baked:Lower-oil positioning aligned with health-oriented menu reformulation in institutional foodservice contracts.
- Chewy:Specialized density profile for ethnic snack and confectionery hybrid applications.
Crispy textures lead production volumes today; puffed profiles show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes manufacturing corridor anchors North American snack pellet production, with extrusion infrastructure clustering around grain supply chains in Illinois, Michigan, and Ohio.
United States
Foodservice operators across quick-service chains and cinema concessionaires drive procurement of shelf-stable intermediates that compress kitchen labor requirements. The FDA's updated Nutrition Facts labeling requirements and trans fat restrictions compel multigrain reformulation across institutional foodservice contracts. Processing capacity concentrates in the Great Lakes states where J.R. Short Milling Co leverages Midwest grain infrastructure for supply security.
Canada
Cross-border foodservice expansion creates demand alignment with U.S. operational standards among Canadian quick-service chains. Health Canada and PMRA enforce parallel labeling and nutritional content standards that streamline compliance for exporters from the Great Lakes corridor. Ontario and Quebec processing facilities serve regional convenience store networks with private-label pellet formulations.
Mexico
Industrial buyers in Mexico integrate imported pellets into composite snack products for domestic retail distribution. The country's national food safety regulator enforces ingredient declaration standards that align with North American trade frameworks. Northern border states concentrate demand for cost-efficient corn-based formulations serving price-sensitive retail channels.
North America Snack Pellets Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers scale extrusion lines to capture foodservice procurement consolidation. The market structures around three tiers: integrated grain processors with captive milling infrastructure, specialized texture specialists, and private-label contract manufacturers. Strategic archetypes include Midwest grain-anchored processors, Japanese texture technology providers, and distributor-captive private-label suppliers. Competitive moves concentrate on direct manufacturer relationships displacing regional distributors and portfolio diversification into multigrain formulations.
Within the grain-integrated processor tier, J.R. Short Milling Co exemplifies supply security through Midwest milling infrastructure. Calbee occupies a position among texture specialists leveraging die-design capabilities for puffed and crispy profiles. Balance Foods Inc represents the private-label contract archetype with distributor-captive shelf space across convenience store networks.
| Leading Market Players |
|---|
| Balance Foods Inc |
| J.R. Short Milling Co |
| LC America, Inc. |
| Calbee |
| BACH SNACKS SAL |
| GRUPO MICHEL |
| Crum Snack USA |
| Festida Foods Ltd |
| Heartland Harvest, Inc. |
| Others |
Value Network & Pricing Analysis
Quick-service chain procurement consolidation across the U.S. Great Lakes corridor is forcing pellet manufacturers to reconfigure extrusion capacity and absorb input volatility, compressing margin structures for mid-scale operators unable to secure long-term grain contracts.
Pricing Analysis
Corn and potato starch input-cost pass-through dominates pellet pricing, with contract structures tethering quarterly adjustments to agricultural commodity indices. Price differentiation rests on texture complexity and clean-label certification tiers, with puffed profiles commanding premiums over standard crispy formulations. Cost compression in economy-tier potato-based segments is intensifying due to buyer concentration among national distributors. Private-label convenience store channels exhibit highest price sensitivity, while cinema concessionaires show lowest sensitivity due to sensory differentiation requirements.
Supply Chain Analysis
Dual-sourcing mandates from major quick-service chains require manufacturers to qualify backup extrusion facilities, anchoring primary supply in Illinois, Michigan, and Ohio while developing secondary relationships with Ontario processors. The supply chain draws from corn belt harvests, potato starch imports, and multigrain blends sourced through Midwest grain elevators. Single-source vulnerability concentrates around specialized die-design equipment for puffed textures. Distribution runs through direct manufacturer relationships with national chains, displacing regional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Snack Pellets Market functions as a geographic-arbitrage play where Canadian foodservice expansion offers margin expansion against U.S. sodium-reduction compliance costs, with Health Canada standards enabling streamlined cross-border formulation reuse.
For Market Incumbents: Deepen backward integration into captive corn milling capacity to insulate margins from agricultural commodity swings. Secure extended holding-time certification for puffed textures to defend against emerging texture-technology specialists. Prioritize direct manufacturer relationships with consolidating quick-service chains to lock out regional distributor competitors.
For New Entrants and Emerging Players: Advanced die-design extrusion systems enabling single-line texture flexibility offer entry into mid-scale foodservice operators previously excluded by capital barriers. Target Canadian quick-service chains seeking U.S.-compatible supply standards with localized Ontario production. Deploy technical service partnerships as primary go-to-market mechanism to overcome incumbent supply-security advantages.
For Investors and Strategic Acquirers: Asymmetric upside sits with private-label contract manufacturers controlling captive convenience store shelf space. Long-term viability hinges on multigrain formulation capabilities aligned with evolving FDA sodium targets. Watch pending FDA acrylamide guidance as inflection indicator that could disqualify legacy extrusion assets and trigger consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Multigrain Formulation Expansion | Positions manufacturers for FDA sodium reduction compliance and USDA whole grain procurement contracts. |
| Direct Foodservice Channel Development | Bypasses regional distributors to capture margin from consolidating quick-service chain procurement. |
| Cross-Border Canadian Capacity | Leverages Health Canada alignment with U.S. standards for geographic arbitrage in foodservice expansion. |
| Advanced Die-Design Extrusion Investment | Enables single-line production of crispy, puffed, and baked profiles to reduce SKU complexity. |
| Acrylamide Mitigation Technology | Preempts FDA guidance risk that could disqualify conventional extrusion systems from market access. |
Research Methodology
Direct dialogue with extrusion plant managers, quick-service chain procurement directors, convenience store category buyers, and FDA regulatory affairs specialists grounded qualitative insights, cross-referenced with USDA grain supply reports, FDA guidance documents, Health Canada standards, and SEC filings from publicly traded food manufacturers. Bottom-up facility capacity assessments and top-down channel revenue estimates were triangulated to validate market sizing.
Segment-level projections across product type, end user, distribution channel, and texture specifications were generated through the analytical framework, with CAGRs derived from extrusion capacity expansion schedules and foodservice procurement growth patterns. Key inputs included grain price forecasting models, quick-service chain unit expansion plans, and regulatory compliance timeline assumptions.
The model holds under stable FDA sodium reduction implementation and Health Canada alignment; deviation in acrylamide guidance stringency or agricultural commodity volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Savory Snack Products Market
Snacks
Extruded Cereals Market
Snacks
Snack Bar Market
Snacks
North America Energy Bar Market
Snacks
Specialty Snacks Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Low Calorie Crackers Market
Snacks
Meat Snacks Market
Snacks
Europe Snack Bar Market
Snacks
Refrigerated Snacks Market
Snacks
Spain Snack Bar Market
Snacks
South Africa Snack Bar Market
Snacks
Latin America Extruded Snack Food Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
Low Sugar Fruit Snacks Market
Snacks
Allergy-Free Snacks Market