
 Snack Products Market | 2026-2036
Snack Products Market Size, Share, and Industry Trends Forecast 2026-2036
Snack Products Market Outlook
Buyer concentration across the snack products landscape is broadening as convenience stores, quick-service restaurants, and direct-to-consumer subscription services fragment traditional supermarket dominance. PepsiCo Inc. leverages its vertical integration across potato sourcing and flavor technology to control cost structures in the chips segment. Mondelez International Inc. anchors its position through deep distribution networks in emerging economies. Mars Inc. differentiates via pet-care-to-snack cross-promotional ecosystems that sustain brand loyalty.
Snack products encompass ready-to-eat food items manufactured through baking, frying, extrusion, or cold-pressing, typically packaged for immediate consumption with shelf stability ranging from weeks to eighteen months depending on moisture content and barrier materials. Their primary commercial purpose centers on satisfying between-meal hunger occasions while delivering flavor intensity, portability, and portion-controlled caloric intake. The ingredient type dimension shows high-protein and gluten-free formulations capturing margin pools as functional snacking displaces indulgence-only purchasing, while chips retain volume leadership across supermarket and convenience channels. E-commerce distribution is accelerating fastest among channels as replenishment algorithms and subscription bundling reduce customer acquisition costs.
The FDA governs nutrition labeling and allergen declarations for snack products distributed in the United States, while the EU Green Deal and F-Gas Regulation constrain packaging material choices and refrigeration-dependent supply chains across European markets. India's FSSAI enforces progressively stricter limits on trans-fat content and artificial additive usage, compelling reformulation investments for multinational entrants. Stakeholders must monitor how divergent packaging sustainability mandates across these jurisdictions reshape capital allocation between biodegradable films and conventional multi-layer barriers.
Market Dynamics
Clean-label ingredient mandates and plant-based formulation advances are compressing R&D cycles while fragmenting supply chains across the snack products landscape. Manufacturers must now reconcile shorter product lifecycles with extended shelf-stability requirements as regulatory thresholds tighten in multiple jurisdictions simultaneously.
Growth Catalysts
- EU Green Deal packaging mandates:Biodegradable film adoption is accelerating reformulation investments and opening premium positioning for compliant producers across German and French retail channels.
- Extrusion technology advancement:High-moisture extrusion processes enable convincing meat analog textures in protein snacks, expanding addressable occasions beyond traditional indulgence segments.
- Urban snacking frequency in China:Tier-one city consumption patterns normalize multiple daily snack occasions, driving volume expansion in portion-controlled formats through convenience store networks.
Market Restraints
- Palm oil price volatility:Input cost swings constrain margin predictability for fried snack categories dependent on Southeast Asian supply origins.
- FDA allergen declaration complexity:Cross-contamination testing requirements extend production changeover times and complicate multi-SKU manufacturing lines.
- Refrigerated supply chain gaps:Cold-chain infrastructure deficits in emerging markets limit distribution reach for fresh-format snack alternatives.
Strategic Opportunities
- India FSSAI trans-fat limits:Reformulation service demand creates B2B revenue streams for flavor houses and oil technology providers serving multinational entrants.
- Quick-service restaurant snack integration:Daypart expansion into between-meal occasions opens co-development partnerships for shelf-stable companion products.
- Direct-to-consumer subscription algorithms:Replenishment data capture enables predictive flavor preference modeling and reduced customer acquisition costs.
Industry Challenges
- Clean-label formulation expertise scarcity:Natural preservative chemistry and clean-label texturizer sourcing strain technical talent pools in mid-tier manufacturers.
- Multi-layer barrier recycling incompatibility:Conventional packaging materials face mounting Extended Producer Responsibility compliance costs across EU member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snack Products Market |
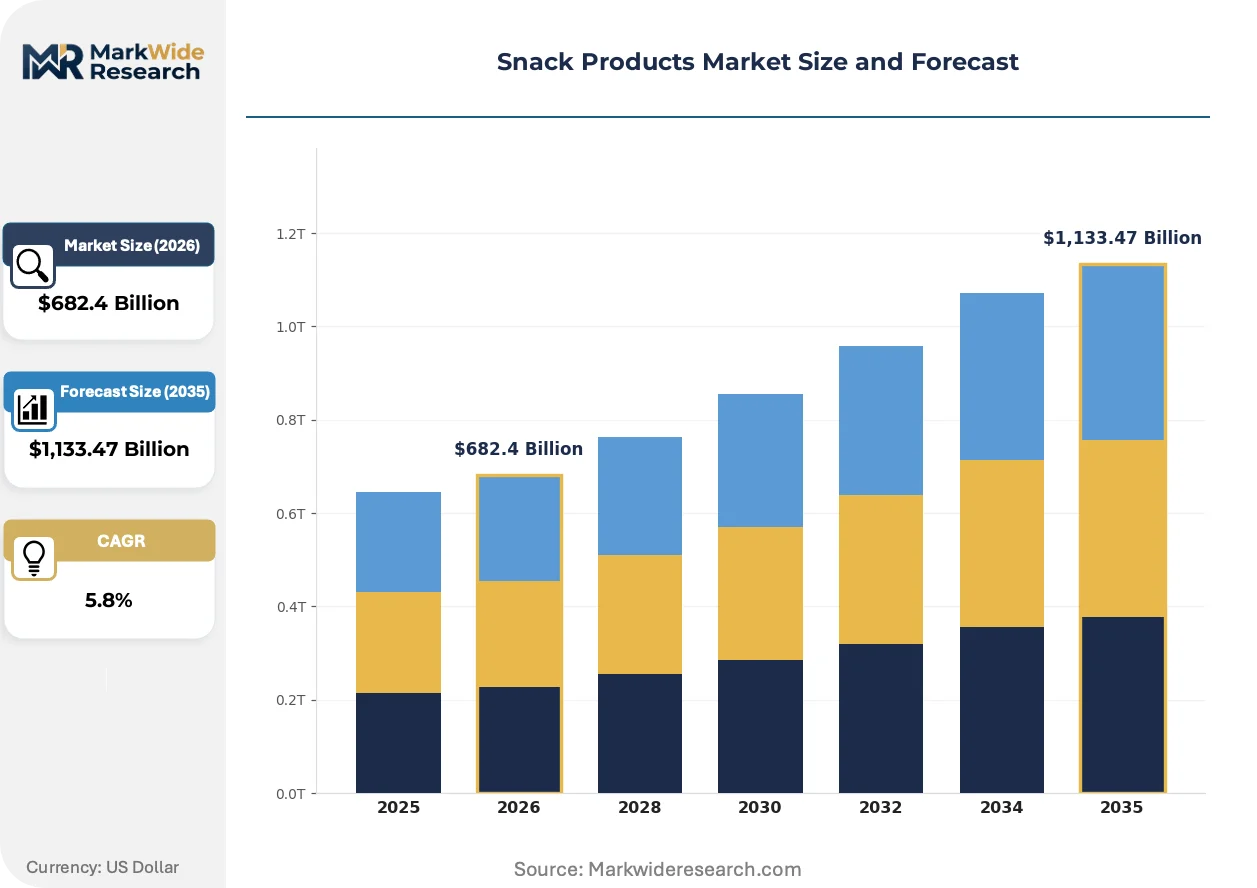
| Market Size in 2026 | $682.4 Billion |
| Market Size in 2035 | $1,133.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Nuts, Bars, Cookies Ingredient Type: Organic, Gluten-Free, Vegan, High-Protein Packaging Type: Bags, Boxes, Pouches, Tins Distribution Channel: Supermarkets, Convenience Stores, E-Commerce, Health Food Shops |
| Companies Covered | PepsiCo Inc., Mondelez International Inc., Mars Inc., Nestle S.A., Kellogg Company, General Mills Inc., Conagra Brands Inc., Calbee Inc., The Kraft Heinz Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snack Products Market Strategic Shifts
Automation and algorithmic decision-making are penetrating formulation, manufacturing, and distribution simultaneously, compressing the gap between consumer signal detection and product response. These capabilities are redrawing competitive boundaries between capital-rich multinationals and agile regional specialists.
High-throughput screening platforms for natural flavor compounds is automating the identification of clean-label alternatives to artificial additives, collapsing development timelines from months to weeks. Mid-sized manufacturers in the United States and Germany are deploying these systems to match multinational speed-to-market. The technology is automating sensory mapping and accelerating reformulation cycles for regulatory compliance deadlines.
The EU F-Gas Regulation and parallel state-level refrigerant restrictions in California are forcing cold-chain-dependent snack categories toward ambient-stable alternatives or capital-intensive refrigeration retrofits. Manufacturers serving European markets face compressed equipment replacement windows and stranded asset risk in legacy cooling infrastructure. Fresh-format protein snacks and dairy-based offerings bear the highest compliance burden, with some producers pivoting toward retort-processed shelf-stable formats.
Subscription bundling and replenishment algorithms are fragmenting traditional supermarket replenishment power, enabling direct relationships between snack brands and repeat purchasers. Convenience stores and quick-service outlets are responding with loyalty-integrated mobile ordering to retain traffic. This pattern concentrates most visibly in United States coastal metros and Chinese tier-one cities where digital payment penetration supports seamless subscription management.
Snack Products Market Segmentation
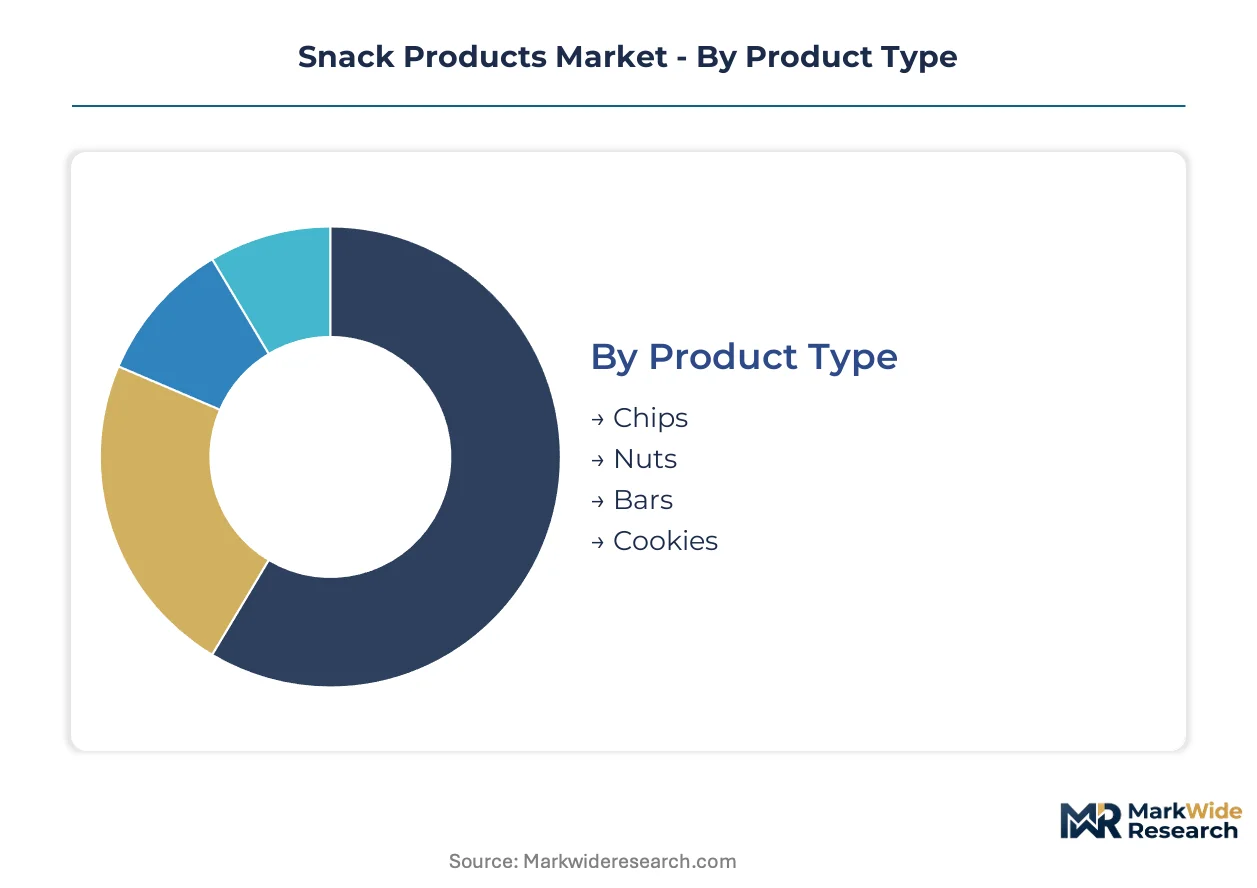
Segmentation in snack products reveals how formulation priorities, packaging economics, and channel access costs fragment buyer groups. Manufacturers must align R&D spend and shelf positioning to the distinct margin structures and replenishment cadences that separate indulgence purchasers from functional snack adopters.
Product Type:
Buyers in this category separate by consumption occasion length and flavor intensity tolerance rather than demographic profile alone.
- Chips:Thin-sliced potato or extruded starch substrates fried or baked to sub-2% moisture targets, delivering immediate salt-fat flavor saturation. Demand concentrates in United States convenience store networks and German petrol station retail, where single-serve impulse velocity rewards packaging speed over ingredient complexity. Portion-controlled 28-gram sachets are displacing family bags in urban Chinese vending channels.
- Bars:Cold-extruded or slab-formed matrices combining proteins, binders, and inclusions into shelf-stable 40-60 gram units. High-protein and meal-replacement occasions in United States coastal metros and London financial districts drive premium positioning, with clean-label formulations commanding price multiples over conventional candy bars. Refrigerated protein bar segments face EU F-Gas Regulation compliance costs that ambient-stable formats avoid.
- Nuts:Roasted or raw tree nuts and legumes, dry- or oil-roasted with seasoning adhesion via tumbling or spray technologies.
- Cookies:Baked wheat or alternative flour matrices with fat-sugar structural frameworks, ranging from crisp to chewy textures.
Volume sits with chips; growth tilts toward bars.
Ingredient Type:
Cost tier separates buyers here, with certification premiums creating distinct procurement workflows and supplier qualification demands.
- High-Protein:Formulations achieving minimum 20% protein content through dairy isolates, plant concentrates, or insect flour integration, requiring moisture management to prevent Maillard-driven off-flavors during shelf life. United States gym-adjacent retail and Chinese tier-one city convenience stores concentrate demand, with collagen and pea protein sources gaining formulation share as whey costs fluctuate. Retort processing enables ambient distribution where cold-chain infrastructure remains deficient.
- Gluten-Free:Products formulated without wheat, barley, or rye inputs, relying on rice, tapioca, or almond flour matrices with hydrocolloid binders to replicate gluten-network functionality. Celiac-diagnosed consumers and discretionary avoiders in Germany and United States coastal states sustain the segment, with FDA allergen declaration requirements extending label complexity for multi-SKU manufacturers.
- Organic:Certified synthetic pesticide-free ingredient sourcing with supply chain documentation requirements.
- Vegan:Exclusion of all animal-derived inputs, requiring plant-based emulsifiers and flavor carriers.
Mainstream formulations capture volume; high-protein and gluten-free segments are climbing the fastest.
Packaging Type:
Supply concentration in flexible film converting determines buyer access to barrier performance tiers and sustainability positioning.
- Pouches:Multi-layer laminates or monomaterial structures with resealable zipper or laser-scored features, offering surface-area-to-volume ratios that optimize shelf presence and shipping cube efficiency. E-commerce subscription services in United States and Chinese direct-to-consumer channels favor pouches for dimensional weight savings, though EU Extended Producer Responsibility fees are pressuring converters toward recyclable mono-PE structures.
- Bags:Form-fill-seal pillow or gusseted configurations in single-web or laminate constructions, dominating high-velocity chips and extruded snacks.
- Boxes:Paperboard secondary packaging with primary film or tray inserts, common in premium cookie and bar assortments.
- Tins:Metal or rigid paperboard cylindrical containers, residual in gift and seasonal cookie segments.
Operational scale favors bags; sustainability mandates and e-commerce growth favor pouches.
Distribution Channel:
Customer acquisition cost and replenishment data ownership separate channel strategies, with algorithmic inventory management creating divergent margin structures.
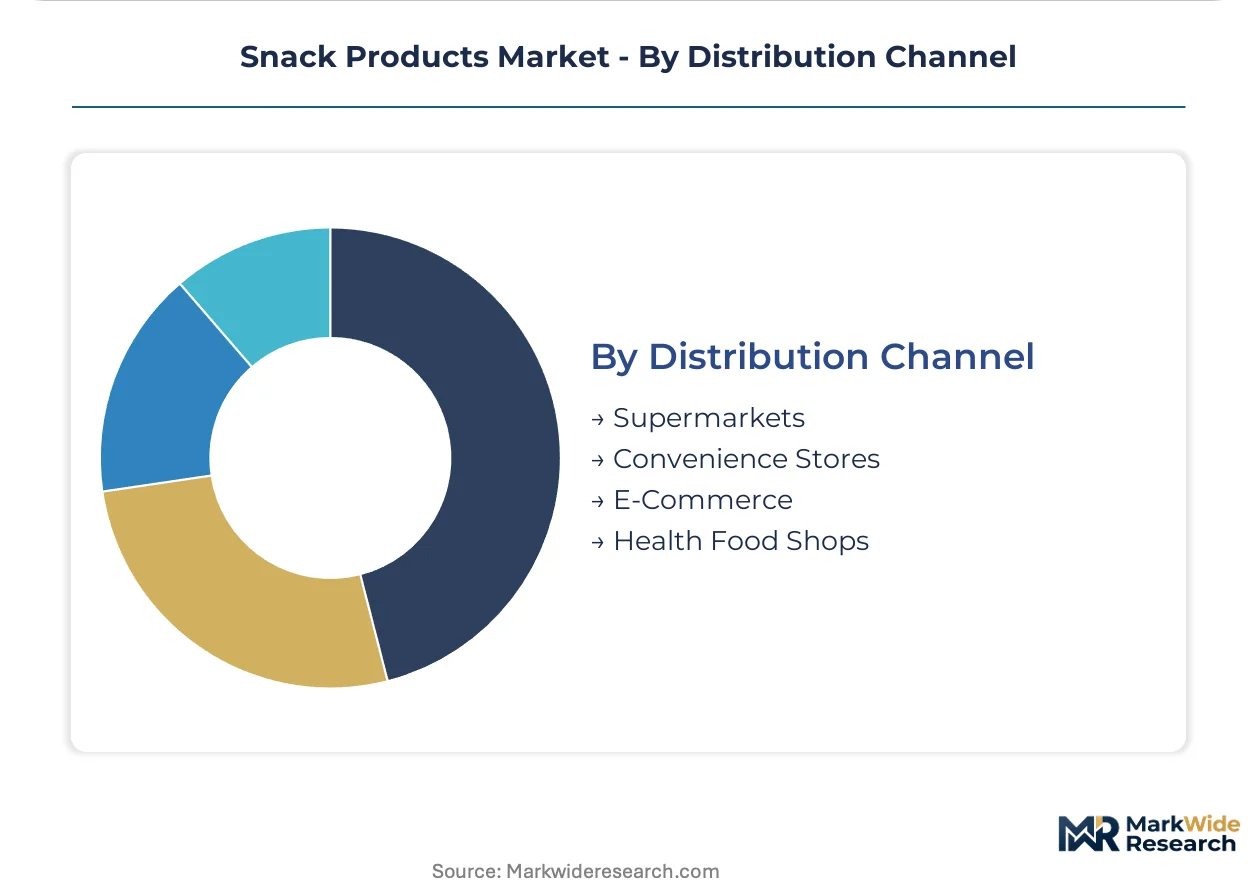
- E-Commerce:Direct-to-consumer and third-party marketplace fulfillment with replenishment algorithm integration, enabling predictive flavor preference modeling and subscription bundling. United States and Chinese urban markets concentrate adoption, where digital payment penetration supports seamless auto-replenishment and customer lifetime value calculations exceed traditional retail.
- Convenience Stores:High-frequency, small-format retail with limited SKU counts and rapid inventory turns, prioritizing single-serve and immediate-consumption pack sizes.
- Supermarkets:Full-assortment retail with category management negotiations and promotional fund requirements.
- Health Food Shops:Curated specialty retail with educated staff and certification-focused merchandising.
Supermarkets retain volume; e-commerce represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Potato cultivation belts in Idaho and North Dakota anchor North American raw material flows, while Southeast Asian palm oil plantations supply frying fat inputs to Asian processing clusters. These geographic dependencies shape where extrusion and flavor compounding capacity concentrates.
United States
Convenience store network expansion and quick-service restaurant daypart extension drive portion-controlled format demand. FDA nutrition labeling and allergen declaration requirements extend production changeover times for multi-SKU manufacturers. Chicago and Dallas-Fort Worth metropolitan areas concentrate co-manufacturing capacity serving private-label retail programs.
Germany
Petrol station retail and urban vending machine networks normalize multiple daily snack occasions. EU Green Deal packaging mandates and Extended Producer Responsibility fees press converters toward recyclable mono-PE structures. Bavaria hosts flexible film converting clusters adapting barrier specifications to biodegradable compliance deadlines.
China
Tier-one city convenience store penetration and digital payment integration enable subscription replenishment models. SAMR food safety standards and dual carbon goals constrain processing energy intensity and packaging material choices. Yangtze River Delta manufacturing zones concentrate extrusion equipment fabrication and flavor compounding capacity.
India
Urban snacking frequency climbs as organized retail expands beyond traditional kirana stores. FSSAI trans-fat limits and artificial additive restrictions compel reformulation investments from multinational entrants. Maharashtra and Gujarat host oil processing and seasoning adhesion technology clusters serving domestic and export markets.
Japan
Aging demographics and single-person households sustain demand for portion-controlled, shelf-stable formats. METI energy efficiency standards and plastic resource circulation laws reshape packaging material selection and processing equipment retrofits. Kanto region concentration of convenience store headquarters drives product development specifications for the domestic market.
Snack Products Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue functional and clean-label positioning to capture premium margin pools. The vendor base spans capital-rich multinationals with captive distribution, mid-tier regional specialists with co-manufacturing flexibility, and niche insurgents leveraging direct-to-consumer channels. Strategic archetypes include vertical integrators controlling upstream potato and flavor inputs, platform brands bundling subscription replenishment, and private-label suppliers serving retailer consolidation. Competitive moves center on portfolio diversification into high-protein and plant-based formats, plus geographic expansion through emerging market distribution partnerships.
Among North American-dominant conglomerates, PepsiCo Inc. and Mondelez International Inc. exemplify scale-driven archetypes with upstream control over raw material sourcing and flavor technology development. Mars Inc. occupies a distinct position spanning snack and adjacent consumer categories, enabling cross-promotional ecosystems that sustain repeat purchase frequency. These three entities anchor the competitive structure against which mid-tier manufacturers and direct-to-consumer entrants position reformulation speed and channel flexibility as counterweights.
| Leading Market Players |
|---|
| PepsiCo Inc. |
| Mondelez International Inc. |
| Mars Inc. |
| Nestle S.A. |
| Kellogg Company |
| General Mills Inc. |
| Conagra Brands Inc. |
| Calbee Inc. |
| The Kraft Heinz Company |
| Others |
Value Chain & Pricing Dynamics
Premium-mid-economy pricing differentiation in snack products manifests through certification ladders and formulation complexity, with clean-label and high-protein tiers commanding multiples over commodity chips while supply chains bifurcate between captive potato sourcing and outsourced specialty ingredient procurement.
Pricing Analysis
Service-bundling in snack pricing separates subscription replenishment models with predictive flavor algorithms from transactional convenience store purchases, with the former capturing lifetime value premiums and the latter competing on single-serve velocity. Three-tier pricing structure across premium, standard, and economy levels aligns with ingredient certification grade and moisture management technology, as clean-label formulations with natural preservatives justify shelf price multiples. Cost compression in economy chips is intensifying because palm oil price volatility from Southeast Asian origins constrains margin predictability. Quick-service restaurant buyers exhibit highest price sensitivity due to daypart volume commitments, while direct-to-consumer subscribers show lowest sensitivity given auto-replenishment convenience lock-in.
Supply Chain Analysis
Palm oil supply rests on Indonesian and Malaysian plantation networks, with secondary concentration in Philippine coconut oil alternatives for premium frying applications. Potato sourcing draws from Idaho and North Dakota cultivation belts in the United States, plus German and Polish starch processing clusters for extruded substrates. Single-source vulnerability in natural flavor compound extraction from Madagascar vanilla and Indian spice origins creates disruption exposure. Distribution runs through convenience store networks in United States and Chinese tier-one cities, with e-commerce fulfillment centers displacing traditional supermarket replenishment power in coastal metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Snack product competition has become a vertical-integration race, with upstream control over potato cultivation and flavor technology development separating margin-defensible leaders from contract-manufacturing dependents.
For Market Incumbents: Extend captive sourcing into pea protein and collagen isolate supply through backward integration or long-term offtake agreements with Yangtze River Delta processors, insulating against whey cost volatility that threatens high-protein margin structures. Deepen extrusion technology expertise in-house to compress reformulation cycles for EU Green Deal packaging compliance deadlines, defending against agile regional specialists with algorithmic speed-to-market.
For New Entrants and Emerging Players: Direct-to-consumer subscription algorithms offer the most penetrable route for insurgent brands, enabling predictive flavor preference modeling and reduced customer acquisition costs against supermarket-dependent incumbents. Target refrigerated protein bar white space in India and Southeast Asia where cold-chain infrastructure gaps have limited multinational distribution reach, partnering with local oil technology providers for ambient-stable retort processing alternatives.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform brand acquisitions with proven replenishment algorithm traction and recurring revenue visibility. Mid-tier manufacturers with co-manufacturing flexibility and clean-label formulation capabilities represent the most viable acquisition archetype over the medium-term horizon. Watch FDA allergen declaration complexity and EU Extended Producer Responsibility fee escalation as inflection indicators that will accelerate consolidation toward capital-rich multinationals with compliance infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Replenishment algorithm integration reduces acquisition costs and builds lifetime value in United States coastal metros. |
| Clean-Label Reformulation Investment | Natural preservative chemistry capabilities unlock EU Green Deal premium positioning and German retail channel access. |
| Backward Integration into Potato Sourcing | Idaho and North Dakota cultivation control insulates margin structures from commodity price volatility in chips segment. |
| Retort Processing Capacity Addition | Ambient-stable format expansion bypasses cold-chain infrastructure deficits in Indian and Southeast Asian distribution. |
| Biodegradable Packaging Transition | Mono-PE and film converter partnerships preempt Extended Producer Responsibility compliance cost escalation across EU member states. |
Study Parameters
Independent corroboration across category buyers at convenience store chains, quick-service restaurant procurement directors, and flavor house technical directors underwrites the qualitative findings in this study. Primary interviews with snack product brand managers, flexible film converting specialists, and e-commerce fulfillment operators combined with secondary validation from FDA labeling guidance documents, EU Green Deal implementation timelines, FSSAI trans-fat regulation updates, and Nielsen retail audit data. Bottom-up SKU-level volume aggregation and top-down macroeconomic factor adjustment provided triangulation across the analysis window.
Rate-of-change decomposition across product type, ingredient certification tier, packaging format, and distribution channel dimensions enabled segment-specific trajectory modeling throughout the forecast period. CAGRs derived from historical velocity patterns in United States convenience networks, Chinese tier-one city vending channels, and German petrol station retail, adjusted for regulatory compliance cost pass-through and substitution elasticity between ambient and refrigerated formats. Extrusion technology adoption curves and palm oil futures volatility indices served as industry-specific forecast inputs.
The model holds under stable regulatory enforcement timelines and intact cold-chain investment flows; deviation in EU packaging mandate acceleration or Southeast Asian palm oil export restrictions would shift volume and value trajectories. Forecasts reflect documented assumptions regarding urban snacking frequency normalization and digital payment penetration thresholds. A small set of named triggers including F-Gas Regulation enforcement intensity and India FSSAI additive prohibition scope warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Protein Bars Market
Snacks
Brazil Snack Bar Market
Snacks
Baked Chips Market
Snacks
Fried Potato Chips Market
Snacks
Europe Popcorn Market
Snacks
South Korea Snack Bar Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
Roasted Corn Market
Snacks
North America Extruded Snack Food Market
Snacks
Nachos Market
Snacks
Organic Snack Food Market
Snacks
Europe Extruded Snack Food Market
Snacks
Energy Balls Market
Snacks
Fruit Jerky Market
Snacks
Southeast Asia Savory Snacks Market
Snacks
Low Fat Sweet Snacks Market