
 Superfoods-Based Packaged Snacks Market | 2026-2036
Superfoods-Based Packaged Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Superfoods-Based Packaged Snacks Market Intelligence
Food technologist and formulation chemist availability is collapsing across North America and Western Europe as plant-based ingredient science outpaces university training pipelines. General Mills Inc. leverages its Minneapolis R&D campus to sustain proprietary extrusion capabilities for ancient-grain snack matrices. PepsiCo Inc. anchors North American distribution through direct-store-delivery control of convenience and club channels. Creative Nature Ltd. competes in the UK free-from segment with allergen-managed production protocols.
Superfoods-based packaged snacks comprise shelf-stable consumer goods incorporating nutrient-dense ingredients such as chia seeds, quinoa, açaí, and spirulina into ready-to-eat formats, typically manufactured through low-temperature dehydration or cold-press extrusion to preserve bioactive compounds and achieve moisture contents below 10 percent for extended stability without synthetic preservatives. The category serves health-conscious consumers seeking functional nutrition in portable formats that replace traditional confectionery or salty snacks. Bars dominate value contribution due to premium positioning and meal-replacement utility, while chips represent the fastest-expanding product type as vegetable and seaweed substrates displace potato in savory applications. Ingredient source segmentation shows seeds outpacing fruits in growth velocity as hemp and pumpkin varieties deliver protein density with lower sugar loads than dried fruit inclusions.
The US FDA enforces nutrition labeling and health claim substantiation under Food Labeling Guide provisions, while the EU EFSA reviews novel food authorizations for non-traditional ingredients like moringa or camu camu under Regulation (EU) 2015/2283. China's SAMR implements GB national food safety standards that mandate contaminant limits and additive approvals for imported superfood formulations. Stakeholders must monitor evolving novel food approval timelines and adapt formulation portfolios to preempt regulatory exclusion in priority export markets.
Market Dynamics
The collapse of food technologist pipelines across North America and Western Europe is fragmenting R&D capabilities, forcing manufacturers to internalize proprietary extrusion and cold-press dehydration expertise or cede formulation control to specialized contract manufacturers.
Growth Catalysts
- Clean-label mandates:The EU EFSA's tightening novel food authorizations under Regulation (EU) 2015/2283 compel manufacturers to validate bioactive compound retention, creating first-mover advantages for compliant formulators.
- Urban millennial demand:Dense metropolitan clusters in the United States, Germany, and China embed functional snacking into convenience retail, expanding shelf space for nutrient-dense alternatives.
- Cold-press extrusion:Low-temperature processing preserves heat-sensitive compounds in chia and spirulina matrices, enabling shelf-stable formats without synthetic preservatives.
Market Restraints
- Ingredient cost volatility:Organic açaí and camu camu supply concentrates in Brazilian and Peruvian extractive zones, exposing margins to climate-driven harvest fluctuations.
- Novel food approval timelines:China's SAMR GB standard reviews for moringa and hemp protein extend 18-24 months, freezing portfolio expansion in priority export channels.
- Technical shelf-life ceiling:Moisture content thresholds below 10 percent constrain texture innovation, limiting savory chip formats against conventional potato alternatives.
Strategic Opportunities
- Seaweed substrate expansion:Vegetable and seaweed chip formats in Japan and South Korea demonstrate savory displacement potential with lower input costs than ancient grain bases.
- Direct-to-club channel control:Warehouse club penetration in the United States rewards bulk-format SKUs with premium positioning and reduced slotting fee exposure.
- Carbon labeling alignment:The EU Green Deal's farm-to-fork traceability requirements favor vertically integrated suppliers with controlled ingredient provenance.
Industry Challenges
- Formulation chemist scarcity:University plant-based science programs lag industrial demand, forcing manufacturers to poach talent from pharmaceutical or cosmetic sectors.
- Allergen protocol complexity:Free-from certification requirements in the United Kingdom and Germany mandate segregated production lines, inflating capital intensity for mid-scale entrants.
- Cross-border standardization gaps:Divergent contaminant limits between the US FDA and China's SAMR force dual-formulation strategies, eroding scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superfoods-Based Packaged Snacks Market |
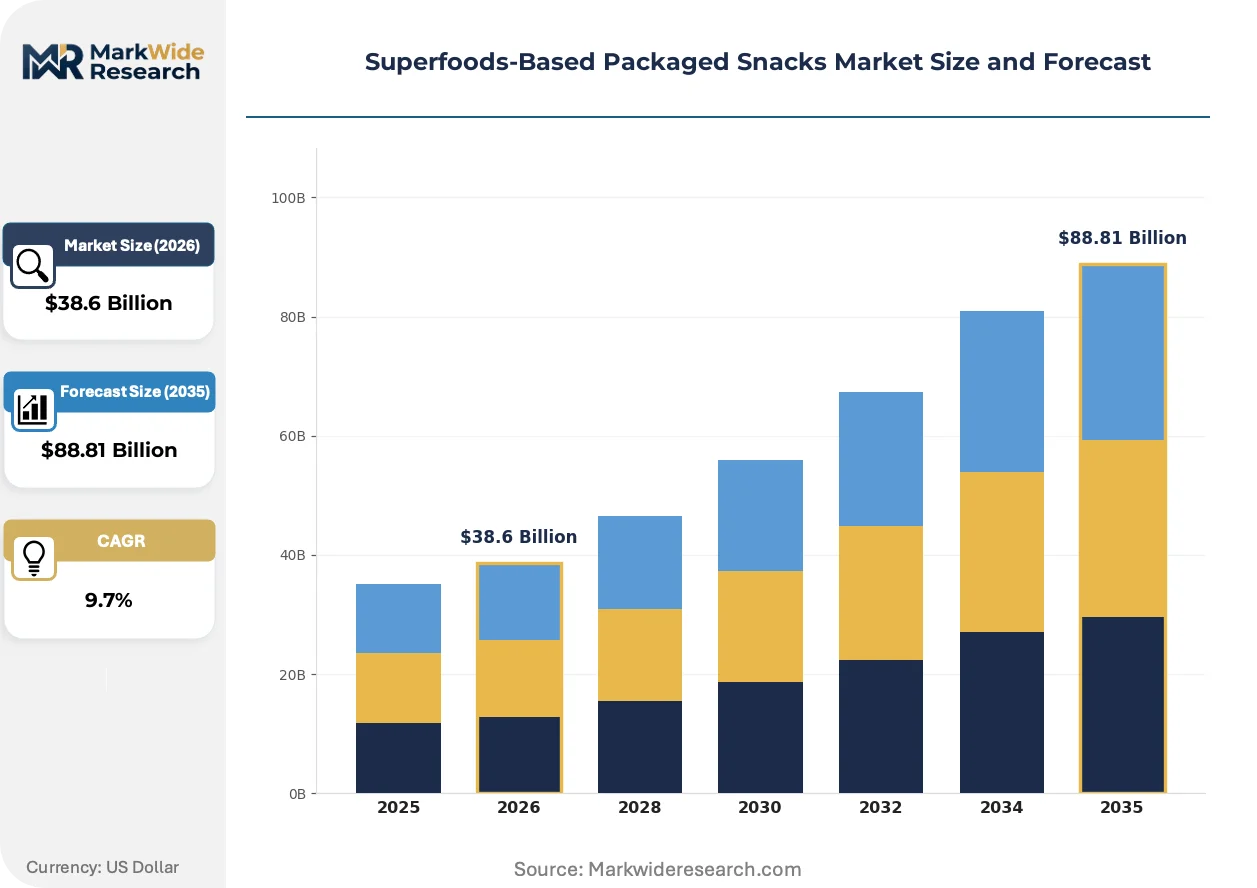
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $88.81 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Bars, Cookies, Trail Mix Ingredient Source: Fruits, Nuts, Seeds, Grains Flavor Profile: Sweet, Savory, Spicy, Umami Packaging Type: Flexible Pouches, Rigid Containers, Boxes, Jars |
| Companies Covered | Nestlé S.A., Creative Nature Ltd., General Mills Inc., Suncore Foods Inc., Navitas LLC, PepsiCo Inc., Nature's Path Foods Inc., Del Monte Pacific Group, Mondelez International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superfoods-Based Packaged Snacks Market Strategic Shifts & Innovations
Processing technology divergence and regulatory fragmentation are compressing competitive moats, while procurement behavior shifts reward suppliers with transparent supply chain documentation and rapid reformulation agility.
Cold-press extrusion systems are fragmenting the manufacturing base by enabling small-batch nutrient preservation without industrial-scale dehydration infrastructure. Regional craft producers in Portland, Copenhagen, and Melbourne adopt these systems to localize ancient-grain processing. The technology is fragmenting volume concentration previously held by multinational extrusion facilities, distributing production capacity into urban micro-factories.
The EU Green Deal's farm-to-fork sustainability metrics now require ingredient provenance documentation for carbon intensity claims, affecting chia and hemp suppliers most acutely. Manufacturers must retrofit traceability systems to capture cultivation-stage emissions data. German and French retailers are demanding blockchain-verified supply chain records as a listing prerequisite, compressing approval cycles for non-compliant entrants.
Meal-replacement utility now drives bar-format purchasing decisions among urban professionals, displacing impulse confectionery grabs. Convenience channel buyers in New York and London negotiate exclusive SKUs with elevated protein density and reduced sugar loads. This behavioral pivot concentrates volume in club and specialty retail, marginalizing traditional grocery center-store placements.
Superfoods-Based Packaged Snacks Market Segmentation
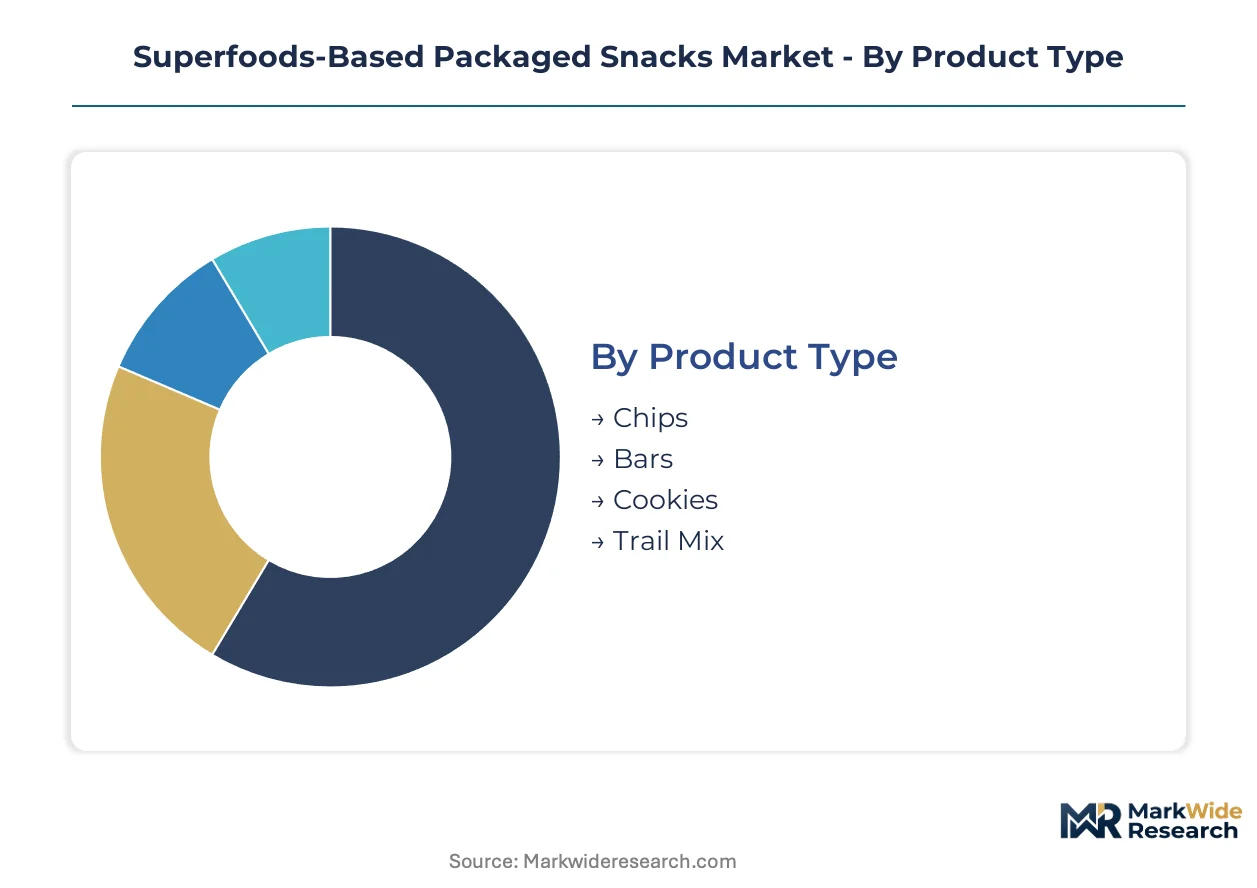
Superfoods-based packaged snacks fragment across four distinct category axes, each carrying unique regulatory and commercial implications. Product format determines moisture thresholds and shelf-life engineering requirements. Ingredient sourcing drives novel food authorization complexity across export markets.
Product Type:
Regulatory scrutiny intensifies for formats claiming meal-replacement utility, with the US FDA and EU EFSA imposing divergent substantiation standards on protein content declarations.
- Bars:Cold-pressed or extruded matrices combining ancient grains with nut butters achieve moisture content below 10 percent without synthetic preservatives. Demand concentrates in US urban professionals seeking portable meal replacements, constrained by protein density thresholds that trigger FDA health claim review.
- Chips:Vegetable and seaweed substrates displace potato through low-temperature dehydration, preserving heat-sensitive bioactives in spirulina and kale coatings. German and Chinese retailers expand shelf space fastest as savory functional snacking displaces conventional salty alternatives.
- Cookies:Almond flour and chia binders replace wheat in free-from formulations, requiring segregated production lines for UK allergen certification.
- Trail Mix:Raw seed and dried fruit combinations face China's SAMR contaminant limits on aflatoxin and pesticide residues in imported hemp and goji berries.
Established volume favors bars; emerging adoption favors chips.
Ingredient Source:
Cost tier differentiation separates commodity inputs from premium traceable supply chains with blockchain-verified provenance.
- Seeds:Hemp and pumpkin varieties deliver protein density exceeding 25 percent with minimal sugar load, outpacing fruit inclusions on growth velocity. Cold-press extrusion preserves omega fatty acid profiles in Minneapolis and Copenhagen micro-factories.
- Fruits:Açaí and camu camu concentrates from Brazilian and Peruvian extractive zones expose margins to climate-driven harvest volatility and EU EFSA novel food authorization timelines.
- Nuts:Almond and cashew bases dominate US bar formulations, constrained by California water scarcity and Prop 65 litigation exposure on heavy metals.
- Grains:Quinoa and amaranth substrates require prebiotic treatment to reduce saponin content, adding processing cost for German clean-label compliance.
Premium positioning clusters on seeds; volume scale concentrates on grains.
Flavor Profile:
Application context drives formulation — sweet profiles target morning consumption, savory and umami capture afternoon salty-snack displacement.
- Sweet:Date syrup and coconut nectar binders replace refined sugar in US and UK formulations, though China's GB standards restrict non-traditional sweetener labeling claims.
- Savory:Nutritional yeast and mushroom extracts deliver umami depth without sodium overload, expanding fastest in Japanese and South Korean seaweed chip applications.
- Spicy:Capsicum and turmeric coatings require heat-stable encapsulation to preserve bioactive potency through extrusion processing.
- Umami:Kombu and miso-derived flavor systems face EU novel food scrutiny when imported from non-traditional supply origins.
Morning occasion dominance favors sweet; afternoon snacking transition favors savory.
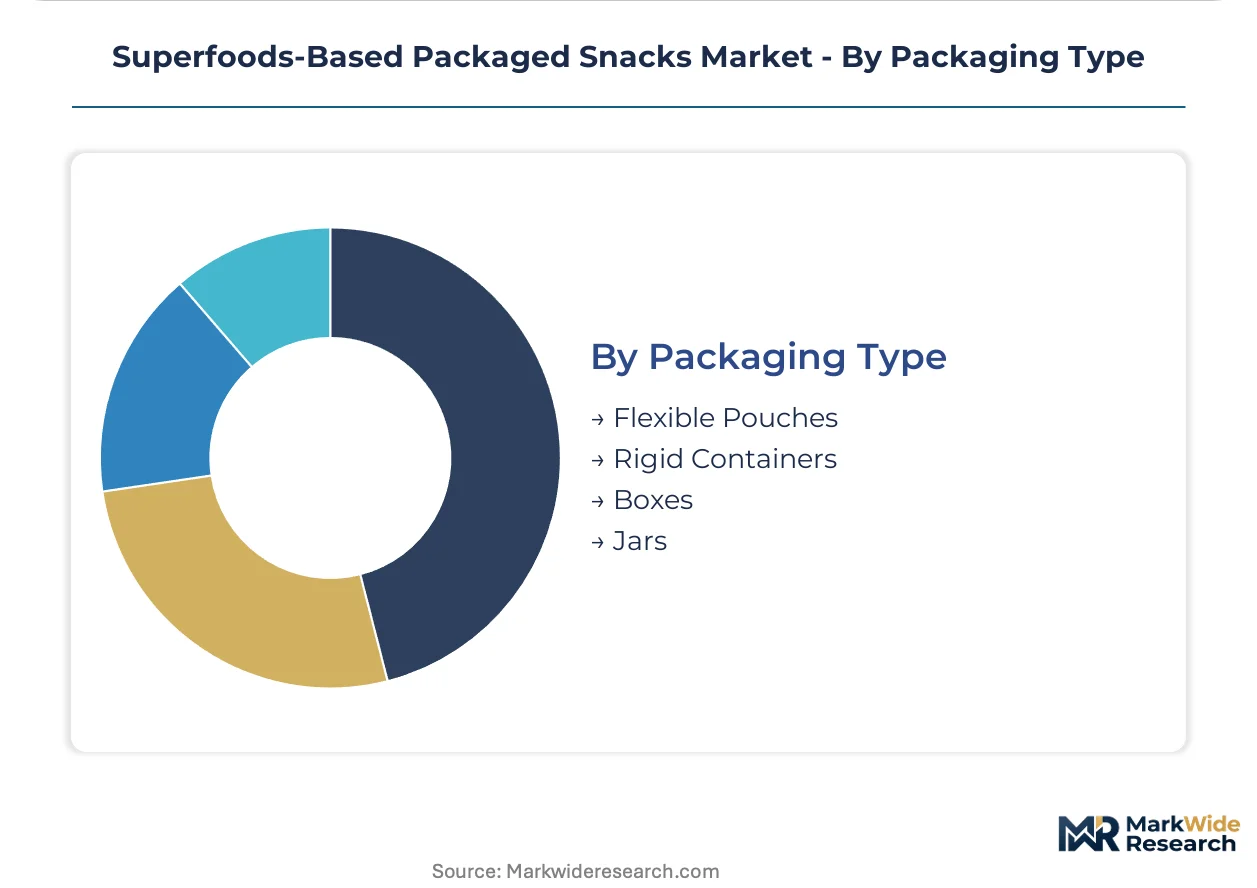
Packaging Type:
Customer type and channel format dictate material selection — convenience retail demands portability, club channels reward bulk efficiency.
- Flexible Pouches:Multi-layer barrier films with oxygen scavengers extend shelf life for high-lipid seed formulations, dominating US convenience and grab-and-go channels.
- Rigid Containers:PET and PP tubs protect fragile chip integrity through German and French retail distribution, though carbon intensity metrics under EU Green Deal pressure material selection.
- Boxes:Paperboard secondary packaging enables premium gifting positioning in Chinese and UAE markets with strict plastic reduction mandates.
- Jars:Glass containment supports zero-waste refill programs in Scandinavian urban centers, constrained by weight and shipping cost penalties.
Convenience velocity favors flexible pouches; premium channel positioning favors rigid containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Urban professionals in the United States treat superfood bars as meal replacements, while German consumers prioritize clean-label certifications, and Chinese buyers favor functional positioning in gifting contexts.
United States
Millennial professionals in New York and Los Angeles drive bar-format demand for portable breakfast substitutes. The FDA enforces nutrition labeling and health claim substantiation under Food Labeling Guide provisions. Minneapolis hosts General Mills' R&D campus, where proprietary extrusion capabilities sustain ancient-grain snack matrix development.
Germany
Retailers in Berlin and Hamburg mandate blockchain-verified supply chain records as a listing prerequisite under EU Green Deal farm-to-fork requirements. The EFSA reviews novel food authorizations for non-traditional ingredients under Regulation (EU) 2015/2283. Bavaria's clean-label manufacturing clusters specialize in allergen-managed production protocols for free-from segments.
China
Functional snacking embeds into mainstream retail channels in Shanghai and Beijing as wellness culture penetrates tier-one cities. SAMR implements GB national food safety standards mandating contaminant limits and additive approvals for imported formulations. Pearl River Delta distribution hubs handle bulk import volumes for premium gifting SKUs.
United Kingdom
Free-from certification requirements concentrate demand in London and Manchester for allergen-segregated production lines. The EFSA's novel food timelines affect moringa and hemp protein portfolio expansion. Creative Nature Ltd. anchors competitive positioning in the domestic free-from segment with managed production protocols.
Japan
Seaweed chip formats demonstrate savory displacement potential in Tokyo and Osaka convenience channels. METI oversees food safety standards for functional ingredient imports. Urban micro-factories in Kanto region localize cold-press extrusion systems for small-batch nutrient preservation.
Superfoods-Based Packaged Snacks Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with multinational CPG conglomerates controlling distribution infrastructure while craft producers capture premium niches through localized processing. The market structure rewards proprietary extrusion capabilities and direct-store-delivery channel control. Three archetypes dominate: diversified CPG conglomerates with captive R&D, specialist free-from formulators with allergen protocols, and regional craft producers with urban micro-factory networks. Competitive moves center on warehouse club penetration strategies and carbon labeling alignment for EU market access.
Within the diversified CPG tier, Nestlé S.A. and General Mills Inc. represent integrated leaders with captive supply chain infrastructure and proprietary formulation capabilities. PepsiCo Inc. exemplifies distribution-heavy positioning through convenience and club channel control. Among specialist formulators, Creative Nature Ltd. occupies a position exemplifying allergen-managed production protocols for free-from market segments.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Creative Nature Ltd. |
| General Mills Inc. |
| Suncore Foods Inc. |
| Navitas LLC |
| PepsiCo Inc. |
| Nature's Path Foods Inc. |
| Del Monte Pacific Group |
| Mondelez International Inc. |
| Others |
Cost & Logistics Intelligence
EU EFSA novel food authorizations under Regulation (EU) 2015/2283 gate both supplier qualification timelines and price differentiation between compliant and non-compliant ingredient tiers, compressing margins for exporters awaiting approval while rewarding validated formulators with premium positioning.
Pricing Analysis
Long-term offtake contracts dominate procurement for organic açaí and hemp protein, insulating manufacturers from spot-market volatility in Brazilian and Peruvian extractive zones. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-verified provenance SKUs from conventional certified-organic and commodity-grade alternatives. Cost compression in the standard tier is intensifying because German and French retailers are consolidating shelf space around carbon-labeled products. Price-sensitive mass-market buyers in Chinese tier-two cities resist premium positioning, while US warehouse club channels absorb bulk-format premiums with minimal elasticity.
Supply Chain Analysis
Just-in-time inventory strategies prevail for chia and quinoa inputs in Minneapolis and Copenhagen micro-factories, while strategic stockpiling of açaí concentrate buffers climate-driven harvest fluctuations in Brazilian supply zones. Raw material sourcing draws from Peru for camu camu, China for goji berries, and Canada for hemp protein. Single-source vulnerability concentrates in Amazon basin extractive regions exposed to deforestation enforcement actions. Distribution runs through direct-store-delivery networks controlled by PepsiCo in US convenience channels and through Pearl River Delta hubs for Chinese import clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional snacking penetration in Chinese tier-one cities and German clean-label retail channels signals early-cycle expansion with substantial runway before saturation thresholds emerge.
For Market Incumbents: Shield proprietary extrusion capabilities at Minneapolis R&D campuses through accelerated patent filings on ancient-grain matrix formulations. Deepen backward integration into hemp protein cultivation in Canada to preempt supply competition from emerging plant-based specialists. Prioritize EFSA compliance documentation to defend shelf space against novel food authorization delays affecting challenger brands.
For New Entrants and Emerging Players: Allergen-managed production protocol gaps in the UK free-from segment expose white-space opportunities for mid-scale entrants with segregated line investments. Target Japanese seaweed chip applications where savory functional snacking displacement lags behind bar-format saturation. Pursue direct-to-club channel strategies with bulk-format SKUs to bypass slotting fee barriers in conventional grocery.
For Investors and Strategic Acquirers: China's SAMR GB standard harmonization reshapes the acquisition landscape by devaluing portfolios dependent on 18-24 month novel food approval timelines. Long-term viability centers on vertically integrated suppliers with controlled ingredient provenance spanning cultivation through retail. Monitor EU Green Deal farm-to-fork traceability implementation velocity as the signal indicating premium pricing power sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Press Extrusion Capacity Expansion | Minneapolis and Copenhagen micro-factories localize nutrient preservation without industrial-scale infrastructure. |
| Blockchain Supply Chain Verification | German retailers mandate provenance documentation as listing prerequisite under EU Green Deal metrics. |
| Novel Food Authorization Pre-Submission | EFSA review timelines for moringa and camu camu compress first-mover advantages for compliant formulators. |
| Seaweed Substrate Formulation Development | Japanese and South Korean chip applications demonstrate savory displacement with lower input costs than grains. |
| Direct-to-Club Channel Penetration | US warehouse club buyers reward bulk-format SKUs with reduced slotting fee exposure and premium positioning. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA Food Labeling Guide provisions, EFSA novel food authorization databases, SAMR GB standard filings, and Nielsen retail audit data. Interviews with formulation chemists, category buyers at German and US retailers, plant-based ingredient procurement leads, and cold-press extrusion equipment manufacturers inform demand-side and supply-side validation. Bottom-up volume modeling triangulates against top-down market sizing from trade flow analysis and customs records.
Segmentation dimensions modeled span product format, ingredient source, flavor profile, and packaging type across the projection horizon. CAGRs derive from growth rate convergence analysis applied to urban millennial adoption curves and clean-label regulatory penetration patterns. Forecast inputs incorporate cold-press extrusion technology diffusion rates and novel food approval timeline distributions.
Forecasts assume regulatory continuity in US FDA, EU EFSA, and China SAMR regimes; material policy shifts on novel food authorization or contaminant limits would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Trail Mix Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
South America Frozen Snacks Market
Snacks
India Snack Bar Market
Snacks
South America Cereal Bar Market
Snacks
Europe Frozen Snacks Market
Snacks
Potato Chips Market
Snacks
Savoury Biscuits Market
Snacks
Meat Protein Chips Market
Snacks
Spain Snack Bar Market
Snacks
Low Sodium Snacks Market
Snacks
Dairy Protein Crisps Market
Snacks
Sweet Potato Chips Market
Snacks
Fiber Bars Market
Snacks
Thailand Snack Bar Market
Snacks
Snack Products Market