
 Button Mushroom Products Market | 2026-2036
Button Mushroom Products Market Size, Share, and Industry Trends Forecast 2026-2036
Button Mushroom Products Market Insights
Subscription-based freshness guarantees and temperature-monitored replenishment services are recalibrating how button mushroom suppliers contract with retail buyers. Monaghan Mushrooms leverages its integrated compost-to-retail network across Ireland and the United Kingdom to lock in multi-year supply agreements. Bonduelle sustains its position through deep backward integration into canning and frozen product lines that buffer against fresh-price volatility. Costa Group anchors Australasian foodservice demand with controlled-environment growing capacity that extends seasonal availability.
Button mushroom products encompass the fruiting bodies of Agaricus bisporus and their processed derivatives, typically cultivated on composted substrates of straw, gypsum, and poultry manure under strictly controlled humidity and carbon dioxide conditions. The species delivers a protein content of approximately three grams per one hundred grams fresh weight alongside selenium and B-vitamin complexes, serving as both a meat alternative substrate and a functional food ingredient. Fresh mushrooms occupy the dominant share of value generation due to perishability-driven price premiums and direct-to-retail channel control. Canned mushrooms retain mature, stable demand in institutional food processing where shelf stability trumps sensory fidelity. Nutraceutical applications represent the fastest-expanding margin pool as extraction technologies isolate beta-glucan compounds for immune-modulation supplements.
The European Food Safety Authority sets maximum residue limits for agrochemicals under EU Regulation 396/2005, directly conditioning substrate pasteurization protocols and post-harvest handling investments. The United States Department of Agriculture's National Organic Program and the Food and Drug Administration's Food Safety Modernization Act impose parallel traceability and preventive-control requirements on importers and domestic growers. China's National Health Commission and Ministry of Agriculture and Rural Affairs enforce GB standards for edible fungi that govern heavy-metal thresholds and additive use in processed formats. Stakeholders must monitor divergence between regional contaminant thresholds and packaging sustainability mandates as dual compliance burdens reshape sourcing geography and capital allocation.
Market Dynamics
EU Regulation 396/2005 pesticide residue limits are forcing substrate pasteurization upgrades across composting facilities, compressing margins for growers without captive compost production while redirecting capital toward controlled-environment infrastructure.
Growth Catalysts
- Foodservice channel expansion:Hotel chains and institutional caterers in Germany and France are locking multi-year fresh supply contracts with temperature-guaranteed logistics provisions.
- EFSA substrate safety protocols:The European Food Safety Authority's tightening contaminant thresholds are accelerating grower migration toward synthetic compost alternatives and automated climate control.
- Controlled-environment agriculture:LED-optimized growing rooms and CO2 enrichment systems are extending harvest cycles beyond traditional seasonal windows in the Netherlands and Poland.
Market Restraints
- Straw and gypsum input volatility:Poultry manure supply fluctuations and grain byproduct pricing swings directly compress substrate production economics for non-integrated growers.
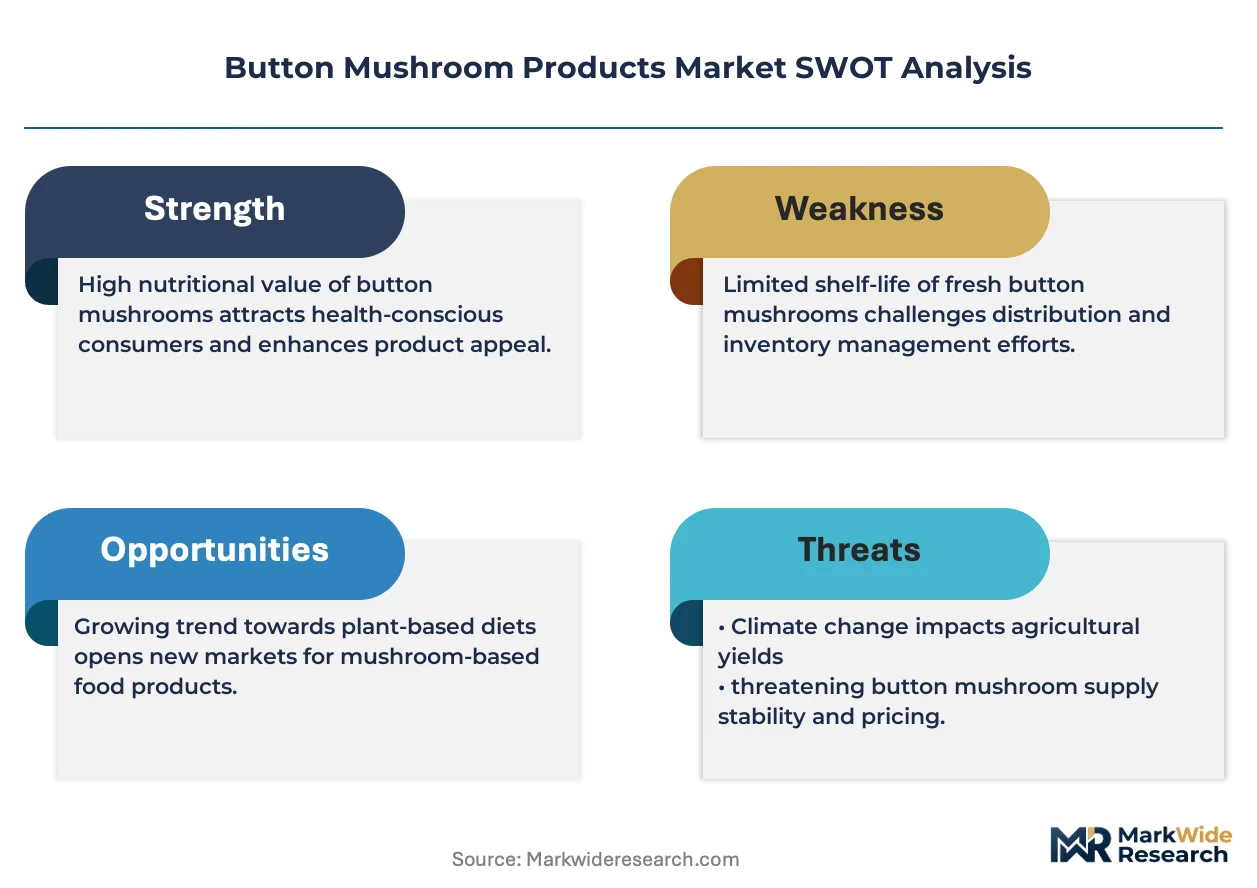
- Fresh perishability premium compression:Refrigerated distribution network coverage gaps in Eastern Europe limit price realization for exporters from Iberian and Benelux production clusters.
- Canned format demand erosion:Institutional food processors are substituting toward individually quick-frozen mushroom alternatives that retain superior texture in prepared meals.
Strategic Opportunities
- Nutraceutical extraction white space:Beta-glucan isolation for immune-modulation supplements offers margin expansion beyond commoditized fresh and processed formats.
- EU Green Deal Farm to Fork alignment:Substrate innovations that eliminate synthetic pesticide dependencies qualify growers for sustainability-linked procurement contracts with major retail banners.
- Subscription freshness guarantees:Temperature-monitored replenishment services are opening direct-to-kitchen channels that bypass traditional wholesale intermediaries.
Industry Challenges
- Mycology technician scarcity:Controlled-environment facility operators face recruitment gaps for specialists capable of managing spawn-run optimization and disease pressure monitoring.
- Organic certification timeline compression:USDA National Organic Program and EU organic equivalency audits are extending approval cycles for substrate inputs and post-harvest handling protocols.
- Legacy composting infrastructure retrofit costs:Converting open-phase composting to enclosed, bio-secure systems demands capital outlays that strain mid-scale grower balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Button Mushroom Products Market |
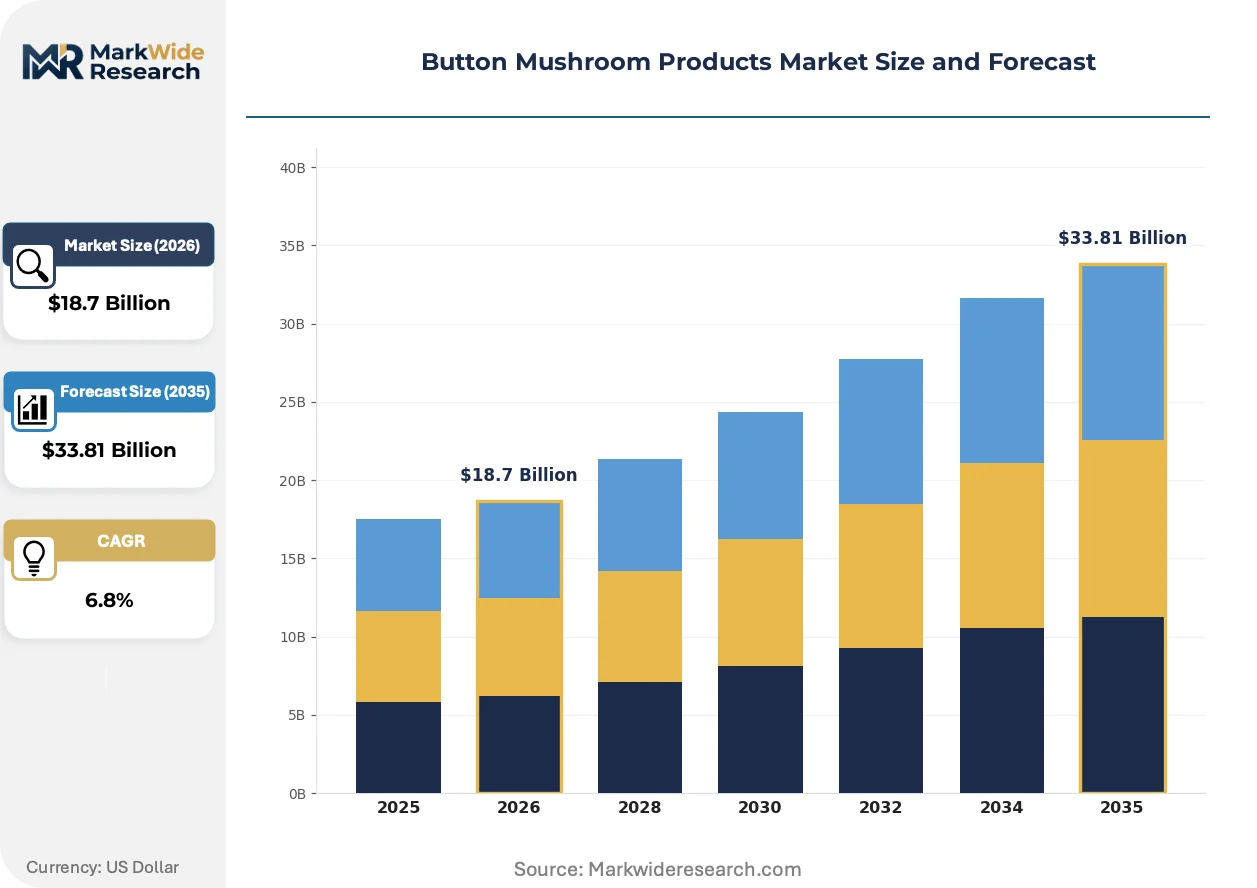
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Mushrooms, Canned Mushrooms, Frozen Mushrooms, Dried Mushrooms, Pickled Mushrooms Application: Foodservice, Household Cooking, Food Processing, Nutraceuticals, Cosmetic Formulations Packaging Type: Plastic Containers, Cardboard Boxes, Vacuum Packs, Glass Jars, Pouches Customer Type: Supermarkets, Specialty Stores, Hotel Chains, Exporters, Wholesalers |
| Companies Covered | Monaghan Mushrooms, Bonduelle, Greenyard, Monterey Mushrooms, Costa Group, Okechamp, Shanghai Finc Bio-Tech, Phillips Mushroom Farms, Scelta Mushrooms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Button Mushroom Products Market Trends and Innovations
Automation and biosafety engineering are converging to reshape production economics, while regulatory chemistry thresholds and procurement model evolution are redrawing competitive boundaries across the value chain.
Automated harvesting robotics and computer-vision grading systems are consolidating quality control and labor efficiency in high-volume fresh operations. Dutch and Belgian growing facilities are deploying these technologies fastest, achieving consistent cap-size sorting that commands premium shelf placement in German and French retail. The structural consequence is compressing viability for manual-harvest operations below fifty-ton annual output thresholds.
REACH chemical authorization requirements and the EU F-Gas Regulation are phasing out conventional refrigerants and sanitizing agents in post-harvest handling. Growers must validate alternative cold-chain chemistries and ozone-based surface treatments through EFSA safety dossiers. Fresh-format exporters to Nordic markets face the steepest compliance recertification burdens as national food agencies enforce divergent transition timelines.
Buyer consolidation among supermarket banners is compressing supplier rosters and extending payment terms for fresh mushroom contracts. German and UK retail alliances are displacing fragmented wholesale purchasing with centralized produce category management that demands traceability dashboards and volume guarantees. The Netherlands-based cooperatives and Irish integrated networks are capturing disproportionate share of these restructured procurement relationships through captive logistics investments.
Button Mushroom Products Market Segmentation
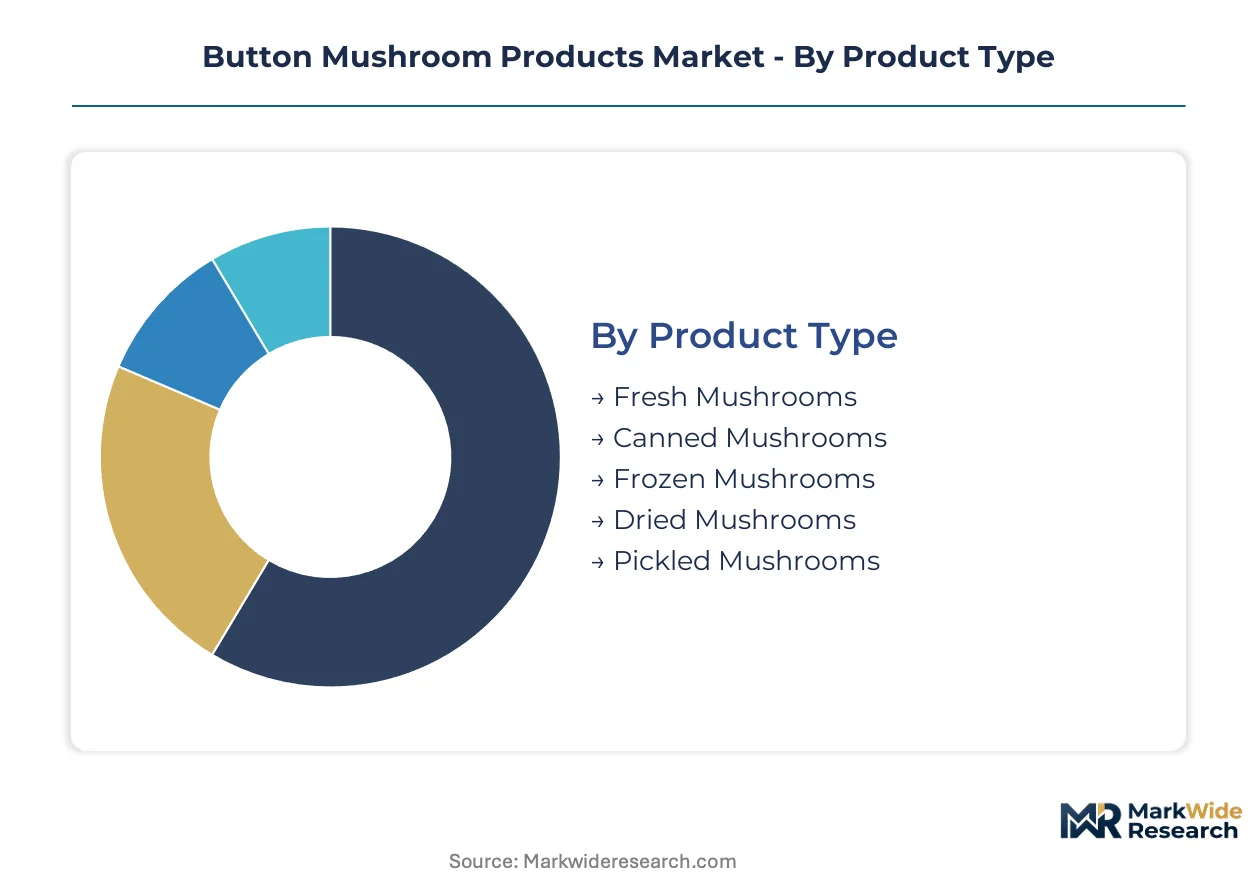
Button mushroom suppliers calibrate production specifications and packaging formats against divergent perishability tolerances and channel handling requirements. Segmentation discipline separates commoditized bulk formats from precision-controlled premium lines that command shelf placement premiums in temperature-guaranteed retail networks.
Product Type:
Standardization dominates at the commodity end where shelf stability trumps sensory fidelity, while customization intensifies toward fresh formats demanding spawn-run optimization and cap-size grading precision.
- Fresh Mushrooms:Whole fruiting bodies harvested at veil-intact or veil-open maturity stages, requiring continuous cold chain maintenance from compost facility to retail shelf. German hotel chains and French supermarket banners concentrate procurement through multi-year contracts with temperature-monitored replenishment guarantees. Perishability compresses distribution radii and rewards captive compost-to-retail integration.
- Canned Mushrooms:Thermally processed slices or pieces in brine solution, delivering eighteen-month shelf stability for institutional food manufacturing. Demand concentrates in North American and European food processing where labor cost reduction outweighs texture degradation. Format erosion accelerates as quick-frozen alternatives capture prepared meal applications.
- Frozen Mushrooms:Individually quick-frozen segments retaining cellular structure through cryogenic tunnel processing. Expanding share in ready-meal manufacturing.
- Dried Mushrooms:Dehydrated whole caps or slices reconstituted for soup and sauce applications. Stable demand in Asian export markets.
- Pickled Mushrooms:Acidified preservation in vinegar brine for appetizer and salad applications. Niche positioning in Eastern European retail.
Volume leadership: Fresh Mushrooms. Steepest expansion trajectory: Frozen Mushrooms.
Application:
Cost tier separation distinguishes high-frequency replenishment channels from capital-intensive extraction processes commanding nutraceutical margin premiums.
- Foodservice:Hotel chains, institutional caterers, and restaurant groups purchasing graded fresh mushrooms through contracted logistics providers. German and French operators dominate volume, specifying cap diameter tolerances and traceability dashboards that disqualify fragmented suppliers.
- Household Cooking:Retail-packaged fresh and processed formats for consumer preparation. Supermarket banner consolidation compresses supplier rosters and extends payment terms.
- Food Processing:Ingredient supply to soup, sauce, and ready-meal manufacturers. Canned and frozen formats predominate.
- Nutraceuticals:Beta-glucan extraction for immune-modulation supplements. EFSA health claim validation requirements filter supplier eligibility.
- Cosmetic Formulations:Polysaccharide isolates for topical hydration products. Emerging demand from Korean and French formulators.
Leading by volume: Foodservice. Expanding most quickly: Nutraceuticals.
Packaging Type:
Customer type dictates material selection, with automated retail replenishment favoring standardized cube-efficient formats while specialty channels absorb premium sustainable materials.
- Plastic Containers:Polypropylene punnies with perforated film overwrap for fresh retail display. Dominates supermarket produce sections.
- Cardboard Boxes:Corrugated bulk containers for foodservice and wholesale distribution. Standardized pallet configurations optimize logistics.
- Vacuum Packs:Barrier film with modified atmosphere for extended fresh shelf life. Growing share in premium retail.
- Glass Jars:Sterilizable containers for pickled and marinated products. Concentrated in specialty retail.
- Pouches:Flexible retort or frozen formats for processed applications. Lightweight shipping economics favor adoption.
Volume leader: Plastic Containers. Gaining share fastest: Vacuum Packs.
Customer Type:
Supply concentration shapes procurement power asymmetries, with consolidated retail banners extracting traceability investments while fragmented exporters compete on spot pricing.
- Supermarkets:Centralized produce category management demanding volume guarantees, sustainability certifications, and direct-to-dock logistics. German and UK retail alliances displace wholesale intermediaries.
- Hotel Chains:Multi-property operators locking fresh supply contracts with temperature-guaranteed provisions and chef-specified grading.
- Specialty Stores:Independent retailers and organic banners purchasing smaller lots with premium positioning.
- Exporters:Cross-border traders managing phytosanitary documentation and regulatory compliance divergence.
- Wholesalers:Traditional intermediaries facing margin compression from direct retail and foodservice contracting.
Leading the category by volume: Supermarkets. Growing fastest: Hotel Chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Ireland, Poland, and the Netherlands supply consumption centers in Germany and France, creating a continental trade pattern shaped by composting infrastructure and cold-chain density.
Germany
Hotel chains and supermarket banners concentrate procurement through multi-year fresh supply contracts with temperature-guaranteed logistics. The EU's Farm to Fork Strategy under the European Green Deal tightens pesticide residue limits through EFSA protocols. Industrial-scale composting facilities in Lower Saxony and Bavaria anchor year-round supply networks.
France
Institutional caterers and restaurant groups drive graded fresh mushroom volumes with chef-specified cap diameter tolerances. REACH chemical authorization requirements phase out conventional sanitizing agents in post-harvest handling. The Île-de-France and Hauts-de-France regions host controlled-environment growing capacity serving Parisian foodservice demand.
Netherlands
LED-optimized growing rooms and CO2 enrichment systems extend harvest cycles beyond traditional seasonal windows. The EU F-Gas Regulation forces validation of alternative cold-chain chemistries through EFSA safety dossiers. Dutch cooperatives capture disproportionate share of restructured German and UK retail procurement through captive logistics investments.
Poland
Controlled-environment agriculture investments accelerate as growers migrate toward automated climate control systems. EU Regulation 396/2005 pesticide residue limits redirect capital toward enclosed, bio-secure composting infrastructure. Warsaw and Łódź production clusters supply Central European markets with refrigerated distribution network expansion.
United States
Fresh mushroom adoption accelerates in foodservice channels with direct-to-retail channel control. The USDA National Organic Program and FDA Food Safety Modernization Act impose traceability and preventive-control requirements on domestic growers. Pennsylvania and California growing regions anchor North American supply with substrate pasteurization protocol investments.
Button Mushroom Products Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across a tiered structure where captive compost-to-retail integration commands premium shelf placement. The vendor base clusters around three strategic archetypes: Irish and Dutch cooperatives with backward integration into composting, French and Belgian processors with canning and frozen product buffers, and Australasian controlled-environment specialists extending seasonal availability. Dominant competitive moves include multi-year supply contract locking with temperature-guaranteed provisions and substrate innovation investments qualifying for sustainability-linked procurement.
Among Irish integrated networks, Monaghan Mushrooms exemplifies the cooperative archetype with compost-to-retail control across Ireland and the United Kingdom. French processor Bonduelle occupies a position within the diversified-format tier, sustaining market presence through canning and frozen lines. Australasian operator Costa Group represents the controlled-environment specialist archetype, anchoring foodservice demand with year-round growing capacity.
| Leading Market Players |
|---|
| Monaghan Mushrooms |
| Bonduelle |
| Greenyard |
| Monterey Mushrooms |
| Costa Group |
| Okechamp |
| Shanghai Finc Bio-Tech |
| Phillips Mushroom Farms |
| Scelta Mushrooms |
| Others |
Pricing and Supply Chain Analysis
Poultry manure spot pricing in the Benelux region cascades through substrate production economics into three-tier pricing structure across premium, standard, and economy levels, with German retail banners extracting cost-down concessions that compress margins for non-integrated growers.
Pricing Analysis
Margin tightening in standard-grade fresh formats reflects supermarket banner consolidation extending payment terms to ninety days. Pricing stratifies across premium, standard, and economy tiers based on cap diameter grading precision and organic certification status under EU Regulation 396/2005. Cost-down pressure on economy-tier canned products accelerates as quick-frozen alternatives capture prepared meal applications. Foodservice buyers show lowest price sensitivity due to chef-specified quality requirements, while institutional processors drive hardest bargain on bulk frozen contracts.
Supply Chain Analysis
Straw and gypsum supply rests on agricultural byproduct markets in Poland, the Netherlands, and Ireland where grain production cycles create input volatility. Composting infrastructure draws from poultry manure networks, synthetic additive suppliers, and pasteurization equipment providers. Single-source vulnerability concentrates in specialized spawn suppliers controlling Agaricus bisporus genetics. Distribution runs through refrigerated consolidation hubs in Lower Saxony and Île-de-France serving German and French retail banners with temperature-guaranteed replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-environment growing capacity scarcity props pricing for year-round supply contracts, constraining volume growth to the pace of capital-intensive facility commissioning.
For Market Incumbents: Deploy captive compost-to-retail integration to lock multi-year supply agreements with temperature-guaranteed logistics provisions. Accelerate LED-optimized growing room investments in Poland and the Netherlands to extend harvest cycles beyond seasonal windows. Counter quick-frozen substitute threats by emphasizing chef-specified cap diameter tolerances that frozen formats cannot replicate. For New Entrants and Emerging Players: Begin with nutraceutical beta-glucan extraction targeting immune-modulation supplement manufacturers seeking EFSA-validated suppliers. Target the fastest-expanding margin pool where extraction technology barriers filter incumbent competition. Pursue direct-to-kitchen subscription freshness guarantees bypassing traditional wholesale intermediaries in fragmented Eastern European markets. For Investors and Strategic Acquirers: The window for entry favors controlled-environment facility operators with existing composting infrastructure and organic certification timelines already initiated. Long-term viability hinges on substrate innovation capabilities qualifying for EU Green Deal sustainability-linked procurement contracts. Watch EFSA contaminant threshold revisions as inflection indicator for pasteurization equipment upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composting | Captive substrate production insulates margin from poultry manure price volatility in Benelux supply zones. |
| Controlled-Environment Capacity Expansion | LED-optimized growing rooms in Poland extend harvest cycles beyond traditional seasonal windows for German retail. |
| Nutraceutical Extraction Partnership | Beta-glucan isolation agreements with supplement manufacturers unlock margin pools beyond commoditized fresh formats. |
| Sustainability Certification Program | EU organic equivalency and Farm to Fork alignment qualify growers for premium procurement contracts with major banners. |
| Temperature-Guaranteed Logistics Investment | Refrigerated network density in Eastern Europe closes distribution coverage gaps limiting price realization. |
Research Methodology
EU agricultural statistics, EFSA contaminant monitoring databases, and customs trade records formed the secondary backbone, cross-referenced with primary interviews involving compost facility operators, supermarket category buyers, and foodservice procurement directors. Bottom-up and top-down triangulation validated production volume estimates against consumption surveys and channel shipment data.
Bottom-up modeling anchored forecasts in facility-level capacity assessments and substrate input cost trajectories across the projection horizon. Segmentation dimensions included product format, application channel, packaging type, and customer archetype. CAGRs derived from regression analysis of historical price-volume relationships and capacity expansion pipelines. Industry-specific inputs incorporated EU Regulation 396/2005 compliance cost schedules and LED growing technology adoption curves.
Underlying measurement precision varies by segment; fresh mushroom volume estimates carry tighter precision than nutraceutical extraction projections due to established tracking infrastructure. Forecasts incorporate assumptions regarding EFSA threshold stability and composting facility commissioning timelines. Regulatory divergence between EU member states on cold-chain chemistries and organic certification reciprocity warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Spain Tropical Fruits Market
Fruits and Vegetables
Sudachi Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Dry Beans Market
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Global Bean Sprouts Market
Fruits and Vegetables
Europe Orange Market