
 South America Protein Bar Market | 2026-2036
South America Protein Bar Market Size, Share, and Industry Trends Forecast 2026-2036
South America Protein Bar Market Analytics
Asset-light contract manufacturing and third-party co-packing arrangements is rewriting competitive entry dynamics in the South America Protein Bar Market. Nestlé S.A. leverages its Pan-American distribution infrastructure to secure shelf presence across Brazilian retail chains. Arcor anchors its position through backward integration into domestic soy protein sourcing in Argentina. Quest Nutrition LLC competes via specialized high-protein formulations targeting CrossFit and functional fitness communities.
A protein bar is a shelf-stable, extruded or cold-pressed food product containing 10–30 grams of protein per serving, typically bound by hydrolyzed collagen or plant-based syrups and manufactured through high-shear mixing followed by slab-forming or enrobing processes, designed to deliver convenient post-exercise amino acid delivery or meal replacement nutrition. Whey and plant-based variants currently lead volume, with plant-based bars capturing accelerating interest as Brazilian consumers reduce dairy intake; the athletes and fitness enthusiasts target audience commands the deepest margin pools due to premium pricing tolerance and repeat purchase frequency.
Brazil's national health surveillance agency, ANVISA, enforces strict nutritional labeling and health claim verification that bars must clear before commercialization, while Argentina's food code authority mandates compositional thresholds for protein content declarations. These frameworks elevate compliance costs for new entrants but simultaneously reinforce consumer trust in verified formulations. Stakeholders must monitor evolving Mercosur harmonization talks, as unified standards would reshape cross-border manufacturing strategies and sourcing decisions across the trade bloc.
Market Dynamics
ANVISA's evolving protein-content verification protocols are compressing product development cycles across Brazilian manufacturers while Argentine import substitution policies redirect soy protein sourcing toward domestic crushing facilities.
Growth Catalysts
- CrossFit penetration:Functional fitness communities in São Paulo and Rio de Janeiro normalize post-workout protein consumption, creating habitual purchase patterns among urban professionals.
- Mercosur harmonization talks:Proposed unified nutritional labeling standards would eliminate duplicate certification costs for manufacturers operating across Brazil, Argentina, and Uruguay.
- Extrusion technology:High-shear mixing equipment with real-time moisture control enables cleaner-label formulations without texture degradation, appealing to ingredient-conscious consumers.
Market Restraints
- Whey protein import dependency:Brazilian manufacturers rely on North American and European dairy isolate shipments, exposing margins to currency volatility and ocean freight rate spikes.
- ANVISA claim verification timelines:Health benefit submissions require 18-24 month review cycles, freezing marketing messaging and delaying regional rollouts.
- Fresh food substitution:Traditional post-gym meals of grilled chicken and rice retain cost and cultural preference advantages in secondary Brazilian cities.
Strategic Opportunities
- Colombian market entry:Bogotá and Medellín fitness club density now matches 2018 São Paulo levels, yet protein bar shelf space remains underdeveloped in Andean retail.
- Pharmacy channel expansion:Brazilian drugstore chains are reallocating shelf space from supplements toward fortified snacks, creating premium positioning opportunities.
- Collagen-peptide convergence:Hydrolyzed collagen inclusion addresses joint health positioning while maintaining protein content, differentiating from pure dairy-based competitors.
Industry Challenges
- Food technologist scarcity:Brazilian universities produce limited graduates experienced in high-protein extrusion and shelf-stable binding systems, constraining R&D velocity.
- Cold-chain reconfiguration:Temperature-controlled distribution networks designed for chocolate confections require retrofitting to accommodate protein bar texture sensitivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Protein Bar Market |
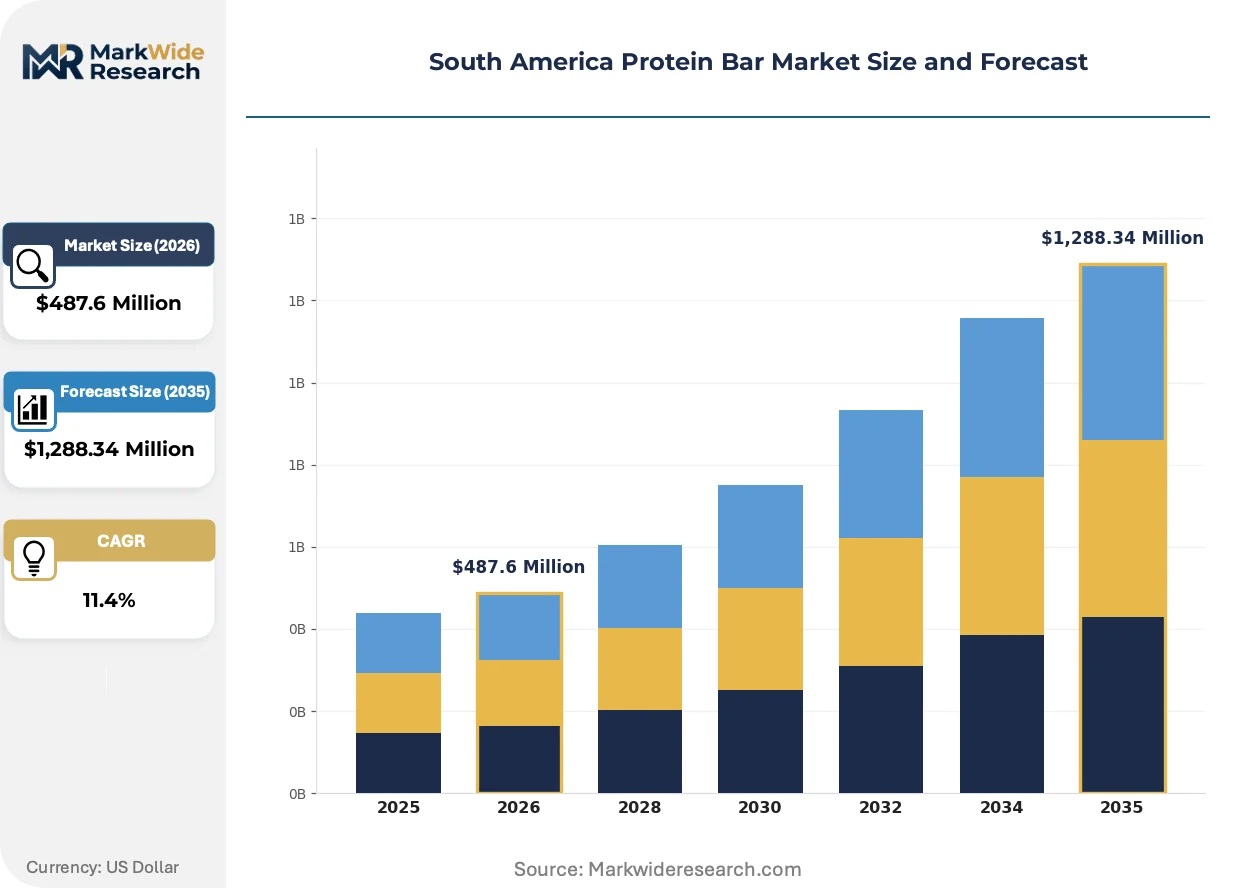
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey, Soy, Plant-Based, Casein Target Audience: Athletes, Fitness Enthusiasts, Health-Conscious Consumers, Diabetics Distribution Channel: Retail, Online, Gym Stores, Vending Machines Flavor Profile: Chocolate, Vanilla, Peanut Butter, Fruit |
| Companies Covered | General Mills Inc, Nestlé S.A., The Kellogg Company, Quest Nutrition LLC, Arcor, Skout Backcountry LLC, Clif Bar, PowerBar, MusclePharm Corp, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Protein Bar Market Evolving Landscape
Reformulation priorities are pivoting toward plant-protein functionality as Brazilian consumers reduce dairy intake, while regulatory verification demands reshape competitive moats around established players.
Cold-pressed manufacturing is migrating from artisanal positioning toward mainstream production economics. This technique preserves heat-sensitive amino acid profiles in pea and rice protein blends. Brazilian mid-market brands are adopting it to close the sensory gap with whey-based incumbents. The technology is migrating from premium specialty lines toward standard grocery SKUs, compressing price premiums that previously separated natural-channel and mass-market positioning.
Argentina's national food code authority mandates updated compositional thresholds for protein content declarations, forcing reformulations that align analytical testing with label claims. Manufacturers must now submit third-party laboratory verification for every production batch. This regulatory tightening most acutely affects imported brands lacking domestic quality control infrastructure, advantaging Argentine producers with captive laboratory relationships.
Brazilian gym operators are unbundling retail from membership fees, converting pro-shop space into revenue-sharing arrangements with external snack vendors. This channel fragmentation displaces traditional wholesale-to-retail distribution for premium protein bar lines. The shift is most visible in São Paulo's independent fitness studios, where localized brand curation replaces national chain standardization.
South America Protein Bar Market Segmentation
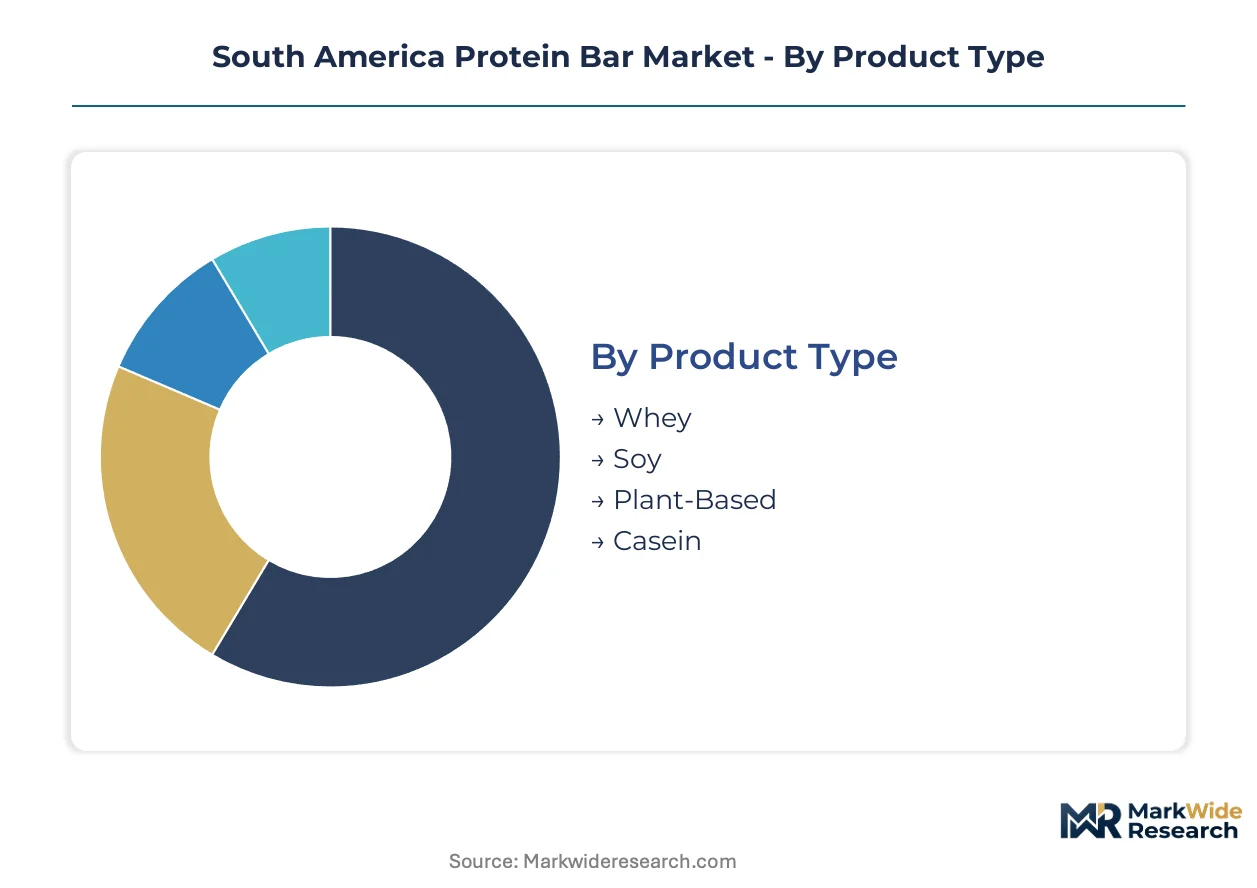
Segmentation in the South America Protein Bar Market reveals how formulation choices, distribution access, and consumer health priorities create distinct competitive battlegrounds. Manufacturers must align protein sourcing strategies with regulatory frameworks and channel economics to capture value.
Product Type:
Mature whey-based formulations coexist with emerging plant-protein alternatives as Brazilian consumers reduce dairy intake and ANVISA tightens compositional verification.
- Whey:Dairy-derived isolates deliver complete amino acid profiles with rapid absorption kinetics favored by strength athletes. Brazilian manufacturers import North American and European isolates, exposing margins to currency volatility and freight rate spikes in the southeastern corridor.
- Plant-Based:Pea-rice protein blends processed through cold-pressed manufacturing preserve heat-sensitive amino acids while closing the sensory gap with dairy incumbents. São Paulo and Rio de Janeiro fitness communities normalize these formulations as gym culture penetrates secondary cities.
- Soy:Argentina's domestic crushing facilities supply cost-competitive isolates under import substitution policies.
- Casein:Slow-release dairy protein targets overnight recovery positioning with limited shelf presence.
Whey retains volume leadership; plant-based holds the steepest expansion curve.
Target Audience:
Cost tiers separate premium-tolerance athletes from price-sensitive health-conscious segments, with diabetic formulations commanding specialized positioning.
- Athletes:Competitive and recreational competitors demand 20-30 gram protein servings with verified amino acid profiles. These consumers accept premium pricing and exhibit habitual repeat purchase patterns in São Paulo's independent fitness studios.
- Fitness Enthusiasts:Urban professionals in CrossFit communities normalize post-workout consumption, creating consistent demand through revenue-sharing gym retail arrangements.
- Health-Conscious Consumers:Ingredient label scrutiny drives cleaner-label preferences across Brazilian supermarket channels.
- Diabetics:Low-glycemic formulations with sugar alcohol binders address metabolic management needs.
Athletes dominate margin pools; fitness enthusiasts represent the broadest addressable base.
Distribution Channel:
Channel fragmentation is displacing traditional wholesale economics as Brazilian gym operators unbundle retail from membership fees.
- Retail:Brazilian supermarket and pharmacy chains reallocate shelf space from supplements toward fortified snacks, creating premium positioning opportunities in the southeastern corridor.
- Gym Stores:Revenue-sharing arrangements with external vendors replace pro-shop wholesale models in São Paulo's independent studios.
- Online:Direct-to-consumer subscriptions bypass ANVISA claim verification delays for established brands with domestic quality infrastructure.
- Vending Machines:Temperature-controlled units require retrofitting from chocolate confection standards to accommodate protein bar texture sensitivity.
Retail commands volume concentration; gym stores are climbing the fastest as channel control shifts.
Flavor Profile:
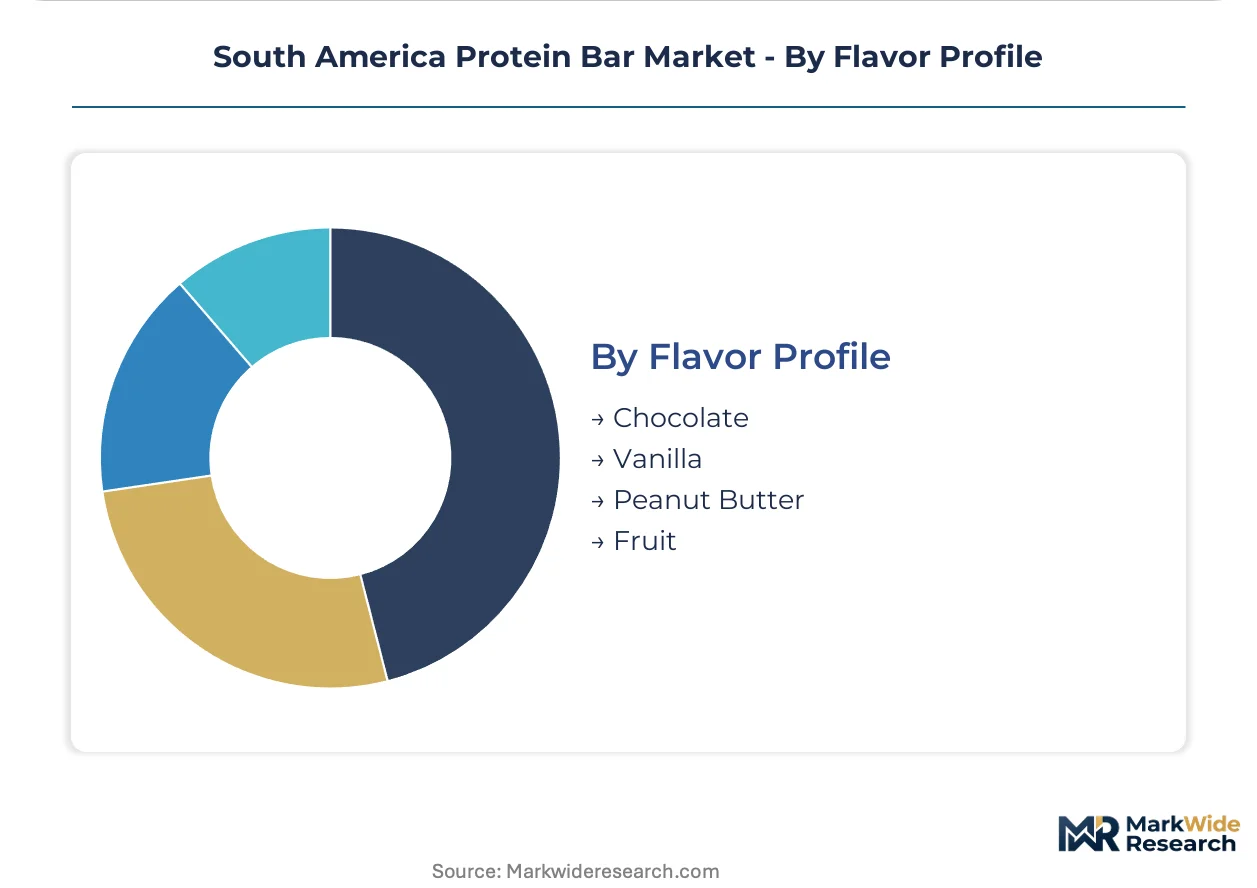
Application-driven preferences reflect functional consumption occasions rather than indulgence positioning.
- Chocolate:Cocoa-based coatings mask plant-protein off-notes while delivering familiar sensory expectations.
- Peanut Butter:Brazilian domestic nut sourcing supports cost-competitive formulations with regional taste alignment.
- Vanilla:Neutral base enables cleaner-label positioning with minimal ingredient complexity.
- Fruit:Natural flavor systems appeal to ingredient-conscious consumers reducing artificial additive exposure.
Chocolate anchors standard assortment; peanut butter gains share fastest through local sourcing economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mercosur harmonization talks are reshaping cross-border manufacturing strategies as Brazilian import substitution policies and Argentine domestic sourcing mandates redirect supply chain configurations across the continent.
Brazil
ANVISA's protein-content verification protocols compress product development cycles for domestic manufacturers. The southeastern corridor spanning São Paulo, Rio de Janeiro, and Belo Horizonte concentrates demand as gym culture penetrates secondary cities. Cold-pressed manufacturing adoption accelerates in this cluster to preserve heat-sensitive amino acid profiles.
Argentina
Domestic soy protein crushing facilities supply cost-competitive isolates under national food code mandates. Updated compositional thresholds for protein content declarations force batch-by-batch third-party laboratory verification. Buenos Aires and Córdoba anchor production capacity with captive laboratory relationships advantaging local producers.
Colombia
Bogotá and Medellín fitness club density now matches 2018 São Paulo levels, yet protein bar shelf space remains underdeveloped in Andean retail channels. The national food and drug surveillance institute enforces labeling standards that imported brands must navigate for market entry. Pharmacy channel expansion creates premium positioning opportunities in urban centers.
Chile
Santiago's functional fitness communities normalize post-workout protein consumption among urban professionals. The national economic prosecutor's office monitors competition compliance as multinational brands expand distribution. Temperature-controlled logistics networks require retrofitting from chocolate confection standards to accommodate protein bar texture sensitivity.
Uruguay
Proposed unified Mercosur nutritional labeling standards would eliminate duplicate certification costs for manufacturers operating across the trade bloc. Montevideo's food control service aligns with regional harmonization timelines. The metropolitan area serves as a testbed for cross-border distribution models ahead of broader regulatory convergence.
South America Protein Bar Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented retail and gym store networks. The market structure tiers between multinational packaged food conglomerates with Pan-American distribution infrastructure and focused nutrition brands targeting functional fitness communities. Three archetypes dominate: diversified food conglomerates leveraging existing retail relationships, specialized sports nutrition firms commanding premium pricing, and domestic South American producers exploiting local sourcing economics. Competitive moves concentrate on pharmacy channel expansion and revenue-sharing arrangements with gym operators displacing traditional wholesale models.
Among diversified food conglomerates, Nestlé S.A. and General Mills Inc exemplify scale-driven positioning through existing retail network access. Quest Nutrition LLC occupies the specialist tier with high-protein formulations targeting CrossFit communities. Arcor anchors the domestic producer archetype through backward integration into Argentine soy protein sourcing. These three represent distinct competitive vectors rather than direct substitutes.
| Leading Market Players |
|---|
| General Mills Inc |
| Nestlé S.A. |
| The Kellogg Company |
| Quest Nutrition LLC |
| Arcor |
| Skout Backcountry LLC |
| Clif Bar |
| PowerBar |
| MusclePharm Corp |
| Others |
Value Network & Pricing Analysis
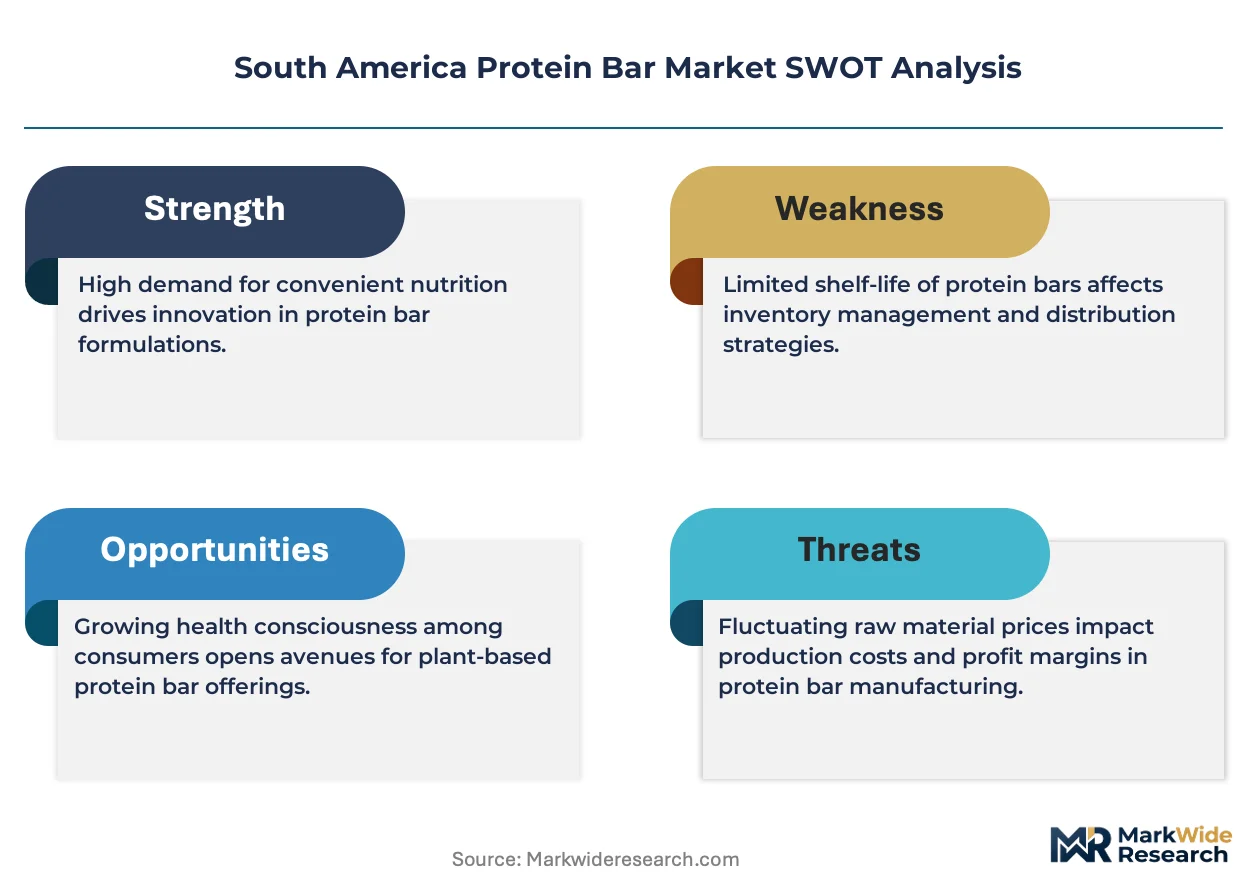
Whey protein import dependency from North American and European dairy isolate shipments compresses both margin structures and supply chain configurations across Brazilian manufacturers. Currency volatility against the real and ocean freight rate spikes force pricing stratification between whey-based premium tiers and domestically sourced plant-protein alternatives, while Argentine import substitution policies redirect soy protein sourcing toward domestic crushing facilities with cost-competitive positioning.
Pricing Analysis
Certification level under ANVISA's protein-content verification protocols creates the primary spread between validated premium formulations and unverified economy alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by verified amino acid profiling, cold-pressed manufacturing adoption, and pharmacy channel positioning. Pricing pressure stems from fresh food substitution in secondary Brazilian cities where grilled chicken and rice retain cost advantages. Health-conscious supermarket shoppers exhibit highest price sensitivity; athletes in São Paulo's independent fitness studios demonstrate lowest.
Supply Chain Analysis
ANVISA's evolving health claim verification timelines function as export-control equivalents for imported brands lacking domestic quality infrastructure, limiting cross-border product flows. Geographic supply concentrates in Argentina for soy protein isolates, Brazil for domestic pea-rice blends, and North America for whey isolates. Raw material dependencies span hydrolyzed collagen, plant-based syrups, and third-party laboratory verification services. Single-source vulnerability runs through Brazilian manufacturers' reliance on European whey shipments. Distribution runs through pharmacy chain reallocations and revenue-sharing gym retail arrangements displacing wholesale models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against fresh food alternatives and unregulated informal protein sources that undercut verified formulations on price. Traditional post-gym meals retain cultural preference advantages that bar manufacturers must overcome through convenience positioning and verified nutritional claims.
For Market Incumbents: Harden laboratory verification infrastructure to compress ANVISA submission cycles below competitor timelines, locking in marketing message advantages. Deepen backward integration into Argentine soy protein sourcing to insulate margins from whey import volatility. Channel control through exclusive revenue-sharing arrangements with São Paulo's independent fitness studios creates defensive moats against retail price erosion.
For New Entrants and Emerging Players: Pursue Colombian market entry where Bogotá and Medellín fitness club density matches 2018 São Paulo levels yet protein bar shelf space remains underdeveloped. Target pharmacy channel expansion in Brazilian drugstore chains reallocating space from supplements toward fortified snacks. Direct-to-consumer subscription models bypass ANVISA claim verification delays for brands with domestic quality infrastructure.
For Investors and Strategic Acquirers: Cold-pressed manufacturing specialists with captive pea-rice protein sourcing represent priority acquisition archetypes as plant-based adoption accelerates. Long-term viability hinges on regulatory verification capabilities becoming scarcer competitive assets across the projection horizon. Watch Mercosur harmonization implementation timelines as inflection indicators for cross-border manufacturing consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soy Protein | Argentine domestic crushing facilities supply cost-competitive isolates under import substitution mandates. |
| Cold-Pressed Manufacturing Scale-Up | Preserves heat-sensitive amino acid profiles in pea-rice blends closing sensory gaps with whey. |
| Pharmacy Channel Expansion | Brazilian drugstore chains reallocate shelf space from supplements toward fortified snack positioning. |
| Revenue-Sharing Gym Retail | São Paulo independent studios convert pro-shop space into external vendor arrangements displacing wholesale. |
| Collagen-Peptide Convergence | Hydrolyzed collagen inclusion addresses joint health positioning while maintaining protein content differentiation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANVISA regulatory filings, Argentine national food code updates, Nielsen retail audit data, and customs trade records across the Mercosur bloc. Primary interviews engaged brand managers at multinational packaged food conglomerates, category buyers at Brazilian pharmacy chains, supply planners at Argentine soy crushing facilities, and technical R&D directors at cold-pressed manufacturing operations. Bottom-up demand modeling triangulates against top-down market sizing from production capacity assessments and channel shipment data.
Forecast inputs span protein source segmentation, target audience tiers, distribution channel economics, and flavor profile adoption curves across the projection horizon. The analytical framework models whey versus plant-based formulation splits, athlete versus health-conscious consumer penetration rates, and retail versus gym store channel shifts. CAGRs derive from regression analysis against gym culture penetration indices and regulatory verification timeline compressions. Industry-specific inputs include CrossFit community growth rates and ANVISA submission backlog trends.
Sensitivities concentrate around Mercosur harmonization implementation delays, currency volatility against whey import costs, and fresh food substitution persistence in secondary Brazilian cities. Forecasts reflect documented assumptions on regulatory timeline evolution and consumer dairy reduction trajectories. Material shifts in ANVISA verification protocols or Argentine import substitution policy intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
No Fat Snacks Market
Snacks
UAE Cereal Bar Market
Snacks
Argentina Snack Bar Market
Snacks
North America Energy Bar Market
Snacks
Latin America Extruded Snack Food Market
Snacks
North America Potato Chips Market
Snacks
Savory Snacks Market
Snacks
Global Tortilla Chips Market
Snacks
Duck Neck (Chinese Snack) Market
Snacks
North America Snack Pellets Market
Snacks
High Fiber Snack Foods Market
Snacks
UAE Snack Bar Market
Snacks
Organic Snacks Market
Snacks
North America Snack Bar Market
Snacks
Extruded Cereals Market
Snacks
North America Fruit Snacks Market