
 Baked Chips Market | 2026-2036
Baked Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Baked Chips Market Analysis
Convenience retail is pivoting toward better-for-you snack sets, expanding facings for baked formats over fried alternatives. PepsiCo leverages its Frito-Lay distribution network to sustain national shelf dominance in the baked segment. Kettle Brand differentiates through regional flavor specialization and premium positioning in natural grocery channels. Hain Celestial anchors its portfolio in organic and non-GMO baked chip lines that command higher retail margins.
Baked chips are thin-sliced or extruded snack products cooked via forced hot-air convection rather than oil immersion, typically containing 40-70% less fat than fried equivalents by weight. The primary commercial purpose is delivering craveable crunch and flavor delivery in permissible indulgence formats that satisfy clean-label and reduced-fat consumer mandates. Potato-based SKUs still occupy the largest volume share across retail scan data, though vegetable blends incorporating sweet potato, beet, and kale are recording the fastest velocity growth in premium channels. Pouch packaging controls the highest margin pool due to extended shelf stability and lower material cost per ounce versus rigid carton formats.
FDA nutrition labeling requirements and proposed sodium reduction targets directly pressure reformulation timelines and ingredient sourcing decisions across the category. USDA organic certification and Non-GMO Project verification function as de facto market access filters for placement in Whole Foods Market, Sprouts Farmers Market, and comparable natural retail banners. Stakeholders must monitor evolving front-of-package disclosure rules and clean-label threshold definitions that determine which products retain authorized health claims.
Market Dynamics
FDA sodium reduction mandates and front-of-package labeling proposals are compressing formulation cycles while convenience retailers reallocate shelf space toward better-for-you snack sets, forcing manufacturers to accelerate clean-label transitions.
Growth Catalysts
- USDA Organic Certification:Natural grocery banners now require organic or Non-GMO Project verification for baked chip placement, expanding addressable shelf space for compliant manufacturers.
- Millennial and Gen Z urban demand:Coastal US metropolitan clusters show concentrated purchasing velocity for permissible indulgence formats with transparent ingredient decks.
- Forced hot-air convection technology:Equipment advances enable 40-70% fat reduction without sacrificing texture, satisfying clean-label mandates at commercial scale.
Market Restraints
- Input cost volatility:Specialty potato and vegetable blend sourcing faces pressure from agricultural commodity fluctuations and climate-driven yield variability.
- Supply concentration risk:Frito-Lay's distribution network controls dominant shelf presence in mainstream convenience and grocery channels.
- Technical formulation barriers:Sodium reduction targets conflict with flavor delivery requirements, creating reformulation bottlenecks for legacy recipes.
Strategic Opportunities
- Vegetable blend SKUs:Sweet potato, beet, and kale formulations record fastest velocity growth in premium natural channels with higher retail margins.
- Front-of-package labeling tailwind:FDA disclosure rules favor products meeting clean-label thresholds, creating authorized health claim advantages.
- Pouch packaging innovation:Extended shelf stability and lower material cost per ounce versus rigid cartons unlock margin expansion in club and e-commerce channels.
Industry Challenges
- Reformulation timeline compression:FDA sodium targets pressure R&D cycles while maintaining sensory parity with fried alternatives.
- Certification backlog complexity:Non-GMO Project verification and organic accreditation face processing delays that gate retail placement timelines.
- Legacy equipment retrofit costs:Transitioning production lines from oil immersion to forced hot-air convection requires substantial capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baked Chips Market |
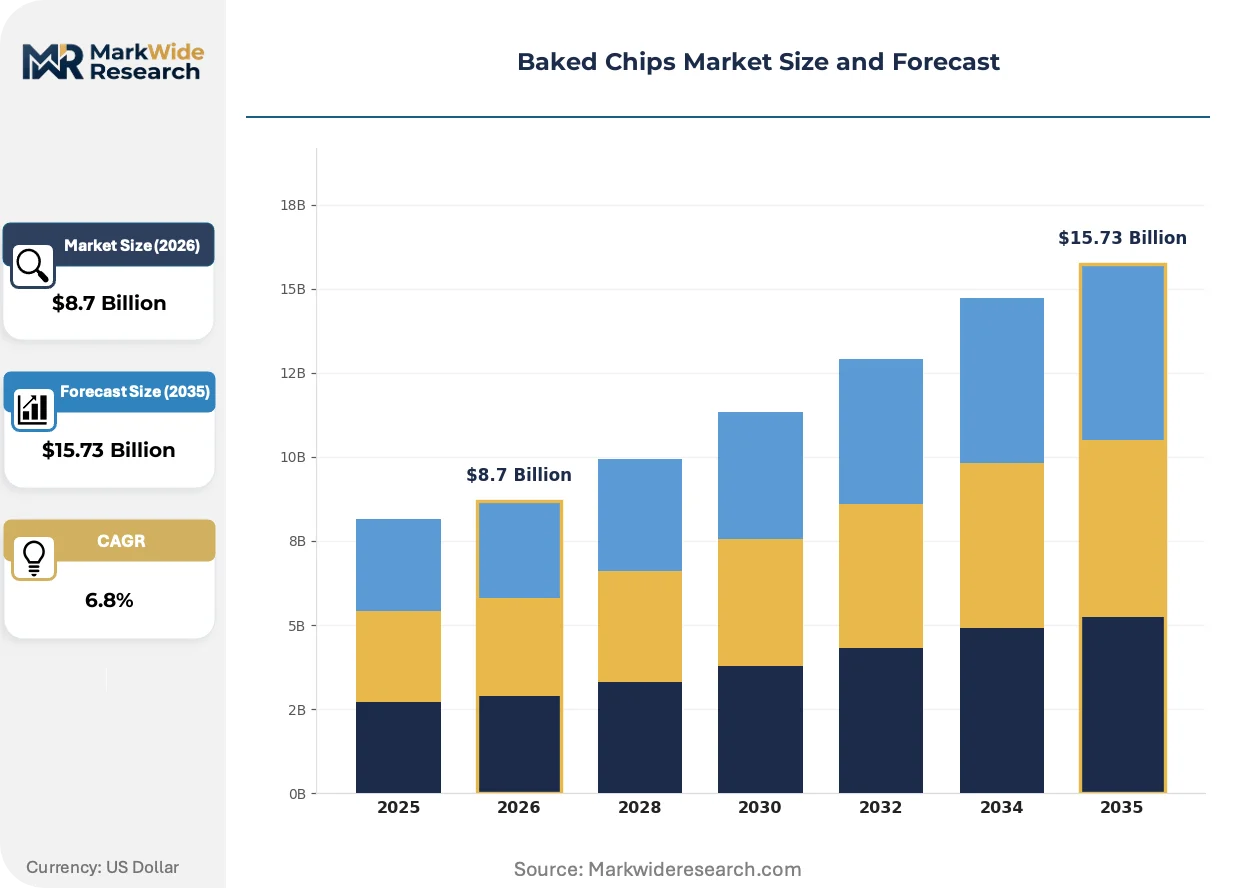
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potato, Corn, Tortilla, Vegetable Flavor Profile: Cheddar, Barbecue, Sour Cream & Onion, Sea Salt Packaging Type: Bag, Box, Carton, Pouch Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Hain Celestial Group, Baked in Brooklyn, PepsiCo, Kettle Brand, Cape Cod, Kraft Heinz, PopChips, Utz Brands, General Mills, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baked Chips Market Emerging Trajectories
Forced hot-air convection systems and clean-label ingredient sourcing are compressing traditional fried snack advantages while regulatory disclosure mandates reshape competitive positioning around transparency credentials.
Precision moisture control technology is integrating into commercial baking lines to maintain crunch texture at reduced fat levels. Premium and natural channel manufacturers are adopting these systems fastest to meet clean-label thresholds. The technology is integrating sensor-driven process control that enables real-time adjustment, compressing yield loss and extending production runs for vegetable-based formulations.
FDA front-of-package labeling proposals are mandating nutrient disclosure formats that favor baked over fried alternatives in retail sets. The industrial consequence is accelerated reformulation investment to capture authorized health claims. Baked potato and vegetable blend SKUs in US convenience and natural grocery channels are responding with simplified ingredient decks and sodium reduction to maintain placement eligibility.
Urban millennial and Gen Z purchasing patterns are rotating toward permissible indulgence formats with transparent supply chain credentials. Direct-to-consumer and subscription snack boxes are displacing traditional impulse purchase occasions in coastal metropolitan markets. This behavioral shift concentrates most visibly in California, New York, and Washington state clusters where natural grocery penetration and digital-native consumption overlap.
Baked Chips Market Segmentation
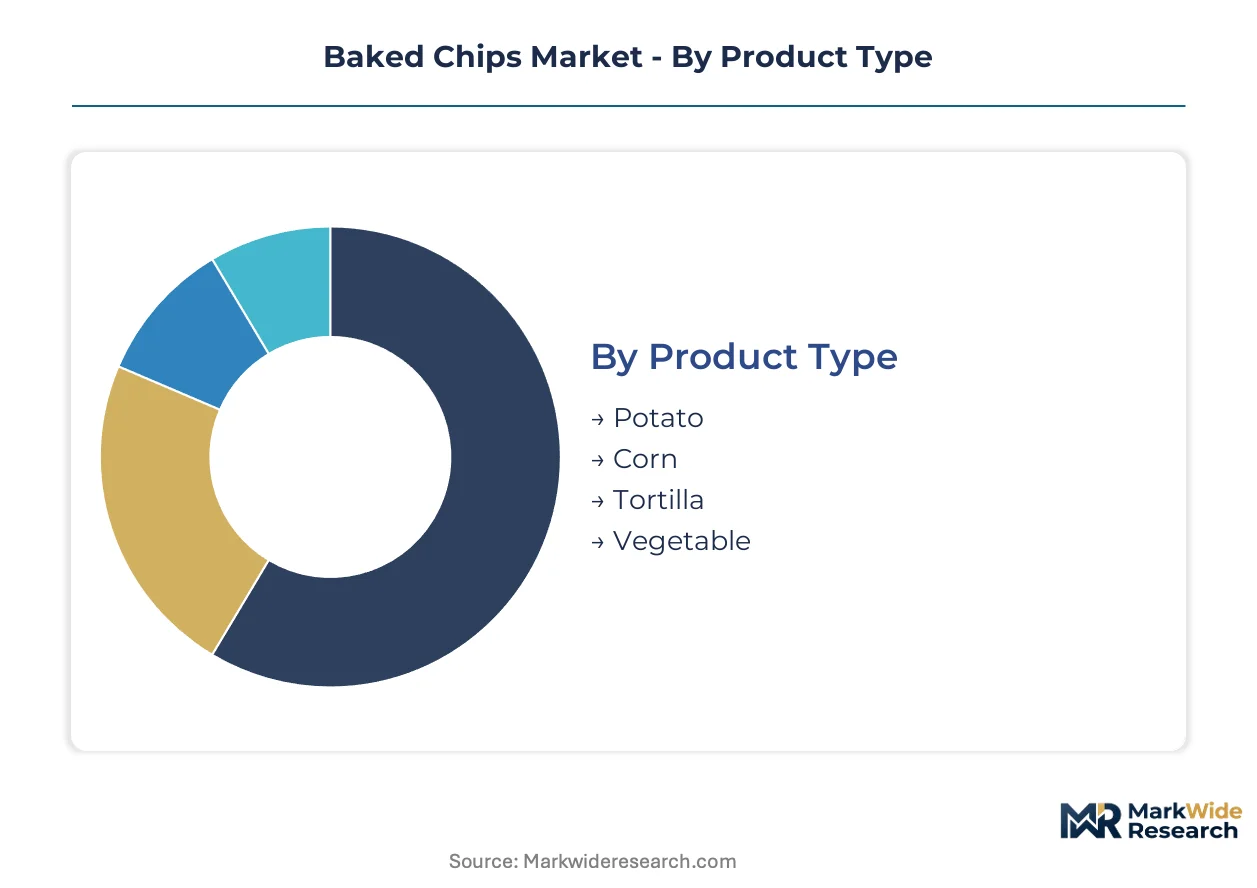
Baked chips manufacturers align product architecture with distinct consumption occasions and channel requirements. Specification choices across base ingredient, flavor intensity, and packaging format determine placement eligibility and margin capture in convenience versus natural grocery channels.
Product Type:
Forced hot-air convection technology enables distinct textural outcomes depending on base ingredient starch composition and moisture content.
- Vegetable:Formulations incorporating sweet potato, beet, and kale leverage lower glycemic indices and vibrant visual differentiation. Demand concentrates in coastal US metropolitan clusters among millennial and Gen Z consumers seeking permissible indulgence with transparent ingredient decks.
- Potato:Thin-sliced tuber products retain the largest volume share across retail scan data due to familiar crunch texture and neutral flavor substrate. US convenience store chains expand facings for reduced-fat potato SKUs as FDA sodium targets pressure reformulation toward clean-label thresholds.
- Corn:Extruded masa-based products deliver denser bite and extended shelf stability. Mexican and Southwestern US regional preferences drive velocity in Hispanic grocery banners.
- Tortilla:Stone-ground or extruded formats with lime or multigrain positioning target premium snacking occasions. Natural channel placement requires Non-GMO Project verification.
Mature deployment sits with potato. Newer deployment is concentrated in vegetable.
Flavor Profile:
Flavor intensity and ingredient complexity determine clean-label compliance and sodium load, directly impacting FDA front-of-package labeling eligibility.
- Sea Salt:Minimal ingredient decks satisfy the strictest clean-label definitions. Whole Foods Market and Sprouts Farmers Market mandate sea salt or no-salt variants for premium placement.
- Barbecue:Tomato, vinegar, and smoke flavor systems require careful sodium management to meet reduction targets. Regional US preferences vary between molasses-forward and vinegar-sharp profiles.
- Sour Cream & Onion:Dairy-derived powder coatings face organic certification requirements in natural channels. Reformulation to plant-based alternatives accelerates.
- Cheddar:Cheese powder sourcing from USDA-certified organic dairies commands retail price premiums. Supply concentration among Wisconsin and California processors creates procurement bottlenecks.
Clean-label velocity is climbing the fastest in sea salt. Complexity and certification burden concentrate in cheddar.
Packaging Type:
Material cost per ounce and shelf stability duration determine margin pool allocation across club, convenience, and e-commerce channels.
- Pouch:Multi-layer film structures with nitrogen flush deliver extended shelf stability and lowest material cost per ounce. Amazon and Costco procurement specifications favor pouch formats for shipping efficiency.
- Bag:Standard pillow pouches dominate impulse purchase occasions in US convenience stores. High graphic surface area supports seasonal and limited-edition marketing.
- Carton:Rigid paperboard formats signal premium positioning in natural grocery. Higher material and shipping costs restrict deployment to high-margin SKUs.
- Box:Corrugated or paperboard multi-serve containers target club channel and direct-to-consumer subscription boxes. California and New York metropolitan clusters show strongest velocity for boxed variety packs.
Volume concentration remains in bag. Margin expansion and channel growth are steepest in pouch.
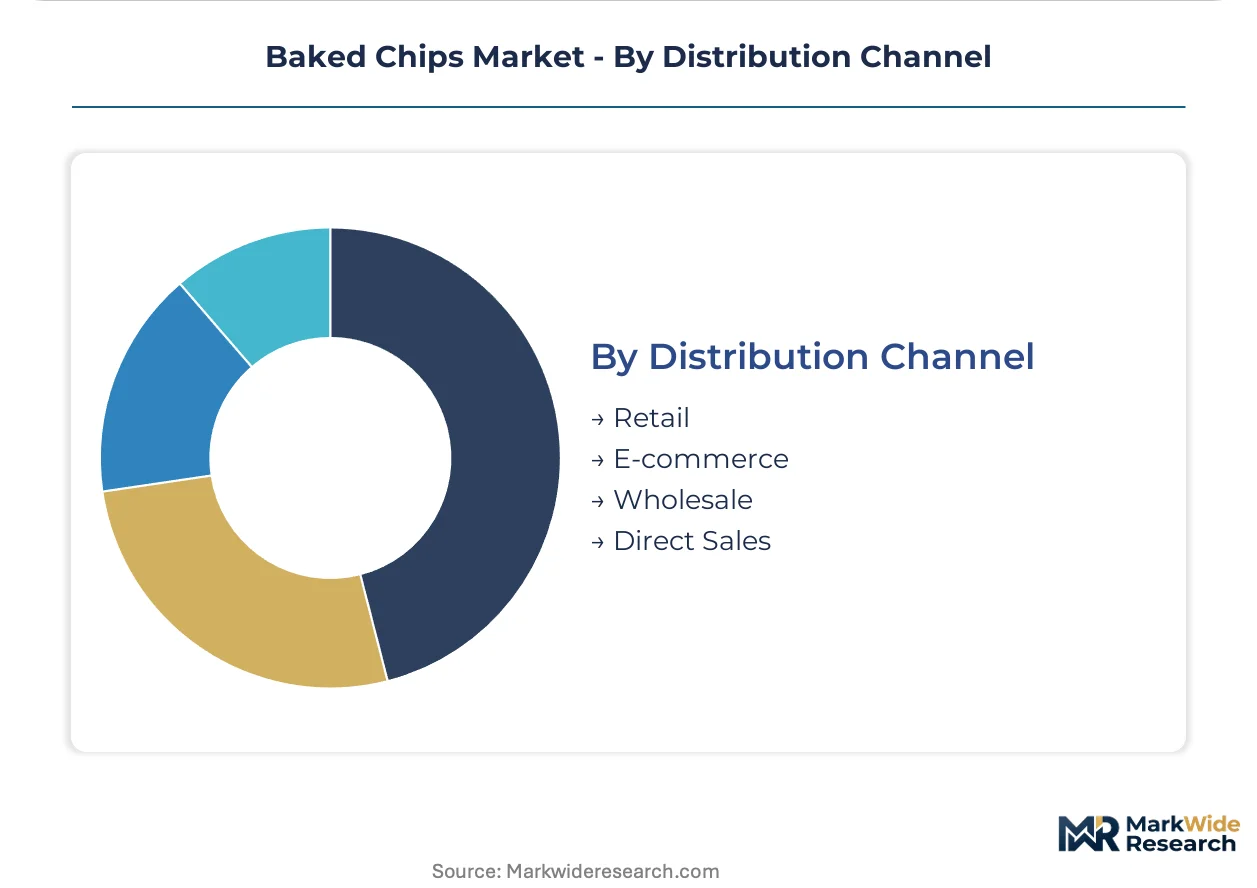
Distribution Channel:
Channel selection dictates pricing architecture, promotional cadence, and consumer data capture capabilities.
- E-commerce:Direct-to-consumer and marketplace platforms enable subscription models and flavor customization. Urban coastal markets in California, New York, and Washington state show highest digital-native snack purchasing velocity.
- Retail:Brick-and-mortar grocery and convenience stores remain the dominant volume channel. Frito-Lay's distribution network controls shelf presence in mainstream US accounts.
- Wholesale:Foodservice and institutional supply to corporate cafeterias, universities, and hospitality. Bidding specifications increasingly require USDA organic or non-GMO verification.
- Direct Sales:Company-owned stores, pop-up activations, and event-based sampling. Premium and emerging brands deploy direct channels to build trial before retail expansion.
Legacy volume anchors in retail. Subscription and data-rich deployment is expanding most quickly in e-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Opportunity Zones and state-level food processing incentives concentrate baked chip manufacturing in designated development corridors. These zones attract capital deployment through tax abatements tied to clean-label production investments. Coastal metropolitan clusters anchor demand velocity for permissible indulgence formats.
United States
Millennial and Gen Z consumers in California, New York, and Washington state drive premium velocity for vegetable-blend SKUs with transparent supply chains. FDA sodium reduction targets and front-of-package labeling proposals compress reformulation timelines for national brands. Austin and Brooklyn anchor emerging direct-to-consumer subscription channels displacing traditional impulse occasions.
Germany
Organic and non-GMO verification requirements from EFSA-aligned national standards gate placement in REWE and Edeka premium snack sets. The country's packaging waste reduction targets pressure manufacturers toward mono-material pouch formats. Bavaria's food processing corridor hosts forced hot-air convection equipment suppliers serving Central European baked snack producers.
United Kingdom
HFSS (high fat, salt, sugar) regulations restrict promotional placement and front-of-store positioning for non-compliant snack products. London and Southeast England concentrate demand for clean-label permissible indulgence formats among urban professional demographics. Tesco and Sainsbury's procurement specifications increasingly mandate reduced-sodium baked alternatives.
Japan
METI-sponsored food technology initiatives accelerate precision moisture control adoption in domestic baking lines. Tokyo and Osaka metropolitan markets show concentrated demand for premium vegetable-blend formats with umami-forward flavor profiles. Convenience store chains Lawson and 7-Eleven Japan expand facings for better-for-you snack sets in response to aging consumer health consciousness.
Australia
Health Star Rating front-of-package labeling mandates favor baked over fried alternatives in Coles and Woolworths shelf resets. Sydney and Melbourne coastal clusters concentrate millennial demand for transparent ingredient decks and regional flavor specialization. The country's agricultural commodity fluctuations create input cost volatility for domestic potato and vegetable blend sourcing.
Baked Chips Market Vendor Landscape
Top-tier vendors anchor mainstream retail distribution, while mid-tier specialists occupy natural grocery and premium channels. The competitive structure stratifies around scale-driven national presence versus certification-heavy premium positioning. Three archetypes dominate: diversified snack conglomerates with baked line extensions, organic specialists with non-GMO verification, and regional craft brands with flavor localization. Capacity expansion and clean-label portfolio diversification constitute the dominant competitive moves across tier levels.
Within the diversified conglomerate tier, PepsiCo and Kraft Heinz exemplify scale-driven distribution leverage through existing snack and grocery networks. Hain Celestial Group occupies a position representing organic and non-GMO specialists commanding retail margin premiums in natural channels. Kettle Brand exemplifies regional flavor specialization archetypes that differentiate through premium positioning rather than price competition.
| Leading Market Players |
|---|
| Hain Celestial Group |
| Baked in Brooklyn |
| PepsiCo |
| Kettle Brand |
| Cape Cod |
| Kraft Heinz |
| PopChips |
| Utz Brands |
| General Mills |
| Others |
Supply Flow & Price Mechanics
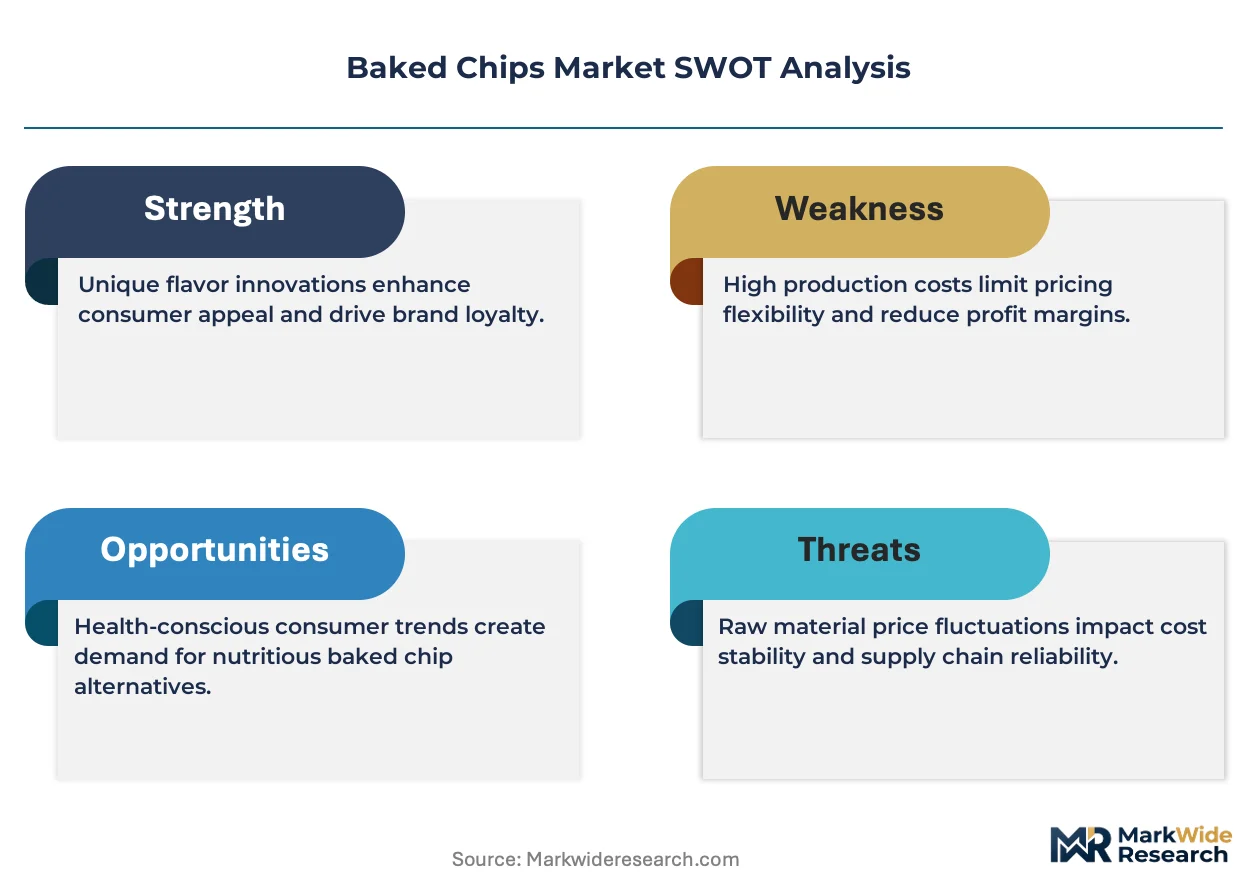
Captive sourcing of specialty potato and vegetable blends anchors margin control for premium baked chip manufacturers while outsourcing commodity inputs to third-party processors. This integration choice concentrates pricing power among vertically aligned producers who can absorb agricultural volatility through contract farming arrangements in Idaho and Washington state growing regions.
Pricing Analysis
Short lead-time premiums apply to organic-certified vegetable blend SKUs requiring expedited Non-GMO Project verification turnaround. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic pouch formats from conventional bagged alternatives and private-label economy tiers. Pricing pressure stems from Frito-Lay's scale-driven procurement leverage in mainstream convenience channels. Foodservice buyers exhibit highest price sensitivity due to bidding specifications, while natural grocery consumers tolerate premiums for transparent supply chain credentials.
Supply Chain Analysis
Freight cost differentials between rigid carton and flexible pouch formats reshape distribution economics for cross-country fulfillment. Raw material sourcing draws from Idaho potato processors, California vegetable blend suppliers, and Wisconsin organic dairy powder facilities. Single-source vulnerability concentrates in forced hot-air convection equipment from Bavarian manufacturers serving North American production lines. Distribution runs through Frito-Lay's direct-store-delivery network for mainstream accounts, with natural channel fulfillment via regional distributors to Whole Foods Market and Sprouts Farmers Market banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The baked chips market sits in a technology-transition phase where forced hot-air convection systems displace legacy oil immersion frying infrastructure. This equipment shift compresses reformulation timelines and capital deployment requirements across the competitive landscape.
For Market Incumbents: Cement shelf presence in expanding better-for-you snack sets by retrofitting production lines to precision moisture control standards before FDA sodium reduction mandates take effect. Prioritize backward integration into organic potato sourcing to secure supply continuity against climate-driven yield variability threatening Idaho and Washington growing regions.
For New Entrants and Emerging Players: The price-point gap between premium organic vegetable blends and economy private-label potato SKUs offers white-space positioning for mid-tier clean-label alternatives. Target direct-to-consumer subscription channels in California and New York metropolitan clusters where millennial purchasing velocity concentrates. Launch with simplified sea salt formulations to bypass certification bottlenecks slowing barbecue and cheddar variant placement.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified snack conglomerates seeking organic certification capabilities and natural channel access. Long-term viability hinges on forced hot-air convection equipment deployment and clean-label portfolio breadth. Monitor FDA front-of-package labeling rule finalization as inflection indicator for reformulation investment cycles and authorized health claim eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Production Line Retrofit | Forced hot-air convection adoption enables 40-70% fat reduction at commercial scale for FDA compliance. |
| Organic Certification Investment | USDA organic and Non-GMO Project verification unlocks placement in Whole Foods Market and Sprouts Farmers Market. |
| Vegetable Blend SKU Expansion | Sweet potato, beet, and kale formulations capture fastest velocity growth in premium natural channels. |
| Pouch Packaging Transition | Multi-layer film structures reduce material cost per ounce and extend shelf stability for Amazon and Costco. |
| Direct-to-Consumer Launch | Subscription models in coastal metropolitan clusters displace traditional impulse purchase occasions. |
Methodological Framework
Document review covered FDA filing databases, USDA organic certification registries, and Nielsen retail audit data, complemented by interviews with baked chip category managers at natural grocery banners, Frito-Lay distribution executives, forced hot-air convection equipment suppliers, and organic potato sourcing coordinators. Secondary validation drew from SEC 10-K filings of public snack manufacturers, customs import records for vegetable blend ingredients, and equipment procurement disclosures. Bottom-up SKU velocity analysis triangulated against top-down category spending estimates.
Historical shipment data cross-referenced against panel input from procurement officers at convenience store chains and natural grocery buyers shaped the analytical framework across the analysis window. Segmentation dimensions modeled include base ingredient type, flavor profile intensity, packaging format, and distribution channel. CAGRs were derived from trend extrapolation adjusted for regulatory timeline impacts and technology adoption curves. Forecast inputs incorporated FDA sodium reduction target implementation schedules and forced hot-air convection equipment deployment pipelines.
Inputs from Nielsen retail scan data and USDA organic certification databases were available through the study window; gaps in private-label manufacturer production disclosures introduce uncertainty bands around volume share estimates. Forecasts reflect documented assumptions regarding regulatory implementation timing and clean-label threshold evolution. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Mediterranean Lentil Crisps and Inclusion Bases Market
Snacks
North America Pretzel Market
Snacks
Europe Energy Bar Market
Snacks
Middle-East and Africa Cereal Bar Market
Snacks
North America Extruded Snack Food Market
Snacks
Dairy Snacks Market
Snacks
Low Calorie Granola Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Extruded Snacks Market
Snacks
Healthy Fruit and Vegetable Chips Market
Snacks
Edible Flakes Market
Snacks
Spain Snack Bar Market
Snacks
Low Calorie Dip Market
Snacks
South East Asia Snack Bar Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Peanut Butter Keto Snacks Market