
 Europe Hummus Market | 2026-2036
Europe Hummus Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hummus Market Analysis
Private-label hummus production is reconfiguring margin pools away from branded premiums toward retailer-controlled supply chains. Bakkavor Group leverages its chilled-food manufacturing scale to dominate UK retail listings. Strauss Group anchors its European position through Sabra Dipping Company's Mediterranean recipe specialization. Deldiche N.V. competes in Benelux food-service channels with industrial-volume formats.
Hummus is a cold-processed chickpea-tahini emulsion with a typical pH below 4.6, preserved through refrigeration and high-pressure processing rather than thermal sterilization. Classic formulations remain the volume foundation, while Roasted Red Pepper variants command higher shelf prices in specialty stores. Tub packaging leads household penetration, though pouch formats are gaining traction in online channels where shipping-weight reduction matters.
EFSA governs novel ingredient approvals for functional additive claims, while EU Green Deal packaging rules from ECHA mandate recyclability targets that reshape tub material selection. REACH compliance for imported tahini supply chains affects raw-material sourcing costs. Stakeholders must monitor how CSRD disclosure requirements alter supplier auditing depth for sesame seed provenance.
Market Dynamics
Private-label expansion is compressing branded hummus margins across European retail channels, forcing manufacturers to reconfigure production economics around retailer-controlled supply chains rather than consumer brand loyalty.
Growth Catalysts
- EU Green Deal packaging mandates:ECHA recyclability targets are accelerating tub material innovation toward mono-material polypropylene formats that reduce sorting complexity for municipal waste systems.
- United Kingdom:Chilled deli section expansion in Tesco, Sainsbury's and Waitrose is creating dedicated shelf space for premium-positioned hummus variants with extended ingredient storytelling.
- High-pressure processing:Cold-pasteurization technology is extending refrigerated shelf life without thermal degradation of tahini emulsion texture, enabling wider distribution radii from centralized production.
Market Restraints
- Sesame seed supply concentration:Ethiopian and Sudanese tahini sourcing dominates European import volumes, exposing processors to Red Sea shipping disruptions and currency volatility in origin markets.
- REACH compliance costs:ECHA registration requirements for imported tahini supply chains add documentation burden and testing expenditure for small-batch artisanal producers without dedicated regulatory staff.
- Refrigerated logistics intensity:Cold-chain distribution from production through retail consumes margin at rates that disadvantage regional entrants against national-scale chilled-food networks.
Strategic Opportunities
- Poland and Romania:Modern retail penetration in these markets remains below Western European benchmarks, creating first-mover advantage for private-label suppliers establishing chilled-dip category conventions.
- Food-service pouch formats:Squeeze-tube and portion-control packaging is displacing bulk tubs in contract catering and airline meal production, opening volume contracts with institutional buyers.
- CSRD disclosure requirements:Mandatory supplier auditing for sesame provenance creates competitive differentiation for operators with traceable seed-to-tub documentation systems.
Industry Challenges
- Chickpea protein functionality:Formulation chemists with expertise in cold-processed emulsion stability remain scarce, constraining R&D velocity for texture-modified variants targeting specific dietary positioning.
- Dual certification burden:Organic and kosher/halal accreditation timelines stretch 8-14 months, delaying product launches and locking working capital in inventory awaiting label approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hummus Market |
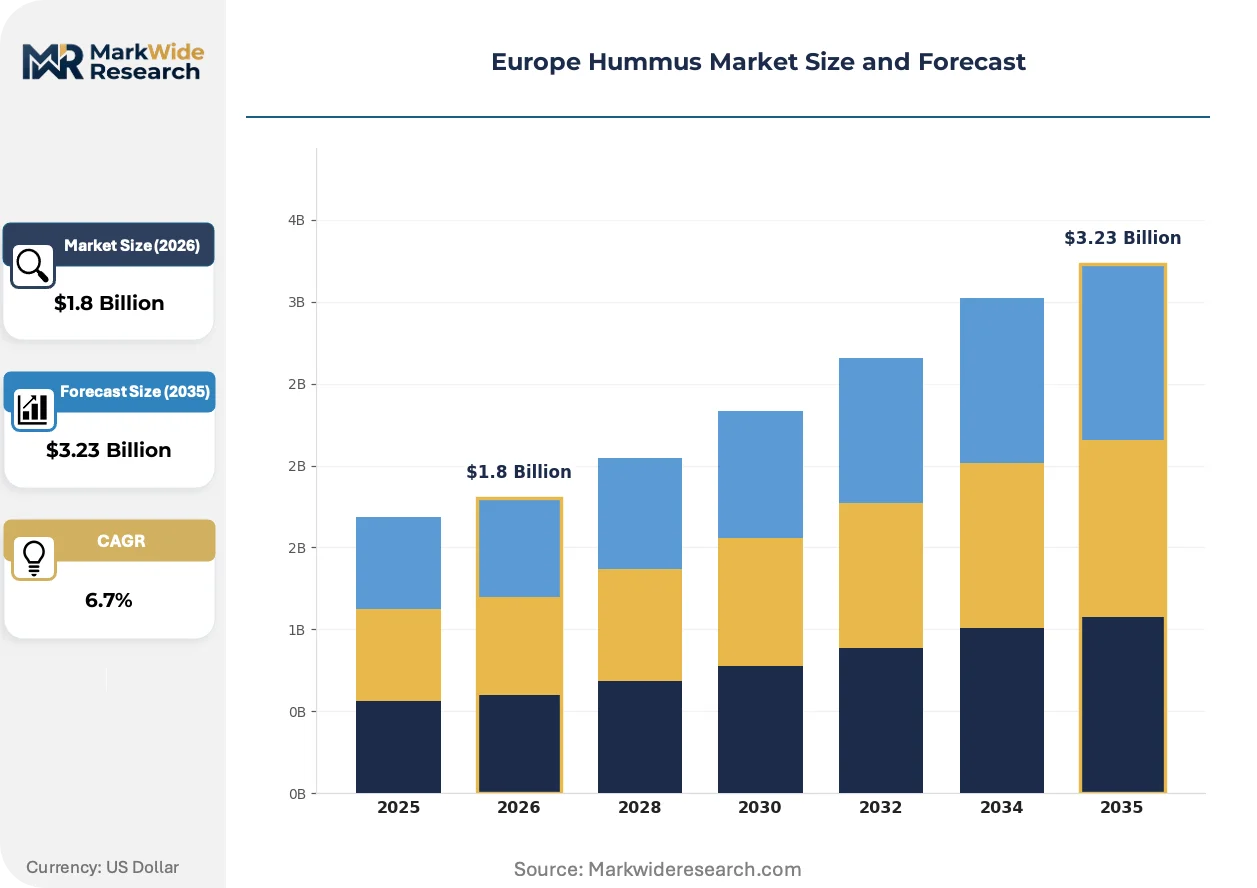
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Spicy, Garlic, Roasted Red Pepper Packaging Type: Tub, Sachet, Jar, Pouch End User: Household, Food Service, Retail, Industrial Distribution Channel: Supermarket, Online, Specialty Stores, Wholesale |
| Companies Covered | Obela, Me Too! Foods, Sabra Dipping Company, Deldiche N.V., Moorish, Bakkavor Group, Tribe Mediterranean Foods, Tahini Bros, Strauss Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hummus Market Emerging Trajectories
Digital shelf analytics and AI-driven demand forecasting are reconfiguring how hummus manufacturers align production runs with promotional calendars in European grocery retail.
High-pressure processing equipment is virtualizing the traditional thermal pasteurization infrastructure that once anchored regional production economics. German and Dutch co-manufacturers are adopting HPP units at 15-20% annual expansion rates, enabling centralized production for multiple retail banners without geographic proximity to end markets. This compression of the pasteurization step is virtualizing the need for distributed thermal processing facilities across national borders.
EFSA novel food ingredient pathways are tightening scrutiny on functional additive claims for probiotic and protein-fortified hummus variants. Manufacturers seeking "gut health" or "high protein" positioning must now submit dossiers demonstrating substantiated physiological benefit, extending time-to-market by 18-24 months for innovation pipelines. Spanish and Italian processors are responding by reformulating around established ingredients with pre-cleared status rather than pioneering unproven bioactive additions.
Direct-to-restaurant ordering platforms are fragmenting traditional food-service distribution concentration in the Benelux and Nordics. Chef buyers in Copenhagen and Brussels are sourcing artisanal hummus through specialized B2B marketplaces that bypass broadline distributors, compressing order minimums and delivery frequencies. This channel disintermediation is most visible in premium independent restaurants where menu differentiation justifies supplier relationship overhead.
Europe Hummus Market Segmentation
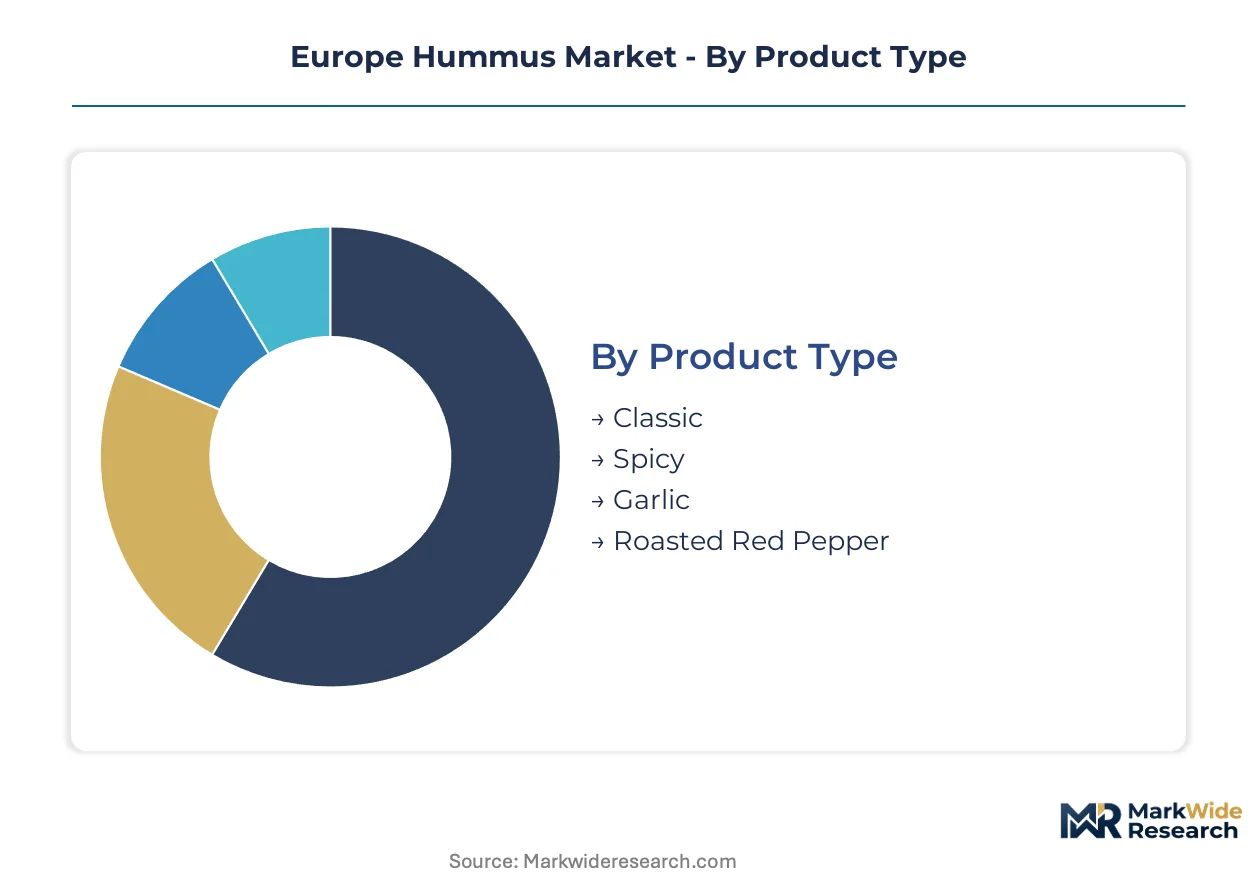
Segmentation in the Europe hummus market reveals how cold-chain logistics, packaging innovation, and channel economics fragment commercial opportunity across distinct demand profiles. Manufacturers configure production lines and shelf-life protocols around these divisions rather than treating hummus as a uniform commodity.
Product Type:
Flavor positioning separates volume foundation from margin extraction across European retail channels.
- Classic:The foundational chickpea-tahini emulsion with lemon and garlic maintains the largest production volumes. German and French supermarket chains stock this variant at entry price points to drive category penetration in households new to Mediterranean dips.
- Roasted Red Pepper:Smoked paprika and fire-roasted capsicum formulations command shelf price premiums in UK specialty stores. Waitrose and Selfridges position these variants with extended ingredient storytelling that justifies refrigerated logistics costs.
- Spicy:Harissa-infused and chili-forward recipes target younger demographics in urban markets.
- Garlic:Elevated allium content appeals to Mediterranean-origin communities concentrated in London and Paris.
Classic commands the established base. The steepest expansion runs through Roasted Red Pepper.
Packaging Type:
Container format dictates cold-chain intensity, shipping economics, and retail shelf placement across the region.
- Tub:Mono-material polypropylene tubs dominate UK and German retail penetration. ECHA recyclability mandates under the EU Green Deal are accelerating mono-material adoption to reduce municipal sorting complexity.
- Pouch:Flexible formats reduce shipping weight for online channels and food-service institutional buyers. Squeeze-tube configurations are displacing bulk tubs in contract catering and airline meal production.
- Sachet:Single-serve portions target convenience stores and grab-and-go retail in Benelux transit hubs.
- Jar:Glass containers persist in Italian and Spanish premium positioning despite higher logistics costs.
Tub formats anchor household penetration. Pouch configurations are gaining share fastest in food-service and e-commerce channels.
End User:
Customer type determines batch size, certification burden, and formulation stability requirements.
- Household:Consumer packs require extended refrigerated shelf life through high-pressure processing. Tesco and Sainsbury's chilled deli sections stock 200-300 gram formats for weekly purchase cycles.
- Food Service:Restaurant and catering volumes demand industrial-scale consistency with shorter delivery frequencies. Copenhagen and Brussels chef buyers are sourcing through specialized B2B marketplaces that bypass broadline distributors.
- Retail:Private-label production for supermarket banners concentrates in UK chilled-food manufacturing networks.
- Industrial:Ingredient-grade hummus for processed food manufacturing requires modified texture for downstream incorporation.
Household consumption commands the established base. Food Service is climbing the fastest as channel disintermediation accelerates.
Distribution Channel:
Channel selection shapes margin retention, promotional cadence, and traceability documentation depth.
- Supermarket:Chilled deli section expansion in Tesco, Sainsbury's, and Waitrose creates dedicated shelf space for premium-positioned variants. Private-label expansion here is compressing branded margins across UK retail channels.
- Online:E-commerce growth favors pouch formats where shipping-weight reduction offsets cold-chain packaging costs. German and Dutch co-manufacturers are adopting high-pressure processing to enable centralized production for multiple retail banners.
- Specialty Stores:Mediterranean grocers and organic retailers stock artisanal variants with extended provenance documentation.
- Wholesale:Broadline distributors serve institutional buyers with bulk formats, though this channel is fragmenting in the Nordics and Benelux.
Supermarket channels command the established base. Online distribution represents the fastest-growing trajectory as digital shelf analytics reconfigure promotional calendars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United Kingdom households consume hummus as a staple sandwich spread and crudité dip, while German shoppers treat it primarily as a Mediterranean specialty condiment alongside falafel and kebab. French retail channels emphasize premium provenance storytelling over volume positioning. This consumption-mix differential shapes how manufacturers configure formulation stability, packaging formats, and chilled-logistics investments across national markets.
United Kingdom
Tesco, Sainsbury's and Waitrose chilled deli sections now dedicate expanded shelf space to premium-positioned hummus variants with extended ingredient provenance documentation. EFSA novel food ingredient pathways govern functional additive claims for probiotic and protein-fortified variants seeking "gut health" positioning. London and the Southeast anchor UK consumption, with Birmingham and Manchester emerging as secondary demand clusters where independent Mediterranean grocers compete with supermarket private-label penetration.
Germany
Rewe, Edeka and Aldi Süd supermarket chains are widening retail shelf space for plant-based dips as flexitarian diets expand beyond Berlin and Hamburg into secondary cities. EU Green Deal sustainable packaging mandates from ECHA push manufacturers toward recyclable mono-material polypropylene tub formats that reduce municipal sorting complexity. The Rhine-Ruhr industrial corridor hosts chilled-food manufacturing networks serving both domestic retail and export markets into neighboring Benelux and Austria.
France
Carrefour and Monoprix premium positioning strategies emphasize Mediterranean terroir storytelling for hummus variants stocked in dedicated chilled sections. REACH compliance requirements for imported tahini supply chains add documentation burden and testing expenditure, particularly affecting small-batch artisanal producers without dedicated regulatory staff. Paris and the Île-de-France region concentrate demand, with Lyon and Marseille emerging as secondary clusters where North African-origin communities sustain specialty retailer channels.
Netherlands
Albert Heijn and Jumbo supermarket banners drive private-label hummus penetration, compressing branded margins across Dutch retail channels. ECHA registration requirements for sesame seed derivatives shape raw-material sourcing economics for processors importing Ethiopian and Sudanese tahini volumes. The Randstad conurbation anchors consumption, with Rotterdam's port infrastructure serving as the primary European entry point for containerized chickpea and sesame seed shipments from origin markets.
Poland
Biedronka and Żabka modern retail penetration remains below Western European benchmarks, creating first-mover advantage for private-label suppliers establishing chilled-dip category conventions. CSRD disclosure requirements for supplier auditing depth alter how processors document sesame seed provenance for institutional buyers. Warsaw and the Masovian Voivodeship lead consumption growth, with Kraków and Wrocław emerging as secondary clusters where food-service channels experiment with portion-control pouch formats for contract catering contracts.
Europe Hummus Market Vendor Landscape
Capability concentration sits with chilled-food manufacturing specialists; scale advantage sits with diversified food conglomerates. The vendor base organizes around three strategic archetypes: retailer-controlled private-label producers, Mediterranean-recipe brand specialists, and tahini-forward artisanal operators. Consolidation pressure runs through supermarket banner consolidation and co-manufacturing network rationalization. Dominant competitive moves include backward integration into sesame seed sourcing and geographic expansion through chilled-distribution partnerships.
Within the private-label manufacturing tier, Bakkavor Group and Deldiche N.V. exemplify scale-driven production economics configured around retailer-controlled supply chains. Sabra Dipping Company and Strauss Group occupy positions as Mediterranean-recipe specialists leveraging tahini emulsion expertise for branded premium positioning. Moorish and Tribe Mediterranean Foods represent the artisanal tier where provenance documentation and small-batch texture differentiation command shelf price premiums in specialty retail channels.
| Leading Market Players |
|---|
| Obela |
| Me Too! Foods |
| Sabra Dipping Company |
| Deldiche N.V. |
| Moorish |
| Bakkavor Group |
| Tribe Mediterranean Foods |
| Tahini Bros |
| Strauss Group |
| Others |
Supply Flow & Price Mechanics
Ethiopian and Sudanese tahini sourcing concentration anchors European hummus production economics, transmitting origin-market currency volatility and Red Sea shipping disruptions directly into processor margin structures downstream. Cold-chain distribution intensity from production through retail consumes margin at rates that disadvantage regional entrants against national-scale chilled-food networks, concentrating pricing power with manufacturers operating centralized high-pressure processing facilities.
Pricing Analysis
Long-term offtake contracts between supermarket banners and chilled-food manufacturers dominate volume procurement, insulating anchor buyers from spot-market tahini volatility while compressing branded premiums. Three-tier pricing structure across premium, standard, and economy levels separates Waitrose-positioned provenance-storytelling variants from private-label entry points at Aldi Süd and Lidl. Cost compression in the standard tier is intensifying because private-label expansion forces branded manufacturers to absorb logistics overhead without price recovery. Food-service institutional buyers exhibit highest price sensitivity due to squeeze-tube format commoditization, while specialty Mediterranean grocers sustain lowest sensitivity through artisanal texture differentiation.
Supply Chain Analysis
Tariff exposure between Ethiopia and EU customs authorities dominates supply chain risk planning for tahini-dependent processors. Raw material sourcing draws from Ethiopian sesame seed harvests, Sudanese tahini milling, and Turkish chickpea processing as the three anchor geographies. Single-source vulnerability concentrates in Red Sea shipping lanes where Houthi disruption has forced route diversion around the Cape of Good Hope. Distribution runs through Rotterdam's port infrastructure into Rhine-Ruhr chilled-food manufacturing networks serving retail banners across Germany, the Netherlands, and export markets into Austria and Benelux.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing virtualization is disrupting traditional thermal pasteurization economics, compressing the geographic radius within which regional production facilities can compete against centralized co-manufacturing networks.
For Market Incumbents: Harden chilled-distribution partnerships through exclusive capacity reservations at German and Dutch co-manufacturing facilities adopting HPP units at 15-20% annual expansion rates. Secure backward integration into traceable sesame seed provenance documentation systems ahead of CSRD disclosure mandates. Private-label margin compression from retailer-controlled supply chains threatens branded premium positioning unless manufacturers anchor differentiation through EFSA-cleared functional additive claims.
For New Entrants and Emerging Players: Poland and Romania's modern retail penetration gaps below Western European benchmarks offer first-mover advantage for private-label suppliers establishing chilled-dip category conventions. Food-service pouch formats in contract catering and airline meal production represent the most penetrable white-space segment, with squeeze-tube configurations displacing bulk tubs. Chef buyers in Copenhagen and Brussels sourcing through specialized B2B marketplaces provide a direct go-to-market angle bypassing broadline distributor concentration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across high-pressure processing equipment installation as virtualization eliminates distributed thermal facility requirements. Long-term viability over the next decade favors acquiring chilled-food manufacturing specialists with established retailer relationships rather than artisanal operators dependent on specialty retail channel fragmentation. The signal to watch is supermarket banner consolidation pace, which will determine whether private-label producers or Mediterranean-recipe brand specialists capture margin pool reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Virtualizes thermal pasteurization infrastructure and extends distribution radii from centralized production. |
| Mono-Material Packaging Transition | ECHA recyclability mandates under EU Green Deal reshape tub material selection toward polypropylene formats. |
| Private-Label Capacity Expansion | Retailer-controlled supply chains reconfigure margin pools away from branded premiums in UK and German retail. |
| Traceable Tahini Sourcing | CSRD disclosure requirements for sesame seed provenance create competitive differentiation for compliant operators. |
| Food-Service Pouch Formats | Squeeze-tube configurations displace bulk tubs in contract catering and airline meal production volumes. |
Methodological Framework
The analysis maps flavor positioning tiers, packaging format economics, and channel distribution structures, each validated through procurement leads at supermarket banners, chilled-food manufacturing executives, and tahini import specialists. Primary interviews with category buyers at Tesco, Sainsbury's, and Albert Heijn combined with secondary validation from EFSA novel food ingredient filings, ECHA REACH registration databases, and EU customs trade records. Bottom-up volume modeling across production facility outputs triangulates against top-down retail audit data from Nielsen and Circana.
Assumptions held fixed include EFSA regulatory timelines for functional additive claims and EU Green Deal packaging mandate implementation schedules, while variables included Red Sea shipping disruption duration and supermarket private-label expansion rates. Segmentation dimensions modeled encompass flavor category, packaging format, end-user type, and distribution channel across the projection horizon. CAGRs derive from production capacity expansion announcements and retail shelf space allocation trends. Forecast inputs incorporate high-pressure processing equipment installation rates and chilled-logistics network density metrics.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by private-label manufacturers or rapid artisanal brand consolidation would shift outcomes. Tahini supply disruption severity and EFSA novel food pathway acceleration represent primary revision risks for the Europe hummus market. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Guacamole Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Poke Food Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Silver Food Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Foie Gras Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Cannabis Infused Drinks Market
Specialty Foods
White Fungus Market