
 Gluten Free Snacks Market | 2026-2036
Gluten Free Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Free Snacks Market Foresight
Rice flour is broadening its role as the dominant wheat substitute in extruded snack formulations, cutting raw material costs while preserving crunch and shelf stability. General Mills, Inc. leverages its cereal manufacturing infrastructure to produce certified gluten-free crackers at scale. The Hain Celestial Group, Inc. anchors its portfolio in organic ingredient sourcing that commands premium positioning in health food stores. Mondelez International Inc competes through its global distribution network, placing gluten-free variants in mainstream supermarket aisles alongside conventional products.
Gluten-free snacks comprise edible products formulated without wheat, barley, rye, or cross-contaminated oats, typically substituting alternative starches and achieving less than 20 parts per million gluten content under Codex Alimentarius standards. These products serve consumers with celiac disease, non-celiac gluten sensitivity, and voluntary wheat-avoidance diets across retail and foodservice channels. Chips and crackers dominate current revenue owing to established manufacturing lines and familiar consumption occasions, while quinoa-based and almond flour segments attract margin-rich positioning in specialty retail. Online retailers represent the fastest-growing distribution vector as direct-to-consumer subscription models bypass traditional slotting fee barriers.
The FDA enforces its gluten-free labeling rule through facility audits and product testing requirements that create entry barriers for uncertified imports. The European Food Safety Authority coordinates with national bodies such as Germany's BfR to harmonize threshold limits across member states, simplifying pan-European launches. Australia's Food Standards Code mandates explicit allergen declarations that shape packaging design and reformulation priorities. Stakeholders must monitor evolving definitions of "gluten-free" in emerging markets where regulatory divergence threatens harmonized supply chains.
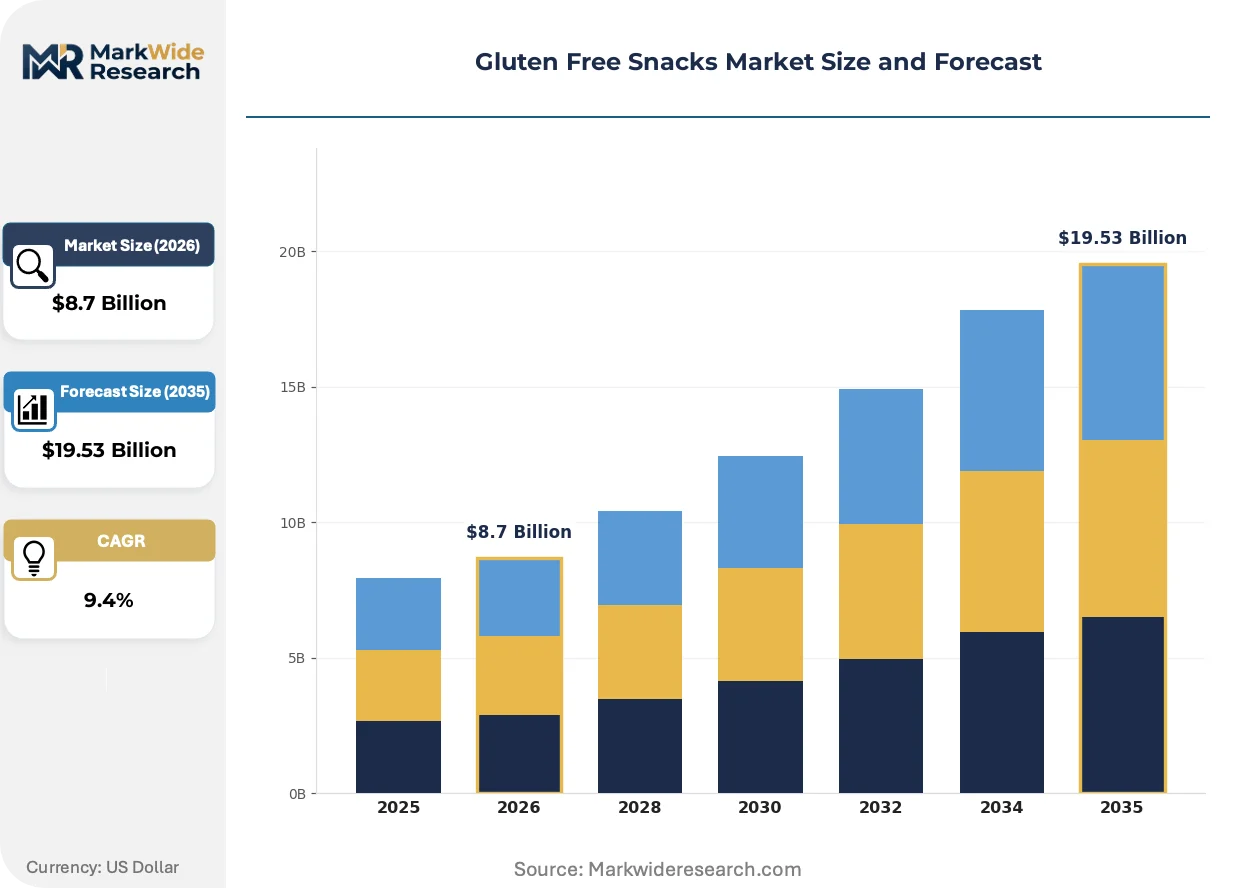
Market Dynamics
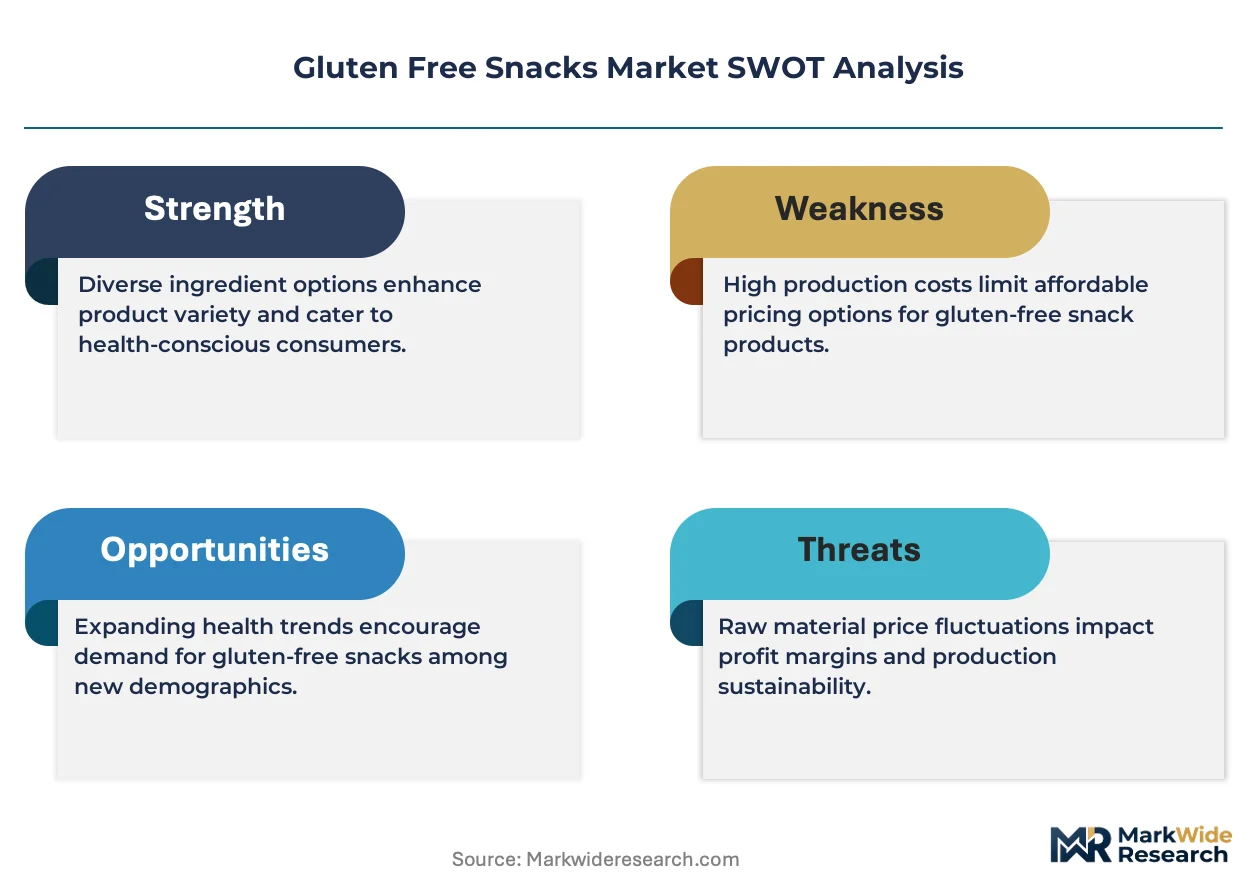
The FDA's gluten-free labeling rule and parallel standards from EFSA and Australia's Food Standards Code have erected compliance barriers that favor certified manufacturers with dedicated production lines over commodity snack producers attempting opportunistic entry.
Growth Catalysts
- Clean-label certification:Germany's BfR and Australia's Food Standards Code mandate explicit allergen declarations that reward manufacturers with segregated supply chains and third-party verification.
- Urban millennial demand:Health-conscious consumers in United States metropolitan clusters accelerate demand for quinoa-based and almond flour alternatives that command premium shelf positioning.
- Rice flour substitution:Extrusion technology adapted from cereal manufacturing cuts raw material costs while preserving the crunch texture and shelf stability that conventional wheat formulations deliver.
Market Restraints
- Input cost volatility:Almond flour and quinoa prices fluctuate with California drought cycles and Andean harvest variability, compressing margins on premium-positioned products.
- Supply concentration risk:Certified gluten-free oat sourcing concentrates in Scandinavian and Canadian growing regions, creating geographic single-points-of-failure for cross-contamination-sensitive formulations.
- Technical limitation:Alternative starches lack the elastic gluten network that enables conventional dough sheeting, constraining cracker geometry and limiting product format innovation.
Strategic Opportunities
- Direct-to-consumer subscription:Online retailers bypass traditional supermarket slotting fees that have historically blocked specialty snack entrants from mainstream aisle placement.
- Foodservice penetration:Airline and hospitality channels in Australia and Germany seek pre-packaged certified options to accommodate celiac passengers without kitchen cross-contamination protocols.
- Organic convergence:The EU Green Deal's farm-to-fork sustainability targets align with organic ingredient sourcing that commands dual-certification premiums in health food retail.
Industry Challenges
- Segregated production infrastructure:Dedicated gluten-free facilities require capital-intensive buildouts that commodity snack manufacturers resist without volume guarantees from retail buyers.
- Auditor capacity constraints:Third-party certification bodies face backlogs for facility validation under FDA and Codex Alimentarius protocols, delaying new product launches by 6-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Free Snacks Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Granola Bars, Crackers, Popcorn, Nut Mixes, Rice Cakes Ingredient Source: Rice Flour, Corn Flour, Almond Flour, Tapioca Starch, Quinoa, Buckwheat Distribution Channel: Specialty Stores, Online Retailers, Health Food Stores, Supermarkets, Pharmacies Consumer Age Group: Children, Adolescents, Adults, Seniors |
| Companies Covered | The Kraft Heinz Company, The Hain Celestial Group, Inc., General Mills, Inc., Kellogg Company, Conagra Brands, Inc., Dr. Schär AG/SPA, Mondelez International Inc, Freedom Foods Group Limited, Hero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Free Snacks Market Shifts & Advancements
Extrusion and alternative starch formulation technologies are compressing the cost gap between gluten-free and conventional snacks while regulatory harmonization across FDA, EFSA, and Australian frameworks simplifies multi-territory launches.
High-pressure extrusion systems adapted from breakfast cereal production are automating the continuous processing of rice flour and tapioca starch blends at throughputs that approach wheat-based benchmarks. Contract manufacturers in the United States Midwest retrofit idle cereal lines to serve emerging gluten-free brands lacking capital for greenfield facilities. This capital-light scaling model is automating market entry for regional players previously blocked by equipment barriers.
REACH-aligned contaminant thresholds and the EU's evolving digital product passport requirements are forcing reformulation of flavor systems and packaging adhesives used in European gluten-free cracker production. Manufacturers must now document supply chain provenance for rice flour sourced from Asian milling operations to satisfy EFSA audit protocols. German retailers have responded by demanding batch-level traceability data that exceeds current FDA requirements.
Health food store buyers now specify dual organic-gluten-free certification as a baseline qualification, displacing single-attribute positioning that dominated specialty retail five years ago. This specification compression forces reformulation of legacy products that relied on conventional rice flour without organic chain-of-custody documentation. The shift is most visible in United States coastal metropolitan markets where Whole Foods and Sprouts set procurement standards that regional distributors propagate inland.
Gluten Free Snacks Market Segmentation
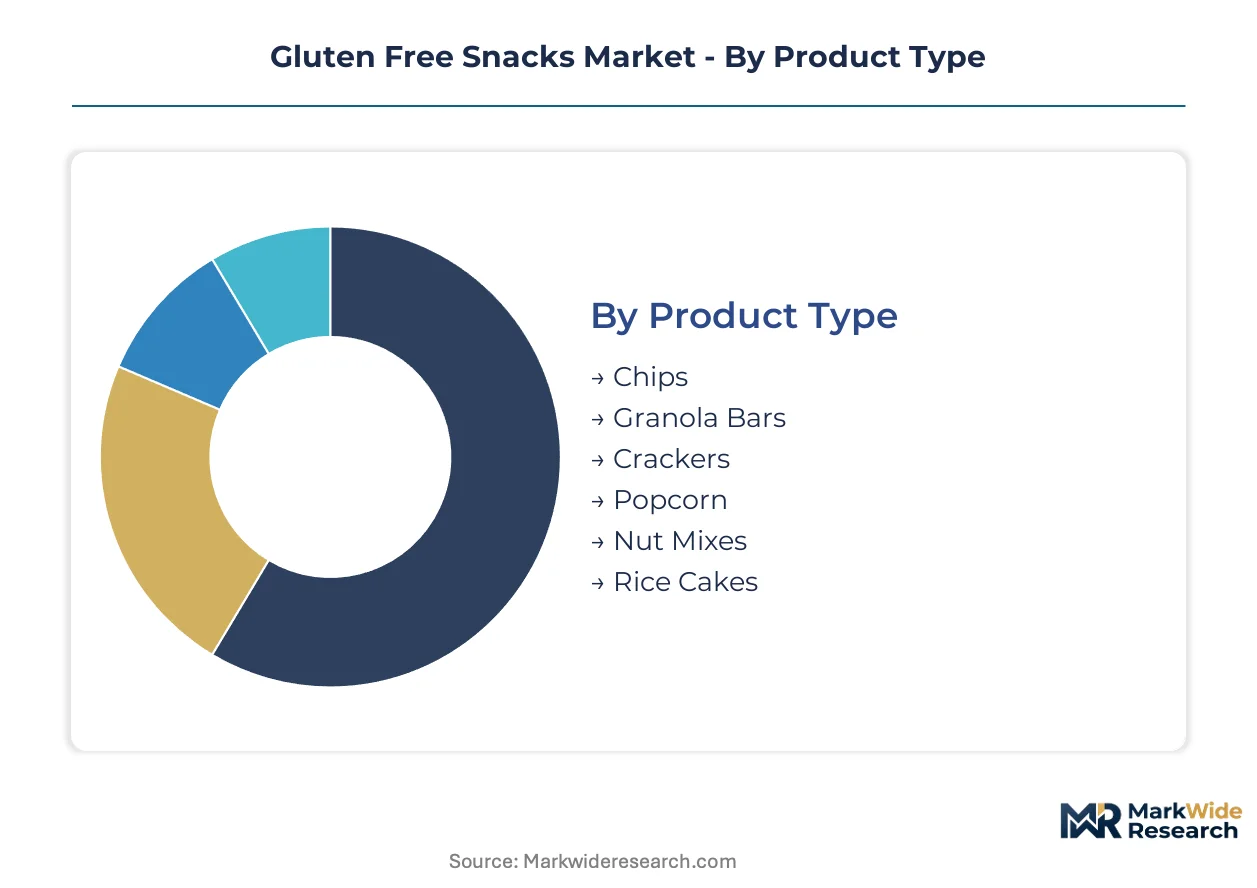
Segmentation in the gluten-free snacks market reveals how formulation choices, channel access, and demographic targeting create distinct competitive arenas. Manufacturers align R&D investment and certification strategies against specific segment economics rather than pursuing undifferentiated scale.
Product Type:
Upgrade cycles in gluten-free snacking follow texture innovation and format familiarity, with consumers replacing conventional wheat-based equivalents as manufacturing quality improves.
- Chips:Extruded and kettle-cooked variants using rice flour or tapioca starch achieve the crunch benchmarks that conventional potato chips established. Demand clusters in United States metropolitan markets where convenience stores and vending machine operators now stock certified alternatives alongside legacy brands.
- Crackers:Sheeted and rotary-molded formats rely on xanthan gum and modified starches to simulate gluten's binding properties. German health food retailers specify these for their deli accompaniment sections, driving reformulation toward neutral flavor profiles that pair with cheeses.
- Granola Bars:Oat-free formulations using puffed rice and seed binders serve school lunchbox requirements in Australia where allergen policies have tightened.
- Popcorn:Naturally gluten-free positioning requires processing line segregation to maintain Codex Alimentarius certification for flavored varieties.
- Nut Mixes:Seasoning adhesion challenges drive oil-based coating innovations for clean-label positioning in United States coastal markets.
- Rice Cakes:Mature segment facing displacement by more textured alternatives in European supermarkets.
Volume placements concentrate in chips; the faster expansion belongs to crackers.
Ingredient Source:
Cost tiering in raw materials separates premium-positioned products from mass-market alternatives, with flour selection directly determining retail shelf placement and margin structure.
- Rice Flour:White and brown rice milling byproducts provide the neutral flavor base and extrusion stability that dominates commodity gluten-free production. United States contract manufacturers in the Midwest leverage idle cereal processing infrastructure to achieve wheat-competitive unit economics.
- Almond Flour:Blanched and natural varieties deliver protein content and moisture retention that command dual organic-gluten-free certification premiums. California drought cycles and water allocation disputes create input cost volatility that compresses margins on premium-positioned bakery-style crackers.
- Corn Flour:Masa and fine grind variants anchor Latin American-inspired snack formats with established supply chains.
- Tapioca Starch:Thai and Vietnamese cassava sourcing provides the elastic mouthfeel that extruded puffs require.
- Quinoa:Andean harvest variability and export quota restrictions limit scalable adoption despite nutritional positioning.
- Buckwheat:Eastern European and Canadian sourcing supports niche Eastern European market penetration.
Mainstream volume flows through rice flour; the steepest expansion trajectory belongs to almond flour.
Distribution Channel:
Customer type fragmentation across channels forces packaging format and certification documentation adaptations that add complexity to unified brand strategies.
- Supermarkets:Mainstream aisle placement requires slotting fee commitments and promotional calendar participation that only scaled manufacturers sustain. United States national chains now dedicate permanent shelf sets to certified gluten-free sections, displacing the specialty store intermediaries that previously controlled access.
- Online Retailers:Direct-to-consumer subscription models bypass traditional retail gatekeepers and enable batch-level traceability documentation that German and Australian regulators increasingly require. Amazon and specialized health platforms aggregate demand for regional brands lacking national distribution infrastructure.
- Specialty Stores:Celiac-focused boutiques in Australia and Germany provide education-intensive shopping environments that justify premium pricing.
- Health Food Stores:Whole Foods and Sprouts procurement standards in United States coastal markets propagate inland through distributor consolidation.
- Pharmacies:CVS and Walgreens shelf space treats gluten-free snacks as adjunct to digestive health categories rather than conventional food.
Transaction value concentrates in supermarkets; the channel climbing fastest is online retailers.
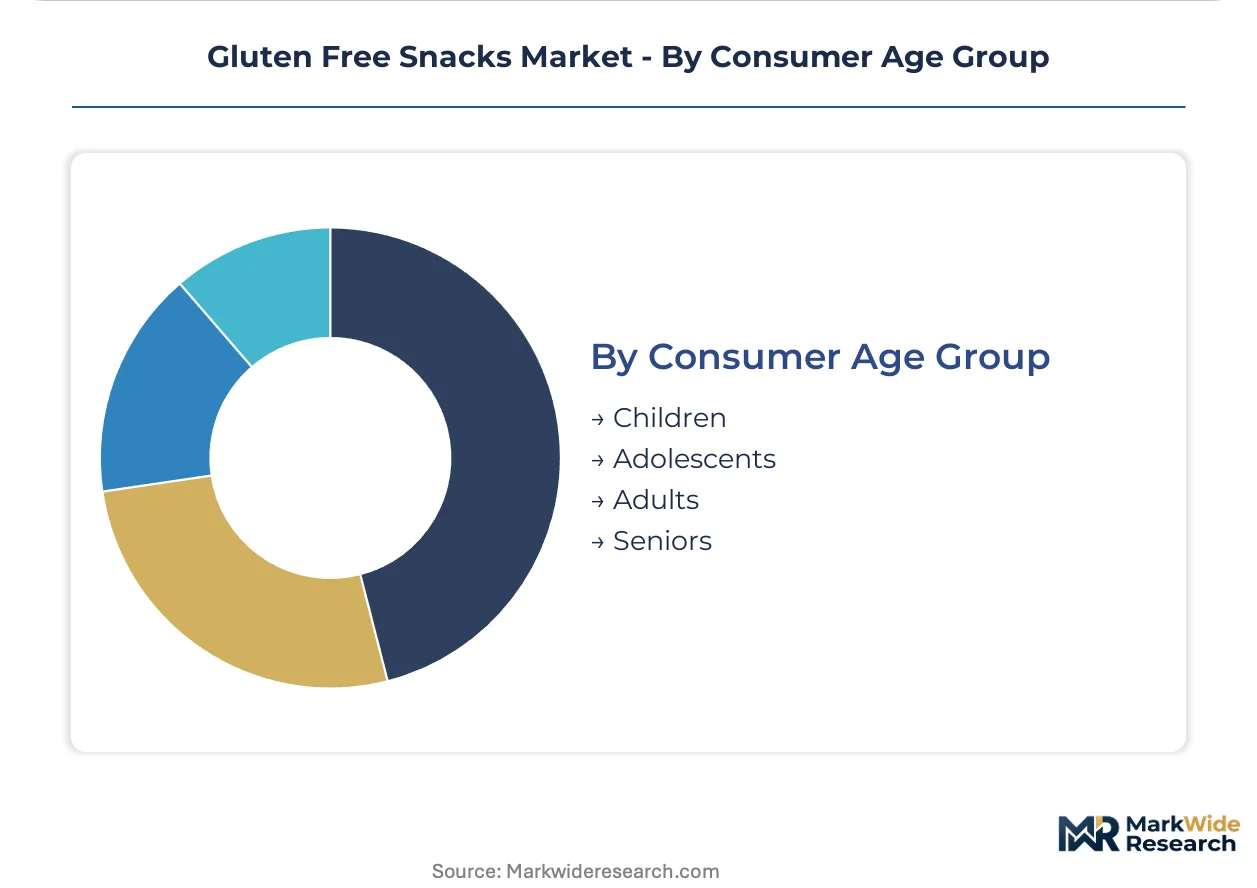
Consumer Age Group:
Maturity differentiation across life stages shapes portion sizing, nutritional fortification, and marketing channel selection with limited overlap in execution.
- Adults:Millennial and Gen-Z urban professionals in United States and German metropolitan clusters drive clean-label demand and subscription adoption. This segment accepts price premiums for organic certification and transparent supply chain documentation.
- Children:School-safe packaging and allergen-free claims dominate procurement decisions by Australian and United States parents navigating district-level ban policies.
- Adolescents:Social media-influenced trial behavior favors novel flavor launches and limited-edition collaborations.
- Seniors:Digestive comfort positioning and softer texture formats address dentition and absorption concerns in aging populations.
Purchase frequency concentrates in adults; the demographic gaining share fastest is children.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates and Singapore accelerate gluten-free snack distribution hub development, concentrating logistics investment and regulatory sandbox testing for halal-certified variants.
United States
Millennial and Gen Z consumers in coastal metropolitan clusters drive clean-label subscription adoption. The FDA enforces gluten-free labeling through facility audits and testing protocols that favor dedicated production lines. Chicago-area contract manufacturers retrofit idle cereal extrusion equipment to serve emerging brands lacking capital for greenfield facilities.
Germany
Health food retailers in Berlin and Munich specify dual organic-gluten-free certification as baseline procurement standards. Germany's BfR coordinates with EFSA to harmonize allergen threshold limits across EU member states. Bavarian milling operations supply rice flour to cracker manufacturers serving pan-European supermarket chains.
Australia
School lunchbox allergen policies tighten procurement requirements for oat-free granola bar formulations. Food Standards Code mandates explicit gluten declarations that shape packaging design priorities. Sydney and Melbourne specialty retailers provide education-intensive shopping environments justifying premium positioning for certified imports.
United Kingdom
Post-Brexit regulatory divergence creates compliance complexity for manufacturers serving both UK and EU markets. The Food Standards Agency maintains Codex Alimentarius alignment while negotiating mutual recognition agreements. London-based direct-to-consumer brands leverage subscription models to bypass traditional supermarket slotting fees.
Gluten Free Snacks Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with scale-driven multinationals commanding mainstream supermarket placement while regional players capture health food channel premiums. Market structure tilts toward consolidated leadership in extruded snack categories and fragmented competition in specialty cracker formats. Three archetypes dominate: legacy cereal manufacturers repurposing infrastructure, organic-certified specialists anchoring premium positioning, and contract manufacturers enabling capital-light market entry. Capacity expansion and strategic certification investments constitute the primary competitive moves as players secure dedicated gluten-free production lines.
Among legacy packaged food operators, General Mills, Inc., The Hain Celestial Group, Inc., and Mondelez International Inc occupy positions spanning mass-market and premium-tier vectors. General Mills exemplifies infrastructure repurposing through cereal manufacturing adaptation. The Hain Celestial Group represents organic-certified specialist positioning in health food retail channels. Mondelez International anchors global distribution scale for mainstream aisle penetration alongside conventional product portfolios.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| The Hain Celestial Group, Inc. |
| General Mills, Inc. |
| Kellogg Company |
| Conagra Brands, Inc. |
| Dr. Schär AG/SPA |
| Mondelez International Inc |
| Freedom Foods Group Limited |
| Hero Group |
| Others |
Supply & Pricing Matrix
German health food retailers' dual organic-gluten-free certification mandates force rice flour suppliers to document chain-of-custody provenance, compressing margins on non-compliant inventory and rewarding segregated supply chain investments with shelf access premiums.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Australian airlines and hospitality chains demand certified gluten-free snacks with batch-level traceability documentation on compressed delivery schedules. Three-tier pricing structure across premium, standard, and economy levels separates dual-certified organic products from conventional rice flour formulations and commodity spot purchases. Pricing pressure stems from California almond flour cost volatility driven by drought-cycle water allocation disputes. School lunchbox procurement teams in Australia exhibit highest price sensitivity, while United States coastal millennial subscribers accept premiums for transparent supply chain documentation.
Supply Chain Analysis
Dual-sourcing requirements from German retailers and Australian foodservice buyers mandate multi-supplier qualification for rice flour, preventing single-origin dependence on Thai or Vietnamese milling operations. Supply concentrates in the United States Midwest for contract manufacturing, California for almond flour, and Scandinavia for certified gluten-free oats. Raw material dependencies center on rice flour, tapioca starch, and quinoa with Andean harvest variability. Single-source vulnerability threatens oat-based formulations given geographic concentration in Canadian and Scandinavian growing regions. Distribution runs through direct-to-consumer subscription channels bypassing traditional supermarket slotting fee barriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure extrusion technology adapted from cereal manufacturing is displacing legacy batch processing, enabling continuous production at throughputs that approach wheat-based benchmarks while cutting unit costs.
For Market Incumbents: Deploy dedicated gluten-free facility certification as the primary defensive lever against commodity snack manufacturers attempting opportunistic entry. Retrofit idle cereal extrusion infrastructure in the United States Midwest to serve emerging brands lacking capital for greenfield buildouts. Secure auditor relationships early to avoid third-party certification backlogs that delay launches by 6-18 months. For New Entrants and Emerging Players: Direct-to-consumer subscription routes bypass supermarket slotting fees that have historically blocked specialty snack entrants from mainstream aisle placement. Target airline and hospitality channels in Australia and Germany seeking pre-packaged certified options without kitchen cross-contamination protocols. Lead with batch-level traceability documentation that exceeds current FDA requirements to capture German retailer procurement specifications. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with retrofit cereal extrusion capacity and established auditor relationships. Mid-term viability hinges on organic-gluten-free dual certification capabilities as baseline health food store requirements displace single-attribute positioning. Watch EFSA digital product passport implementation timelines as the inflection signal for European supply chain provenance investments.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Organic-gluten-free certification secures placement in Whole Foods and Sprouts procurement pipelines. |
| Direct-to-Consumer Launch | Subscription models bypass slotting fees and enable batch-level traceability documentation for German regulators. |
| Retrofit Manufacturing Scale-Up | Idle cereal extrusion lines in the United States Midwest achieve wheat-competitive unit economics for emerging brands. |
| Foodservice Channel Expansion | Airline and hospitality penetration in Australia accommodates celiac passengers without cross-contamination protocols. |
| Sustainability Repositioning | EU Green Deal farm-to-fork alignment commands dual-certification premiums in European health food retail. |
Research Methodology
Document review covered FDA facility audit protocols, EFSA allergen threshold harmonization frameworks, and Australia's Food Standards Code labeling requirements, complemented by interviews with contract manufacturing executives, health food store category buyers, cereal extrusion equipment suppliers, and third-party certification auditors. Secondary validation drew from Codex Alimentarius standards documentation, United States customs import data for alternative starches, and EU Green Deal farm-to-fork policy filings. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Market size outputs across the projection horizon reflect modeled assumptions for product type segmentation by chips, crackers, and granola bars; ingredient source tiering across rice flour, almond flour, and quinoa; and distribution channel splits between supermarkets and online retailers. CAGRs were derived from trend extrapolation of urban millennial and Gen Z adoption curves, regulatory harmonization timelines, and extrusion technology cost compression trajectories. Forecast inputs incorporated California drought cycle impact on almond flour pricing and Andean harvest variability for quinoa supply.
Inputs from FDA facility audit records and EFSA digital product passport pilot programs were available through the study window; gaps in real-time third-party certification auditor capacity data introduce uncertainty bands around new entrant launch timelines. Deviation in EU digital product passport implementation schedules or FDA enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Sugar Fruit Snacks Market
Snacks
Kids Snacks Market
Snacks
Poland Snack Bar Market
Snacks
Middle East and Africa Snack Food Market
Snacks
North America Savory Snacks Market
Snacks
Fat Free Meals and Snacks Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Baked Savoury Snacks Market
Snacks
Better for You Snacks Market
Snacks
Global Rice Snacks Market
Snacks
Nutritional Bar Market
Snacks
United Arab Emirates Energy Bar Market
Snacks
Low Calorie Biscuits Market
Snacks
UK Snack Market
Snacks
Marshmallow Market