
 Saudi Arabia Snacks Industry Market | 2026-2036
Saudi Arabia Snacks Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Snacks Industry Market Insights
Expatriate food technician availability is collapsing across Saudi Arabia's snack manufacturing base, forcing producers to accelerate local training academies and automation retrofits. PepsiCo leverages its Riyadh-based bottling and snack co-manufacturing infrastructure to sustain route-to-market density across the Kingdom's hypermarket channels. Mondelez International anchors its Gulf operations through Jeddah distribution hubs that compete directly with regional private-label importers. Almarai dominates dairy-derivative snack categories by controlling chilled supply chain assets that extend product freshness windows in ambient desert climates.
The Saudi Arabia Snacks Industry comprises processed ready-to-eat food products manufactured through baking, frying, extrusion, or air-popping of cereal grains, tubers, oilseeds, and dairy inputs, with shelf stability typically achieved through moisture control below 5% and modified-atmosphere packaging. These products serve immediate consumption occasions across retail, food service, and institutional channels where convenience and portion control determine purchasing decisions. Chips and extruded snacks lead volume throughput due to established production lines and lower per-unit input costs, while nuts command premium positioning through health-association branding and gift-packaging formats. Flexible pouches capture the fastest-growing packaging share as brands prioritize portion-size experimentation and reduced material costs against rigid alternatives.
SFDA mandates govern ingredient disclosure, allergen labeling, and nutritional claim verification for all packaged snacks distributed within the Kingdom, while SASO technical regulations enforce packaging material safety and shelf-life validation protocols. These frameworks shape demand by requiring reformulation investments from importers and domestic producers alike, effectively raising compliance capital thresholds for market entry. Stakeholders must monitor evolving front-of-pack labeling proposals and local content incentives under Vision 2030 industrial policy to anticipate margin compression or qualification advantages.
Market Dynamics
SFDA labeling mandates and shelf-life validation protocols are compressing formulation timelines across Saudi Arabia's snack manufacturing base, forcing producers to rebuild R&D pipelines around compliance-first design rather than taste-optimized iteration.
Growth Catalysts
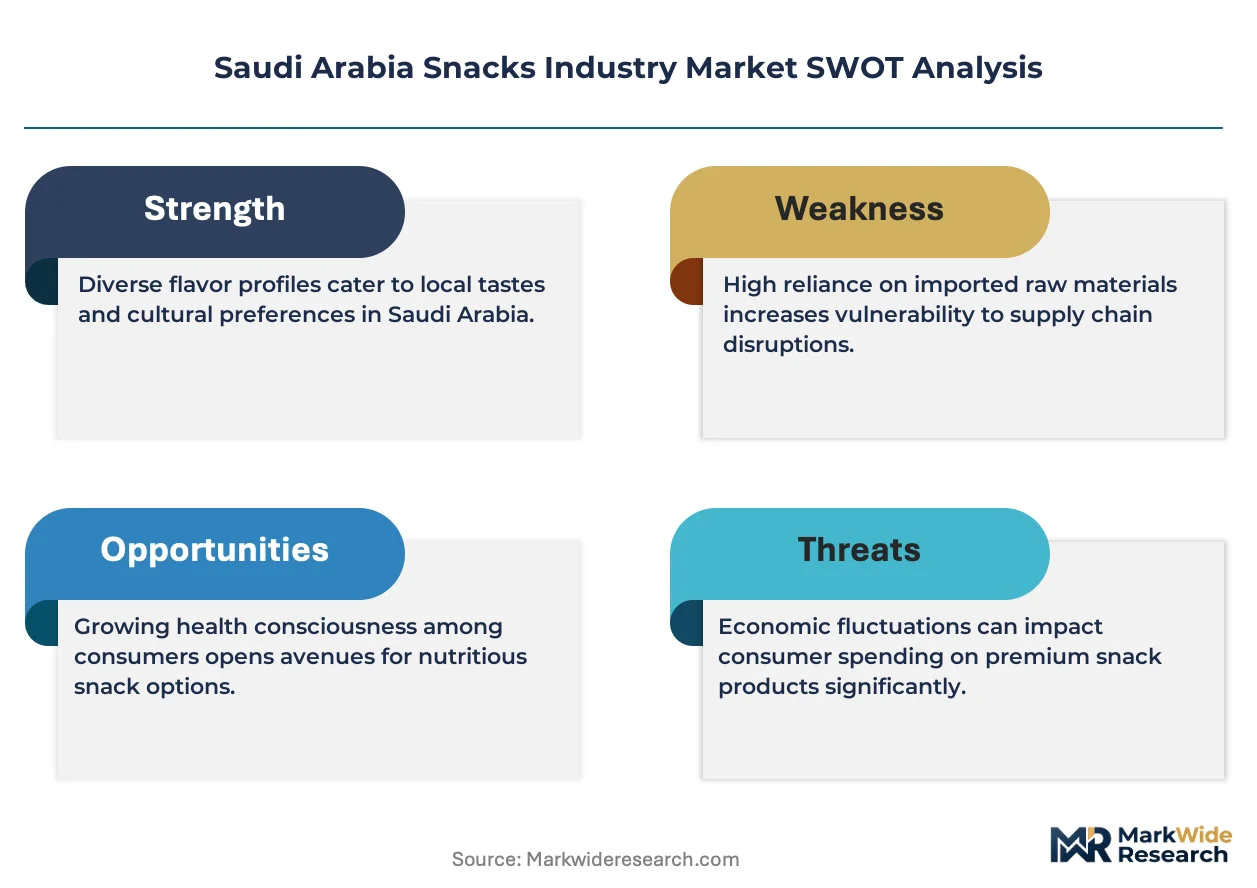
- Vision 2030 Localization Incentives:Industrial policy frameworks reward domestic production of packaged foods, drawing capital into greenfield extrusion and baking facilities across Riyadh Industrial City and Jeddah Third Industrial Zone.
- Hypermarket Channel Expansion:Modern retail formats in Riyadh and Jeddah are capturing snack purchasing occasions previously served by traditional grocery, expanding addressable volume for branded and private-label portfolios alike.
- Extrusion Technology Maturation:Continuous extrusion lines with real-time moisture control are reducing per-unit energy costs and enabling rapid SKU rotation for portion-size experimentation.
Market Restraints
- Palm Oil Price Volatility:Input cost swings for the primary frying medium compress margin predictability for chip and extruded snack categories, forcing hedging costs onto mid-scale producers.
- Chilled Supply Chain Concentration:Dairy-derivative snacks depend on a limited pool of cold-chain logistics providers operating between Riyadh, Jeddah, and Dammam, creating single-point vulnerability for freshness-dependent categories.
- SFDA Allergen Disclosure Complexity:Cross-contamination documentation requirements for nut-adjacent production lines extend product launch timelines and raise qualification barriers for imported alternatives.
Strategic Opportunities
- Eastern Province Underpenetration:Dammam and Khobar modern trade density lags Riyadh and Jeddah by a significant margin, leaving white space for distribution infrastructure investment and localized brand building.
- Front-of-Pack Labeling Tailwinds:Anticipated SFDA traffic-light nutritional scoring systems will advantage reformulated portfolios with reduced sodium and sugar profiles, rewarding early compliance investment.
- E-Commerce Fulfillment Convergence:Quick-commerce platforms and dark-store networks are collapsing delivery windows for impulse snack purchases, opening direct-to-consumer channels previously dominated by retail intermediaries.
Industry Challenges
- Food Technician Scarcity:Expatriate formulation specialists are exiting the Kingdom faster than local training academies can replace them, creating bottlenecks in product development and process optimization functions.
- Automation Retrofit Capital Burden:Legacy frying and packaging lines require substantial reinvestment to meet SFDA traceability and hygiene standards, straining balance sheets of family-owned producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Snacks Industry Market |
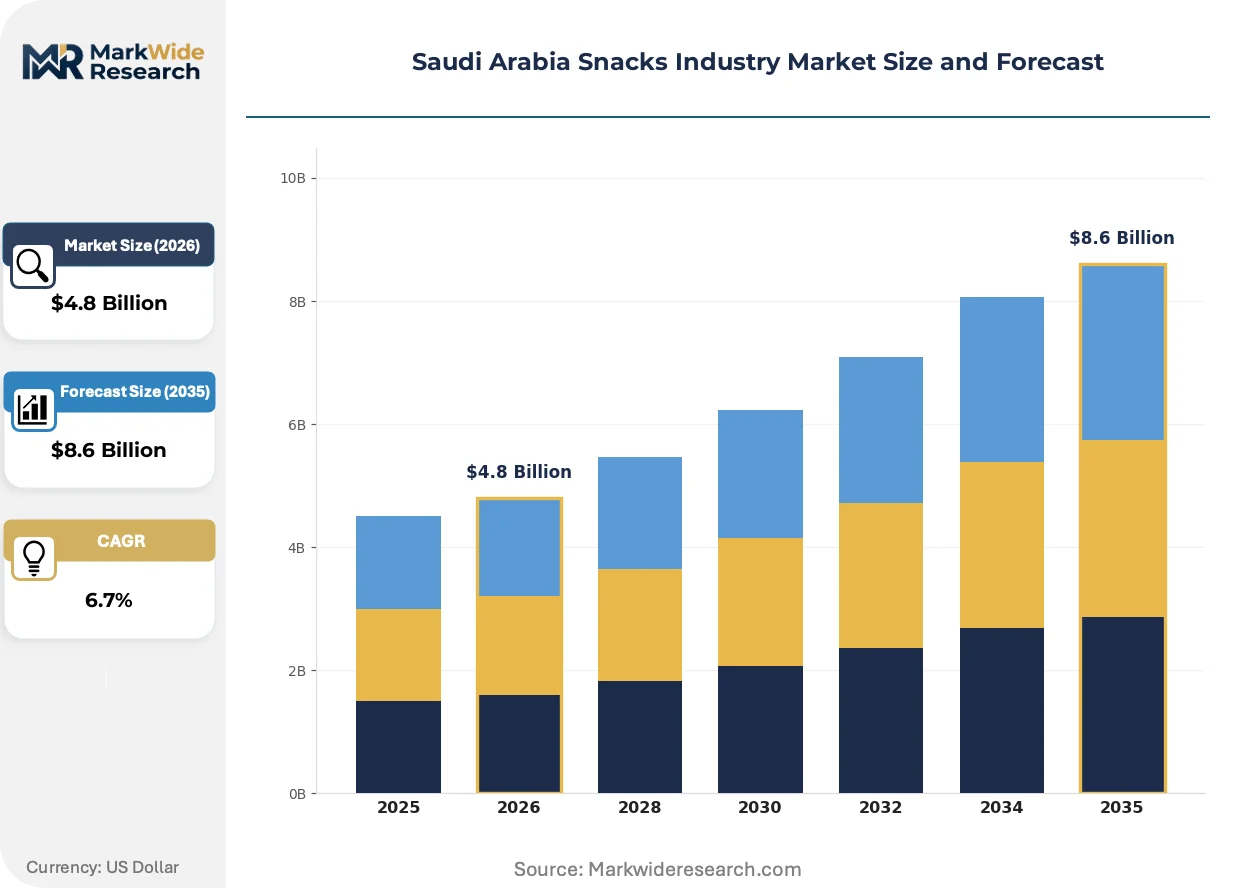
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Nuts, Popcorn, Extruded Snacks Packaging Type: Flexible Packaging, Rigid Packaging, Pouches, Cans Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Flavor Profile: Spicy, Sweet, Savory, Cheese |
| Companies Covered | PepsiCo Inc, Mondelez International, Kellanova, General Mills Inc, Nestle SA, Conagra Brands Inc, Hershey's, Almarai, SADAFCO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Snacks Industry Market Trends and Innovations
Packaging technology and regulatory disclosure frameworks are converging to reshape how Saudi snack producers design for shelf stability, portion control, and consumer transparency simultaneously.
Modified-atmosphere packaging systems with embedded oxygen scavengers are extending shelf life without chemical preservatives. Urban retail chains in Riyadh and Jeddah are specifying these specifications for private-label procurement. The technology is miniaturizing barrier-layer thickness while maintaining moisture control below critical thresholds, compressing material costs against rigid canister alternatives.
SFDA front-of-pack labeling proposals are advancing through regulatory consultation phases. These frameworks will mandate color-coded nutritional density indicators on all packaged snacks, forcing reformulation of legacy portfolios. Importers and domestic producers are responding by accelerating sodium reduction programs and alternative sweetener trials to preempt qualification disadvantages.
Young urban professionals are fragmenting consumption occasions across micro-portion formats and protein-fortified alternatives. Hypermarket bulk purchasing is losing share to convenience-store single-serve and quick-commerce immediate-delivery channels. This behavioral rotation is most visible in Riyadh's northern districts and Jeddah's Corniche-adjacent neighborhoods where time-compressed purchasing patterns dominate.
Saudi Arabia Snacks Industry Market Segmentation
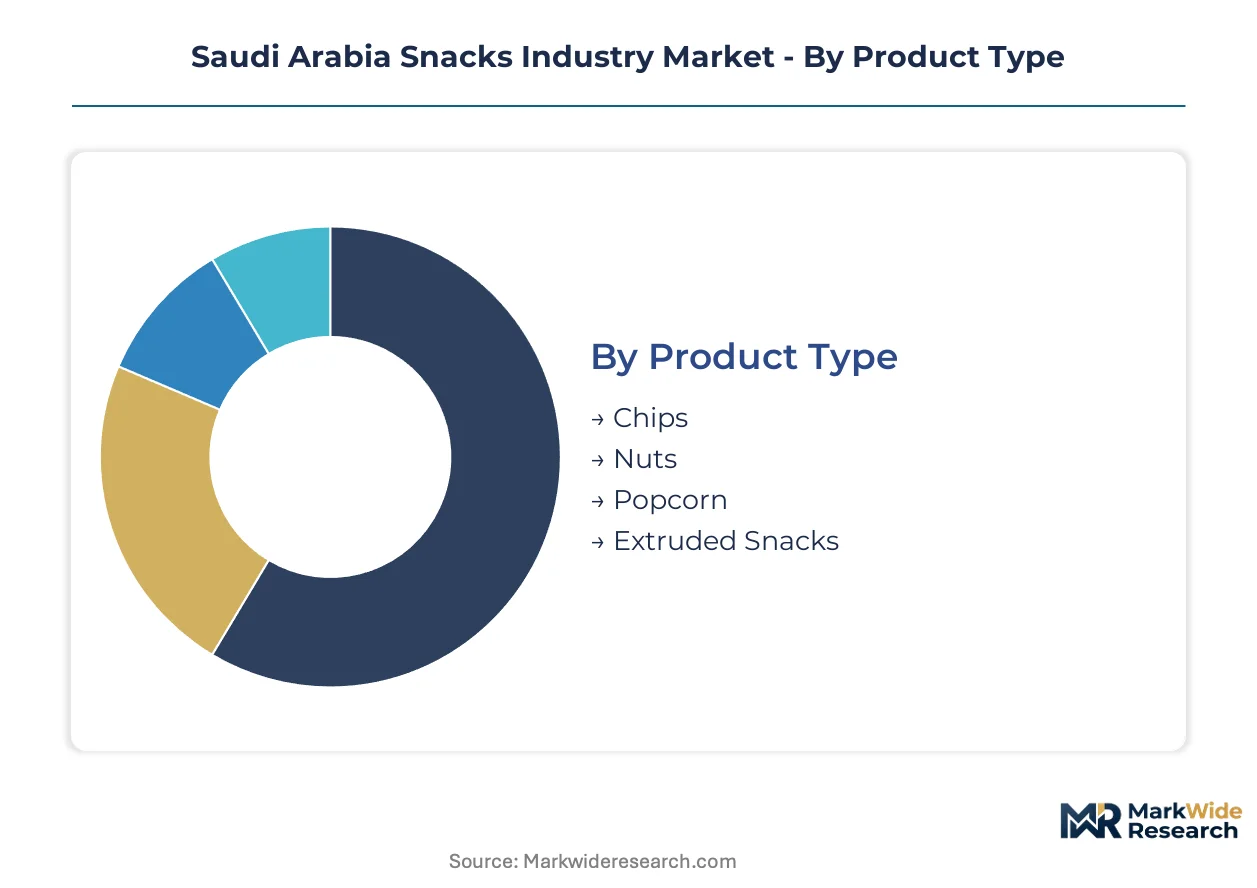
Segmentation in the Saudi Arabia snacks market reveals how regulatory pressure from SFDA and SASO differentially impacts product viability across categories. Manufacturers must align R&D investments with the compliance burden specific to each segment's formulation complexity and shelf-life requirements.
Product Type:
SFDA allergen disclosure rules and shelf-life validation protocols create divergent compliance costs across manufacturing technologies, separating capital-intensive categories from artisanal alternatives.
- Chips:Thin-sliced tuber or grain substrates fried in palm oil dominate production volume through continuous line efficiency. Riyadh hypermarkets absorb the bulk of branded chip throughput as young professionals prioritize portion-controlled single-serve formats for workplace consumption.
- Extruded Snacks:High-pressure thermal processing of cereal dough creates hollow or puffed structures with moisture content below critical thresholds. Jeddah's modern trade channels are expanding shelf space for extruded alternatives as local producers exploit Vision 2030 localization incentives to displace imported equivalents.
- Nuts:Roasted or raw tree nuts and legumes carry elevated SFDA cross-contamination documentation requirements.
- Popcorn:Air-popped or oil-popped maize kernels serve cinema and home-entertainment occasions with minimal processing overhead.
Chips handle the majority of throughput; extruded snacks are expanding most quickly on share.
Packaging Type:
Cost tier differentiation separates premium barrier technologies from commodity formats, with material selection directly tied to shelf-life extension investments mandated by desert climate logistics.
- Flexible Packaging:Multi-layer polymer films with metallized or co-extruded barrier layers enable modified-atmosphere preservation without rigid material weight. Northern Riyadh retail clusters are specifying these specifications for private-label procurement as quick-commerce platforms demand lighter fulfillment loads.
- Pouches:Stand-up or flat pouches with resealable zipper closures support portion-control experimentation and reduced per-unit material costs. Jeddah Corniche-adjacent convenience stores are rotating pouch SKUs fastest to capture impulse purchasing from time-compressed urban professionals.
- Rigid Packaging:Thermoformed trays or composite canisters offer structural protection for fragile substrates at higher material cost.
- Cans:Metal or composite cylinders provide maximum barrier properties for premium nut assortments and gift formats.
Flexible packaging commands the volume base; pouches are climbing the fastest on adoption curves.
Distribution Channel:
Customer type fragmentation across purchasing occasions is collapsing traditional channel boundaries as quick-commerce platforms capture impulse transactions previously routed through physical retail.
- Supermarkets:Hypermarket and supermarket formats in Riyadh and Jeddah aggregate bulk purchasing occasions with extended aisle exposure for brand building. These channels concentrate modern trade penetration where Vision 2030 retail infrastructure investments have deepest reach.
- Online Retail:Dark-store networks and quick-commerce platforms are compressing delivery windows to under thirty minutes for immediate consumption needs. Eastern Province urban centers are seeing fastest platform expansion as infrastructure investment lags the Riyadh-Jeddah axis.
- Convenience Stores:Small-format urban outlets capture single-serve and emergency replenishment occasions with limited SKU depth.
- Food Service:Institutional and hospitality channels procure bulk formats for preparation or direct service with customized specification requirements.
Supermarkets retain the dominant throughput position; online retail is gaining share fastest.
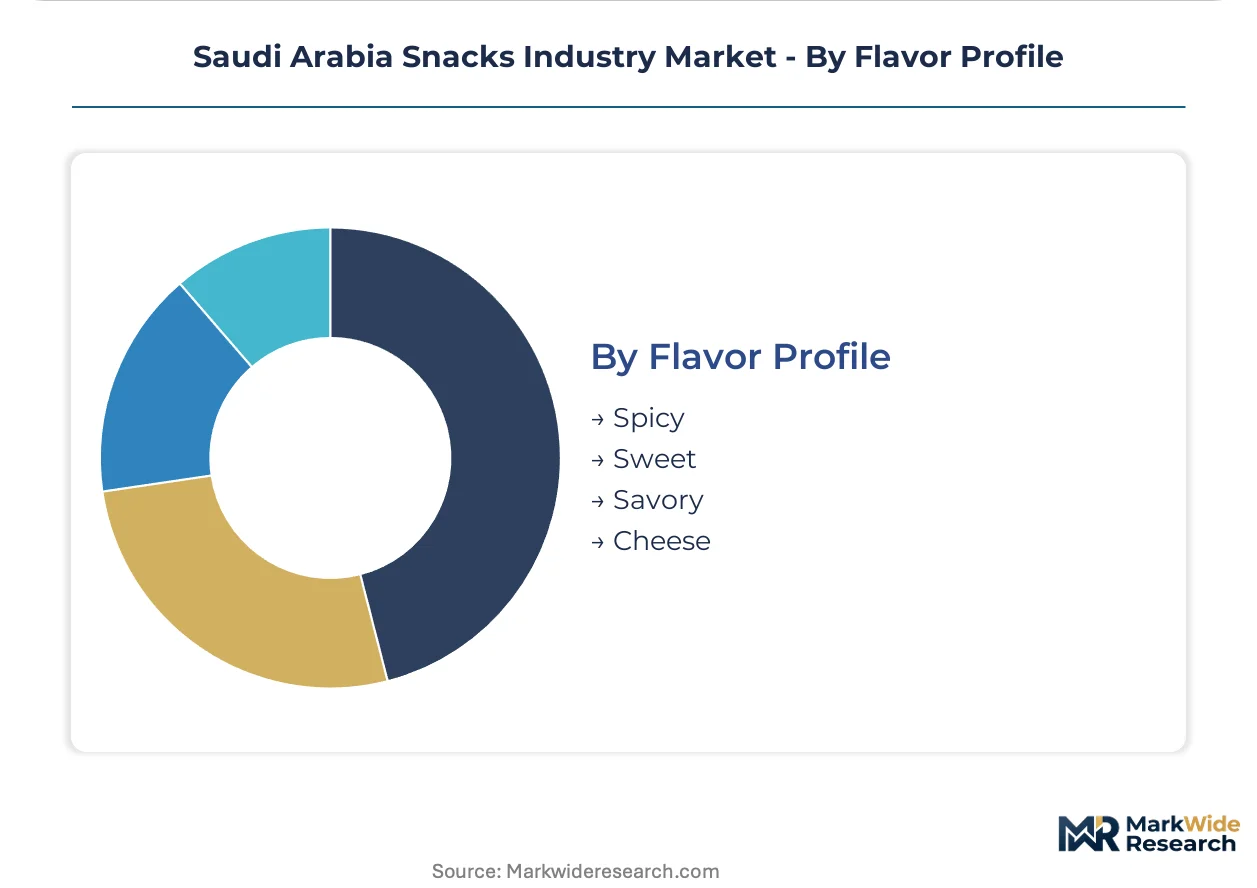
Flavor Profile:
Geography of demand within the Kingdom shapes flavor preference concentration, with urban coastal versus inland demographics driving differentiated formulation priorities.
- Savory:Salt-forward profiles with umami enhancement dominate mature categories through established consumer habit formation. Riyadh's professional districts sustain highest per-capita savory consumption as workplace snacking occasions concentrate in corporate environments.
- Spicy:Capsicum-derived heat levels calibrated to regional preference thresholds are capturing experimentation-oriented segments. Jeddah's expatriate-influenced neighborhoods are driving spicy format trial rates above national averages as cross-cultural flavor adoption accelerates.
- Cheese:Dairy-derived coating or seasoning systems require chilled supply chain integrity for ingredient freshness.
- Sweet:Sugar or alternative sweetener coatings serve dessert-occasion substitution and younger demographic preferences.
Savory formats carry the volume burden; spicy profiles are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA labeling mandates and shelf-life validation protocols are compressing formulation timelines across Saudi Arabia's snack manufacturing base, forcing producers to rebuild R&D pipelines around compliance-first design rather than taste-optimized iteration.
Riyadh
Young urban professionals are driving per-capita consumption upward through workplace snacking occasions and impulse purchases at modern trade formats. Vision 2030 localization incentives are drawing capital into greenfield extrusion and baking facilities across Riyadh Industrial City. Northern Riyadh retail clusters are specifying flexible packaging specifications for private-label procurement as quick-commerce platforms demand lighter fulfillment loads.
Jeddah
Modern trade channels are expanding shelf space for extruded alternatives as local producers exploit localization incentives to displace imported equivalents. Mondelez International anchors its Gulf operations through Jeddah distribution hubs that compete directly with regional private-label importers. Jeddah Corniche-adjacent convenience stores are rotating pouch SKUs fastest to capture impulse purchasing from time-compressed urban professionals.
Eastern Province
Dammam and Khobar modern trade density lags Riyadh and Jeddah by a significant margin, leaving white space for distribution infrastructure investment and localized brand building. Dark-store networks and quick-commerce platforms are compressing delivery windows to under thirty minutes as infrastructure investment lags the Riyadh-Jeddah axis. Dairy-derivative snacks depend on a limited pool of cold-chain logistics providers operating between Dammam and the central corridor.
Western Region
Expatriate-influenced neighborhoods are driving spicy format trial rates above national averages as cross-cultural flavor adoption accelerates. Hypermarket bulk purchasing is losing share to convenience-store single-serve and quick-commerce immediate-delivery channels. Coastal logistics corridors are enabling faster import clearance for nut-adjacent categories with elevated SFDA cross-contamination documentation requirements.
Saudi Arabia Snacks Industry Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Saudi Arabia's snack industry. Multinational conglomerates with co-manufacturing infrastructure dominate branded volume throughput, while regional dairy majors leverage captive chilled supply chains to defend freshness-dependent categories. Family-owned producers and private-label importers occupy distinct strategic tiers based on compliance capital thresholds and route-to-market density. Competitive moves concentrate on automation retrofits to meet SFDA traceability standards and geographic expansion into underpenetrated Eastern Province corridors.
Within the multinational branded tier, PepsiCo Inc and Mondelez International exemplify archetypes that sustain route-to-market density across hypermarket channels through Riyadh-based bottling and snack co-manufacturing infrastructure. Almarai occupies a position representing regional dairy-derivative specialists that control chilled supply chain assets extending product freshness windows in ambient desert climates. These three anchors illustrate how compliance capital and logistics integration separate scalable positions from fragmented alternatives.
| Leading Market Players |
|---|
| PepsiCo Inc |
| Mondelez International |
| Kellanova |
| General Mills Inc |
| Nestle SA |
| Conagra Brands Inc |
| Hershey's |
| Almarai |
| SADAFCO |
| Others |
Pricing and Supply Chain Analysis
SFDA allergen disclosure mandates and shelf-life validation protocols gate both supplier qualification and price tier differentiation in Saudi Arabia's snack industry. Compliance capital thresholds separate premium barrier-technology suppliers from commodity packaging alternatives, while reformulation costs for front-of-pack labeling readiness feed directly into landed cost structures across import and domestic production channels.
Pricing Analysis
Riyadh-Jeddah price spreads for identical SKUs reflect chilled supply chain premiums and modern trade slotting fee differentials. Three-tier pricing structure across premium, standard, and economy levels stratifies by packaging barrier technology and brand heritage, with private-label alternatives compressing mid-tier margins. Cost compression in economy extruded snacks is intensifying because palm oil hedging costs transfer to mid-scale producers lacking vertical integration. Hypermarket bulk buyers exhibit lowest price sensitivity; convenience-store operators and quick-commerce platforms face highest margin pressure from delivery cost absorption.
Supply Chain Analysis
Strategic stockpiling of palm oil and modified-atmosphere packaging films dominates inventory strategy over just-in-time approaches given input price volatility and desert climate logistics. Manufacturing equipment and barrier-layer films draw from China, Germany, and South Korea; palm oil feeds from Malaysia and Indonesia. Single-source vulnerability concentrates in chilled logistics providers operating the Riyadh-Jeddah-Dammam corridor. Distribution runs through hypermarket consolidation centers with secondary routing to dark-store networks and convenience wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as young urban professionals fragment consumption occasions across micro-portion formats and protein-fortified alternatives, creating niche entry points between multinational scale and artisanal positioning.
For Market Incumbents: Consolidate route-to-market density through automation retrofits that meet SFDA traceability standards, locking in hypermarket shelf space against private-label displacement. Acquire chilled logistics capacity to defend dairy-derivative freshness windows against regional dairy majors expanding snack adjacencies. Prioritize sodium reduction R&D to preempt front-of-pack labeling qualification disadvantages.
For New Entrants and Emerging Players: Anchor in Eastern Province distribution infrastructure gaps, where Dammam and Khobar modern trade density lags the Riyadh-Jeddah axis by significant margins. Target spicy flavor profiles calibrated to expatriate-influenced Jeddah neighborhoods as the most penetrable taste segment. Pursue quick-commerce dark-store partnerships as the primary go-to-market angle, collapsing delivery windows below thirty minutes.
For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned producers facing automation retrofit capital burdens and SFDA compliance threshold pressures. Long-term viability centers on positions with captive chilled supply chains or extrusion technology leadership. Watch SFDA front-of-pack labeling implementation timelines as the critical inflection signal for reformulation investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Automation Retrofit for SFDA Traceability | Enables qualification for hypermarket private-label procurement specifications. |
| Chilled Supply Chain Acquisition | Secures freshness-dependent dairy-derivative snack positioning in ambient desert climates. |
| Sodium Reduction R&D Program | Preempts front-of-pack labeling disadvantage when SFDA color-coded systems activate. |
| Eastern Province Distribution Buildout | Captures white space in Dammam-Khobar corridors before infrastructure investment accelerates. |
| Quick-Commerce Dark-Store Partnership | Collapses delivery windows for impulse occasions previously routed through retail intermediaries. |
Research Methodology
A standing panel of snack manufacturing plant managers, SFDA regulatory affairs specialists, hypermarket category buyers, and chilled logistics operators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from SFDA filing databases, SASO technical regulation updates, Nielsen retail audit data, and customs import records. Bottom-up production capacity modeling and top-down consumption estimation triangulated volume and value outputs.
Consistency checks against external benchmarks validated projection outputs across the analysis window. Segmentation dimensions modeled include product type, packaging technology tier, distribution channel, and flavor profile, with regional urban density patterns as an additional industry-specific dimension. CAGRs derived from historical trajectory analysis and policy-impact scenario weighting, incorporating extrusion line capacity expansion schedules and Vision 2030 localization incentive uptake curves as key forecast inputs.
Underlying assumptions cover palm oil price stability, SFDA regulatory implementation timelines, and quick-commerce platform penetration rates, with deviation risk concentrated in chilled logistics provider consolidation and expatriate technician availability. Practitioners should keep alternative scenarios live as front-of-pack labeling consultation outcomes and localization incentive structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Grass-Fed Jerkies Market
Snacks
Cereal Bars Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
South Africa Savory Snacks Market
Snacks
North America Pretzel Market
Snacks
Fat Free Snacks Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Baked Savoury Snacks Market
Snacks
Meat Snacks Market
Snacks
Nuts and Seeds (Savory Snacks) Market
Snacks
RTE Popcorn Market
Snacks
Europe Popcorn Market
Snacks
Australia Snack Bar Market
Snacks
Protein Bars Market
Snacks
North America Cereal Bar Market
Snacks
North America Potato Chips Market