
 Lipoprotein Metabolism Disorders Treatment Market | 2026-2036
Lipoprotein Metabolism Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lipoprotein Metabolism Disorders Treatment Market Foresight
RNA-targeted gene silencing is reshaping how lipid-lowering therapies reach patients, shifting development from small-molecule dominance toward nucleic acid platforms. Pfizer leverages its manufacturing scale to supply oral statin formulations across retail pharmacy networks. Amgen anchors the injectable segment with monoclonal antibody production capabilities. Regeneron Pharmaceuticals differentiates through sustained R&D investment in siRNA and antisense approaches.
Lipoprotein metabolism disorders treatment encompasses pharmacological interventions that modulate cholesterol synthesis, absorption, and clearance through hepatic LDL receptor upregulation or VLDL secretion suppression, with formulations ranging from 5 mg to 80 mg potency for oral statins and subcutaneous biologics dosed every 2-4 weeks. The primary purpose is reducing atherosclerotic cardiovascular risk in patients with familial hypercholesterolemia, statin intolerance, or residual lipid abnormalities despite standard therapy. PCSK9 inhibitors command premium positioning due to their ability to achieve LDL reductions exceeding 50% in refractory populations. Oral delivery maintains volume leadership through decades of prescriber familiarity and pharmacy distribution infrastructure. Injectable modalities represent the fastest-expanding channel as self-administration training programs expand into homecare settings.
FDA reviews of cardiovascular outcome data shape approval pathways and label expansions for novel mechanisms, while EMA's benefit-risk assessments influence parallel submissions from multinational sponsors. The EPA monitors environmental discharge from active pharmaceutical ingredient synthesis, adding compliance layers to manufacturing site selection. Reimbursement authorities in Germany and France increasingly tie coverage to hard endpoint demonstration rather than surrogate biomarker achievement. Stakeholders must monitor how real-world evidence mandates from HTA bodies redefine commercialization timelines for combination lipid therapies.
Market Dynamics
RNA-targeted gene silencing platforms are compressing development timelines and forcing incumbents to reallocate R&D budgets away from small-molecule dominance toward nucleic acid manufacturing capabilities.
Growth Catalysts
- PCSK9 inhibitor label expansions:FDA cardiovascular outcome requirements are accelerating submissions for familial hypercholesterolemia indications in pediatric populations.
- Integrated delivery network consolidation:United States-based health systems negotiate exclusive formulary placement for next-generation lipid-lowering agents through risk-sharing arrangements.
- Subcutaneous self-administration training:Homecare nursing programs in Germany reduce clinic visit dependency and expand addressable patient pools for biologic therapies.
Market Restraints
- Active pharmaceutical ingredient concentration:Lipid nanoparticle manufacturing for siRNA therapies concentrates among contract development organizations in Switzerland and Ireland.
- EMA benefit-risk assessment stringency:Parallel submission requirements for novel mechanisms extend regulatory review timelines by 12-18 months compared to FDA pathways.
- Oral statin generic substitution:Pharmacy benefit managers in the United States mandate step-therapy protocols that delay biologic access for non-refractory patients.
Strategic Opportunities
- France reimbursement innovation:HAS is piloting indication-based pricing for combination therapies that demonstrate hard endpoint superiority in real-world evidence studies.
- siRNA-antisense convergence:GalNAc conjugation chemistry enables liver-targeted delivery platforms that reduce dosing frequency to quarterly intervals.
- Specialty pharmacy channel expansion:Hub services in Texas and Florida coordinate prior authorization navigation and patient adherence monitoring for injectable regimens.
Industry Challenges
- Nucleic acid manufacturing scale-up:Commercial production of synthetic oligonucleotides requires dedicated cleanroom facilities with 18-24 month construction timelines.
- LDL-C assay standardization:Laboratory variability in ultracentrifugation methods complicates endpoint demonstration for regulatory submissions across jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipoprotein Metabolism Disorders Treatment Market |
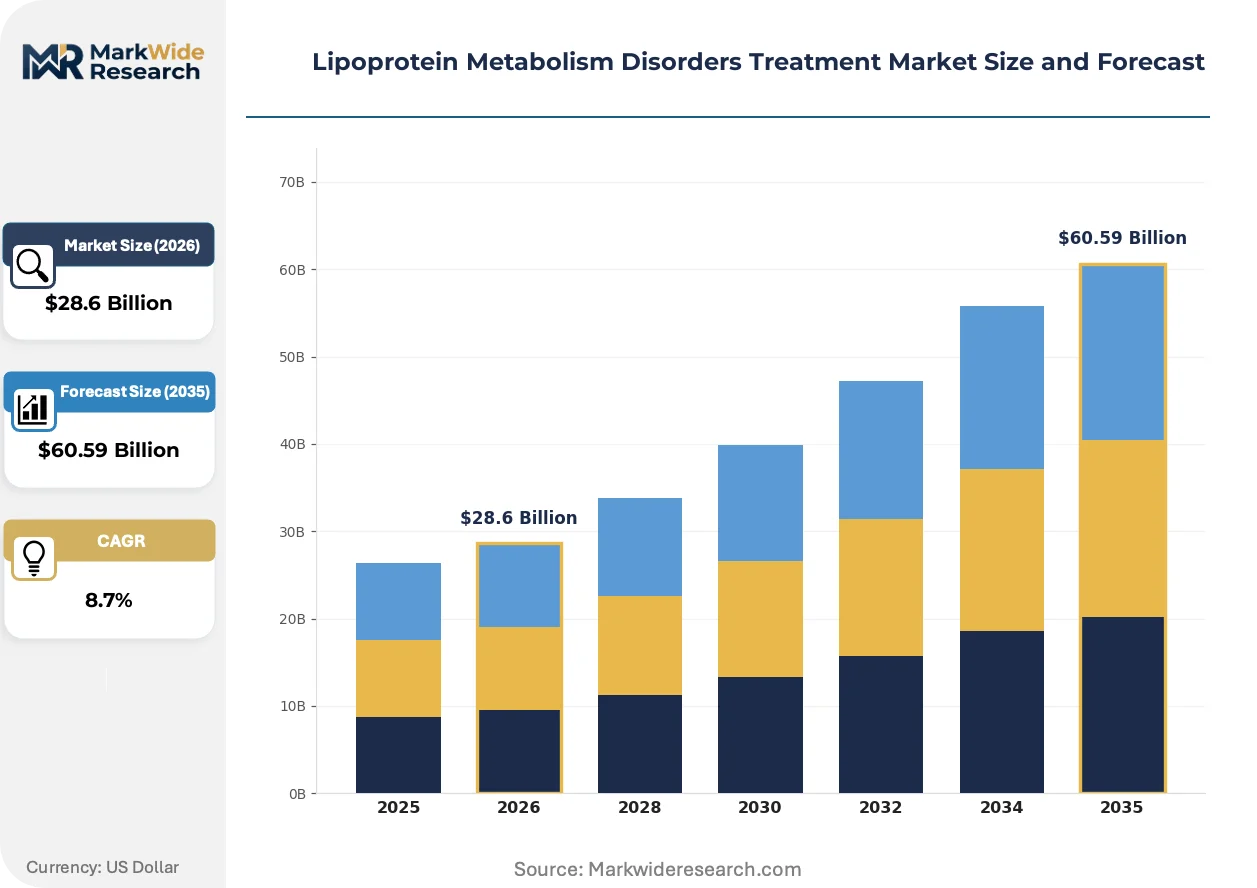
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Statins, Fibrates, Niacin, PCSK9 Inhibitors Delivery Mode: Oral, Injectable, Transdermal, Intravenous End User: Hospitals, Clinics, Homecare, Long-term Care Facilities Therapy Area: Hyperlipidemia, Dyslipidemia, Cardiovascular Disease, Metabolic Syndrome |
| Companies Covered | Pfizer, Amgen, Novartis, AstraZeneca, Regeneron Pharmaceuticals, Merck & Co., Sanofi, Roche, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipoprotein Metabolism Disorders Treatment Market Shifts & Advancements
Gene silencing modalities are rewriting competitive boundaries between oral and injectable segments, while real-world evidence mandates reshape how sponsors design post-market commitment studies.
GalNAc-conjugated siRNA chemistry is collapsing the dosing frequency gap between small molecules and biologics, enabling quarterly subcutaneous administration that matches patient preference for oral convenience. Specialty pharmacies in California and New York report 40% faster therapy initiation when home injection training replaces clinic-based induction. This compression of the care delivery model is forcing traditional infusion centers to restructure as remote monitoring hubs.
EMA's evolving guidance on cardiovascular outcome trials now requires active comparator arms rather than placebo controls for novel LDL-lowering mechanisms. Sponsors must enroll statin-treated populations that mirror real-world heterogeneity, including diabetes and chronic kidney disease subgroups. The requirement is lengthening trial duration and shifting site selection toward Eastern European countries with centralized national health registries.
Integrated delivery networks in the United States are unbundling pharmacy benefit from medical benefit administration, creating separate contracting leverage for lipid-lowering agents. Risk-bearing entities in Minnesota and Wisconsin negotiate outcomes-based contracts that tie formulary tier placement to LDL goal attainment rates measured through health information exchanges. This behavioral shift concentrates purchasing authority among systems with robust analytics infrastructure.
Lipoprotein Metabolism Disorders Treatment Market Segmentation
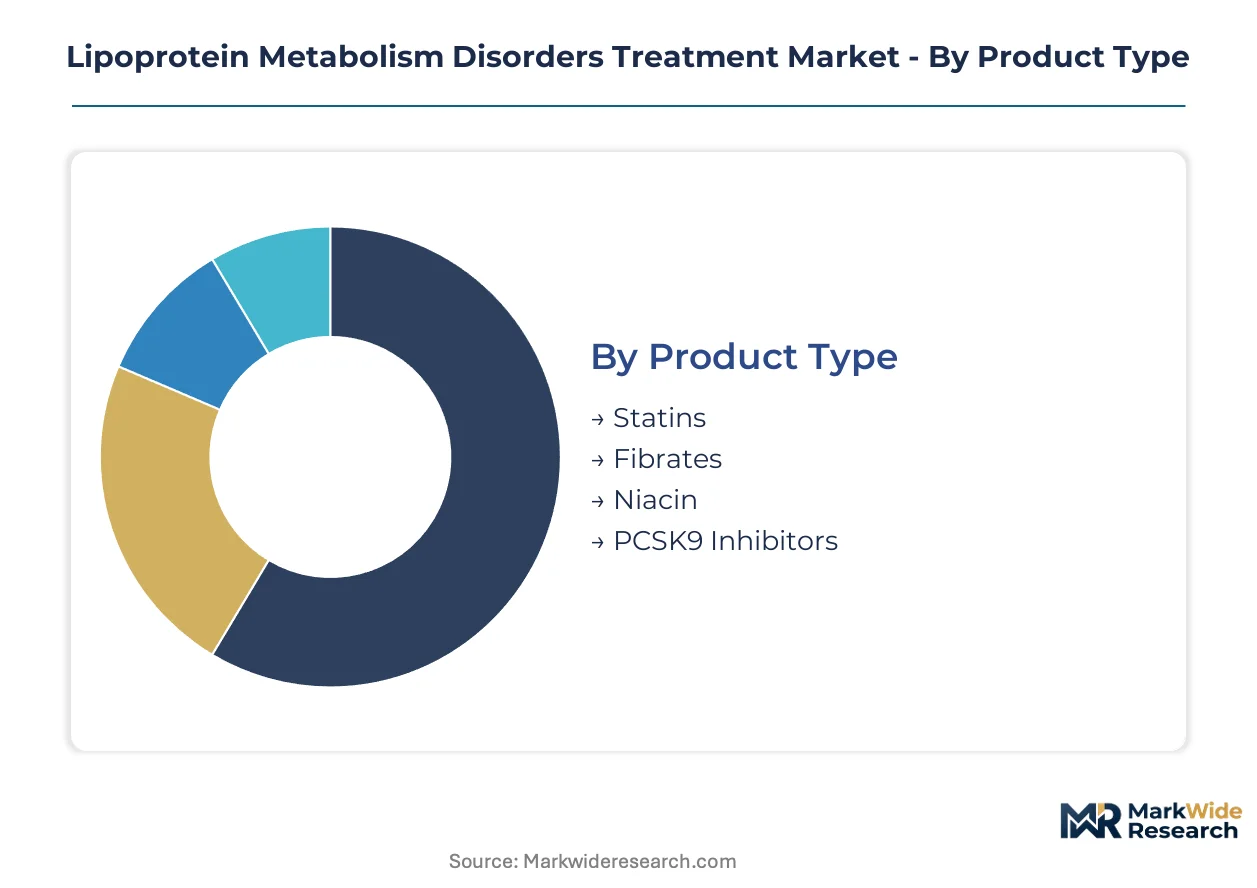
Segmentation in lipid-lowering therapies reveals divergent commercial strategies across administration routes and care settings. Manufacturers must align formulation investments with prescriber workflow preferences and reimbursement channel economics.
Product Type:
Maturity varies sharply across this category, with small-molecule platforms decades ahead of nucleic acid technologies in commercial infrastructure.
- Statins:Oral HMG-CoA reductase inhibitors ranging from 5 mg to 80 mg potency remain the foundational therapy class. Demand concentrates in retail pharmacy networks across the United States and Germany, where pharmacy benefit managers enforce step-therapy protocols that prioritize generic atorvastatin and rosuvastatin before biologic escalation.
- PCSK9 Inhibitors:Monoclonal antibodies and siRNA constructs targeting proprotein convertase subtilisin/kexin type 9 achieve LDL reductions exceeding 50% in refractory populations. Prescription volume clusters in United States specialty clinics and French hospital outpatient departments where integrated delivery networks negotiate risk-sharing contracts tied to cardiovascular outcome achievement.
- Fibrates:PPAR-alpha agonists prescribed for hypertriglyceridemia occupy a narrowing niche as combination therapy adjuncts.
- Niacin:Vitamin B3 formulations at pharmacological doses face declining utilization due to flushing side effects and outcome trial disappointments.
Statins retain volume leadership across all geographies; PCSK9 inhibitors hold the steepest expansion curve as label expansions reach pediatric familial hypercholesterolemia populations.
Delivery Mode:
Cost tier stratification separates mass-market oral formulations from premium-priced biologic administration systems requiring cold-chain logistics.
- Oral:Tablet and capsule formulations dominate prescription volume through decades of prescriber familiarity and pharmacy distribution infrastructure. United States retail chains and German community pharmacies maintain automated dispensing systems optimized for high-volume statin fulfillment.
- Injectable:Subcutaneous monoclonal antibodies and siRNA therapies dosed every 2-4 weeks command premium positioning. Self-administration training programs in Texas and Florida hub services compress therapy initiation timelines by 40% compared to clinic-based induction.
- Transdermal:Patch-based delivery systems remain experimental for lipid-modifying agents with limited commercial penetration.
- Intravenous:Infusion-center administration is restricted to acute lipid apheresis protocols and investigational gene therapies.
Oral delivery captures the highest prescription count; injectable modalities are climbing the fastest as homecare nursing programs expand across Germany and the United States.
End User:
Customer type determines contracting leverage, with consolidated health systems extracting steeper discounts than fragmented outpatient practices.
- Hospitals:Inpatient and outpatient departments manage acute cardiovascular events and initiate high-intensity lipid-lowering protocols. United States integrated delivery networks in Minnesota and Wisconsin unbundle pharmacy benefit administration to create separate contracting leverage for PCSK9 inhibitors.
- Homecare:Nursing services coordinate subcutaneous injection training and adherence monitoring for biologic therapies. Expansion of remote patient monitoring in Florida and California enables therapy initiation outside traditional infusion centers.
- Clinics:Cardiology and endocrinology practices serve as gatekeepers for biologic access prior authorization navigation.
- Long-term Care Facilities:Nursing homes manage polypharmacy complexity in elderly populations with statin intolerance or drug interaction concerns.
Hospitals retain volume leadership through emergency department capture and specialist referral networks; homecare is gaining share fastest as specialty pharmacy hub services restructure care delivery models.
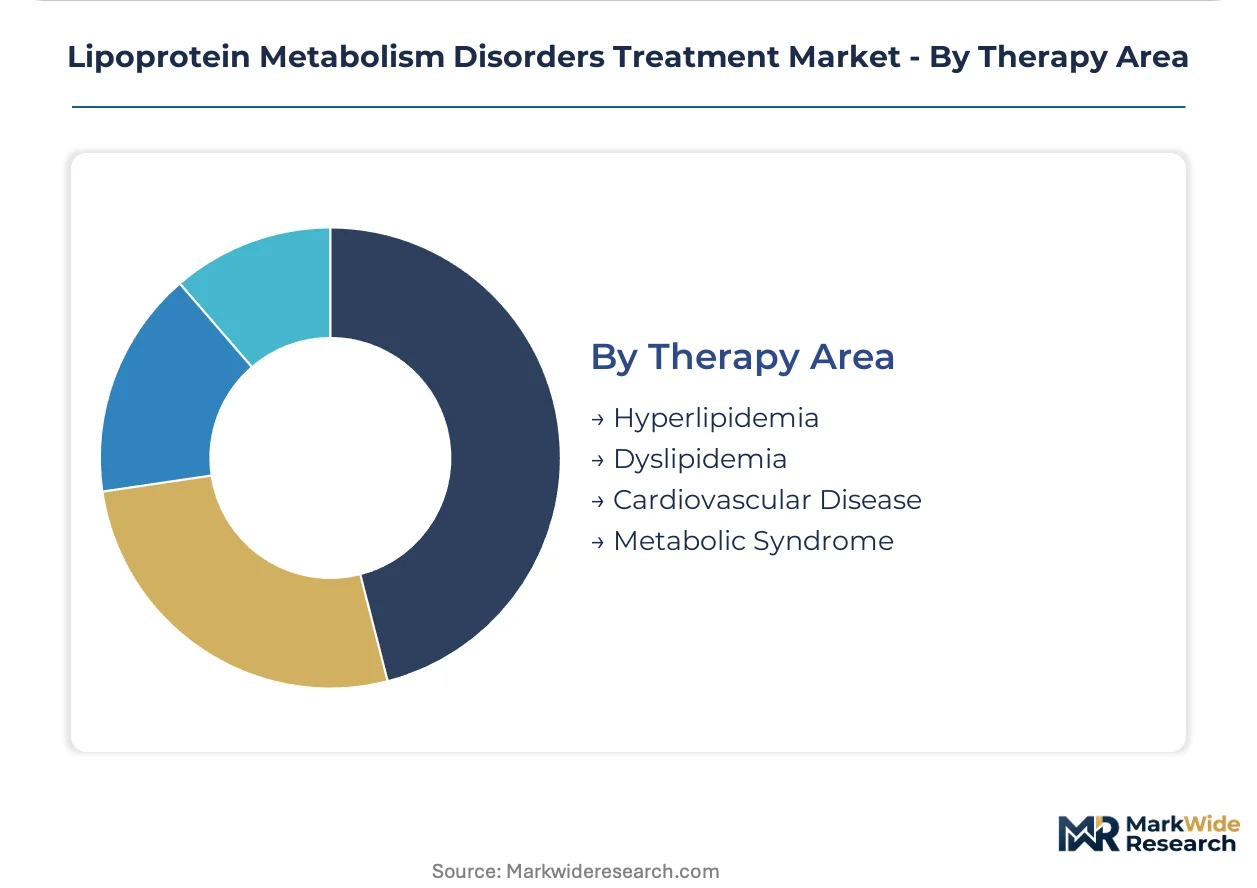
Therapy Area:
Application severity drives pricing tolerance, with established cardiovascular disease justifying premium therapy costs that primary prevention cannot support.
- Cardiovascular Disease:Secondary prevention in post-acute coronary syndrome patients represents the highest-value indication segment. French HAS and German IQWiG reimbursement decisions increasingly tie coverage to hard endpoint demonstration rather than LDL surrogate achievement.
- Hyperlipidemia:Elevated cholesterol and triglyceride levels without established atherosclerotic disease constitute the largest addressable population. United States preventive service guidelines and European Society of Cardiology risk calculators determine treatment thresholds across primary care networks.
- Dyslipidemia:Abnormal lipid profiles in metabolic contexts including diabetes and non-alcoholic fatty liver disease require combination therapy approaches.
- Metabolic Syndrome:Clustered cardiovascular risk factors drive polypharmacy regimens integrating lipid, glucose, and blood pressure management.
Hyperlipidemia retains volume leadership through broad screening program penetration; cardiovascular disease applications show the steepest expansion trajectory as outcome-based contracts concentrate purchasing authority among risk-bearing entities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports lipid-lowering active pharmaceutical ingredients to United States specialty pharmacy networks, while Swiss contract manufacturers supply lipid nanoparticle formulations to North American biotech sponsors.
United States
Integrated delivery networks in Minnesota and Wisconsin negotiate outcomes-based contracts for PCSK9 inhibitors. FDA cardiovascular outcome requirements accelerate pediatric label expansions for familial hypercholesterolemia. Specialty pharmacy hubs in Texas and Florida coordinate home injection training programs that compress therapy initiation timelines.
Germany
IQWiG reimbursement decisions increasingly tie lipid-lowering coverage to hard endpoint demonstration rather than LDL surrogate achievement. EMA benefit-risk assessments extend regulatory review timelines for novel mechanisms by 12-18 months. Homecare nursing programs in Bavaria and North Rhine-Westphalia expand subcutaneous self-administration training for biologic therapies.
Switzerland
Contract development organizations in Basel and Zurich concentrate lipid nanoparticle manufacturing for siRNA therapies. Swissmedic oversight of nucleic acid production adds compliance layers to site selection decisions. The country's precision manufacturing infrastructure supports 18-24 month cleanroom construction timelines for synthetic oligonucleotide facilities.
France
HAS pilots indication-based pricing for combination therapies demonstrating hard endpoint superiority in real-world evidence studies. Pharmacy benefit unbundling from medical benefit administration creates separate contracting leverage for lipid-lowering agents. Hospital outpatient departments in Île-de-France and Auvergne-Rhône-Alpes cluster prescription volume for PCSK9 inhibitors.
United Kingdom
NICE technology appraisals determine formulary access for next-generation lipid-lowering agents across NHS integrated care systems. Real-world evidence mandates from HTA bodies redefine commercialization timelines for combination therapies. Research institutions in London and the Southeast anchor cardiovascular outcome trial enrollment for statin-treated populations with diabetes and chronic kidney disease.
Lipoprotein Metabolism Disorders Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around nucleic acid manufacturing capabilities as RNA-targeted platforms displace small-molecule dominance. Large-cap pharmaceutical companies anchor the oral statin segment through retail pharmacy distribution networks. Mid-cap biotech specialists occupy the injectable biologic tier with monoclonal antibody and siRNA production. Strategic moves concentrate on GalNAc conjugation chemistry licensing and dedicated cleanroom capacity expansion.
Within the large-cap pharmaceutical tier, Pfizer and Novartis exemplify scale-driven supply architectures for oral formulations. Among biotech specialists, Amgen and Regeneron Pharmaceuticals occupy positions defined by injectable production capabilities and sustained R&D investment in gene silencing approaches.
| Leading Market Players |
|---|
| Pfizer |
| Amgen |
| Novartis |
| AstraZeneca |
| Regeneron Pharmaceuticals |
| Merck & Co. |
| Sanofi |
| Roche |
| GlaxoSmithKline |
| Others |
Supply & Pricing Matrix
Swiss contract development organizations concentrating lipid nanoparticle manufacturing for siRNA therapies anchor upstream margin capture, while downstream pricing power accumulates with United States integrated delivery networks negotiating risk-sharing contracts for PCSK9 inhibitors.
Pricing Analysis
Current-generation PCSK9 inhibitors command premium positioning against prior-generation oral statins and emerging next-generation quarterly siRNA formulations. Three-tier pricing structure across premium biologics, standard branded small molecules, and economy generic statins reflects LDL reduction magnitude and cardiovascular outcome data quality. Pricing pressure stems from pharmacy benefit manager step-therapy protocols mandating generic substitution before biologic access. Hospital outpatient departments show least price sensitivity due to outcomes-based contracting, while retail pharmacy networks face greatest cost compression from automated generic dispensing.
Supply Chain Analysis
Extended payment terms from Swiss and Irish contract manufacturers to North American biotech sponsors compress working capital cycles across the nucleic acid tier. Active pharmaceutical ingredient synthesis concentrates in Switzerland, Ireland, and Germany, with formulation finishing in United States specialty pharmacy hubs. Synthetic oligonucleotide production draws from phosphoramidite chemistries, lipid excipients, and GalNAc conjugation reagents. Single-source vulnerability pervades lipid nanoparticle manufacturing due to 18-24 month cleanroom construction timelines. Distribution runs through cold-chain logistics networks serving hospital outpatient departments and homecare nursing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits in a cyclical recovery phase as FDA cardiovascular outcome requirements accelerate pediatric label expansions and replenish pipeline visibility for familial hypercholesterolemia indications.
For Market Incumbents: Pre-empt RNA-targeted platform displacement by acquiring GalNAc conjugation chemistry capabilities or licensing siRNA manufacturing capacity before nucleic acid cleanroom construction timelines extend competitive moats. Anchor backward integration into lipid excipient supply to secure formulation inputs against Swiss and Irish contract manufacturer concentration. Prioritize United States integrated delivery network risk-sharing contracts that tie formulary placement to LDL goal attainment rates. For New Entrants and Emerging Players: German homecare nursing networks represent underpenetrated infrastructure for subcutaneous self-administration training programs that compress therapy initiation timelines outside hospital capture. Target French indication-based pricing pilots for combination therapies demonstrating hard endpoint superiority in real-world evidence studies. Deploy hub service partnerships in Texas and Florida to coordinate prior authorization navigation and patient adherence monitoring. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap biotech specialists with captive siRNA manufacturing capacity and sustained R&D investment in liver-targeted delivery platforms. Long-term viability hinges on nucleic acid production capabilities that displace small-molecule dominance across the analysis window. Monitor EMA benefit-risk assessment stringency as inflection indicator for parallel submission timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| GalNAc Conjugation Chemistry Licensing | Enables liver-targeted siRNA delivery with quarterly dosing frequency matching patient preference. |
| Cleanroom Capacity Expansion | Swiss and Irish sites require 18-24 month construction timelines for synthetic oligonucleotide commercial production. |
| Pediatric Label Expansion | FDA cardiovascular outcome requirements accelerate submissions for familial hypercholesterolemia indications. |
| Integrated Delivery Network Risk-Sharing | United States health systems negotiate outcomes-based contracts tied to LDL goal attainment rates. |
| Specialty Pharmacy Hub Services | Texas and Florida coordinators compress therapy initiation by 40% through home injection training. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling triangulated against top-down manufacturer revenue disclosures.
Calibration against historical prescription trends and regulatory approval timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, delivery mode, end user, and therapy area, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from growth driver elasticity analysis and indication expansion trajectories, incorporating cardiovascular outcome trial enrollment rates and reimbursement authority coverage decisions as industry-specific forecast inputs.
Practitioners should monitor EMA benefit-risk assessment stringency, FDA pediatric label expansion velocity, and nucleic acid manufacturing capacity commissioning for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Chronic Lower Back Pain (CLBP) Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Cachexia Treatment Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Vesicoureteral Reflux Market