
 Hypertriglyceridemia Therapeutics Market | 2026-2036
Hypertriglyceridemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Hypertriglyceridemia Therapeutics Market Outlook
Specialty endocrinology clinics is rotating toward biologic and RNA-targeted therapies as first-line interventions for severe cases. Amarin Pharmaceuticals leverages its marine-derived omega-3 platform to anchor commercial presence in cardiology settings. Ionis Pharmaceuticals sustains pipeline momentum through antisense oligonucleotide programs directed at apolipoprotein C-III. Arrowhead Pharmaceuticals differentiates via RNA interference constructs that silence hepatic triglyceride production pathways.
Hypertriglyceridemia therapeutics comprise pharmacological agents that modulate lipoprotein metabolism through fibrate-mediated peroxisome proliferator activation, omega-3 fatty acid-mediated VLDL synthesis suppression, or HMG-CoA reductase inhibition, typically formulated for oral administration at doses calibrated to fasting triglyceride thresholds above 150 mg/dL. The primary purpose centers on reducing pancreatitis risk in severe presentations and lowering cardiovascular event probability in persistent elevations. Fibrates occupy the mature core of the market with established generic competition compressing margins, while injectable delivery modes represent the fastest-expanding structural pocket as patient self-administration gains traction in home care. Omega-3 fatty acids concentrate margin pools in prescription-grade formulations differentiated from dietary supplement alternatives.
FDA cardiovascular outcomes requirements and EMA efficacy benchmarks for triglyceride-lowering agents shape Phase III trial designs and label expansion pathways across development programs. The EPA's environmental review processes for marine-sourced active pharmaceutical ingredients add supply chain compliance layers for omega-3 manufacturers. Stakeholders must monitor FDA guidance evolution on surrogate endpoint acceptability versus hard cardiovascular outcomes as this determines regulatory capital allocation across mechanism classes.
Market Dynamics
Injectable RNA-targeted therapies are fragmenting the oral-dominant hypertriglyceridemia treatment paradigm, forcing incumbents to defend fibrate franchises while biotech entrants capture severe-case volumes through cardiology specialty networks.
Growth Catalysts
- CVOT Streamlining Initiatives:FDA guidance evolution on surrogate endpoint acceptability accelerates antisense oligonucleotide development timelines, reducing Phase III capital requirements for hepatic triglyceride production inhibitors.
- Home Self-Administration Infrastructure:Specialty pharmacy distribution networks now support patient-managed injectable therapy protocols, expanding addressable populations beyond clinic-dependent oral regimens.
- Marine Sourcing Compliance Frameworks:EPA environmental review standardization for omega-3 active pharmaceutical ingredients stabilizes supply chain predictability for prescription-grade formulations.
Market Restraints
- Generic Fibrate Compression:Established peroxisome proliferator-activated receptor agonists face margin erosion from multi-source generic competition, deflating revenue pools for mechanism-class incumbents.
- Cardiovascular Outcomes Trial Burden:EMA efficacy benchmarks for triglyceride-lowering agents mandate extensive hard endpoint studies, extending regulatory capital lockup periods for novel mechanisms.
- Marine Ecosystem Volatility:Omega-3 manufacturers depend on wild-catch fisheries concentrated in Pacific and Atlantic extraction zones, exposing supply to climate-driven stock fluctuations.
Strategic Opportunities
- Sub-Saharan Africa Penetration:Diagnostic infrastructure expansion in Nigeria, Kenya, and South Africa creates first-mover positioning for portable lipid monitoring paired with telemedicine-managed therapy protocols.
- Combination Formulation Development:Fixed-dose pairing of RNA interference constructs with statin backbones addresses polypharmacy burden in metabolic syndrome populations.
- IRA Price Negotiation Exemptions:Orphan-drug designation pathways for severe hypertriglyceridemia subpopulations shield novel biologics from Medicare price controls through 2031.
Industry Challenges
- Antisense Manufacturing Scale-Up:Oligonucleotide synthesis capacity constraints limit batch sizes for apolipoprotein C-III targeting programs, creating supply-demand mismatches during commercial ramp.
- Specialty Care Coordination Complexity:Endocrinology-cardiology handoff protocols for severe-case management require interoperable electronic health record systems that remain fragmented across hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypertriglyceridemia Therapeutics Market |
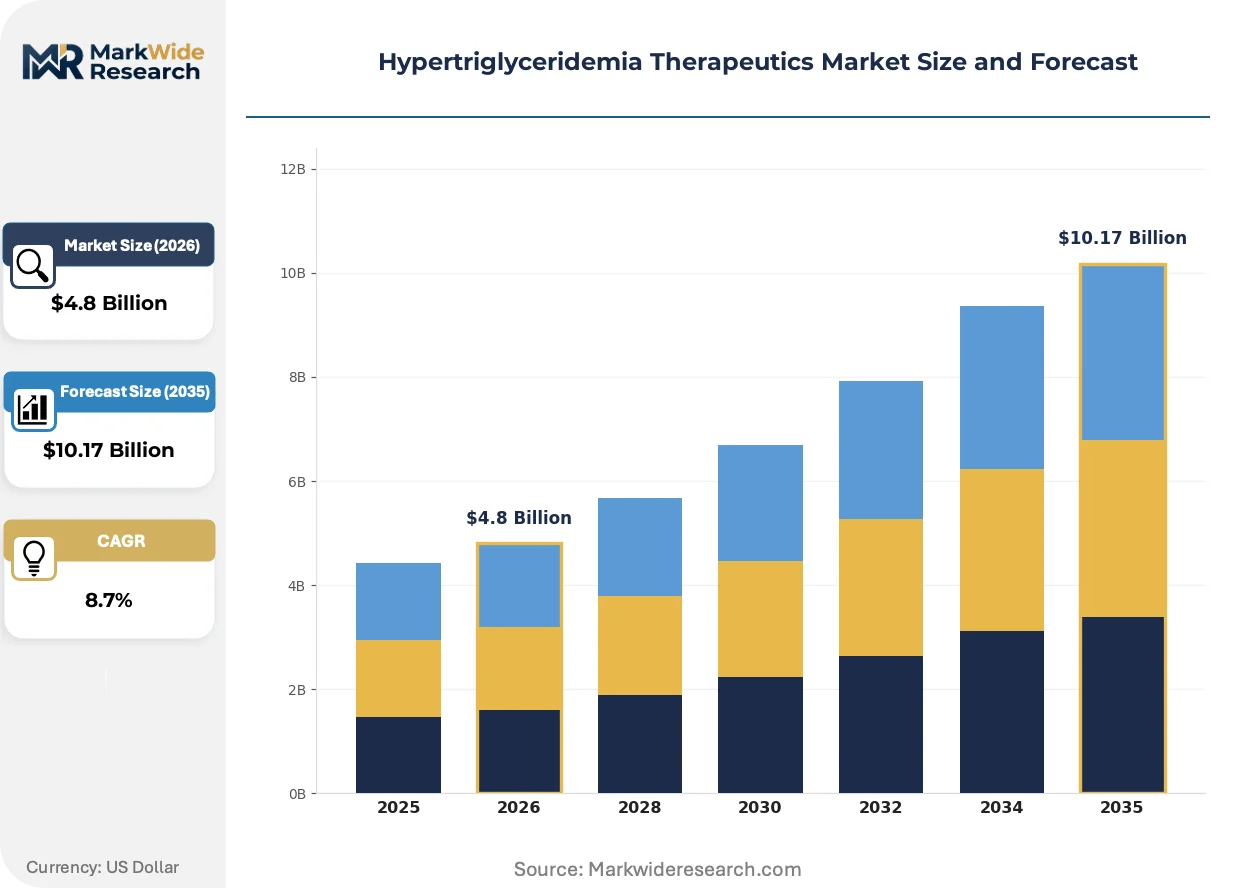
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibrates, Omega-3 Fatty Acids, Statins, Niacin Delivery Mode: Oral, Injectable, Topical, Intravenous Therapy Area: Cardiology, Endocrinology, Metabolism, Internal Medicine End User: Hospitals, Clinics, Home Care, Pharmacies |
| Companies Covered | Ionis Pharmaceuticals, Arrowhead Pharmaceuticals, 89bio, Amarin Pharmaceuticals, AstraZeneca, GlaxoSmithKline, Viatris, Novo Nordisk, NorthSea Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypertriglyceridemia Therapeutics Market Strategic Shifts
RNA-targeted mechanisms are fragmenting the therapeutic hierarchy, while regulatory pressure on cardiovascular outcomes reshapes clinical trial economics and patient self-administration redistributes care delivery from clinics to home settings.
RNA interference constructs silencing hepatic triglyceride production pathways are fragmenting the oral fibrate standard of care. Cardiology departments in integrated hospital systems now prioritize these injectables for severe hypertriglyceridemia patients with recurrent pancreatitis history. This mechanism shift compresses prescription volumes for traditional peroxisome proliferator-activated receptor agonists while expanding specialty pharmacy capture rates.
EMA efficacy benchmarks for triglyceride-lowering agents now require demonstration of pancreatitis risk reduction alongside cardiovascular outcomes. This dual-endpoint mandate extends trial duration and patient recruitment complexity for development programs targeting moderate elevations. Antisense oligonucleotide developers are responding with adaptive trial designs that stratify enrollment by baseline severity thresholds.
Specialty care networks now unbundle diagnostic monitoring from pharmaceutical dispensing, creating independent revenue streams for lipid panel interpretation services. Hospital-affiliated clinics in the United States are contracting with regional laboratories for rapid turnaround triglyceride testing, displacing in-house phlebotomy infrastructure. This channel restructuring concentrates in Medicare Advantage populations where capitated payments incentivize cost-efficient care coordination.
Hypertriglyceridemia Therapeutics Market Segmentation
Hypertriglyceridemia therapeutics distribute unevenly across channel hierarchies, with oral formulations dominating pharmacy volumes while injectable biologics concentrate in specialty care networks. Understanding these flow patterns reveals where margin pools accumulate versus where generic compression erodes value.
Product Type:
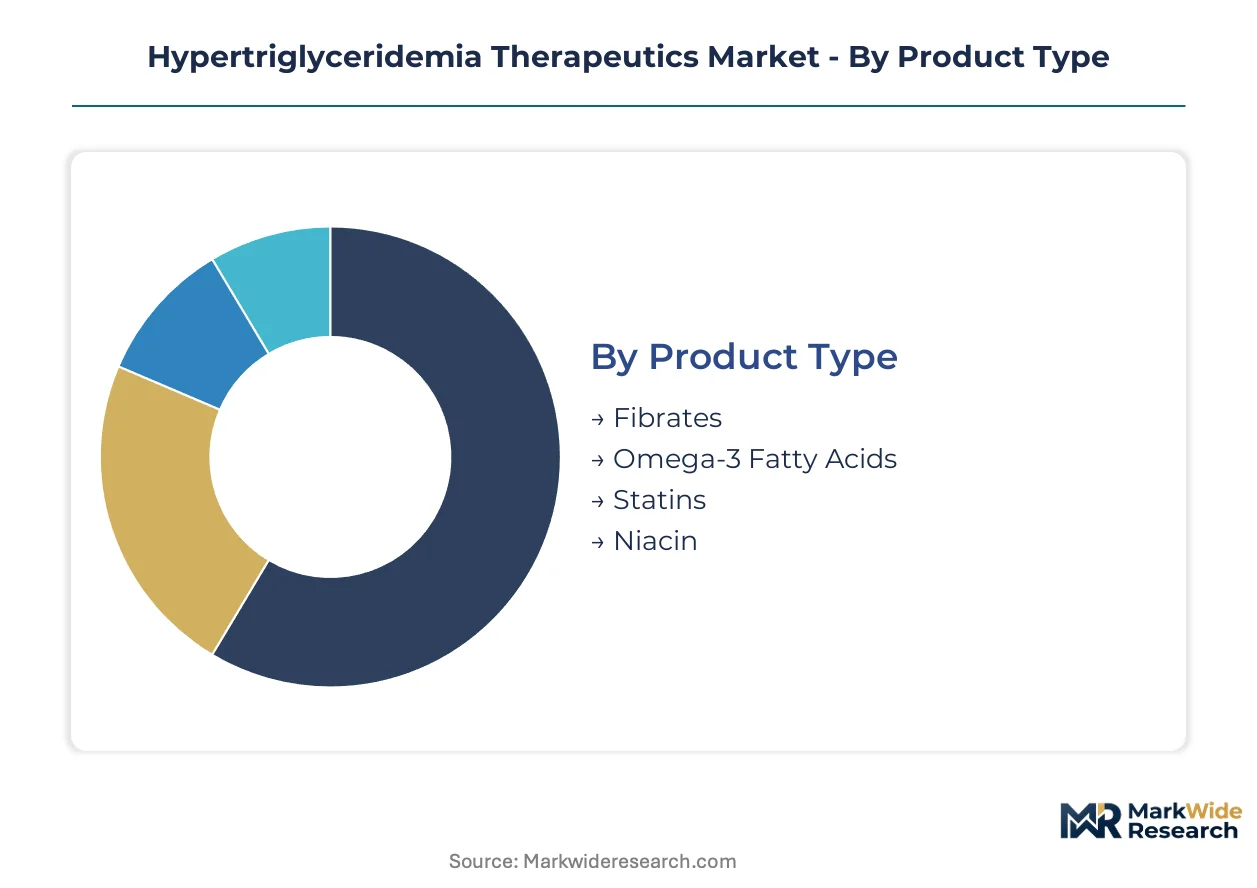
Fibrates and omega-3 formulations flow through retail pharmacy channels in high volumes, while statin combinations and niacin derivatives route through hospital outpatient clinics where prior authorization requirements create gatekeeper dynamics.
- Fibrates:Peroxisome proliferator-activated receptor agonists reduce hepatic VLDL production through mitochondrial fatty acid oxidation activation. Demand concentrates in Medicare Part D formularies where generic fenofibrate dominates prescription volumes despite margin erosion from multi-source competition.
- Omega-3 Fatty Acids:Marine-derived EPA and DHA formulations suppress hepatic triglyceride synthesis through SREBP-1c pathway modulation. Cardiology specialty networks in the United States drive prescription volumes for prescription-grade icosapent ethyl, differentiated from dietary supplement alternatives by FDA-approved cardiovascular outcomes labeling.
- Statins:HMG-CoA reductase inhibitors with triglyceride-lowering effects route through primary care networks managing metabolic syndrome populations.
- Niacin:Nicotinic acid derivatives targeting lipoprotein lipase activity face declining utilization due to flushing side-effect profiles and HDL-centric outcome trial disappointments.
By volume, Fibrates leads. By growth pace, Omega-3 Fatty Acids is ahead.
Delivery Mode:
Cost tier stratification separates clinic-administered intravenous loading doses from patient-managed home injection protocols, with oral maintenance regimens occupying the economy tier of the pricing architecture.
- Oral:Tablet and capsule formulations dominate maintenance therapy for moderate hypertriglyceridemia, with once-daily dosing supporting adherence in chronic populations.
- Injectable:Subcutaneous antisense oligonucleotide and RNA interference constructs enable hepatic triglyceride production silencing. Endocrinology clinics in integrated delivery networks capture these patients for severe hypertriglyceridemia with recurrent pancreatitis history.
- Topical:Transdermal delivery systems remain experimental for lipid-modifying agents, with limited commercial penetration.
- Intravenous:Hospital-based infusion protocols support acute pancreatitis management in extreme triglyceride elevations exceeding 1000 mg/dL.
Oral formulations capture the largest patient population. Injectable delivery is climbing the fastest as self-administration infrastructure matures.
Therapy Area:
Application concentration varies by severity threshold, with cardiology departments managing cardiovascular risk reduction while endocrinology handles severe phenotype cases requiring biologic intervention.
- Cardiology:Integrated hospital systems prioritize triglyceride lowering for residual cardiovascular risk reduction in statin-treated patients. FDA cardiovascular outcomes trial requirements shape prescribing patterns for omega-3 therapies in this channel.
- Endocrinology:Specialty clinics manage severe hypertriglyceridemia populations with genetic lipid disorders or insulin resistance-driven elevations. Antisense oligonucleotide therapies route through this channel due to complexity of monitoring requirements.
- Metabolism:Metabolic syndrome and non-alcoholic fatty liver disease overlap populations drive combination therapy demand.
- Internal Medicine:Primary care gatekeepers handle initial diagnosis and moderate-case management before specialty referral.
Cardiology generates the highest prescription volumes. Endocrinology shows the steepest expansion trajectory for novel biologic adoption.
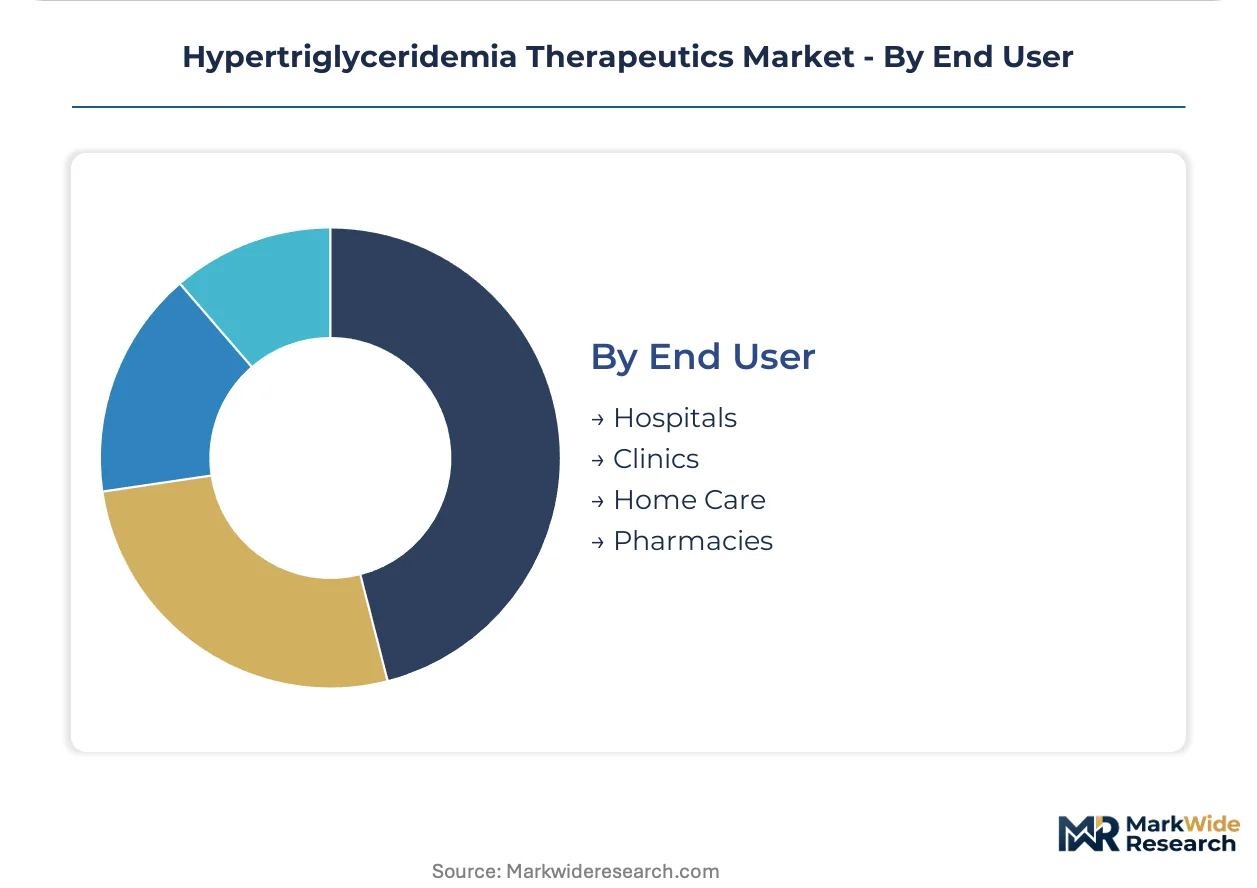
End User:
Customer type determines reimbursement pathway complexity, with hospital outpatient departments navigating bundled payments while home care channels rely on specialty pharmacy distribution networks.
- Hospitals:Inpatient acute pancreatitis management and outpatient infusion centers handle severe case stabilization. Medicare severity-adjusted diagnosis-related groups influence length-of-stay decisions for triglyceride-driven admissions.
- Clinics:Hospital-affiliated specialty care networks unbundle diagnostic monitoring from pharmaceutical dispensing, creating independent revenue streams for lipid panel interpretation services.
- Home Care:Patient self-administration of injectable therapies expands through specialty pharmacy distribution networks supporting subcutaneous injection training and adherence monitoring.
- Pharmacies:Retail and mail-order channels dominate oral maintenance therapy fulfillment, with prior authorization requirements creating friction for branded omega-3 formulations.
Pharmacies lead by prescription volume. Home Care is gaining share fastest as self-administration protocols reduce clinic dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based specialty pharmaceutical manufacturers export prescription-grade omega-3 formulations to cardiology networks across Canada and Western Europe. Marine-sourced active pharmaceutical ingredients flow from North Atlantic fisheries into formulation facilities serving hospital systems worldwide.
United States
Cardiology departments in integrated hospital systems drive demand for injectable RNA-targeted therapies and prescription-grade icosapent ethyl. FDA cardiovascular outcomes trial requirements shape development timelines for novel hepatic triglyceride production inhibitors. The Greater Boston biotech cluster anchors antisense oligonucleotide research programs targeting apolipoprotein C-III.
Germany
EMA efficacy benchmarks for triglyceride-lowering agents mandate dual-endpoint trials demonstrating pancreatitis risk reduction alongside cardiovascular outcomes. REACH compliance frameworks govern chemical synthesis processes for fibrate manufacturing. The Rhine-Ruhr industrial corridor hosts formulation facilities supplying oral maintenance therapies across Central European pharmacy networks.
Japan
PMDA regulatory pathways prioritize hard cardiovascular endpoints over surrogate biomarkers for novel mechanism approvals. METI industrial policy supports domestic manufacturing capacity for marine-derived omega-3 active pharmaceutical ingredients. The Kanto region around Tokyo concentrates specialty endocrinology clinics managing severe hypertriglyceridemia with genetic lipid disorder presentations.
United Kingdom
NHS England reimbursement protocols favor generic fenofibrate for moderate-case management while restricting branded biologic access through specialized commissioning frameworks. MHRA post-Brexit regulatory autonomy enables accelerated assessment pathways for RNA interference constructs. The Cambridge-London life sciences corridor houses clinical trial infrastructure for hepatic triglyceride production inhibitors.
India
CDSCO streamlined approval processes for fixed-dose combinations address polypharmacy burden in metabolic syndrome populations. PLI scheme incentives attract contract manufacturing organizations serving global fibrate generic markets. Hyderabad and Ahmedabad clusters specialize in active pharmaceutical ingredient synthesis for peroxisome proliferator-activated receptor agonists.
Hypertriglyceridemia Therapeutics Market Competitive Environment
Listed leaders compete with private specialists across RNA-targeted mechanism platforms, creating a bifurcated structure where public biotechs advance antisense pipelines and private entities control marine-sourced supply chains. The market organizes around three archetypes: marine-derivative platform holders, RNA interference construct developers, and generic fibrate manufacturers. Consolidation pressure operates through strategic partnerships between biotech innovators and established cardiovascular commercialization networks, while capacity expansion concentrates in oligonucleotide synthesis facilities.
Within the RNA-targeted therapy tier, Ionis Pharmaceuticals and Arrowhead Pharmaceuticals exemplify platform-specialist positioning, with Amarin Pharmaceuticals anchoring the marine-derived omega-3 segment. These three entities occupy distinct competitive spaces defined by mechanism class rather than direct product substitution, reflecting market segmentation between hepatic production inhibition and circulating lipid modification approaches.
| Leading Market Players |
|---|
| Ionis Pharmaceuticals |
| Arrowhead Pharmaceuticals |
| 89bio |
| Amarin Pharmaceuticals |
| AstraZeneca |
| GlaxoSmithKline |
| Viatris |
| Novo Nordisk |
| NorthSea Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Oligonucleotide synthesis scale economies in the Greater Boston biotech cluster anchor production cost floors for RNA-targeted therapies, concentrating margin pools among platform specialists while generic fibrate manufacturers compete on batch-volume efficiency. This scale gradient shapes pricing architecture across mechanism classes, with antisense manufacturing constraints supporting premium positioning for hepatic triglyceride production inhibitors against commodity oral formulations.
Pricing Analysis
Next-generation RNA interference constructs command substantial premiums over mature fibrate mechanisms, while prescription-grade omega-3 formulations occupy a mid-tier position differentiated by FDA cardiovascular outcomes labeling. Pricing stratifies across premium biologic injectables, standard prescription-grade marine derivatives, and economy generic peroxisome proliferator-activated receptor agonists. Cost compression in the fibrate tier stems from multi-source generic competition flooding Medicare Part D formularies. Hospital outpatient departments show lowest price sensitivity for severe-case biologics, while retail pharmacy channels face highest sensitivity for maintenance oral therapies.
Supply Chain Analysis
The United States and India anchor active pharmaceutical ingredient production for fibrate manufacturing, while North Atlantic fisheries and Japanese coastal waters feed marine-derived omega-3 extraction. Oligonucleotide synthesis draws from specialized chemical manufacturing clusters in Massachusetts and California, with formulation finishing concentrated in FDA-inspected facilities across the Eastern Seaboard. Single-source vulnerability concentrates in wild-catch fishery dependencies for EPA and DHA raw materials. Distribution runs through specialty pharmacy networks for injectable biologics, retail chains for oral maintenance therapies, and hospital outpatient clinics for acute-case stabilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in specialty pharmacy adherence monitoring and lipid panel interpretation are expanding faster than pharmaceutical dispensing margins, creating recurring revenue layers that outperform hardware-centric prescription models.
For Market Incumbents: Secure cardiology department formulary positioning through outcomes-based contracting that demonstrates pancreatitis risk reduction in severe hypertriglyceridemia populations. Expand antisense oligonucleotide manufacturing capacity in FDA-registered facilities to preempt supply-demand mismatches during commercial ramp. Counter generic fibrate compression by acquiring RNA-targeted platform capabilities or licensing hepatic triglyceride production inhibitors. For New Entrants and Emerging Players: Differentiate on sub-Saharan Africa diagnostic infrastructure partnerships that pair portable lipid monitoring with telemedicine-managed therapy protocols. Target orphan-drug designation pathways for severe hypertriglyceridemia subpopulations to secure IRA price negotiation exemptions through 2031. Pursue fixed-dose combination development addressing polypharmacy burden in metabolic syndrome populations as primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-specialist biotechs with validated antisense oligonucleotide or RNA interference construct pipelines over single-asset developers. Long-term viability rests on mechanism-class diversification spanning hepatic production inhibition and circulating lipid modification approaches. Acquisition target archetype: clinical-stage RNA-targeted developers with cardiology specialty network relationships. Signal to watch: FDA guidance evolution on surrogate endpoint acceptability versus hard cardiovascular outcomes as inflection indicator for development capital allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Adaptive trial designs stratifying enrollment by baseline severity thresholds accelerate antisense oligonucleotide programs. |
| Manufacturing Scale-Up | Oligonucleotide synthesis capacity expansion in FDA-registered facilities addresses batch-size constraints for apolipoprotein C-III targeting. |
| Regulatory Approval Pathway | Orphan-drug designation for severe hypertriglyceridemia subpopulations shields novel biologics from Medicare price controls. |
| Strategic Partnership | Specialty pharmacy distribution alliances enable patient-managed injectable therapy protocols beyond clinic-dependent oral regimens. |
| Geographic Expansion | Diagnostic infrastructure partnerships in Nigeria, Kenya, and South Africa create first-mover positioning for telemedicine-managed protocols. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling across delivery modes and therapy areas triangulated against top-down market sizing from manufacturer revenue disclosures and specialty pharmacy distribution data.
Across the analysis window, the forecasting framework modeled segmentation dimensions including treatment line, dosage form, administration route, patient severity threshold, and regional regulatory cluster. CAGRs derived from mechanism-class adoption curves, generic erosion rates for mature franchises, and biologic penetration trajectories in severe-case populations. Forecast inputs incorporated CVOT streamlining initiative impacts on development timelines and marine sourcing compliance framework stability.
Decision-makers should treat outputs as directional under assumptions of stable FDA cardiovascular outcomes guidance and continued specialty pharmacy network expansion; material deviation in regulatory endpoint requirements or reimbursement policy would warrant model refresh. Recalibration cycles align with material shifts in regulatory guidance evolution, generic entry events, and marine ecosystem volatility affecting omega-3 supply predictability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Antithrombin Market
Pharmaceuticals
Global Human Rotavirus Vaccine Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Enbrel Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Intravenous Solution Compounders Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Italy Opioids Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
Bulbospinal Muscular Atrophy Drugs Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market