
 Global Chronic Lower Back Pain (CLBP) Market | 2026-2036
Global Chronic Lower Back Pain (CLBP) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chronic Lower Back Pain (CLBP) Market Foresight
Project finance for neuromodulation device leasing is tilting competitive dynamics toward asset-light pain management platforms. Medtronic leverages captive financing programs to sustain implant volume across hospital networks. Johnson & Johnson anchors its position through bundled procedural solutions that integrate device supply with rehabilitation protocols.
Chronic lower back pain denotes persistent lumbar-region discomfort exceeding twelve weeks, typically involving degenerative disc pathology, facet joint dysfunction, or neuropathic radiculopathy managed through multimodal intervention. The condition's primary commercial purpose centers on restoring functional mobility while reducing dependency on systemic opioid therapy. Pharmacological segments still occupy the largest revenue pool, though neuromodulation and radiofrequency ablation are registering the fastest expansion as payers tighten opioid reimbursement. Spinal cord stimulation technology leads margin capture due to recurring device replacement cycles and programming service fees.
The FDA breakthrough device program and EMA's parallel scientific advice framework are compressing time-to-market for novel neuromodulation platforms while tightening post-market surveillance requirements. WHO analgesic ladder revisions and CMS national coverage determinations for dorsal root ganglion stimulation are reshaping prescriber behavior and device procurement criteria. Stakeholders must monitor evolving NICE technology appraisals in the United Kingdom and Japan's MHLW reimbursement pricing reforms for implantable pain devices to anticipate access shifts.
Market Dynamics
Neuromodulation device leasing through captive financing programs is restructuring competitive positioning, allowing asset-light pain management platforms to scale without balance-sheet strain while hospital networks consolidate procurement around bundled procedural solutions.
Growth Catalysts
- FDA Breakthrough Device Pathway:The FDA breakthrough device designation accelerates market access for novel spinal cord stimulation systems, compressing review timelines for refractory CLBP interventions and enabling earlier revenue capture for qualifying platforms.
- Radiofrequency Ablation Expansion:Payer tightening on opioid reimbursement is redirecting procedural volume toward minimally invasive thermal ablation technologies, particularly within United States hospital outpatient departments expanding interventional pain services.
- Germany's Reimbursement Clarity:Germany's statutory health insurance framework provides explicit NUB innovation funding for dorsal root ganglion stimulation, reducing procurement friction and supporting predictable implant volume growth across academic medical centers.
Market Restraints
- Implant Cost Concentration:Spinal cord stimulation generators and leads represent 60-70% of procedural cost, with supply concentrated among three dominant manufacturers, limiting price negotiation leverage for hospital purchasing committees.
- Japan's MHLW Pricing Compression:Japan's Ministry of Health, Labour and Welfare applies biennial reimbursement cuts to implantable medical devices, eroding margin stability for neuromodulation platforms despite stable procedural demand.
- Conservative Therapy Substitution:Structured physical therapy and cognitive behavioral pain management programs retain first-line guideline status in NICE technology appraisals, delaying interventional referral pathways and compressing addressable patient populations.
Strategic Opportunities
- Underpenetrated Indian Market:India's CDSCO regulatory streamlining and expanding private hospital networks in Mumbai, Delhi, and Bangalore create whitespace for neuromodulation adoption as chronic pain prevalence rises with urban aging demographics.
- Closed-Loop Stimulation Convergence:Integration of evoked compound action potential sensing with automated amplitude adjustment enables personalized therapy delivery, differentiating next-generation platforms from fixed-output legacy systems.
- CMS National Coverage Determination:The 2023 CMS NCD for dorsal root ganglion stimulation removes prior authorization barriers for specific neuropathic pain indications, expanding Medicare beneficiary access and standardizing reimbursement across United States markets.
Industry Challenges
- Interventional Pain Specialist Scarcity:Fellowship-trained physicians capable of complex lead placement and programming optimization remain concentrated in tertiary academic centers, constraining procedural capacity expansion into community hospital settings.
- Post-Market Surveillance Burden:FDA and EMA tightened vigilance requirements for implantable neuromodulation devices demand expanded real-world evidence collection, increasing regulatory compliance overhead and extending product lifecycle management costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chronic Lower Back Pain (CLBP) Market |
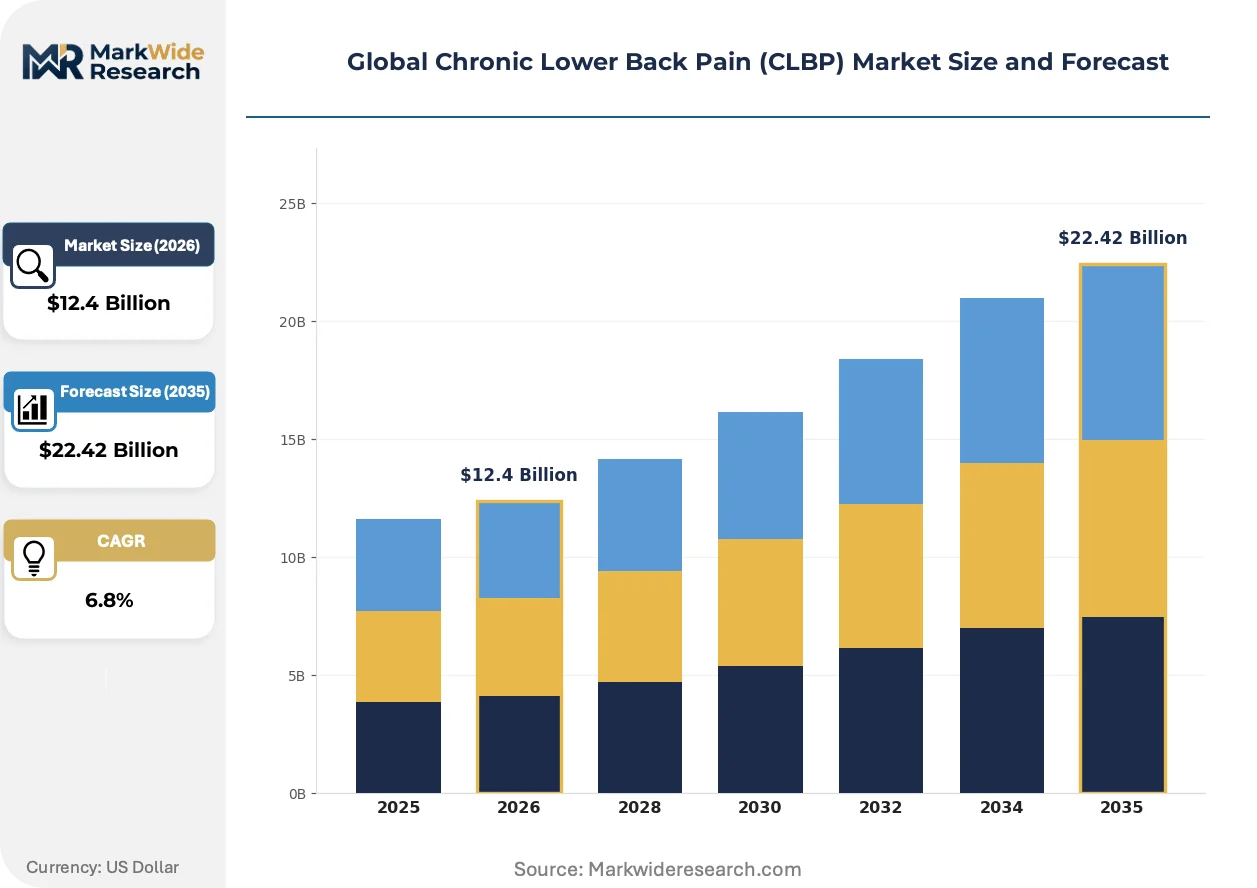
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Pharmacological, Physical Therapy, Surgical Intervention, Neuromodulation, Cognitive Behavioral Therapy Application: Workplace Ergonomics, Postural Correction, Pain Management Clinics, Rehabilitation Centers End User: Orthopedic Specialists, Pain Management Physicians, Rehabilitation Therapists, Primary Care Providers Technology: Transcutaneous Electrical Nerve Stimulation, Radiofrequency Ablation, Spinal Cord Stimulation, Ultrasound Therapy |
| Companies Covered | Medtronic, Johnson & Johnson, Pfizer Inc., Stryker Corporation, Boston Scientific Corporation, Abbott Laboratories, Merck & Co., Inc., Bayer AG, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chronic Lower Back Pain (CLBP) Market Shifts & Advancements
Digital health integration is compressing traditional care delivery models, with remote patient monitoring and algorithm-driven therapy optimization displacing episodic clinic-based programming. Three convergent developments are reshaping product architecture and commercial strategy.
Closed-loop spinal cord stimulation systems incorporating evoked compound action potential sensing are digitizing therapy delivery, enabling automated amplitude adjustment based on real-time neural response feedback. Pain management clinics in the United States and Germany are prioritizing these platforms for complex regional pain syndrome cases. The technology is digitizing the traditional trial-to-implant pathway by reducing manual programming visits and compressing time-to-optimal therapy.
EMA's parallel scientific advice framework permits synchronized pre-submission dialogue across multiple national competent authorities, harmonizing clinical evidence requirements for neuromodulation device approvals. This regulatory convergence reduces redundant trial design and accelerates cross-border market entry. Manufacturers targeting European expansion are leveraging this pathway to align MDR technical documentation with FDA breakthrough device data packages.
Hospital purchasing committees are unbundling device supply from implantation and follow-up services, fragmenting traditional vendor-captured revenue streams. This procurement evolution favors specialized distributors with logistics capabilities and independent pain physicians with ambulatory surgery center ownership. The United States exhibits the most pronounced shift, with regional health systems consolidating implantable device contracts through centralized value analysis committees.
Global Chronic Lower Back Pain (CLBP) Market Segmentation
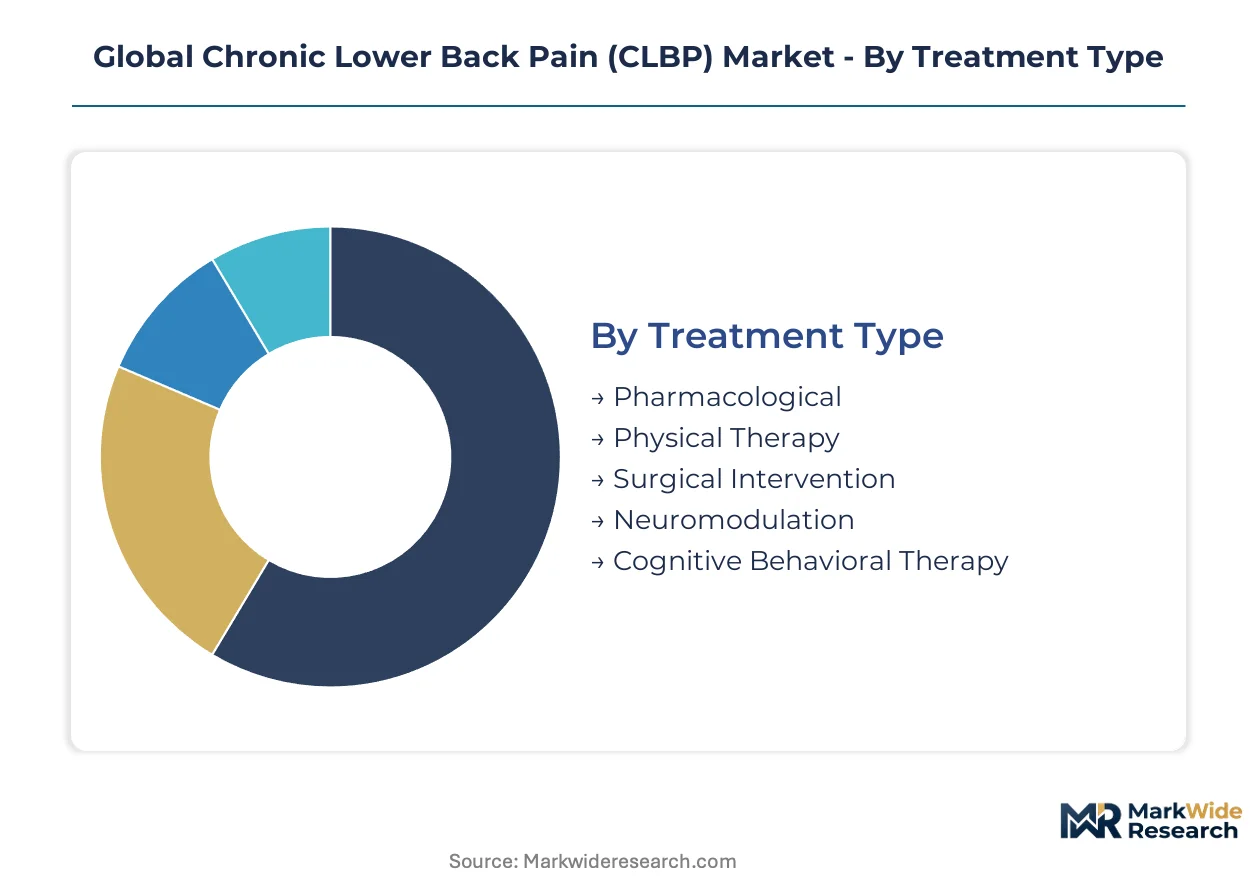
Segmentation in the CLBP market reveals divergent service intensity requirements across treatment modalities. Device-dependent segments demand ongoing programming support and replacement cycles, while pharmacological and therapeutic segments operate on episodic prescription models with minimal after-sales engagement.
Treatment Type:
After-sales service intensity varies dramatically across this category, with implantable systems requiring years of parameter optimization and hardware replacement versus single-dispensation drug therapies.
- Pharmacological:Oral NSAIDs, muscle relaxants, and neuropathic agents constitute the largest revenue pool through chronic prescription patterns. Demand concentrates in United States retail pharmacy chains and Germany's statutory health insurance pharmacy networks as opioid prescribing restrictions tighten and payers prioritize generic formulary compliance.
- Neuromodulation:Implantable spinal cord stimulation and dorsal root ganglion systems generate recurring revenue through battery replacement cycles and remote programming services. Pain management clinics in the United States and academic medical centers in Germany anchor adoption, driven by CMS national coverage determinations and NUB innovation funding pathways.
- Physical Therapy:Structured exercise protocols and manual therapy delivered through outpatient settings.
- Surgical Intervention:Lumbar fusion, disc replacement, and decompression procedures performed in hospital inpatient settings.
- Cognitive Behavioral Therapy:Psychologist-delivered pain coping interventions reimbursable through behavioral health carve-outs.
Pharmacological holds the largest share; momentum sits with neuromodulation.
Application:
Procurement authority fragments across this category, with employers controlling workplace interventions, hospitals governing procedural settings, and independent clinicians directing post-acute rehabilitation.
- Pain Management Clinics:Dedicated interventional facilities performing fluoroscopy-guided injections, radiofrequency ablation, and neuromodulation trials. United States ambulatory surgery centers and German Schmerztherapie practices drive procedural volume growth as specialists consolidate into multi-site platforms.
- Rehabilitation Centers:Post-surgical and chronic pain functional restoration programs combining physical therapy with occupational retraining. Japan's Kaigo rehabilitation facilities and United States skilled nursing facilities represent concentrated demand as aging demographics expand post-acute care needs.
- Workplace Ergonomics:Employer-funded workstation modifications and movement coaching.
- Postural Correction:Retail and clinical biomechanical assessment services.
Pain management clinics hold the largest share; rehabilitation centers are gaining share fastest.
End User:
Referral pathway economics determine commercial access, with gatekeeper primary care providers controlling upstream patient flow while specialists capture procedural margin.
- Pain Management Physicians:Fellowship-trained anesthesiologists and physiatrists performing interventional procedures and device implantation. Demand clusters in United States metropolitan markets and German university hospitals where reimbursement clarity supports dedicated pain practice viability.
- Orthopedic Specialists:Spine surgeons performing decompressive and fusion procedures. Tertiary academic centers in the United States and Japan's JOA-certified spine centers concentrate complex surgical volume.
- Rehabilitation Therapists:Physical and occupational therapists delivering exercise-based interventions.
- Primary Care Providers:First-line diagnosticians and pharmacological prescribers managing uncomplicated CLBP.
Pain management physicians hold the largest share; orthopedic specialists show steepest expansion trajectory.
Technology:
Regulatory pathway complexity stratifies competitive entry, with PMA-designated implantable systems facing multi-year evidence requirements versus 510(k) cleared external devices.
- Spinal Cord Stimulation:Implantable pulse generators and lead arrays delivering paresthesia-based or closed-loop pain inhibition. United States pain practices and Germany's NUB-funded academic centers anchor premium system adoption as closed-loop sensing differentiates next-generation platforms.
- Radiofrequency Ablation:Thermal lesioning of medial branch nerves and dorsal root ganglia using cooled or conventional electrodes. United States hospital outpatient departments and ambulatory surgery centers drive volume as payer restrictions on repeated epidural steroid injections redirect procedural mix.
- Transcutaneous Electrical Nerve Stimulation:External wearable devices for home-based symptomatic relief.
- Ultrasound Therapy:Diagnostic imaging and therapeutic deep heating applications.
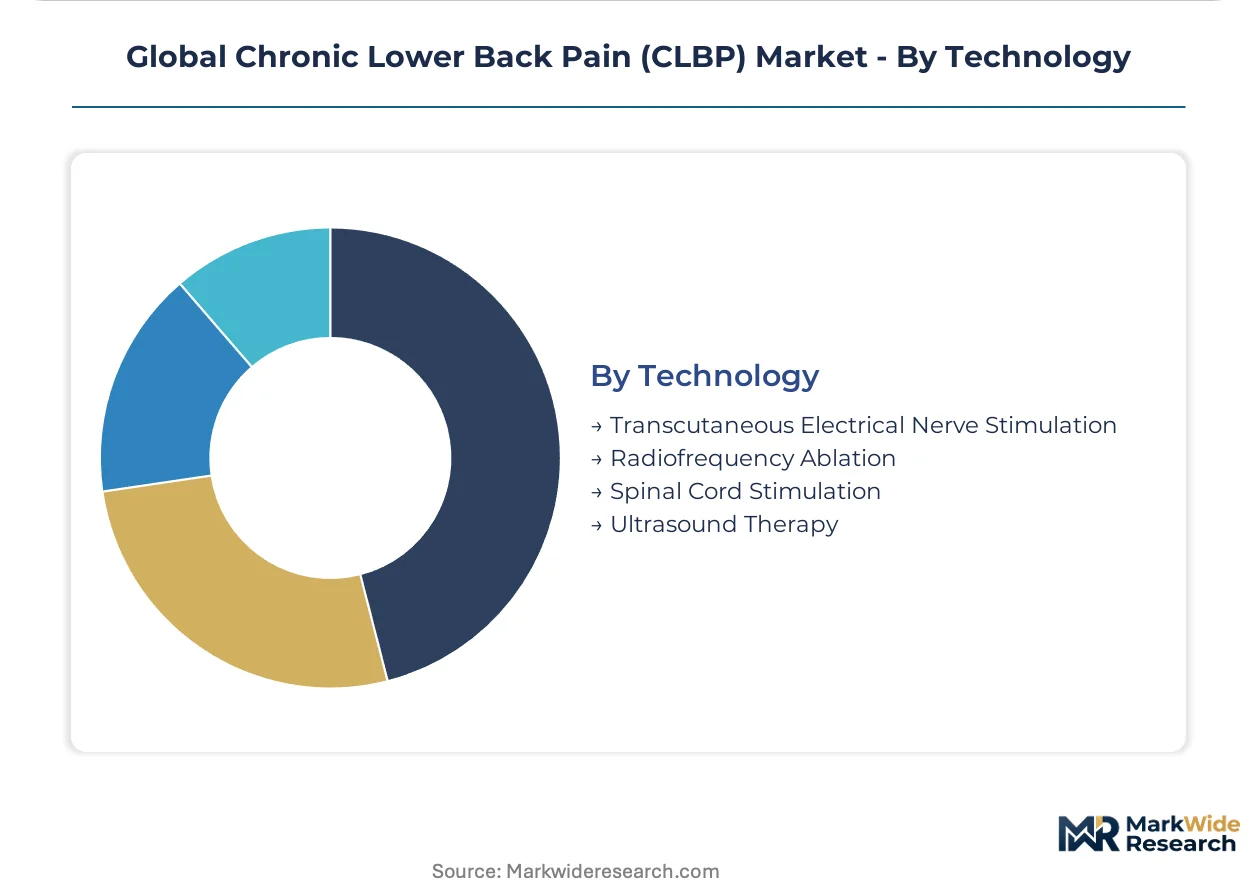
Spinal cord stimulation holds the largest share; radiofrequency ablation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement clarity and regulatory acceleration are concentrating procedural volume in markets with established neuromodulation coverage frameworks. The United States, Germany, Japan, India, and the United Kingdom each present distinct access dynamics shaped by payer structure and device approval pathways.
United States
Medicare coverage determinations and commercial payer bundles are expanding dorsal root ganglion stimulation access. The FDA breakthrough device designation compresses review timelines for novel spinal cord stimulation platforms. Pain management clinics in Florida and Texas are consolidating into multi-site platforms to capture rising procedural volume.
Germany
Statutory health insurance NUB innovation funding provides explicit reimbursement for dorsal root ganglion stimulation procedures. The EMA parallel scientific advice framework harmonizes clinical evidence requirements with FDA pathways. Academic medical centers in Berlin and Munich are anchoring closed-loop system adoption through university hospital procurement networks.
Japan
Aging demographics are expanding the addressable patient population for implantable pain devices. The MHLW applies biennial reimbursement cuts that compress margin stability for neuromodulation manufacturers. Spine centers in Tokyo and Osaka are concentrating complex lead placement capacity within JOA-certified tertiary facilities.
India
Urban aging in Mumbai, Delhi, and Bangalore is driving chronic pain prevalence among working-age populations. CDSCO regulatory streamlining is accelerating market entry timelines for imported neuromodulation systems. Private hospital networks in Maharashtra and Karnataka are building interventional pain service lines to capture self-pay procedural demand.
United Kingdom
NICE technology appraisals retain conservative therapy as first-line guidance, delaying interventional referral pathways. The NHS England specialized commissioning framework governs access to spinal cord stimulation for refractory cases. Pain management networks in London and Manchester are consolidating referral pathways around designated implanting centers.
Global Chronic Lower Back Pain (CLBP) Market Competitive Landscape
On the supply side, the industry is consolidated around three dominant manufacturers controlling spinal cord stimulation generator and lead supply, with pharmaceutical incumbents occupying parallel revenue pools in oral analgesics. Strategic archetypes span integrated device-procedure bundlers, standalone neuromodulation specialists, and diversified pharma-device hybrids. Competitive moves center on captive financing programs to sustain implant volume and unbundling of device supply from follow-up services to capture ambulatory surgery center procurement.
Within the integrated device-procedure tier, Medtronic and Johnson & Johnson exemplify bundling strategies that combine hardware supply with rehabilitation protocol integration. Boston Scientific Corporation occupies a position among neuromodulation specialists focused on spinal cord stimulation platform differentiation. These three manufacturers anchor the implantable device segment where generator and lead costs concentrate procedural economics.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Pfizer Inc. |
| Stryker Corporation |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Merck & Co., Inc. |
| Bayer AG |
| Sanofi |
| Others |
Supply & Pricing Matrix
Undercapacity in Japanese neuromodulation manufacturing is tightening generator and lead availability, forcing United States hospital purchasing committees toward longer-term contracting postures while German academic centers absorb premium pricing for closed-loop systems through NUB innovation funding pathways.
Pricing Analysis
Certification level (FDA-breakthrough versus CE-marked standard) creates the primary spread between spinal cord stimulation platforms, with closed-loop sensing capabilities commanding further differentiation. Three-tier pricing structure across premium sensing-enabled, standard programmable, and economy fixed-output systems dominates procurement negotiations. Cost compression in the economy tier is intensifying because India's CDSCO streamlining invites lower-cost imports. Ambulatory surgery centers exhibit the highest price sensitivity, while German university hospitals show the least due to explicit innovation reimbursement.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for implantable pulse generator components. Manufacturing concentrates in the United States, Ireland, and Costa Rica for final device assembly, while rare earth magnet sourcing draws from Chinese processing facilities. Single-source vulnerability in proprietary lead connector designs constrains second-sourcing options. Distribution runs through specialized medical device distributors with consignment inventory agreements at hospital implanting centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Chronic Lower Back Pain Market sits in early-cycle expansion as closed-loop neuromodulation penetration remains below fifteen percent even in reimbursed markets, with CMS national coverage determinations and Germany's NUB pathways accelerating specialist adoption curves.
For Market Incumbents: Insulate generator and lead margins by deepening backward integration into battery cell production and securing exclusive ambulatory surgery center consignment agreements. Closed-loop algorithm differentiation from emerging sensor-software hybrids represents the core threat requiring sustained R&D allocation toward evoked compound action potential sensing refinement. For New Entrants and Emerging Players: India's private hospital networks in Maharashtra and Karnataka represent the most penetrable entry point, with self-pay procedural demand outpacing reimbursed infrastructure. Radiofrequency ablation equipment for pain management clinics offers lower regulatory barriers than implantable systems, enabling revenue generation while building toward spinal cord stimulation submissions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across radiofrequency ablation platforms as disposable electrode commoditization reduces per-procedure hardware requirements. Acquisition targets should cluster around software-enabled therapy optimization firms with FDA 510(k) clearance pathways, with the signal to watch being CMS national coverage determination expansion beyond dorsal root ganglion stimulation into broader neuropathic indications.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerates review timelines for novel closed-loop spinal cord stimulation platforms targeting refractory cases. |
| Hospital System Partnership | Bundles device supply with rehabilitation protocols across United States multi-site pain management platforms. |
| Reimbursement Strategy Development | Secures CMS national coverage determinations and Germany NUB innovation funding for dorsal root ganglion procedures. |
| Software Companion Development | Enables remote patient monitoring and algorithm-driven therapy optimization displacing episodic clinic visits. |
| CE Marking Pathway Execution | Leverages EMA parallel scientific advice to harmonize clinical evidence with FDA breakthrough device data packages. |
Research Methodology
A spread of perspectives from pain management physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers converged on the working assumptions. Primary interviews combined with secondary validation against FDA 510(k) and PMA filings, CMS national coverage determination records, and Germany's NUB innovation funding databases. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue disclosures across the analysis window.
Demand-supply balance modeling anchored the forecast framework, with segmentation across treatment type, application setting, end-user specialty, and technology platform throughout the forecast period. CAGRs derived from procedure volume growth curves weighted by reimbursement pathway maturity and device replacement cycle economics. Closed-loop adoption rates and radiofrequency ablation procedural mix served as key sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, MHLW pricing compression severity, or NICE technology appraisal conservatism would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and specialist training pipeline expansion. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cystic Fibrosis Transmembrane Conductance Regulator (CFTR) Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
TIL Therapy Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Neuroendocrine Carcinoma Treatment Market
Specialty Medicine
Global Endometriosis Treatment Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Global Gastroparesis Treatment Market