
 Carcinoid Syndrome Diarrhea Treatment Market | 2026-2036
Carcinoid Syndrome Diarrhea Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Carcinoid Syndrome Diarrhea Treatment Market Analysis
North American manufacturing capacity for somatostatin analogs is narrowing as domestic fill-finish investments lag European and Asian expansion. Novartis leverages its integrated peptide synthesis network to sustain supply security across multiple continents. Ipsen Biopharmaceuticals anchors European production with specialized depot formulation capabilities. Lexicon Pharmaceuticals differentiates through targeted small-molecule development for breakthrough symptom control.
Carcinoid syndrome diarrhea treatment encompasses pharmacological interventions that modulate serotonin and peptide hormone overproduction in neuroendocrine tumor patients, primarily using somatostatin analogs such as octreotide and lanreotide that inhibit secretory diarrhea through G-protein coupled receptor blockade. The therapeutic goal centers on reducing bowel movement frequency and improving quality-of-life metrics in refractory cases. Depot injection formulations command premium positioning due to extended dosing intervals and improved adherence profiles among homecare patients. Oral tablet development represents the fastest-growing delivery mode segment as manufacturers pursue patient convenience and reduced healthcare utilization.
FDA orphan drug designation and EMA priority medicine pathways shape clinical trial design and market exclusivity structures for novel entrants in this indication. The EPA and national environmental regulators impose stringent manufacturing discharge limits on peptide production facilities, elevating capital requirements for new capacity. Stakeholders must monitor somatostatin analog biosimilar filings and their associated regulatory data protection periods to anticipate pricing inflection points and portfolio repositioning needs.
Market Dynamics
Peptide manufacturing concentration in Switzerland and Ireland is forcing supply chain reconfiguration as EPA discharge limits tighten and FDA orphan drug exclusivity periods reshape competitive entry timing.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and seven-year market exclusivity accelerate clinical trial enrollment for novel somatostatin analog formulations targeting refractory cases.
- Specialty Pharmacy Networks:Home infusion capabilities expand patient access to depot formulations, reducing hospital utilization and improving adherence metrics in dispersed populations.
- Peptide Synthesis Automation:Solid-phase manufacturing advances compress production cycle times and improve batch consistency for long-acting injectable supply security.
Market Restraints
- Fill-Finish Capacity Bottlenecks:European contract manufacturers dominate sterile peptide processing, creating geographic concentration risk for North American supply continuity.
- EMA Environmental Compliance Costs:REACH chemical registration and wastewater discharge thresholds elevate capital requirements for new European production facilities.
- Oral Small-Molecule Substitution Pressure:Telotristat ethyl and emerging tryptophan hydroxylase inhibitors threaten somatostatin analog market position in mild-to-moderate cases.
Strategic Opportunities
- Japanese PMDA Sakigake Pathway:Expedited review timelines for innovative oncology supportive care products accelerate market entry for next-generation depot formulations.
- Home Healthcare Channel Expansion:Self-administration training programs and remote monitoring integration create direct-to-patient distribution models outside traditional infusion centers.
- Bioconjugate Technology Convergence:Antibody-peptide fusion approaches combine tumor targeting with hormonal suppression, opening addressable populations beyond current analog responders.
Industry Challenges
- Peptide Chemist Talent Scarcity:Specialized expertise in cyclic peptide synthesis and depot formulation science concentrates among a limited pool of experienced practitioners.
- Biosimilar Data Protection Navigation:Reference product exclusivity cliff timing requires precise portfolio lifecycle management to defend branded position.
- Legacy Health System Integration:Electronic health record interoperability gaps complicate real-world evidence collection for outcomes-based contracting with payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carcinoid Syndrome Diarrhea Treatment Market |
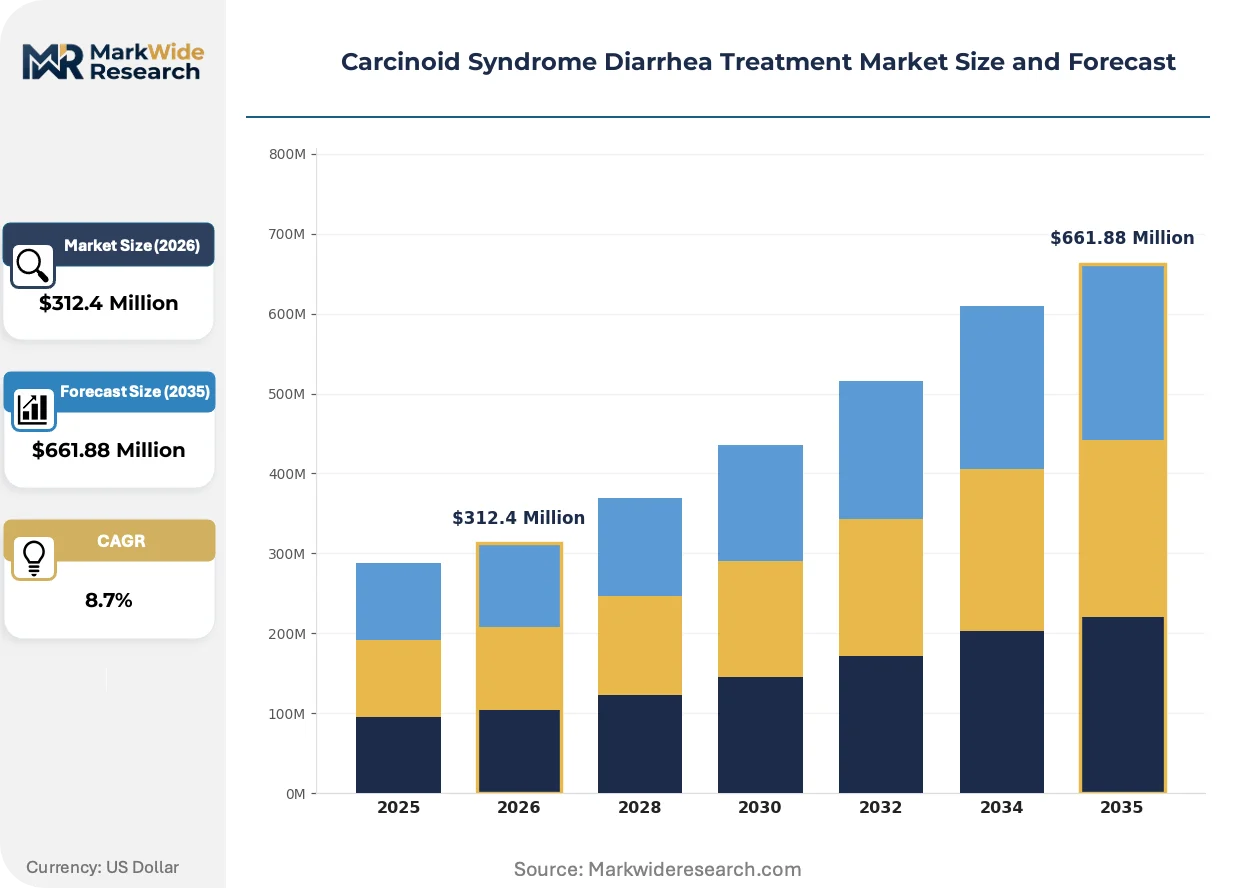
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Octreotide, Lanreotide, Placebo, Combination Therapy Delivery Mode: Subcutaneous Injection, Intravenous, Oral Tablets, Depot Injection End User: Hospitals, Clinics, Homecare, Specialty Pharmacies Treatment Protocol: Direct Therapy, Supportive Care, Patient Education, Palliative Care |
| Companies Covered | Lexicon Pharmaceuticals, Ipsen Biopharmaceuticals, Novartis, Teva Pharmaceutical Industries, Pharmascience, Omega Laboratories, Pfizer, Hutchison China MediTech, Progenics Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carcinoid Syndrome Diarrhea Treatment Market Emerging Trajectories
Digital therapeutics and remote patient monitoring platforms are compressing traditional care delivery models while regulatory pathways accelerate novel mechanism approvals.
Oral somatostatin analog development is virtualizing the injection-dependent treatment paradigm for carcinoid syndrome diarrhea. Patients with needle aversion or limited infusion access are driving enrollment in sublingual and tablet formulation trials. This modality shift is virtualizing specialty pharmacy distribution networks and reducing reliance on cold-chain logistics infrastructure.
EMA's priority medicines scheme and FDA's breakthrough therapy designation are compressing development timelines for novel tryptophan hydroxylase inhibitors. Accelerated assessment pathways compress Phase II-to-approval intervals by twelve to eighteen months for agents demonstrating substantial symptom improvement over standard of care. German and French reimbursement authorities are responding with conditional coverage frameworks tied to post-market outcome confirmation.
Home-based patient reported outcome capture is displacing clinic-centric efficacy measurement. Wearable devices and smartphone-based bowel movement logging applications enable continuous symptom tracking outside traditional site visits. This behavioral shift is most visible in United States integrated delivery networks where value-based contracts reward quality-of-life metric improvements.
Carcinoid Syndrome Diarrhea Treatment Market Segmentation
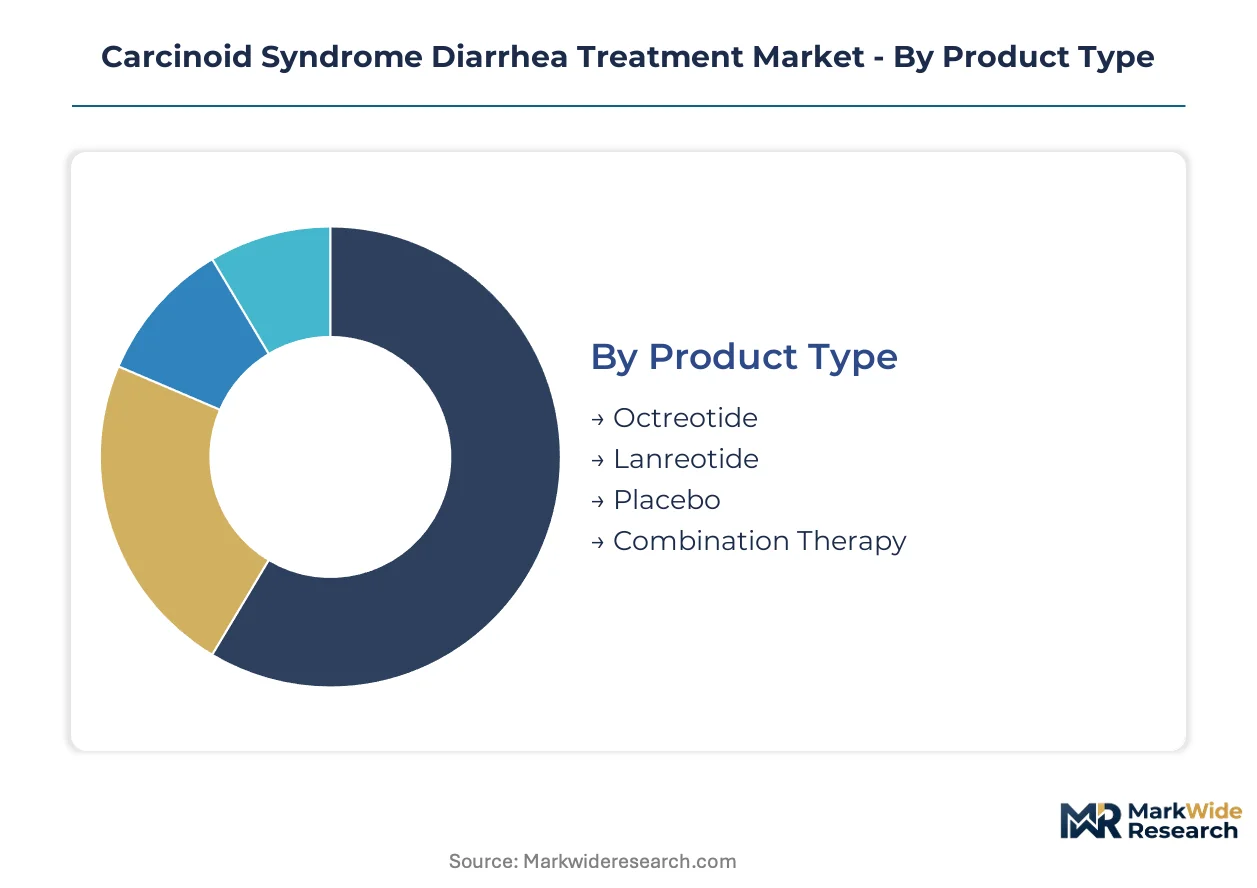
Segmentation in carcinoid syndrome diarrhea treatment reveals how formulation science, care delivery location, and patient acuity intersect to determine therapeutic selection and commercial outcomes. Understanding these divisions exposes where manufacturers must align R&D investment with reimbursement and access infrastructure.
Product Type:
After-sales service intensity varies sharply across this category, with depot formulations requiring specialty pharmacy training programs and adverse event hotlines that small-molecule alternatives simply do not need.
- Octreotide:Synthetic octapeptide somatostatin analog that blocks G-protein coupled receptors to inhibit serotonin and peptide hormone secretion. Demand concentrates in United States integrated delivery networks where prior authorization requirements favor established formularies with robust patient support infrastructure. The molecule's decades-long clinical record anchors prescriber confidence despite injection burden.
- Lanreotide:Slow-release somatostatin analog formulated as prolonged-release aqueous gel for deep subcutaneous administration. German and French hospital networks drive volume for this agent, motivated by extended dosing intervals that reduce nursing workload and align with DRG-based cost containment. EMA orphan drug exclusivity periods have shaped its European commercial trajectory.
- Placebo:Control arm component in clinical trial design and comparative effectiveness research protocols.
- Combination Therapy:Concurrent somatostatin analog plus tryptophan hydroxylase inhibitor regimens targeting refractory symptom profiles.
Octreotide holds the largest share; momentum sits with combination approaches as sequential therapy fails to control breakthrough symptoms.
Delivery Mode:
Cost tier stratification in this category separates premium depot formulations from commodity injection alternatives, with oral development programs threatening to collapse the entire pricing architecture.
- Depot Injection:Long-acting microsphere or aqueous gel formulations enabling monthly or extended-interval administration. Japanese homecare networks and United States specialty pharmacy channels absorb the majority of volume, driven by adherence improvements and reduced healthcare utilization. Cold-chain logistics requirements elevate service costs and create geographic access disparities.
- Oral Tablets:Sublingual and immediate-release tablet formulations in development to eliminate injection dependency. United States and German patient advocacy enrollment is climbing fastest for these trials, motivated by needle aversion and rural access limitations. This modality is gaining share fastest among mild-to-moderate cases where symptom control thresholds are lower.
- Subcutaneous Injection:Immediate-release peptide administration requiring multiple daily doses in acute settings.
- Intravenous:Hospital-based administration for perioperative or critical care scenarios.
Depot injection commands premium positioning; oral tablets are expanding most quickly as convenience-driven demand reshapes development priorities.
End User:
Application concentration in this category tracks the migration of stable patients away from infusion centers toward lower-acuity settings where reimbursement and outcomes measurement differ materially.
- Specialty Pharmacies:Limited-distribution networks with disease-specific clinical expertise, prior authorization management, and patient adherence monitoring. United States volume concentrates here as integrated delivery networks outsource pharmaceutical benefits to contracted partners with REMS capabilities. These entities capture the highest-margin formulations through exclusive distribution agreements.
- Homecare:Self-administration and nursing visit models for patients with established therapeutic response and stable disease. German and Japanese reimbursement frameworks have expanded homecare eligibility fastest, reducing hospital days and aligning with aging population care preferences. Remote monitoring integration is deepening prescriber confidence in this channel.
- Hospitals:Acute care and initial diagnosis settings where intravenous rescue therapy and surgical consultation remain concentrated.
- Clinics:Outpatient oncology and gastroenterology practices managing stable patients between hospital encounters.
Specialty pharmacies hold the largest share; homecare is climbing the fastest as site-of-care policies shift financial risk toward lower-cost settings.
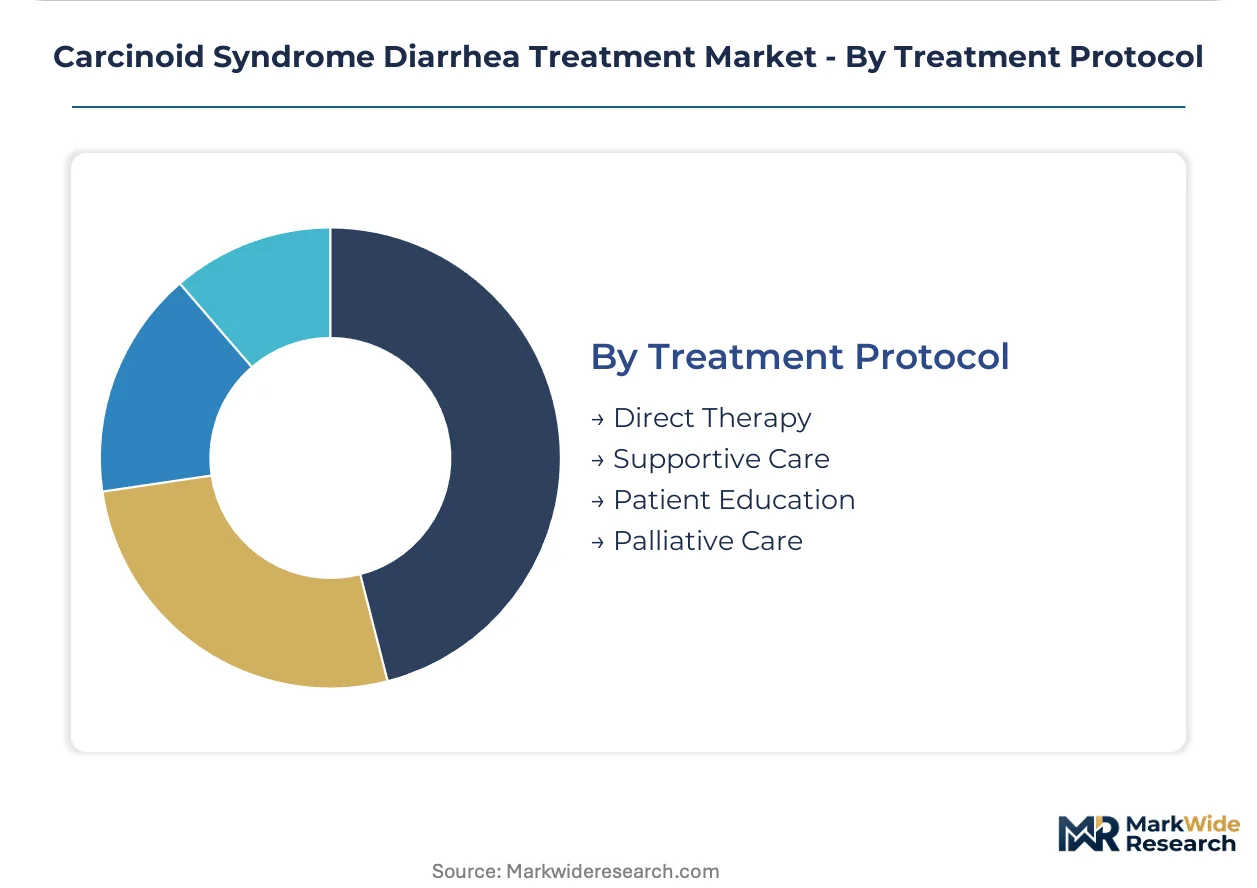
Treatment Protocol:
Customer type differentiation in this category separates curative-intent interventions from chronic management, with palliative protocols commanding distinct reimbursement codes and quality metrics.
- Direct Therapy:Pharmacological intervention targeting tumor hormone secretion as the primary mechanism of symptom control. United States and German prescribing patterns favor this approach for de novo patients with confirmed neuroendocrine tumor burden. Outcomes measurement focuses on bowel movement frequency reduction and biomarker suppression.
- Supportive Care:Adjunctive interventions addressing nutrition, hydration, and electrolyte balance alongside primary therapy. Japanese and French clinical practice integrates this most comprehensively, reflecting broader acceptance of multidisciplinary oncology care models. Reimbursement often fragments across medical and pharmacy benefits.
- Patient Education:Structured programs covering trigger avoidance, symptom recognition, and self-advocacy.
- Palliative Care:Symptom-focused management for advanced disease where disease modification is no longer pursued.
Direct therapy holds the largest share; supportive care is gaining share fastest as value-based contracts reward quality-of-life improvements beyond crude symptom counts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives anchor commercial strategy in the United States, while EMA accelerated pathways and Japanese PMDA frameworks reshape competitive entry timing across developed markets. Peptide manufacturing clusters in Switzerland and Ireland supply active pharmaceutical ingredients to formulation sites in Germany and Japan.
United States
Integrated delivery networks and specialty pharmacy channels concentrate demand for depot somatostatin analog formulations. FDA seven-year orphan drug exclusivity periods protect novel entrants from immediate biosimilar competition. Greater Boston and San Diego biotech clusters host clinical trial operations and peptide synthesis development programs.
Germany
DRG-based hospital reimbursement drives preference for extended-interval dosing that reduces nursing workload. EMA priority medicine pathways compress regulatory review timelines for innovative supportive care agents. Baden-Württemberg pharmaceutical manufacturing corridor specializes in sterile fill-finish capabilities for depot formulations.
Japan
Aging population demographics and homecare reimbursement expansion accelerate patient migration away from infusion centers. PMDA Sakigake designation offers expedited review for oncology supportive care innovations with demonstrated quality-of-life benefits. Kanto region specialty pharmacy networks integrate remote monitoring for self-administered therapy.
Switzerland
Peptide active pharmaceutical ingredient synthesis concentrates in Basel-area chemical manufacturing facilities. Swissmedic regulatory alignment with EMA procedures streamlines parallel market authorization submissions. Alpine region contract manufacturers supply cyclic peptide intermediates to global formulation partners.
United Kingdom
NICE technology appraisals condition reimbursement on demonstrated cost-effectiveness against standard somatostatin analog therapy. MHRA post-Brexit regulatory autonomy enables targeted accelerated assessment for orphan indications. Southeast England clinical research organizations manage multinational carcinoid syndrome trials.
Carcinoid Syndrome Diarrhea Treatment Market Vendor Landscape
Integrated pharmaceutical conglomerates and specialized peptide therapeutics developers split the market between broad oncology portfolios and focused neuroendocrine expertise. Consolidation characterizes the supply side, with three global manufacturers commanding formulation capabilities and distribution infrastructure. Strategic archetypes include vertically integrated API-to-vial operators, bioconjugate technology licensors, and oral small-molecule challengers. Competitive moves center on depot formulation lifecycle extensions and biosimilar defense through device differentiation.
Among Swiss- and French-based integrated operators, Novartis and Ipsen Biopharmaceuticals exemplify the API-to-vial archetype with captive peptide synthesis networks. Lexicon Pharmaceuticals occupies a distinct position as a specialized developer targeting breakthrough symptom control through alternative mechanisms. Teva Pharmaceutical Industries represents the generic and biosimilar entry threat that shapes incumbent pricing and patent strategy.
| Leading Market Players |
|---|
| Lexicon Pharmaceuticals |
| Ipsen Biopharmaceuticals |
| Novartis |
| Teva Pharmaceutical Industries |
| Pharmascience |
| Omega Laboratories |
| Pfizer |
| Hutchison China MediTech |
| Progenics Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Basel-area peptide synthesis clusters anchor global active pharmaceutical ingredient capacity, concentrating manufacturing expertise that translates directly into pricing power for depot formulation suppliers serving United States and German hospital networks.
Pricing Analysis
United States specialty pharmacy channels command 15-25% premiums over German hospital procurement for identical somatostatin analog depot formulations, reflecting reimbursement fragmentation and patient support service bundling. Three-tier pricing structure across premium depot injections, standard subcutaneous vials, and economy-minded oral development candidates stratifies the market by administration convenience and adherence infrastructure. Cost compression in the subcutaneous segment is intensifying as tryptophan hydroxylase inhibitors gain formulary traction for mild-to-moderate cases. Integrated delivery networks exhibit lowest price sensitivity due to outcomes-based contracting, while independent oncology clinics face acute budget pressure from prior authorization delays.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates supply chain risk planning for cyclic peptide intermediates, with customs valuation disputes adding administrative cost layers to already-complex cold-chain logistics. Active pharmaceutical ingredient synthesis concentrates in Switzerland, Ireland, and India, with sterile fill-finish capabilities clustering in Germany and Japan. Manufacturing draws from specialized amino acid precursors, controlled-release polymers, and single-use bioprocessing equipment. Single-source vulnerability pervades the cyclic peptide synthesis equipment tier, where three European vendors control 80% of installed solid-phase reactor capacity. Distribution runs through contracted specialty pharmacy networks with exclusive geographic territories, bypassing traditional wholesale channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where patient adherence monitoring and remote outcome capture expand faster than molecule sales alone, with United States integrated delivery networks already contracting for quality-of-life metric improvements beyond drug acquisition cost.
For Market Incumbents: Insulate depot formulation margins by deepening captive peptide synthesis capabilities in Basel-area facilities, countering biosimilar entry threats from Teva Pharmaceutical Industries and emerging Indian manufacturers. Prioritize FDA device-differentiation filings for next-generation autoinjector platforms that extend exclusivity cliffs beyond orphan drug expiration. Channel control through exclusive specialty pharmacy partnerships remains the critical defensive lever. For New Entrants and Emerging Players: Pursue oral small-molecule development for needle-averse patient segments in United States and German rural markets, where infusion access limitations create addressable white space. Target homecare reimbursement expansion in Japan as the most penetrable geography, leveraging PMDA Sakigake pathway acceleration for quality-of-life endpoints. Lead with direct-to-patient digital therapeutics bundling to circumvent entrenched specialty pharmacy distribution. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bioconjugate platform developers with antibody-peptide fusion pipelines addressing somatostatin analog non-responders. Long-term viability hinges on demonstrating tumor-targeting efficacy beyond hormonal suppression across the 5-10 year development horizon. Acquisition targets should display peptide chemist talent depth and depot formulation IP. The signal to watch is oral bioavailability breakthrough data collapsing injection-dependent treatment paradigms.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III enrollment for oral somatostatin analogs accelerates patient convenience positioning against depot injections. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for tryptophan hydroxylase inhibitors targeting refractory cases. |
| Manufacturing Scale-Up | Swiss and Irish peptide synthesis expansion addresses EPA discharge limit constraints tightening North American capacity. |
| Pipeline Diversification | Antibody-peptide bioconjugate programs extend addressable populations beyond current somatostatin analog responders. |
| Reimbursement Strategy | German DRG alignment and United States value-based contracts reward extended-interval dosing and adherence metric improvements. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Demand-supply-balance framing structured the analytical framework across the projection horizon, with segmentation dimensions spanning treatment line, dosage form, administration route, and regional regulatory cluster. CAGRs were derived from epidemiology-driven patient flow analysis and pricing elasticity modeling, incorporating somatostatin analog biosimilar entry timing and oral small-molecule substitution curves as critical forecast inputs.
Sensitivities concentrate around biosimilar approval velocity, oral formulation bioavailability data, and Japanese homecare reimbursement expansion pace. Forecasts reflect assumptions on patient diagnosis rates, treatment persistence, and pricing erosion trajectories that could materially revise if regulatory pathways accelerate or competitive entry intensifies. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Occupational Medicines Market
Specialty Medicine
Nephroblastoma Therapeutics Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market
Specialty Medicine
Global Chondrosarcoma Market
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Tropical Spastic Paraparesis Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market