
 Amino Acid Metabolism Disorders Treatment Market | 2026-2036
Amino Acid Metabolism Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Amino Acid Metabolism Disorders Treatment Market Intelligence
The expansion of gene therapy platforms for monogenic diseases is narrowing the gap between symptom management and curative treatments for these disorders. This technological shift is reshaping the therapeutic landscape away from lifelong dietary restrictions and toward single-administration solutions. Novartis leverages its deep expertise in cell and gene therapies to advance its pipeline. Takeda Pharmaceutical specializes in rare disease treatments, including metabolic conditions. Meanwhile, Merck sustains its market presence through a diversified portfolio of pharmacological interventions and dietary supplements.
Amino acid metabolism disorders treatment encompasses medical interventions designed to manage inherited conditions where the body cannot properly break down specific amino acids, leading to toxic substance accumulation. These therapies function by replacing deficient enzymes, restricting dietary intake of the problematic amino acid, or correcting the underlying genetic defect. Phenylketonuria treatments dominate the market by disorder classification, driven by widespread newborn screening and established management protocols. Within treatment types, dietary supplements and small molecule therapies constitute the largest segment, though gene therapy is poised for significant future expansion.
Regulatory oversight from bodies like the FDA in the United States and the EMA in Europe critically shapes market access through orphan drug designations and fast-track approval pathways. These incentives encourage investment in therapies for rare conditions that might otherwise be commercially unviable. Compliance with guidelines from Japan's PMDA is also essential for market entry in that key geography. Stakeholder decisions now hinge on navigating complex reimbursement environments for high-cost curative therapies and demonstrating their long-term value over existing standards of care.
Market Dynamics
The primary force reshaping this market is the technological pivot from lifelong symptom management to potentially curative genetic therapies. This shift alters the entire value chain, from R&D focus to long-term patient care models.
Growth Catalysts
- Regulatory Incentives:The FDA's orphan drug designation accelerates development and provides market exclusivity, encouraging investment in treatments for rare conditions like maple syrup urine disease.
- Advanced Diagnostics:Expanded newborn screening panels, mandated in countries like the United States, enable earlier diagnosis, creating a larger addressable patient pool for timely intervention.
- Specialized Infrastructure:The concentration of expertise in dedicated metabolic disorder centers facilitates clinical trials and the adoption of complex new therapies.
Market Restraints
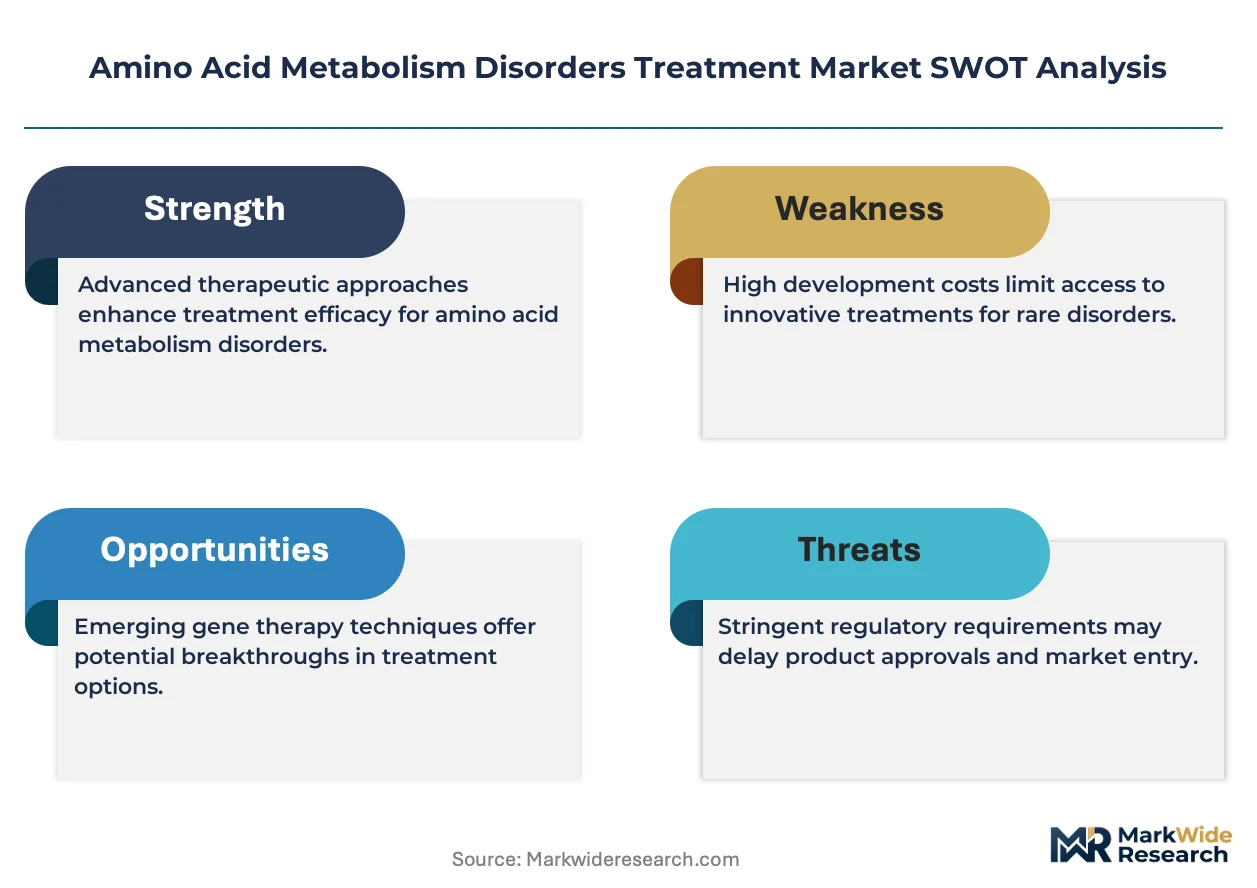
- Prohibitive Treatment Costs:The high upfront cost of novel gene therapies creates significant reimbursement hurdles and limits patient access, particularly outside of well-funded healthcare systems.
- Technical Durability Concerns:Questions surrounding the long-term durability and potential off-target effects of gene therapies represent a key technical barrier for developers and regulators.
- Complex Reimbursement Models:Payers in the US and Europe struggle to adapt traditional reimbursement frameworks to high-cost curative treatments, causing delays in patient access.
Strategic Opportunities
- Geographic Expansion:Introducing newborn screening and treatment infrastructure in large, underserved markets in Asia and Latin America presents a significant opportunity for growth.
- Technology Convergence:Integrating CRISPR-based gene editing with mRNA delivery platforms could yield more precise treatments for a wider range of aminoacidopathies beyond Phenylketonuria.
- Regulatory Harmonization:International efforts to harmonize clinical trial requirements for rare diseases could reduce development costs and speed market entry across the EU and Japan.
Industry Challenges
- Specialized Talent Scarcity:A global shortage of metabolic geneticists and genetic counselors creates bottlenecks in diagnosis, patient management, and the deployment of advanced therapies.
- Manufacturing Scalability:Scaling up GMP-compliant manufacturing for viral vectors and other gene therapy components is a significant capital and technical challenge for biopharmaceutical companies.
- Long-Term Data Collection:Establishing patient registries to track the long-term safety and efficacy of curative therapies is a complex logistical and financial burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Amino Acid Metabolism Disorders Treatment Market |
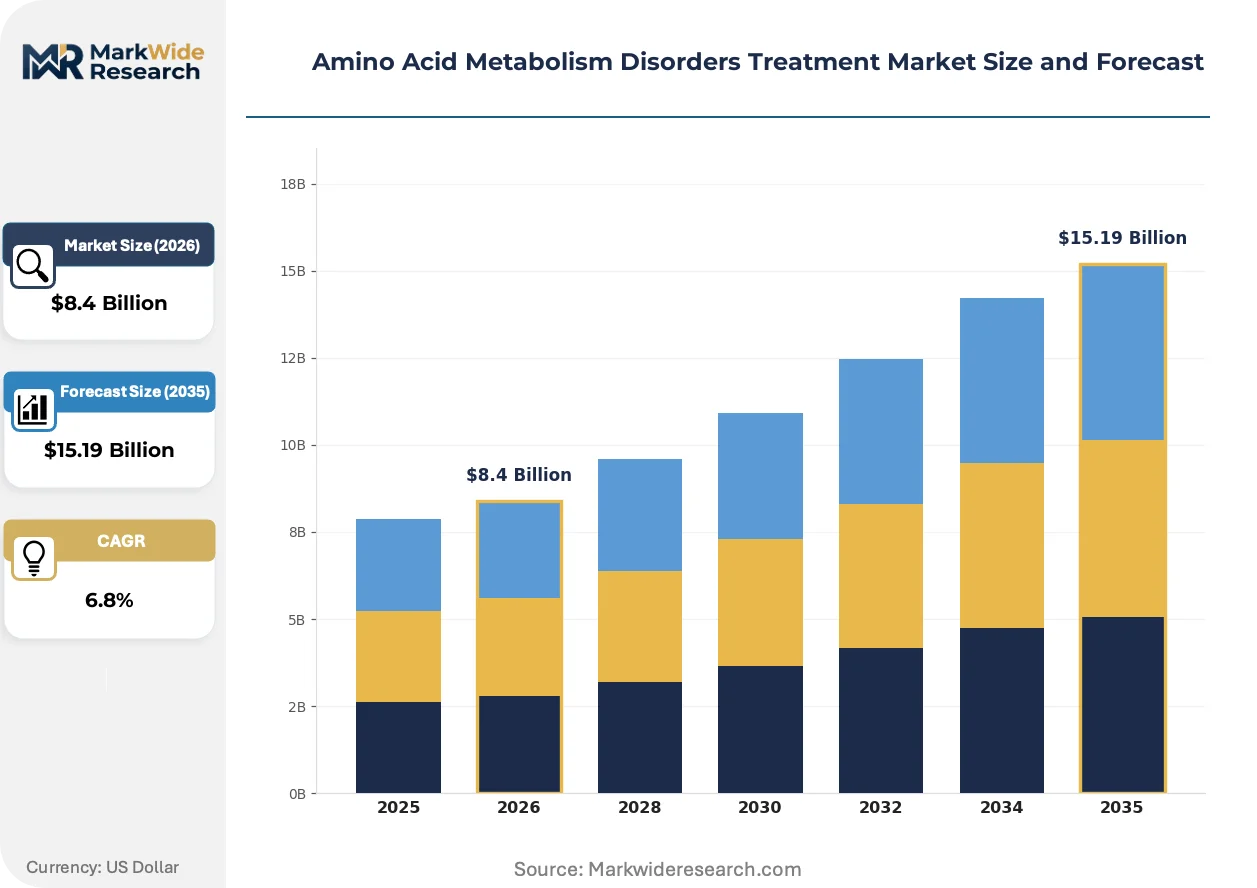
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Enzyme Replacement Therapy, Dietary Supplements, Gene Therapy, Pharmacological Chaperones, Small Molecule Therapy Disorder Classification: Phenylketonuria, Maple Syrup Urine Disease, Homocystinuria, Tyrosinemia, Citrullinemia Care Setting: Specialty Clinics, Genetic Counseling Centers, Pediatric Units, Metabolic Disorder Centers, Home Healthcare Patient Age Group: Neonates, Infants, Adolescents, Adults, Geriatrics |
| Companies Covered | Merck, Novartis, Takeda Pharmaceutical, AstraZeneca, Boehringer Ingelheim, AMINO GmbH, Civentichem, Koninklijke DSM, Kyowa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Amino Acid Metabolism Disorders Treatment Market Strategic Shifts & Innovations
A fundamental transition from chronic disease management to curative intervention defines the therapeutic landscape. This evolution is driven by genetic medicine breakthroughs and shifts in how regulators and payers assess value for these novel treatments.
Single-administration gene therapies using adeno-associated virus (AAV) vectors deliver a functional copy of a missing gene. Specialized metabolic disorder centers are incorporating these therapies into clinical trials and early access programs. This advance is collapsing the treatment paradigm from lifelong dietary management into a single intervention.
The European Medicines Agency's (EMA) PRIority MEdicines (PRIME) scheme offers enhanced regulatory support to developers. This policy accelerates the assessment of promising therapies for rare diseases with no other treatment options. Developers of novel treatments for tyrosinemia are most affected, gaining a more direct route to EU market authorization.
Value-based reimbursement models are gaining traction over traditional fee-for-service payments for high-cost therapies. This shift disrupts conventional pricing, forcing manufacturers to demonstrate long-term clinical and economic value. Implementation of these models is most advanced in healthcare systems in Germany and the United States.
Amino Acid Metabolism Disorders Treatment Market Segmentation
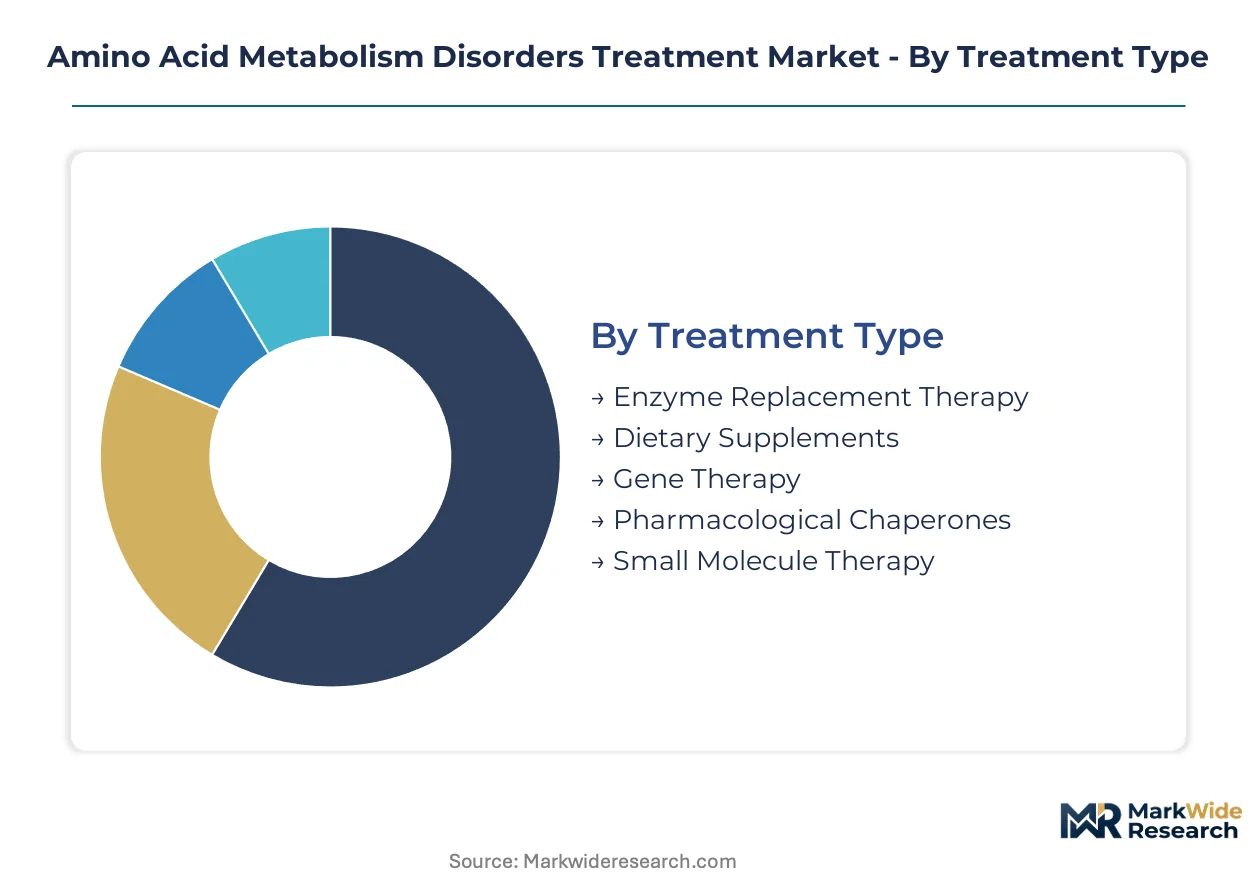
Understanding the segmentation of the amino acid metabolism disorders treatment market is crucial for identifying distinct patient needs and therapeutic approaches. This analysis delineates the market by treatment type, specific disorder classifications, the settings where care is delivered, and the age groups of patients requiring intervention.
Treatment Type:
The after-sales service intensity for amino acid metabolism disorder treatments varies significantly across different therapeutic modalities.
- Gene Therapy:These advanced interventions introduce functional genetic material into a patient's cells to correct underlying genetic defects. Demand for these single-administration solutions is concentrating in specialized metabolic disorder centers in the United States, driven by their potential for curative outcomes.
- Dietary Supplements:These include specialized medical foods, amino acid formulas, and vitamin cofactors designed to manage metabolic imbalances. Demand remains high across all geographies, particularly in Germany, due to established management protocols and widespread patient adherence.
- Enzyme Replacement Therapy:This therapy provides exogenous enzymes to compensate for deficient or absent endogenous enzymes, preventing toxic metabolite accumulation.
- Pharmacological Chaperones:Small molecules that bind to and stabilize misfolded proteins, helping them achieve correct conformation and function within the body.
- Small Molecule Therapy:These orally administered or injectable drugs target specific pathways or receptors to alleviate symptoms or correct metabolic imbalances.
By volume, Dietary Supplements leads. By growth pace, Gene Therapy is ahead.
Disorder Classification:
Disorder classification directly influences the application scope and prevalence of specific treatment protocols.
- Phenylketonuria:An inherited disorder characterized by the inability to metabolize phenylalanine, leading to its accumulation and neurological damage. Treatments for Phenylketonuria dominate the market across the United States, propelled by universal newborn screening programs and established clinical guidelines.
- Tyrosinemia:A group of genetic disorders impairing the body's ability to break down tyrosine, resulting in liver and kidney damage. Novel treatment development for Tyrosinemia is accelerating in Europe, supported by regulatory incentives like the EMA's PRIME scheme.
- Maple Syrup Urine Disease:A rare genetic disorder preventing the body from processing certain amino acids, requiring strict dietary management.
- Homocystinuria:A metabolic disorder caused by the body's inability to process methionine, leading to various systemic complications.
- Citrullinemia:A urea cycle disorder characterized by high levels of ammonia and citrulline in the blood, requiring urgent intervention.
Phenylketonuria treatments hold the largest share of therapeutic interventions, while Tyrosinemia therapies are experiencing rapid expansion.
Care Setting:
The specialization of care settings dictates the type and complexity of interventions available to patients.
- Metabolic Disorder Centers:Highly specialized facilities offering multidisciplinary care, advanced diagnostics, and access to novel therapies for complex metabolic conditions. These centers attract significant investment in countries like Germany, supporting clinical trials and the deployment of gene therapies.
- Pediatric Units:Dedicated hospital departments providing specialized medical care for infants, children, and adolescents with inherited metabolic disorders. Growth in these units is prominent in countries with robust healthcare infrastructure, facilitating early diagnosis and intervention.
- Specialty Clinics:Outpatient facilities focusing on specific aspects of metabolic disorder management, offering ongoing monitoring and dietary guidance.
- Genetic Counseling Centers:Provide risk assessment, diagnostic testing interpretation, and support for families affected by genetic conditions.
- Home Healthcare:Delivers medical services and support directly to patients' homes, managing chronic conditions and reducing hospital visits.
Metabolic Disorder Centers serve as operational hubs for complex therapies, whereas Home Healthcare expands access for routine management.
Patient Age Group:
Patient age group reflects the maturity of diagnostic pathways and the urgency of therapeutic intervention.
- Neonates:Newborn infants, typically within the first 28 days of life, represent a critical window for early diagnosis and intervention for metabolic disorders. Early screening programs in the United States detect conditions like Phenylketonuria in this age group, enabling timely treatment.
- Infants:Patients from one month to one year old, often requiring specialized nutritional management and close monitoring for inherited metabolic conditions. Therapeutic interventions for infants are expanding in regions with advanced healthcare systems, preventing long-term developmental issues.
- Adolescents:Individuals aged 13 to 19, navigating the transition from pediatric to adult care while managing their chronic metabolic disorders.
- Adults:Patients over 19 years old, requiring lifelong management of their amino acid metabolism disorders, often with complex dietary and pharmacological regimens.
- Geriatrics:Elderly patients, whose metabolic disorder management may be complicated by age-related comorbidities and polypharmacy.
Neonates represent a critical intervention window due to early screening, while Adults require sustained management for chronic conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for amino acid metabolism disorder treatments concentrates in regions with established healthcare systems and proactive screening programs. Specialized pediatric units and metabolic disorder centers across developed economies drive the adoption of advanced therapies. These regions possess the infrastructure necessary for early diagnosis and complex intervention.
United States
The United States market is propelled by widespread newborn screening panels, mandated across all states, enabling early detection of conditions like Phenylketonuria. The FDA's orphan drug designation accelerates novel treatment development. Boston and San Francisco Bay Area biopharma clusters are hubs for gene therapy research.
Germany
Germany exhibits strong demand, supported by its robust healthcare infrastructure and high patient adherence to established management protocols. Value-based reimbursement models are gaining traction within German healthcare systems, influencing market access for high-cost therapies. Munich and Berlin serve as key centers for metabolic disorder research.
Japan
Japan's market expansion is influenced by comprehensive newborn screening initiatives and a focus on rare disease research. Compliance with guidelines from the PMDA is essential for market entry, ensuring high standards for novel treatments. The Tokyo metropolitan area hosts numerous pharmaceutical companies and research institutions.
United Kingdom
United Kingdom demand is sustained by the National Health Service (NHS) prioritizing rare disease management. Regulatory incentives from the European Medicines Agency (EMA) influence UK market access for many therapies. London's biomedical research campuses contribute significantly to genetic therapy development.
Brazil
Brazil represents an underserved market with significant growth potential, particularly with the expansion of newborn screening programs. ANVISA, the national health surveillance agency, regulates drug approvals for specialized treatments. São Paulo and Rio de Janeiro are developing specialized clinics and research initiatives.
Amino Acid Metabolism Disorders Treatment Market Key Industry Players
Channel-controlling players compete with product-specialist players across the amino acid metabolism disorders treatment market. The market structure is tiered, featuring large pharmaceutical companies alongside niche biotechnology firms and specialized medical food providers. Strategic archetypes include gene therapy innovators, rare disease specialists, and diversified pharmacological solution providers. Companies engage in significant R&D focus on novel therapies and form strategic partnerships to advance complex treatment platforms and expand their geographic reach.
Specialists in cell and gene therapies, such as Novartis, exemplify the market's shift towards single-administration solutions for monogenic diseases, leveraging advanced technological platforms. Takeda Pharmaceutical occupies a position as a dedicated rare disease treatment provider, focusing on a broad spectrum of metabolic conditions that require specialized interventions. Meanwhile, Merck sustains its market presence through a diversified portfolio, encompassing both pharmacological interventions and dietary supplements, representing a broader approach to patient management across various stages of disease progression.
| Leading Market Players |
|---|
| Merck |
| Novartis |
| Takeda Pharmaceutical |
| AstraZeneca |
| Boehringer Ingelheim |
| AMINO GmbH |
| Civentichem |
| Koninklijke DSM |
| Kyowa |
| Others |
Cost & Logistics Intelligence
Upstream concentration in specialized gene therapy manufacturing capabilities, often found in biopharma clusters, directly influences the premium margin pools captured by innovators downstream. This dynamic impacts the accessibility of high-cost curative treatments.
Pricing Analysis
Value-based reimbursement models, often tied to long-term patient outcomes or clinical milestones, are increasingly defining the pricing landscape for novel amino acid metabolism disorder treatments. Price differentiation stems from demonstrated clinical efficacy and the rarity of the specific disorder, often supported by orphan drug designations. Pricing pressure stems from stringent payer budget constraints in systems like the NHS, challenging access for high-cost therapies. Payers and national health systems represent the most price-sensitive buyers, while patients with no alternative options exhibit lower price sensitivity.
Supply Chain Analysis
Specialized contract development and manufacturing organizations (CDMOs) with expertise in viral vector production, primarily located in US biopharma hubs and select European centers, hold significant capacity for gene therapy components. Geographic supply concentration for key inputs like modified amino acids and enzymes is found in countries such as Germany and Japan. Manufacturing scalability for complex biologicals represents a structural supply chain risk. Distribution runs through highly specialized cold chain logistics networks, directly to metabolic disorder centers and pediatric units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The amino acid metabolism disorders treatment market is defined by a scarcity of highly specialized clinical and manufacturing expertise, particularly concerning advanced genetic therapies. This capability gap creates significant bottlenecks in patient access and therapeutic development.
For Market Incumbents: Entrench market leadership by accelerating R&D investments into next-generation gene editing platforms and acquiring niche biotechs with validated early-stage assets. Strategic partnerships with specialized metabolic disorder centers can secure access to patient cohorts and clinical trial infrastructure. This defends against emerging gene therapy innovators and evolving reimbursement models. Capacity addition in GMP-compliant viral vector manufacturing can reduce reliance on external suppliers.
For New Entrants and Emerging Players: Establish a beachhead in ultra-rare aminoacidopathies where existing treatment options are limited or non-existent, leveraging orphan drug designations for accelerated regulatory pathways. Targeted geographic expansion into underserved markets in Asia and Latin America, coupled with local partnership models, presents white-space opportunities. The most penetrable segment involves early-stage gene therapy development for conditions lacking any approved therapy. A go-to-market angle focusing on comprehensive patient support programs can differentiate offerings.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with biopharmaceutical firms specializing in rare disease R&D, offering attractive targets for strategic acquisitions over a five-to-ten-year window. Investors should target companies with robust gene therapy pipelines or advanced diagnostic platforms for early disease detection. Long-term viability hinges on successful clinical validation and favorable reimbursement policy evolution for curative treatments. The signal to watch is the consistent demonstration of long-term durability and safety data for approved gene therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates novel gene therapy candidates through pivotal studies for rare metabolic disorders. |
| Manufacturing Scale-Up | Ensures commercial readiness and broad patient access for high-demand, complex biological treatments. |
| Licensing Agreement | Expands therapeutic portfolios and technology access for specific enzyme replacement or gene therapies. |
| Geographic Expansion | Reaches underserved patient populations in emerging markets with advanced screening programs. |
| Regulatory Approval Pathway | Secures market authorization and orphan drug status for specialized amino acid metabolism interventions. |
Research Approach
The analysis maps gene therapy, dietary supplements, and enzyme replacement therapy sub-sectors, each validated through extensive primary interviews with metabolic geneticists, pharmaceutical R&D leads, and payer reimbursement specialists. This approach combines insights from these industry stakeholders with rigorous secondary validation. Secondary sources include FDA filings, EMA submissions, clinical trial registries, and healthcare expenditure reports, triangulating data both bottom-up and top-down to ensure accuracy.
The forecast framework held regulatory approval timelines and newborn screening expansion rates as fixed conditions, while varying gene therapy adoption curves across the analysis window. The model segmented demand by treatment type, disorder classification, care setting, patient age group, and regional adoption patterns. Compound annual growth rates were derived from historical trends, pipeline analysis, and expert consensus. Key forecast inputs included orphan drug designations and gene therapy clinical trial success rates.
Stress conditions across gene therapy durability and reimbursement policy shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, acknowledging that unforeseen adverse events for novel therapies or significant changes in healthcare funding could revise projections. Quarterly review of regulatory approvals and payer coverage decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Iron Deficiency Anemia Therapy Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Selectin Blocker Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
Hemorrhagic Stroke Treatment Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Hemangioma Market