
 Focal Segmental Glomerulosclerosis (FSGS) Treatment Market | 2026-2036
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market Foresight
Specialty clinics is broadening as a preferred care setting for FSGS patients, diverting volume from traditional hospital admissions. Travere Therapeutics anchors its position through deep specialization in rare kidney disease portfolios. Novartis leverages its immunology infrastructure to compete across nephrology and autoimmune intersections. Pfizer sustains manufacturing scale that supports consistent supply of corticosteroid and immunosuppressant formulations.
Focal Segmental Glomerulosclerosis constitutes a progressive scarring pattern affecting discrete portions of kidney glomeruli, characterized by segmental capillary loop collapse, podocyte depletion, and matrix accumulation visible on light microscopy with confirmation by electron microscopy. Its primary clinical purpose centers on preserving residual renal function and delaying progression to end-stage kidney disease through proteinuria reduction and immunomodulation. Immunosuppressants occupy the dominant revenue pool given their chronic administration profile and high cost structure, while ACE inhibitors represent a mature, high-volume maintenance segment with thinner margins. Subcutaneous delivery is gaining fastest traction as home administration protocols reduce infusion center dependency.
The FDA's accelerated approval framework and the EMA's orphan drug incentives jointly shape clinical trial design and market access timelines for novel FSGS therapeutics. The EU's MDR requirements impose stricter post-market surveillance obligations on device-drug combination products used in renal care. Stakeholders must monitor how evolving podocyte-targeted mechanisms perform against existing immunosuppressive standards to determine portfolio prioritization and partnership strategies.
Market Dynamics
The FDA's accelerated approval pathway for rare kidney diseases is compressing clinical trial timelines and redirecting R&D investment toward podocyte-targeted mechanisms, forcing developers to restructure evidence-generation strategies around surrogate endpoints.
Growth Catalysts
- Orphan Drug Incentives:The EMA's orphan designation framework grants protocol assistance and fee reductions, encouraging sponsors to pursue FSGS indications despite small addressable populations.
- Biopsy-Integrated Diagnostics:Digital pathology platforms embedding machine learning classifiers are shortening time-to-diagnosis and expanding treatable patient identification.
- Home Administration Protocols:Subcutaneous delivery systems are reducing infusion center dependency and unlocking patient volume in rural and underserved catchment areas.
Market Restraints
- Biologic Manufacturing Concentration:Contract development and manufacturing organizations in Switzerland and Ireland control critical fill-finish capacity for monoclonal antibodies, creating single-source vulnerability.
- Reimbursement Compression:Medicare's bundled payment models for end-stage kidney disease are constraining margins on immunosuppressive maintenance therapy.
- Diagnostic Fragmentation:Heterogeneous biopsy interpretation standards across pathology networks generate false-negative rates that delay treatment initiation.
Strategic Opportunities
- Pediatric Formulation Gaps:The absence of approved therapies for steroid-resistant FSGS in patients under 18 creates first-mover advantage for sponsors with juvenile study data.
- Companion Diagnostic Integration:FDA-cleared assays identifying APOL1 high-risk genotypes could segment populations and support targeted therapy labels.
- Direct-to-Patient Channels:Specialty pharmacy distribution bypassing hospital outpatient departments is capturing margin and adherence data simultaneously.
Industry Challenges
- Nephrology Workforce Constraints:Fellowship program graduation rates are failing to match incident chronic kidney disease prevalence, stretching specialist availability for complex FSGS management.
- Endpoint Validation Delays:Proteinuria reduction as a surrogate for clinical benefit requires prolonged follow-up studies that extend capital lock-up periods for development-stage assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Focal Segmental Glomerulosclerosis (FSGS) Treatment Market |
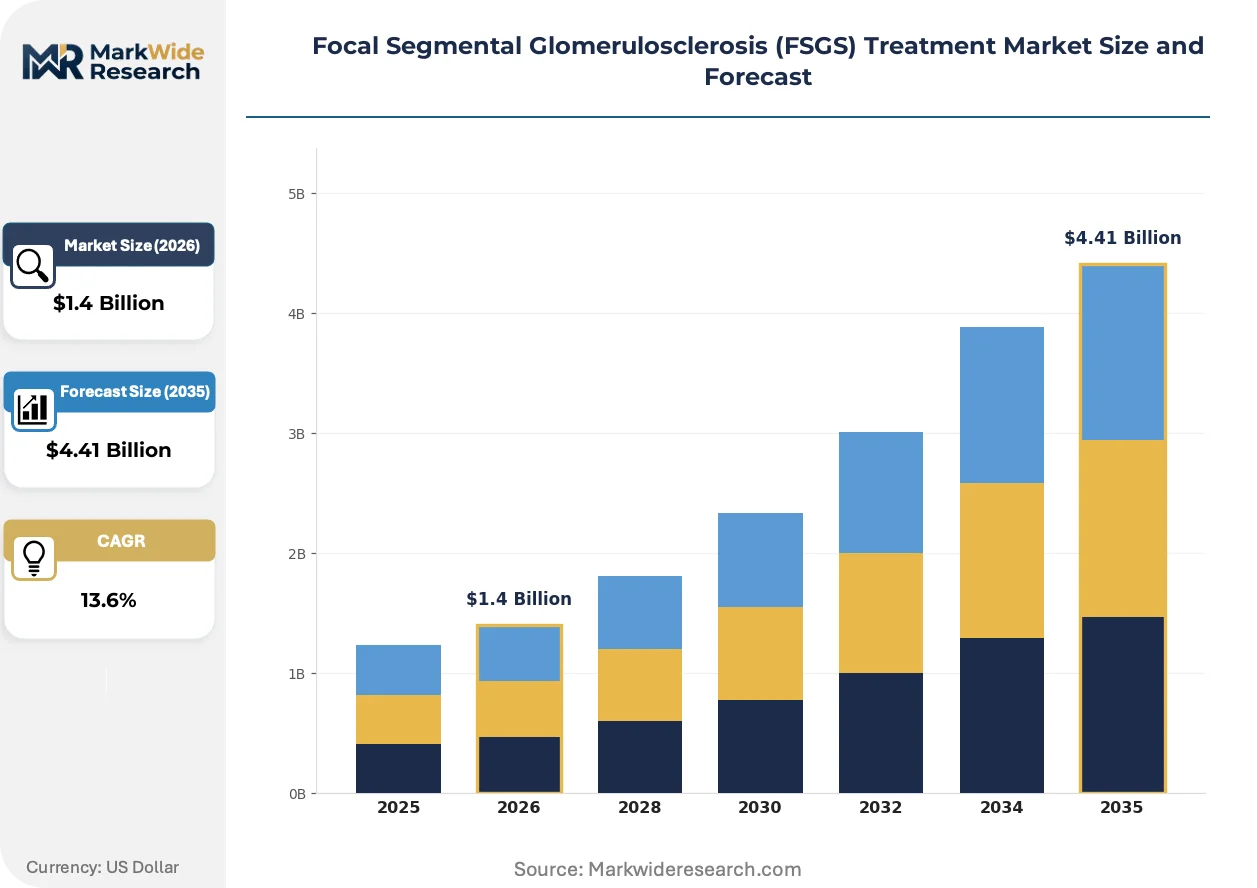
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Steroids, Antihypertensives, ACE Inhibitors Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Therapy Area: Kidney Disorders, Autoimmune Diseases, Inflammatory Conditions, Renal Replacement Therapy |
| Companies Covered | Travere Therapeutics Inc., Merck & Co., Inc., Novartis AG, Bristol-Myers Squibb, GlaxoSmithKline plc, Pfizer Inc., Astellas Pharma Inc., AstraZeneca, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market Shifts & Advancements
Podocyte biology is emerging as the central design target for next-generation therapeutics, displacing the historical dominance of broad immunosuppression and enabling mechanism-based patient stratification.
Sphingosine-1-phosphate receptor modulators are overtaking calcineurin inhibitors in investigator-sponsored trials for steroid-resistant cases. Academic medical centers in the United States and Germany are adopting these agents in combination protocols. The shift is compressing addressable volume for tacrolimus and cyclosporine while expanding the reimbursed biologic category.
The EU's Medical Device Regulation is imposing new clinical evidence requirements on wearable renal monitoring systems used in home-based FSGS management. Manufacturers must now submit prospective safety data for software-as-medical-device classifications. German notified bodies are processing these submissions with 18-month backlogs, delaying market entry for continuous creatinine clearance trackers.
Patients with FSGS are consolidating care at multi-specialty nephrology networks that integrate pharmacy, nutrition, and clinical trial access under single tax identifiers. These vertically organized centers are displacing community-based nephrology practices in metropolitan areas. The concentration is most pronounced in the United States, where vertical integration with dialysis providers creates captive referral pathways.
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market Segmentation
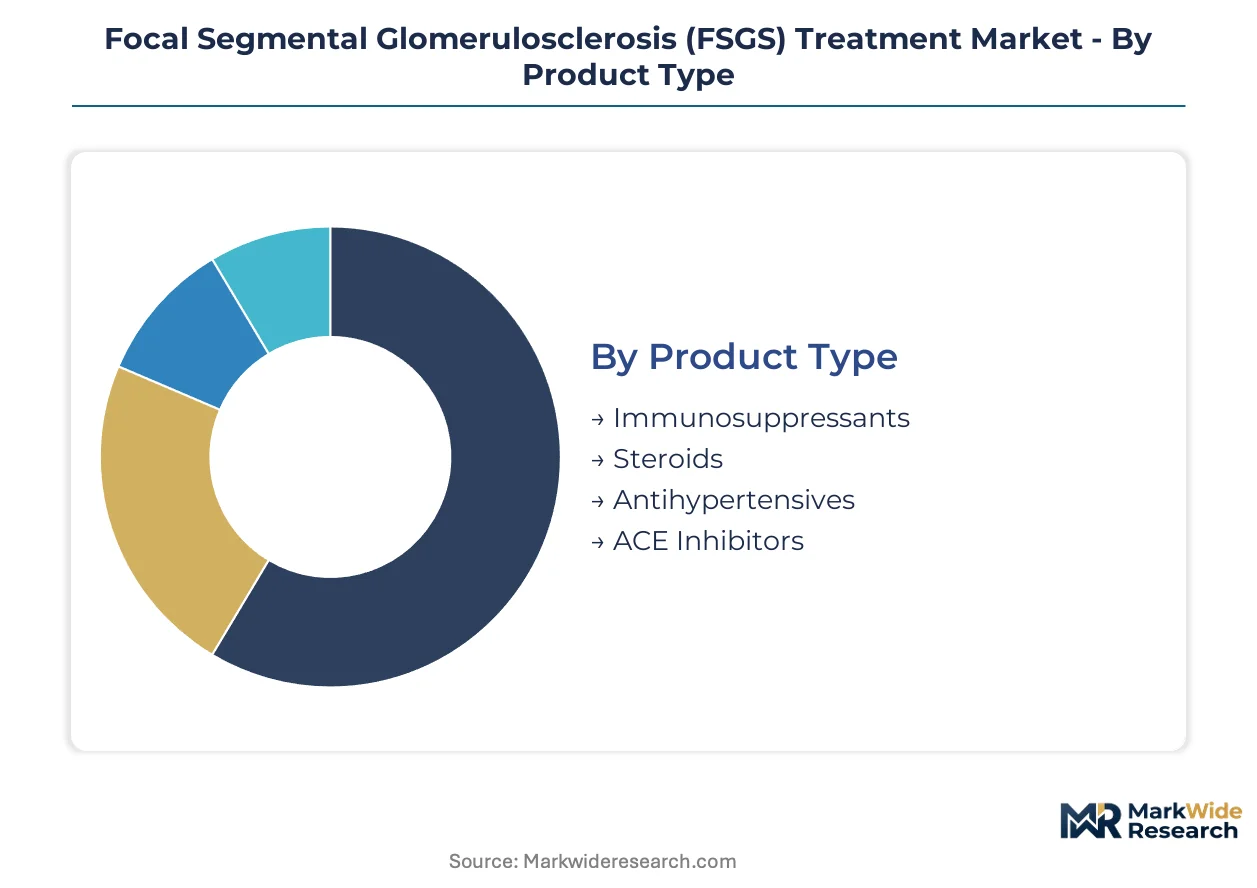
FSGS treatment markets fragment across therapeutic mechanism, administration route, and care setting. Each dimension carries distinct margin profiles and capital requirements that shape portfolio allocation decisions.
Product Type:
Capital intensity varies sharply across therapeutic classes, with biologic manufacturing demanding the heaviest upfront investment.
- Immunosuppressants:Monoclonal antibodies and calcineurin inhibitors require dedicated bioreactor capacity and cold-chain infrastructure. Demand concentrates in the United States where prior authorization pathways favor high-cost biologics over generic alternatives.
- Steroids:Corticosteroid formulations operate on thin margins with commoditized active pharmaceutical ingredients. Prednisone and methylprednisolone remain first-line protocols in Medicare-covered populations despite inferior long-term renal outcomes.
- Antihypertensives:Generic ARBs and calcium channel blockers serve proteinuria reduction adjunctively.
- ACE Inhibitors:Lisinopril and enalapril dominate maintenance therapy with established renal protective labeling.
Most installed capacity flows through Immunosuppressants. Expansion is steepest in this same segment as podocyte-targeted mechanisms displace older standards.
Delivery Mode:
Route selection determines reimbursement tier and patient compliance economics.
- Subcutaneous:Prefilled syringes and autoinjector platforms enable home administration without infusion center overhead. Adoption is accelerating in Germany and the United States where specialty pharmacy networks manage distribution.
- Oral:Tablets and capsules retain volume leadership through convenience and formulary inclusion. Medicare Part D coverage drives prescribing patterns for maintenance immunosuppression.
- Intravenous:Hospital outpatient departments bill under bundled payment models that compress margins.
- Intramuscular:Depot formulations serve niche populations with adherence challenges.
Volume leadership remains with Oral administration. Subcutaneous delivery is climbing the fastest as home-based protocols expand addressable geography.
End User:
Site-of-care economics are shifting patient volume toward lower-acuity settings.
- Specialty Clinics:Dedicated nephrology centers integrate biopsy services, infusion suites, and clinical trial access under single tax identifiers. These facilities capture complex FSGS cases in metropolitan United States markets.
- Hospitals:Academic medical centers retain diagnostic authority for ambiguous cases requiring electron microscopy confirmation.
- Homecare Settings:Subcutaneous administration protocols are unlocking rural patient populations previously dependent on urban infusion centers.
- Research Institutions:Academic sites conduct the bulk of investigator-sponsored trials for steroid-resistant variants.
Patient volume is consolidating fastest at Specialty Clinics. Hospitals retain authority for diagnostic confirmation.
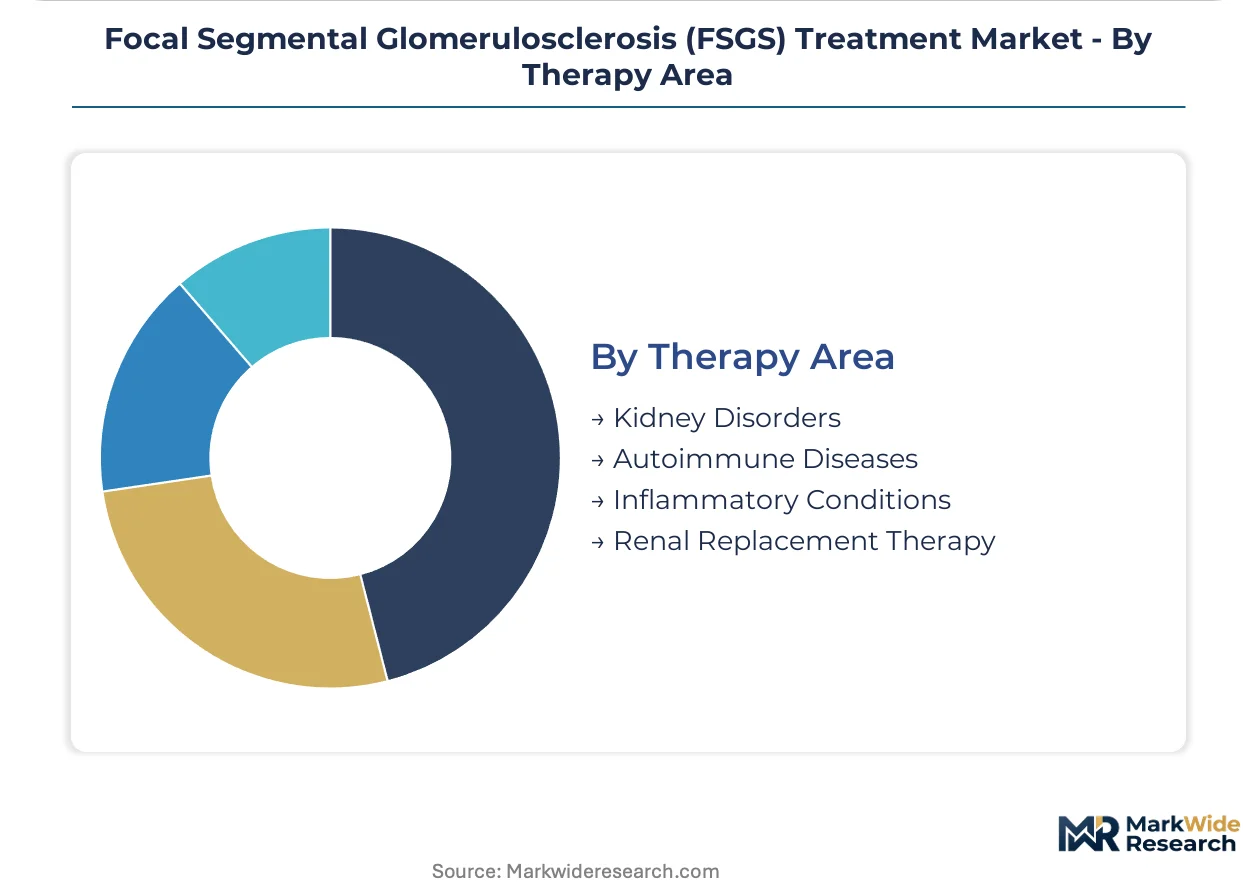
Therapy Area:
Indication breadth determines addressable population and regulatory pathway efficiency.
- Kidney Disorders:Primary FSGS and secondary forms drive the core revenue pool with well-defined biopsy criteria and established surrogate endpoints.
- Autoimmune Diseases:Lupus nephritis overlap creates portfolio synergy for immunology-focused developers.
- Inflammatory Conditions:Podocyte-targeted mechanisms may extend to broader proteinuric diseases.
- Renal Replacement Therapy:Dialysis-dependent populations represent salvage therapy indications with compressed development timelines.
Clinical development concentrates in Kidney Disorders. Autoimmune Diseases offer the steepest label expansion trajectory for mechanism-based assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biopharma corridor anchors FSGS therapeutic development through concentrated nephrology research infrastructure and proximity to FDA headquarters. Clinical trial density and prior authorization pathways concentrate patient access in metropolitan medical centers. Reimbursement frameworks and orphan drug policies diverge sharply across national boundaries.
United States
Academic medical centers in Boston, New York, and San Francisco drive investigator-sponsored trials for steroid-resistant variants. The FDA's accelerated approval pathway compresses development timelines for podocyte-targeted mechanisms. Philadelphia's specialty pharmacy networks manage distribution for subcutaneous biologics, reducing infusion center dependency in rural catchment areas.
Germany
Heidelberg and Berlin university hospitals anchor European biopsy-integrated diagnostic adoption with embedded digital pathology platforms. The EMA's orphan designation framework grants protocol assistance and fee reductions for pediatric formulation development. Munich-based specialty clinics consolidate complex nephrology cases from Central European referral networks.
Japan
Tokyo and Osaka metropolitan areas concentrate dialysis-dependent populations eligible for salvage therapy trials. PMDA consultations for rare kidney diseases align with global surrogate endpoint standards. Yokohama's clinical research organizations manage multicenter protocols across East Asian sites.
Switzerland
Basel's immunology research infrastructure supports mechanism-based patient stratification for next-generation therapeutics. Swissmedic's parallel scientific advice with EMA streamlines regulatory submissions for podocyte-targeted assets. Zurich's contract development organizations control critical fill-finish capacity for monoclonal antibodies.
United Kingdom
London's nephrology networks integrate clinical trial access with National Health Service treatment pathways. The MHRA's reliance on EMA assessments for orphan indications accelerates market access timelines. Manchester's specialty clinics capture proteinuric disease cases from Northern England referral basins.
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek podocyte biology expertise and manufacturing scale. The market structures around three tiers: integrated pharmaceutical conglomerates with immunology infrastructure, rare disease specialists with nephrology focus, and generic manufacturers supplying maintenance corticosteroids. Two competitive moves define positioning: licensing agreements for novel mechanisms and captive supply arrangements for biologic fill-finish capacity.
Among rare disease specialists, Travere Therapeutics Inc. exemplifies deep nephrology portfolio concentration. Novartis AG and Pfizer Inc. occupy positions at the scale-driven end, leveraging immunology infrastructure and manufacturing capacity respectively. These three anchors represent distinct strategic archetypes: mechanism-focused development, diversified immunology platforms, and supply-secured maintenance therapy.
| Leading Market Players |
|---|
| Travere Therapeutics Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| Bristol-Myers Squibb |
| GlaxoSmithKline plc |
| Pfizer Inc. |
| Astellas Pharma Inc. |
| AstraZeneca |
| Roche |
| Others |
Supply & Pricing Matrix
Bioreactor-grade media and single-use consumables flow from Swiss and Irish contract manufacturers through specialty pharmacy networks, with cold-chain logistics costs layering into final reimbursed prices for podocyte-targeted biologics.
Pricing Analysis
Specialty pharmacy margins absorb the steepest channel markup in the FSGS treatment value chain, with distributor spreads widening for temperature-controlled monoclonal antibodies. Three-tier pricing structure across premium biologics, standard immunosuppressants, and economy corticosteroid generics reflects reimbursement tiering and manufacturing complexity. Cost compression in the steroid segment is intensifying because Medicare bundled payments cap outpatient department reimbursement. Community nephrology practices exhibit the highest price sensitivity, while academic medical centers prioritize mechanism novelty over acquisition cost.
Supply Chain Analysis
Fill-finish capacity for monoclonal antibodies rests on Swiss and Irish contract development and manufacturing organizations, with active pharmaceutical ingredient synthesis concentrated in India and China. Critical inputs include recombinant protein media, chromatography resins, and single-use bioreactor bags. Single-source vulnerability concentrates in Basel and Zurich fill-finish sites, where regulatory inspection backlogs create queue risk. Distribution runs through specialty pharmacy networks that bypass hospital outpatient departments, capturing patient adherence data alongside margin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FSGS treatment market compounds steadily as orphan drug incentives sustain R&D investment despite small addressable populations, with podocyte biology advances expanding the treatable patient base.
For Market Incumbents: Deepen captive supply arrangements for bioreactor capacity in Switzerland and Ireland before queue times extend further. Secure FDA-cleared companion diagnostic partnerships to segment APOL1 high-risk populations and defend against mechanism-based competition from sphingosine-1-phosphate receptor modulators. For New Entrants and Emerging Players: Launch via direct-to-patient specialty pharmacy channels to bypass saturated hospital outpatient departments and capture adherence data. Target pediatric formulation gaps in steroid-resistant FSGS, where regulatory pathways offer protocol assistance and fee reductions under EMA orphan designation frameworks. For Investors and Strategic Acquirers: Consolidation pressure builds where nephrology workforce constraints stretch specialist availability and vertical integration with dialysis providers creates captive referral pathways. The most attractive acquisition targets are rare disease specialists with deep biopsy-integrated diagnostic relationships and investigator-sponsored trial infrastructure. Watch FDA accelerated approval decisions for podocyte-targeted mechanisms as the signal for portfolio repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Surrogate endpoint validation for proteinuria reduction compresses capital lock-up periods for development-stage assets. |
| Regulatory Approval Pathway | FDA accelerated approval for rare kidney diseases redirects R&D investment toward podocyte-targeted mechanisms. |
| Licensing Agreement | Mechanism-focused developers source podocyte biology expertise from academic medical centers in Boston and Heidelberg. |
| Manufacturing Scale-Up | Bioreactor capacity expansion in Switzerland reduces single-source vulnerability for monoclonal antibody fill-finish. |
| Pipeline Diversification | Autoimmune disease label extensions for lupus nephritis create portfolio synergy for immunology-focused developers. |
Research Methodology
Coverage spans the United States, Germany, Japan, Switzerland, and the United Kingdom, with primary inputs from each market's nephrology research infrastructure. Drug development executives, regulatory affairs leads, formulary directors, and payer access specialists provided qualitative inputs through structured interviews. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare data. Bottom-up patient volume estimates and top-down reimbursement flow analysis were triangulated against manufacturer-reported revenue patterns.
Granularity-level modeling treated therapeutic mechanism, administration route, and care setting as independent dimensions with distinct margin profiles. Treatment line, dosage form, patient population, and regional regulatory cluster were modeled at the segment level. CAGRs were derived from slope analysis across the projection horizon, with growth rate assumptions calibrated to biopsy-diagnosed incidence trends and prior authorization approval rates for biologic therapies.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Medicare reimbursement compression scenarios and nephrology workforce contraction. Forecasts reflect assumptions about surrogate endpoint acceptance and orphan drug incentive continuity. Regulatory inspection backlogs at Swissmedic and shifting podocyte-targeted mechanism performance against immunosuppressive standards warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Gingivostomatitis Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Middle East and Africa Primary Angle-Closure Glaucoma Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Hepatic Insufficiency/Liver Failure Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market