
 Bleeding Disorders Treatment Market | 2026-2036
Bleeding Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Bleeding Disorders Treatment Market Intelligence
Specialized expertise in hematology and genetic counseling is bifurcating the market between advanced gene therapies and traditional factor replacement treatments. Takeda Pharmaceutical Company Limited sustains a strong position through its R&D in plasma-derived and recombinant products. Roche Holding AG differentiates with its focus on non-factor replacement therapies, targeting a specific patient sub-group. Meanwhile, Novo Nordisk A/S leverages its long-standing presence in the recombinant factor VIIa space.
Bleeding disorders treatment encompasses medical interventions designed to manage congenital or acquired defects in the body's hemostatic system. These therapies often involve administering specific coagulation factors, such as recombinant Factor VIII, to restore normal blood clotting function. The Hemophilia A segment constitutes the largest portion of the market, driven by its higher prevalence compared to Hemophilia B. While coagulation factors are the dominant product type, novel non-factor therapies and gene therapies represent the fastest-growing categories.
Regulatory oversight from agencies like the United States FDA, the European Medicines Agency (EMA), and Japan's PMDA is critical for market entry. These bodies enforce rigorous standards for the clinical efficacy and safety of new treatments, particularly for advanced gene therapies. The key decision for manufacturers and payers revolves around establishing sustainable reimbursement models for high-cost curative treatments.
Market Dynamics
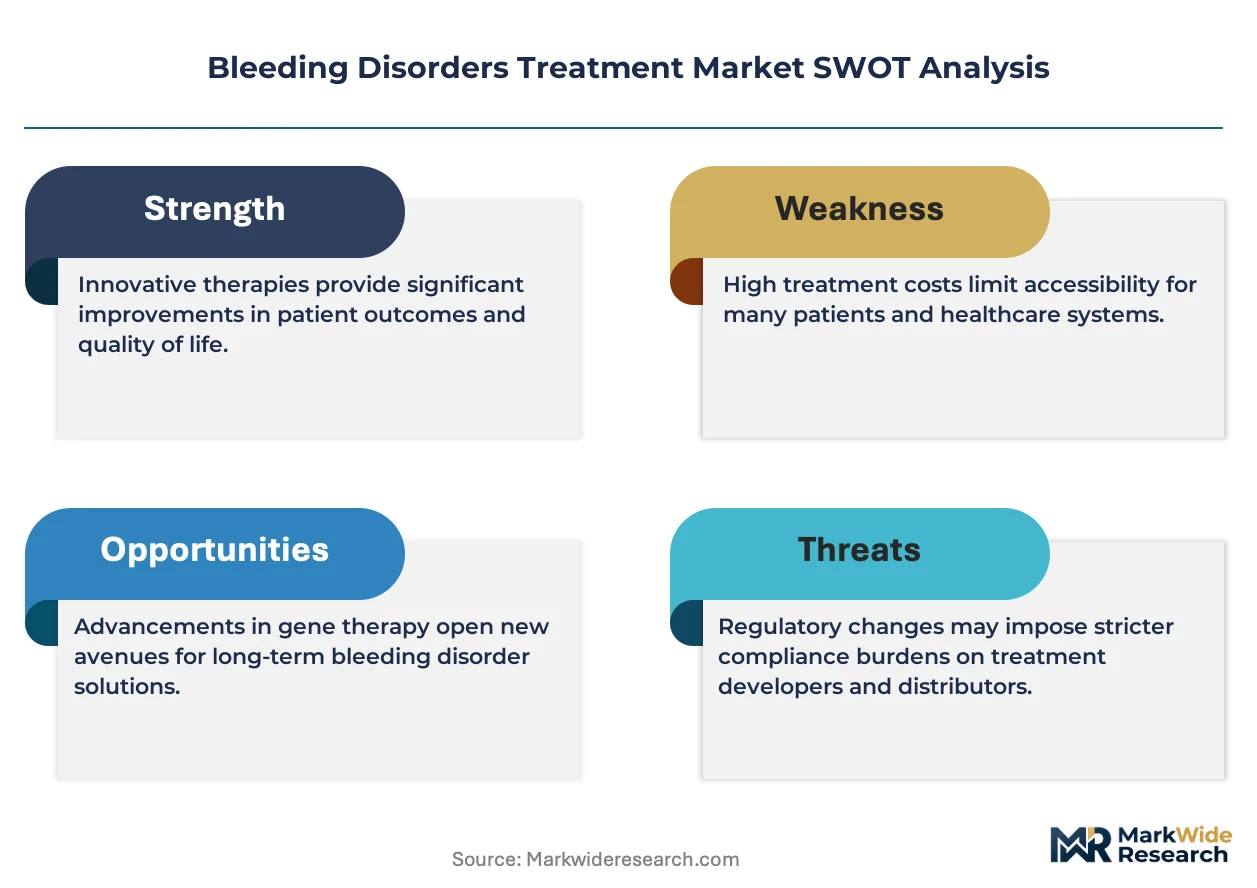
The fundamental dynamic shaping the bleeding disorders treatment market is the economic and clinical tension between high-cost, potentially curative gene therapies and established, chronic-use factor replacement therapies. This bifurcation influences R&D investment, payer reimbursement strategies, and patient treatment pathways.
Growth Catalysts
- Gene Therapy Advancements:Improvements in viral vector technology, specifically adeno-associated virus (AAV) vectors, are enhancing the safety and long-term efficacy profiles of new treatments, encouraging further investment and clinical development for Hemophilia A and B.
- Regulatory Harmonization:Efforts by the International Council for Harmonisation (ICH) to align clinical trial data requirements are streamlining the submission process for approvals with the FDA, EMA, and PMDA, accelerating market access for novel therapies.
- Diagnostic Network Expansion:The establishment and funding of specialized Hemophilia Treatment Centers (HTCs) in countries like Brazil and India are improving diagnosis rates and creating new, concentrated patient populations for existing and emerging therapies.
Market Restraints
- Extreme Treatment Cost:The multi-million dollar price point for single-administration gene therapies creates substantial reimbursement hurdles for public and private payers, limiting patient access despite proven clinical efficacy.
- Long-Term Durability Questions:A lack of extensive, multi-decade data on the durability of therapeutic effect and long-term safety of gene therapies leads to caution among clinicians and patients considering a shift from established treatments.
- Plasma Supply Vulnerability:The manufacturing of plasma-derived factor concentrates depends on a consistent supply of human plasma, a chain susceptible to disruptions from public health crises or changes in donor behavior.
Strategic Opportunities
- Underserved Indications:Developing therapies for ultra-rare bleeding disorders beyond hemophilia, such as von Willebrand disease or various platelet function disorders, offers a significant opportunity in a less saturated clinical space.
- Digital Health Integration:The creation of smartphone applications and wearable-linked platforms for tracking bleeds, managing infusion schedules, and enabling telehealth consultations with hematologists can improve patient adherence and outcomes.
- Prophylactic Treatment Expansion:Targeting patients with moderate bleeding disorders for prophylactic, or preventative, treatment represents a new market segment, shifting from on-demand treatment of acute bleeds to long-term management.
Industry Challenges
- Specialized Talent Scarcity:A global shortage of hematologists and genetic counselors trained in the administration and management of advanced gene and non-factor therapies creates a significant bottleneck for patient access and care delivery.
- Payer Model Divergence:Manufacturers face the challenge of developing separate value propositions and reimbursement strategies to satisfy disparate assessment frameworks, such as those used in the United States versus Germany's G-BA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bleeding Disorders Treatment Market |
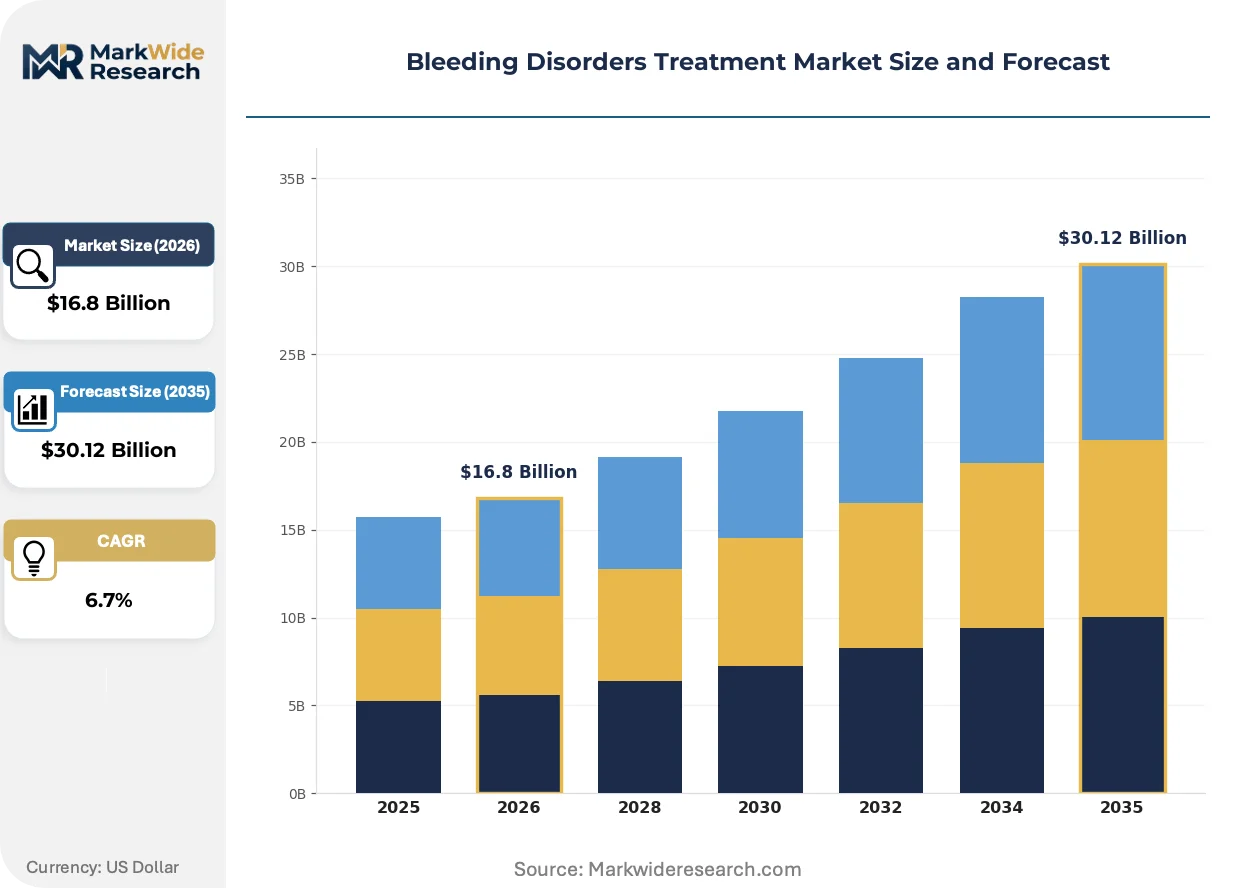
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $30.12 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulation Factors, Antifibrinolytics, Desmopressin, Platelet Aggregation Inhibitors, Blood Clotting Enhancers Therapy Area: Hemophilia A, Hemophilia B, Von Willebrand Disease, Platelet Function Disorders, Rare Coagulation Deficiencies End User: Hemophilia Treatment Centers, Specialty Clinics, Blood Banks, Rehabilitation Facilities Delivery Mode: Intravenous Therapy, Subcutaneous Injection, Oral Administration, Nasal Spray |
| Companies Covered | Takeda Pharmaceutical Company Limited, Roche Holding AG, Novo Nordisk A/S, Pfizer Inc., Bayer AG, Sanofi S.A., Grifols, S.A., Octapharma AG, CSL Behring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bleeding Disorders Treatment Market Strategic Shifts & Innovations
The market's evolution is defined by a paradigm shift from chronic disease management to the pursuit of a functional cure. This transformation is altering treatment algorithms, patient expectations, and the economic models underpinning the entire therapeutic category.
Non-factor replacement therapies, such as monoclonal antibodies that restore hemostatic function, provide a novel therapeutic mechanism. Patients with inhibitors to traditional factor treatments are the primary adopters of these subcutaneously administered drugs. This approach is supplanting the need for frequent intravenous infusions in this difficult-to-treat population, improving quality of life and adherence.
Regulatory pathways like the European Medicines Agency's PRIME scheme and the FDA's RMAT designation are critical. These programs provide enhanced support and expedited review timelines for therapies targeting unmet medical needs, particularly gene therapies. The gene therapy segment is most affected, as these designations enable faster entry but often come with post-market evidence generation requirements.
Patient-centric decision-making is altering treatment selection protocols. The choice between lifelong factor replacement and a one-time gene therapy is increasingly a shared discussion, moving away from a purely physician-directed model. This behavioral shift is most pronounced in the United States and parts of Western Europe, where strong patient advocacy and direct access to clinical data empower patients.
Bleeding Disorders Treatment Market Segmentation
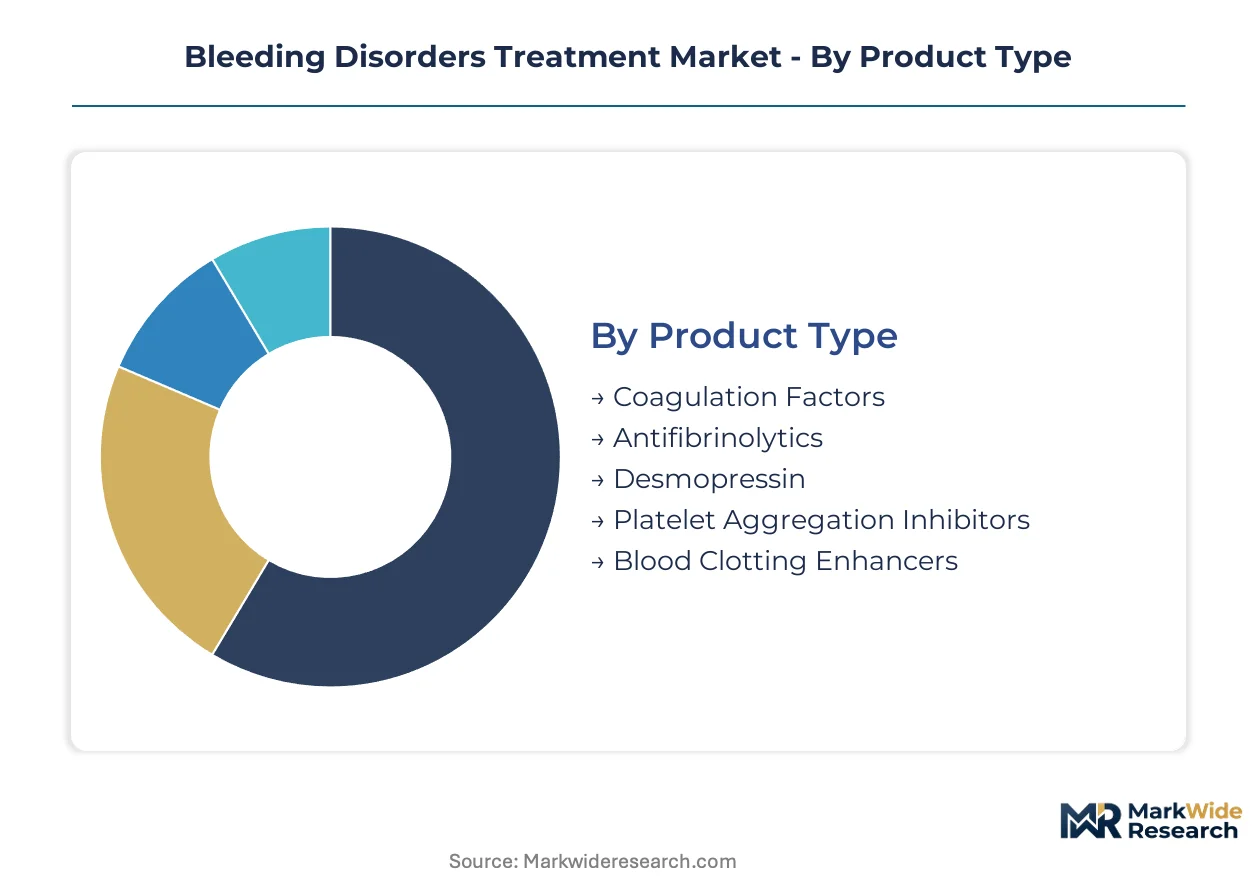
The bleeding disorders treatment market is segmented by the specific characteristics of therapies and patient needs, reflecting the complex nature of hemostatic system defects. This segmentation clarifies the diverse approaches to managing congenital and acquired bleeding conditions, guiding both product development and clinical application strategies.
Product Type:
Regulatory differentiation significantly impacts market entry for various product types, with novel therapies undergoing stringent review processes by agencies like the FDA and EMA.
- Coagulation Factors:These therapeutic proteins, either plasma-derived or recombinant, replace deficient clotting factors to restore normal hemostasis in patients. Demand for these established treatments concentrates in Hemophilia Treatment Centers across countries like the United States and Germany, driven by their proven efficacy in chronic disease management.
- Blood Clotting Enhancers:This category includes agents designed to promote or stabilize clot formation, often encompassing non-factor replacement therapies and other innovative approaches. Demand is concentrating in specialized clinics in Western Europe and Japan, propelled by the need for alternatives for patients with inhibitors or those seeking less frequent dosing.
- Antifibrinolytics:These medications prevent the breakdown of blood clots, thereby helping to maintain hemostasis, particularly in mucocutaneous bleeding.
- Desmopressin:A synthetic vasopressin analog used to increase plasma levels of von Willebrand factor and Factor VIII, primarily for mild Hemophilia A and von Willebrand disease.
- Platelet Aggregation Inhibitors:These medications prevent platelets from clumping together, a mechanism generally used to prevent thrombosis, but their specific application within bleeding disorders treatment is for managing certain co-morbidities.
Coagulation Factors handle the majority of throughput; Blood Clotting Enhancers are the fastest mover on share.
Therapy Area:
Treatment complexity varies significantly across different therapy areas, influencing resource allocation and specialized care requirements.
- Hemophilia A:The most prevalent congenital bleeding disorder, characterized by a deficiency in Factor VIII, requiring lifelong replacement therapy or advanced gene therapy. This therapy area commands the largest patient population globally, with treatment protocols well-established in comprehensive Hemophilia Treatment Centers.
- Rare Coagulation Deficiencies:This diverse group includes deficiencies in coagulation factors other than VIII or IX, such as Factor VII, X, XI, or XIII, often presenting unique diagnostic and treatment challenges. These ultra-rare conditions attract significant research and development interest in academic centers in the United States and Switzerland, aiming to address critical unmet medical needs.
- Hemophilia B:This less common congenital bleeding disorder results from a deficiency in Factor IX, managed through similar therapeutic approaches as Hemophilia A.
- Von Willebrand Disease:The most common inherited bleeding disorder, caused by a qualitative or quantitative defect in von Willebrand factor, requiring tailored treatment strategies.
- Platelet Function Disorders:A group of conditions where platelets do not function correctly, leading to impaired hemostasis, necessitating specific diagnostic and management approaches.
Hemophilia A represents the largest patient cohort, while rare coagulation deficiencies attract significant R&D investment.
End User:
The infrastructure for delivering bleeding disorder treatments is highly specialized, requiring dedicated facilities and expert personnel.
- Hemophilia Treatment Centers:These multidisciplinary facilities provide comprehensive care, including diagnosis, treatment, and patient education, for individuals with bleeding disorders. Demand is concentrated in countries with established healthcare systems like the United States, Germany, and Canada, benefiting from integrated care models.
- Specialty Clinics:Outpatient facilities focusing on specific hematological conditions, offering specialized diagnostic services and ongoing management for various bleeding disorders. Demand for these clinics is expanding in urban centers across Western Europe, providing accessible care beyond large HTCs.
- Blood Banks:Institutions responsible for the collection, processing, and distribution of blood products, including plasma-derived coagulation factors essential for some treatments.
- Rehabilitation Facilities:Centers that provide physical therapy and other rehabilitative services to help patients recover from bleeding-related complications, such as joint damage.
Hemophilia Treatment Centers are central to initial diagnosis and ongoing management, while rehabilitation facilities support long-term patient recovery.
Delivery Mode:
Patient preference and therapeutic efficacy drive the selection of different delivery modes, impacting adherence and quality of life.
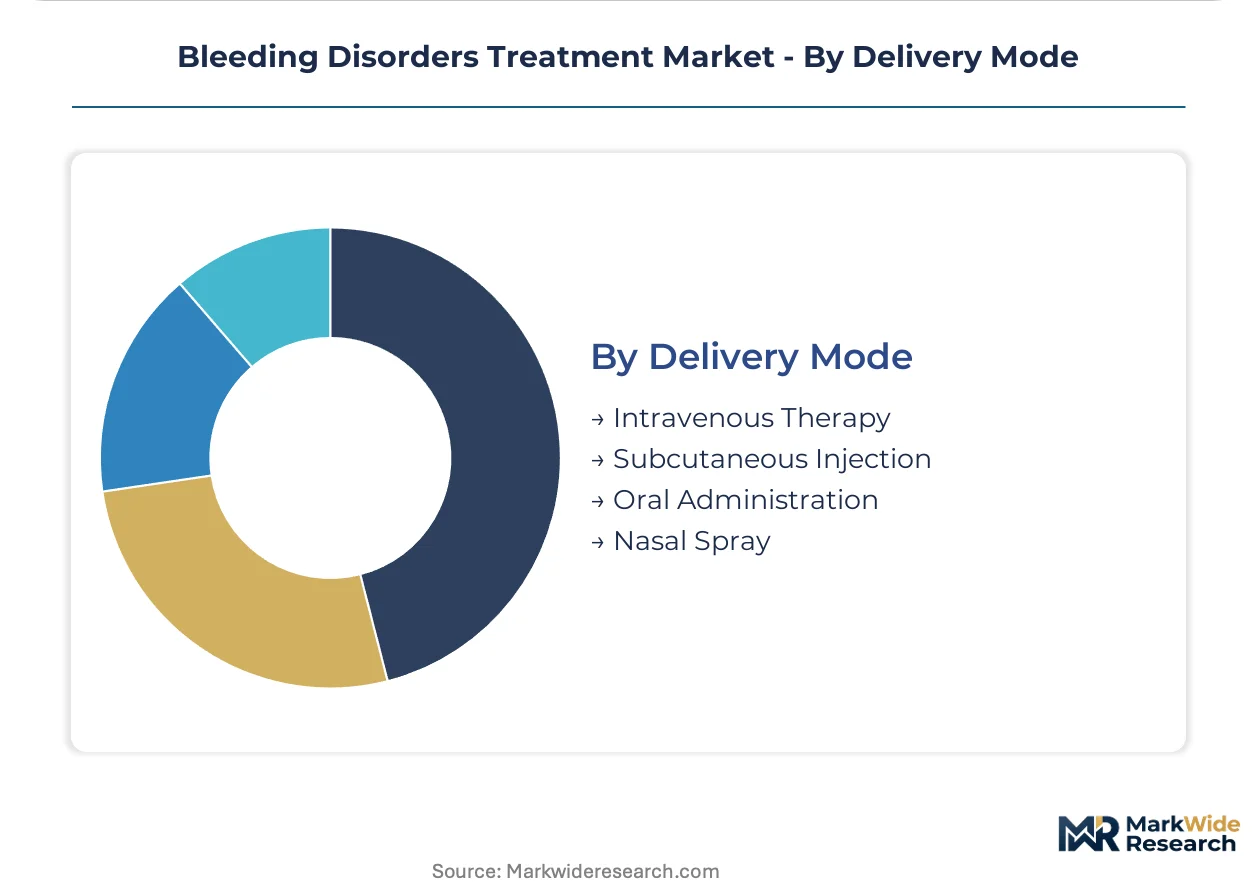
- Subcutaneous Injection:This method involves administering medication just beneath the skin, offering greater patient convenience and suitability for home-based prophylactic treatment. Demand is rapidly increasing for non-factor replacement therapies in the United States and parts of Europe, driven by improved patient adherence and reduced burden of frequent clinic visits.
- Intravenous Therapy:Direct administration of medication into a vein ensures rapid systemic distribution and is the traditional method for delivering coagulation factors, particularly for acute bleeds. This mode remains critical for established factor replacement therapies and emergency situations within Hemophilia Treatment Centers.
- Oral Administration:Medication taken by mouth, offering ease of use for certain adjunctive therapies or future non-factor treatments that can be formulated for oral bioavailability.
- Nasal Spray:Intranasal delivery allows for rapid absorption of certain medications, such as desmopressin, providing a non-invasive option for specific indications.
Intravenous therapy remains critical for acute management, but subcutaneous injection is gaining traction for its convenience in prophylactic care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States FDA's rigorous approval processes anchor advancements in bleeding disorders treatment. Demand for innovative therapies concentrates in regions with established healthcare infrastructure and comprehensive patient registries. Gene therapies and non-factor replacement options are reshaping treatment paradigms across these key markets.
United States
Demand for advanced gene therapies and comprehensive care drives market expansion in the United States. The FDA's expedited review pathways, such as RMAT designation, accelerate access for novel treatments. Specialized Hemophilia Treatment Centers in cities like Boston and New York actively integrate new therapeutic modalities.
Germany
Germany's robust healthcare system and established patient registries support demand for both traditional and novel treatments. The European Medicines Agency (EMA) and Germany's G-BA influence reimbursement strategies for high-cost therapies. Comprehensive care facilities in Munich and Berlin focus on advanced diagnostics and personalized treatment plans.
Japan
Japan exhibits strong demand for advanced coagulation factors and non-factor replacement therapies, driven by an aging population. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures stringent safety and efficacy standards for new market entrants. Leading research institutions in Tokyo and Osaka contribute to clinical trials for gene therapy development.
Brazil
Brazil's expanding network of specialized Hemophilia Treatment Centers increases diagnosis rates for bleeding disorders. ANVISA, the national health surveillance agency, regulates the approval and distribution of essential medicines. Public health initiatives in São Paulo and Rio de Janeiro aim to improve access to prophylactic treatments.
India
India presents a growing opportunity for bleeding disorder treatments, particularly with improved diagnostic capabilities. The Central Drugs Standard Control Organization (CDSCO) oversees the approval of imported and domestically manufactured therapies. Major metropolitan areas like Mumbai and Delhi are establishing new specialized clinics to manage patient populations.
Bleeding Disorders Treatment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the market structure for bleeding disorders treatment. This market exhibits a tiered competitive landscape, with established pharmaceutical giants alongside innovative biotech firms. Archetypes include large-scale factor replacement providers, non-factor therapy innovators focusing on specific patient needs, and gene therapy pioneers pursuing potentially curative solutions. Strategic partnerships for technology access and significant R&D investment in novel mechanisms represent dominant competitive moves across the industry.
Among established pharmaceutical companies, Takeda Pharmaceutical Company Limited exemplifies a strong position through its R&D in both plasma-derived and recombinant products, maintaining a broad portfolio. Roche Holding AG sits within the innovative non-factor replacement therapy segment, specifically targeting patient sub-groups with complex needs. Novo Nordisk A/S occupies a prominent role leveraging its long-standing presence in the recombinant factor VIIa space, a specialized area. These entities anchor the market's evolution, with their diverse portfolios reflecting the ongoing shift from traditional factor replacement to advanced therapeutic modalities. Their global reach and investment in specialized treatment areas define critical competitive benchmarks for the industry.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Roche Holding AG |
| Novo Nordisk A/S |
| Pfizer Inc. |
| Bayer AG |
| Sanofi S.A. |
| Grifols, S.A. |
| Octapharma AG |
| CSL Behring |
| Others |
Cost & Logistics Intelligence
Value-based reimbursement models increasingly dictate pricing and supply access for advanced bleeding disorder treatments, linking therapeutic outcomes to financial outlays for payers. This structure creates visibility for high-cost therapies while demanding clear clinical benefits.
Pricing Analysis
Geographic price spreads for bleeding disorder treatments vary significantly, reflecting diverse healthcare funding systems and regulatory frameworks. Value-based pricing, particularly for gene therapies, dominates the advanced treatment segment. Price differentiation stems from regulatory approval status by agencies like the FDA and EMA, alongside demonstrated clinical efficacy across patient populations. Pricing softness reflects intense reimbursement negotiations, especially from public payers in countries such as Germany. Patient segments with rare coagulation deficiencies exhibit lower price sensitivity due to limited alternative treatment options.
Supply Chain Analysis
Strategic stockpiling of critical components, rather than just-in-time delivery, characterizes the bleeding disorders treatment supply chain, particularly for plasma-derived products. Supply concentrates in countries with robust plasma collection infrastructure like the United States and specialized biomanufacturing hubs in Germany and Japan. Raw material dependencies include human plasma and specialized viral vectors for gene therapies. Plasma supply vulnerability represents a structural risk, susceptible to public health crises. Distribution of these specialized therapies runs through integrated networks connecting manufacturers directly to Hemophilia Treatment Centers and specialty clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, primarily driven by the increasing adoption of gene therapies and improved diagnostic capabilities in emerging economies.
For Market Incumbents: Fortify existing market positions by diversifying into novel non-factor replacement therapies and gene therapy platforms. This strategy mitigates the threat from disruptive curative treatments and emerging specialized biotech firms. Investment in regulatory engagement with bodies like the FDA and EMA for expedited pathways represents a critical lever for sustained growth. Strengthen patient support programs to enhance adherence and outcomes across diverse treatment modalities.
For New Entrants and Emerging Players: FDA's RMAT designation or EMA's PRIME scheme offers a critical certification fast-track for novel therapies addressing unmet needs. Target underserved indications, such as ultra-rare coagulation deficiencies or specific patient sub-groups with inhibitors, represents a penetrable segment. Partnering with established Hemophilia Treatment Centers provides an effective go-to-market angle for specialized product launches. Digital health integration for remote patient monitoring also presents a significant white-space opportunity.
For Investors and Strategic Acquirers: Specialized biotech firms with advanced gene therapy pipelines or novel non-factor replacement platforms represent attractive acquisition targets. The market exhibits favorable long-term viability over a 5-10 year window, driven by high-value, transformative therapies. Watch for successful long-term durability data from pivotal gene therapy clinical trials as a key inflection indicator for investment decisions. Focus on companies with strong intellectual property and established regulatory pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expedites regulatory approval for novel gene therapies and non-factor treatments. |
| Regulatory Approval Pathway | Secures market access by navigating complex FDA and EMA requirements efficiently. |
| Licensing Agreement | Expands product portfolios and technology access for specialized treatment modalities. |
| Manufacturing Scale-Up | Ensures consistent supply for high-demand, complex biologic and gene therapies. |
| Pipeline Diversification | Mitigates risk by addressing multiple bleeding disorders and patient sub-groups. |
Research Approach
Desk research of regulatory filings, scientific publications, and patient registry data preceded structured interviews with hematologists, genetic counselors, and regulatory affairs specialists. This approach combined primary insights with secondary validation, ensuring comprehensive market understanding. Bottom-up and top-down triangulation further refined the data points for accuracy.
Variance decomposition informed the analytical framework for market projections across the analysis window. The model integrated segmentation by product type, therapy area, end user, and delivery mode, alongside regional regulatory clusters. Compound annual growth rates derived from historical trends and projected market dynamics, incorporating gene therapy approval timelines and patient prevalence data as key inputs.
Decision-makers should treat outputs as directional under current regulatory and clinical practice assumptions; material deviation would warrant model refresh. Forecasts reflect a synthesis of available data and expert consensus. Revision becomes warranted when significant shifts in reimbursement policy or long-term gene therapy safety outcomes cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Global Alcoholic Hepatitis Therapeutics Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Brugada Syndrome Market
Specialty Medicine
Global Melanoma Diagnostics and Therapeutics Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Bartonellosis Therapeutics Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Nasal Polyposis Treatment Market