
 Lightning Protection Products Market | 2026-2036
Lightning Protection Products Market Size, Share, and Industry Trends Forecast 2026-2036
Lightning Protection Products Market Intelligence
The integration of predictive analytics and IoT sensors into conventional lightning protection systems is fragmenting the market's traditional hardware focus. This shift introduces new value in software and data services for asset monitoring. DEHN SE + Co KG specializes in advanced surge protective devices for complex industrial settings. Eaton leverages its extensive electrical product portfolio to provide integrated solutions for commercial buildings, while nVent Electric Plc positions itself with specialized grounding and bonding solutions.
Lightning protection products encompass an engineered system of air terminals, conductors, and grounding materials designed to safely channel lightning currents to the earth. These systems utilize materials with high conductivity, such as copper and aluminum, to prevent fire, structural damage, and electronic equipment failure. Within the product landscape, surge arresters and couplers represent higher-margin components, driven by technical requirements in data centers and telecommunication towers. Grounding materials are a volume-centric segment, essential for both new construction and retrofit applications.
Product design and installation are governed by a matrix of international and national standards, including IEC 62305 and the US-based NFPA 780. Regulatory bodies in countries like Germany and Japan enforce stringent building codes that mandate specific protection levels for critical infrastructure and public facilities. The primary strategic decision for manufacturers now revolves around specializing in high-performance components versus developing integrated, software-enabled system solutions for end-to-end protection.
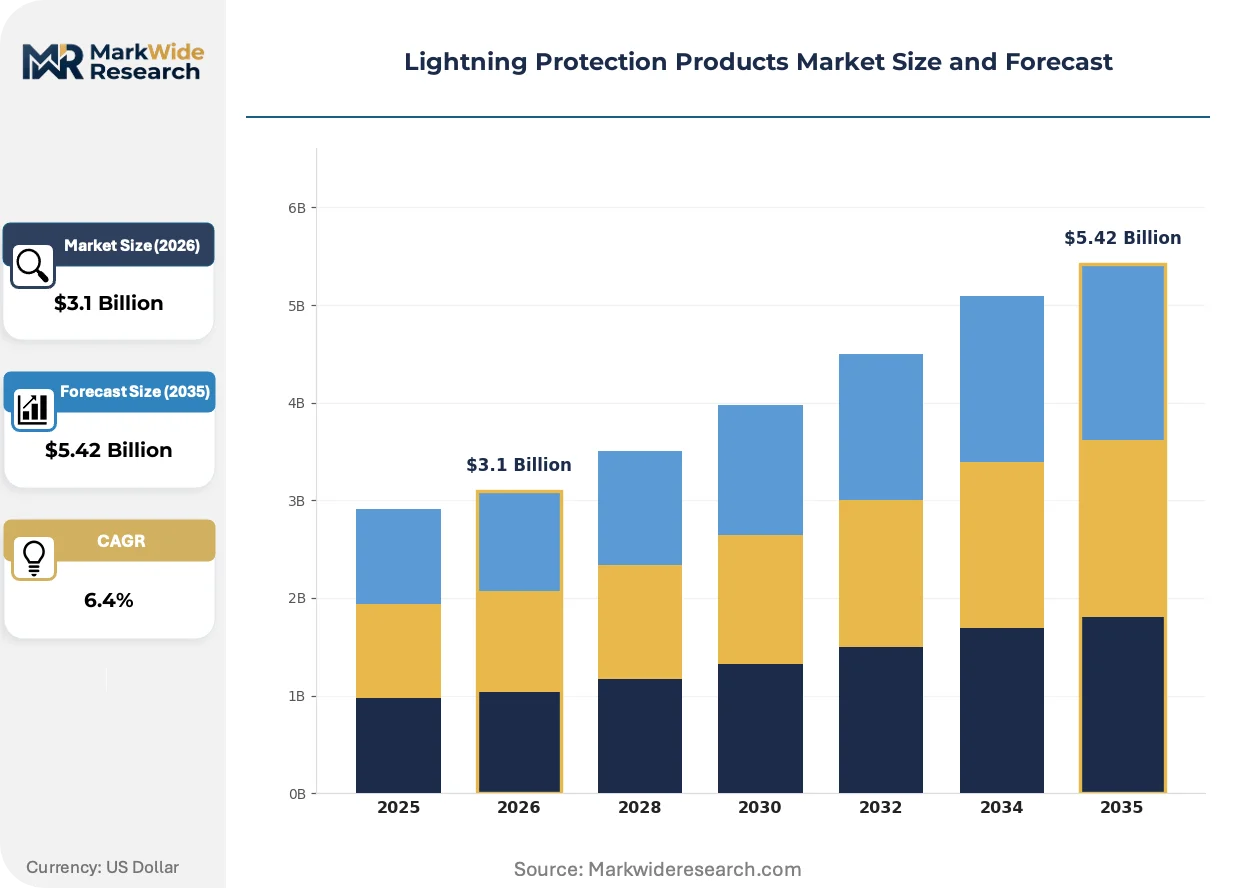
Market Dynamics
The central force shaping the market is the convergence of critical infrastructure expansion with the digitalization of asset management. Demand from new data centers and renewable energy projects requires not just physical protection but also integrated, data-driven monitoring capabilities.
Growth Catalysts
- Mandatory Standards:The enforcement of standards like IEC 62305 compels the use of certified lightning protection systems in new construction, particularly for public buildings, hospitals, and industrial facilities in Europe and Asia.
- Renewable Energy Expansion:The proliferation of large-scale solar and wind farms, often located in exposed, high-lightning-risk areas, necessitates robust protection for turbines and photovoltaic panels to ensure grid stability and asset longevity.
- IoT Integration:The adoption of IoT-based sensors for predictive maintenance in industrial plants and utilities creates demand for advanced surge protection to safeguard sensitive monitoring equipment and data communication lines.
Market Restraints
- Input Cost Volatility:The market is sensitive to price fluctuations in core conductive materials, especially copper. Sudden cost increases can compress manufacturer margins and delay project approvals for large-scale installations.
- Retrofitting Complexity:Upgrading protection systems in existing historical or architecturally complex buildings is often prohibitively expensive and logistically challenging, limiting a significant segment of the built environment.
- Perception of High Initial Cost:In non-critical commercial and residential sectors, the upfront investment for a professionally engineered system competes with a reliance on lower-cost, often inadequate, plug-in surge protectors, slowing adoption.
Strategic Opportunities
- EV Charging Infrastructure:The global build-out of public and private electric vehicle charging stations represents a new, distributed network of vulnerable electrical assets requiring specialized grounding and surge protection solutions.
- Service-Based Models:A shift from one-time product sales to recurring revenue models based on remote monitoring, risk assessment software, and system health analytics offers a significant value-add opportunity.
- Southeast Asian Construction:Rapid urbanization and industrialization in countries like Vietnam and Indonesia, which have high lightning flash densities, create concentrated demand for all categories of lightning protection products.
Industry Challenges
- Certified Installer Shortage:A skills gap exists for technicians qualified to install and certify complex systems that integrate traditional electrical components with modern IT and software elements, particularly under standards like NFPA 780.
- Legacy System Integration:Ensuring compatibility and seamless operation between new, advanced surge protection devices and older, legacy building management or industrial control systems poses a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightning Protection Products Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Terminals, Surge Arresters, Grounding Materials, Lightning Rods, Couplers Application: Telecommunication Towers, Data Centers, Industrial Facilities, Renewable Energy Plants, Transportation Hubs Installation Type: New Construction, Retrofit Projects, Mobile Units, Temporary Installations End User: Utility Companies, Manufacturing Plants, Commercial Buildings, Military Facilities |
| Companies Covered | ABB, A.N. Wallis, DEHN SE + Co KG, Harger Lightning & Grounding, Alltec LLC, nVent Electric Plc, Eaton, Schneider Electric, East Coast Lightning Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightning Protection Products Market Strategic Shifts & Innovations
The market's evolution is defined by the shift from passive hardware components to active, intelligent systems. This transition embeds software and data analytics into the core of lightning protection, creating new value in risk mitigation and asset management.
Lightning prediction software, using data from regional detection networks and atmospheric sensors, provides advance warnings of strike risk. Operators of utility grids and sprawling industrial complexes are early adopters, seeking to proactively safeguard assets and personnel. This software-based approach is virtualizing the need for constant physical site inspections, reallocating operational budgets from manual checks to data-driven predictive actions.
Revisions to the IEC 62305 standard are tightening risk assessment protocols for structures containing sensitive electronics. The regulation now implicitly requires a more granular analysis, driving the specification of higher-performance surge protective devices (SPDs). This trend most acutely affects the design of new data centers and telecommunication towers, where engineers are compelled to adopt multi-stage protection strategies to ensure operational uptime.
A clear behavioral change is the unbundling of hardware sales from system assurance services. End-users in critical sectors are moving beyond simple component purchasing to seek contracts that guarantee system performance and compliance over time. This disrupts the model of traditional electrical distributors, creating an opening for specialized engineering firms offering turnkey design, installation, and monitoring services, a pattern most visible in North American industrial markets.
Lightning Protection Products Market Segmentation
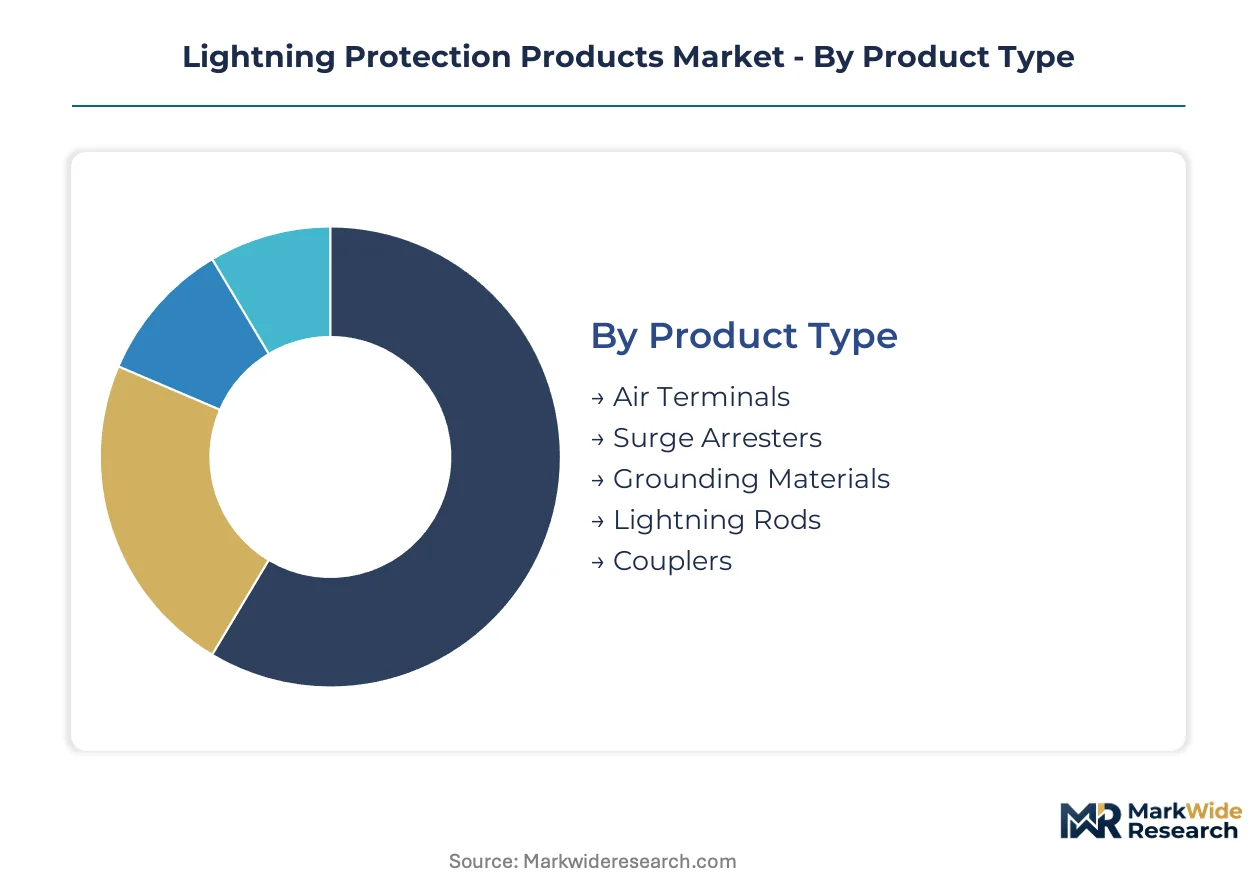
The segmentation of the lightning protection products market is crucial for understanding the diverse needs across various industries and infrastructure types. This analysis details how product innovation, application-specific requirements, and end-user demands shape the competitive landscape.
Product Type:
The product type segmentation delineates the various components used to construct comprehensive lightning protection systems, addressing a wide spectrum of use-case scenarios.
- Air Terminals:These components are positioned at the highest points of a structure to intercept direct lightning strikes, typically made from copper or aluminum to ensure high conductivity and durability. Demand for air terminals is driven by new construction projects in rapidly urbanizing areas like Southeast Asia.
- Surge Arresters:These devices protect electronic equipment from transient overvoltages by diverting excess current to the ground, employing advanced semiconductor technologies. The proliferation of sensitive IT infrastructure in data centers and telecommunication towers in Germany necessitates high-performance surge arresters.
- Grounding Materials:This category includes rods, plates, and conductors that provide a low-impedance path for lightning currents to safely dissipate into the earth, forming the foundation of any protection system. High-volume demand for grounding materials comes from large-scale renewable energy projects in exposed regions of Australia.
- Lightning Rods:Traditional lightning rods are pointed metal conductors installed on structures to attract and channel lightning, primarily used in residential and smaller commercial buildings.
- Couplers:These components are used to connect different parts of a lightning protection system, ensuring electrical continuity and integrity across varied structural elements.
The dominant share belongs to Grounding Materials, while Surge Arresters are closing the gap fastest.
Application:
This segmentation highlights the diverse operational environments where lightning protection systems are critical for asset and personnel safety.
- Telecommunication Towers:These structures require robust protection for sensitive electronic equipment and continuous operation, often located in elevated and exposed areas.
- Data Centers:Critical infrastructure facilities house vast amounts of sensitive IT equipment, demanding multi-stage surge protection and advanced grounding to ensure uninterrupted service. The expansion of cloud computing services globally drives significant investment in data center protection in markets like the United States.
- Industrial Facilities:Manufacturing plants and processing facilities often contain flammable materials and complex machinery, necessitating comprehensive lightning protection to prevent explosions and operational downtime. Industrial expansion in emerging economies like India fuels demand for robust protection systems.
- Renewable Energy Plants:Large-scale solar farms and wind turbines are frequently situated in remote, high-lightning-risk areas, requiring specialized protection for photovoltaic panels and turbine blades. The global push for clean energy, particularly in Europe, mandates robust protection for wind farms.
- Transportation Hubs:Airports, railway stations, and ports require protection for control towers, signaling systems, and critical infrastructure to maintain operational safety and efficiency.
Demand for Industrial Facilities remains significant, with Data Centers exhibiting the steepest expansion trajectory.
Installation Type:
The installation type segmentation categorizes projects by their stage within a building's lifecycle or operational mobility.
- New Construction:This segment involves the integration of lightning protection systems during the initial design and building phase of residential, commercial, and industrial structures. Mandatory building codes in countries like Japan drive consistent demand for new construction installations.
- Retrofit Projects:These projects involve upgrading or adding lightning protection to existing structures that previously lacked adequate systems or require enhanced protection due to new regulations. The complexity and cost of retrofitting older public buildings in European cities often pose significant challenges.
- Mobile Units:This category includes specialized protection for portable equipment, temporary structures, or vehicles that operate in various locations and require flexible solutions.
- Temporary Installations:These systems are deployed for short durations, such as at construction sites, outdoor events, or during emergency response operations, providing transient protection.
New Construction projects consistently drive volume, while Retrofit Projects efforts increasingly gain share.
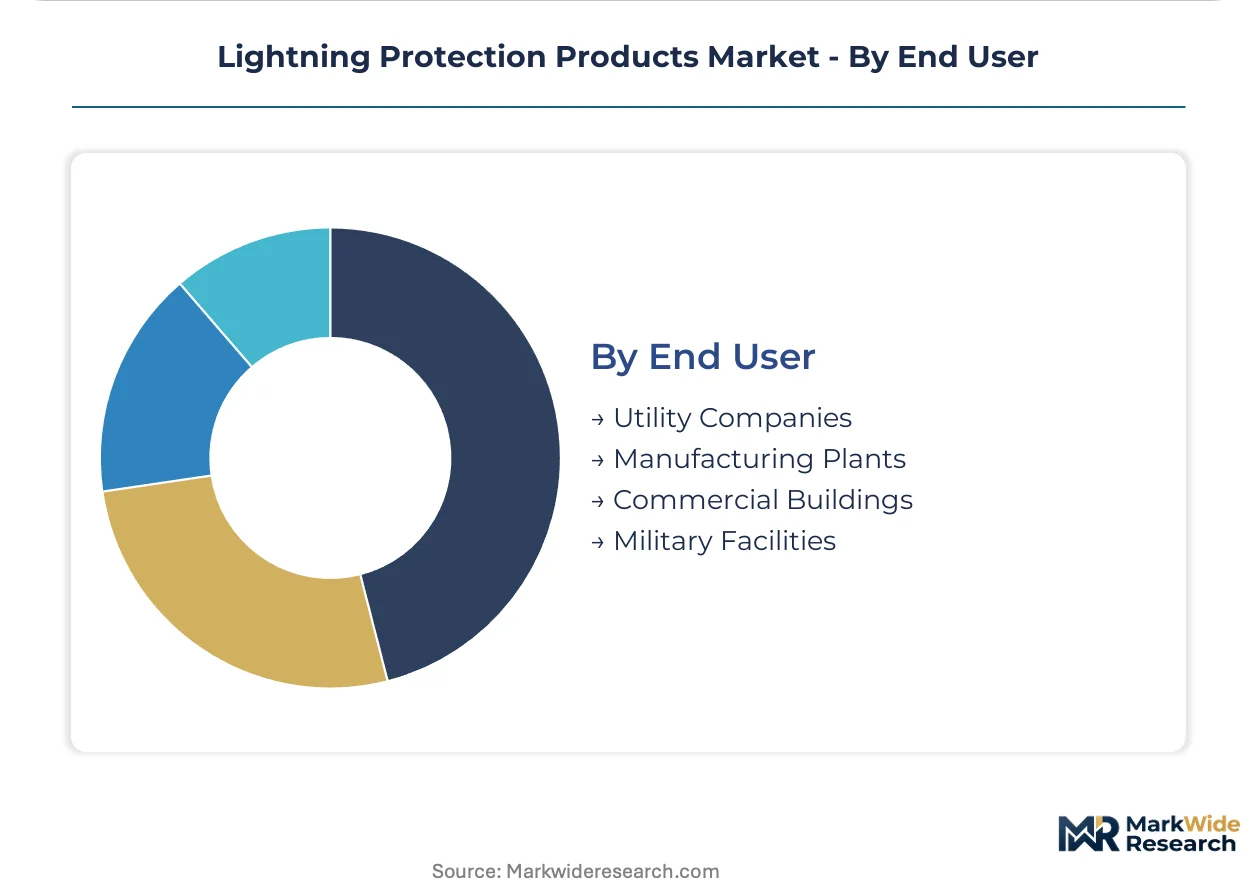
End User:
This segment differentiates end-users based on their specific asset protection requirements and regulatory compliance needs.
- Utility Companies:These entities operate extensive power grids, substations, and transmission lines, requiring robust lightning protection to ensure grid stability and prevent widespread outages. Utility infrastructure upgrades in Brazil are driving substantial demand.
- Manufacturing Plants:Industrial end-users need protection for sensitive machinery, control systems, and raw materials to maintain production continuity and safeguard personnel. The automotive manufacturing sector in South Korea invests heavily in lightning protection for its facilities.
- Commercial Buildings:This segment includes offices, retail centers, and hospitality venues that require protection for electronic systems, building occupants, and structural integrity.
- Military Facilities:These critical installations demand the highest levels of protection for sensitive equipment, communication systems, and personnel due to national security implications.
Utility Companies represent a foundational end-user base, with Military Facilities showing consistent growth in specialized demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global demand for lightning protection products is increasingly shaped by the flow of advanced surge protection components from manufacturing hubs in Germany to critical infrastructure projects across Southeast Asia. This trade pattern highlights the specialized technology transfer driving market evolution. Demand concentrates where new construction meets high lightning frequency.
Germany
Demand for advanced surge arresters in Germany stems from stringent building codes for critical infrastructure and sensitive IT equipment. German regulatory bodies enforce specific protection levels under IEC 62305. Frankfurt and Munich are data center hubs, driving investment in multi-stage surge protection strategies.
United States
The United States sees substantial demand for lightning protection due to its expanding data center footprint and grid stability. NFPA 780 standards guide installations, ensuring comprehensive protection for commercial and industrial facilities. Data center campuses in Virginia and Silicon Valley require advanced grounding and surge protection for cloud service uptime.
India
Industrial expansion and rapid urbanization across India fuel significant demand for comprehensive lightning protection systems in manufacturing plants. National building codes and CEA guidelines mandate protection for critical infrastructure. New industrial corridors in Maharashtra and Gujarat are seeing concentrated investment in robust protection for sensitive machinery.
Vietnam
Vietnam experiences high lightning flash densities, driving demand for air terminals and grounding materials in new construction and urbanization projects. Local building codes are adapting to ensure safety for public and commercial buildings. Ho Chi Minh City and Hanoi lead urban development, requiring extensive protection for emerging complexes.
Australia
Australia's large-scale renewable energy projects in exposed regions necessitate specialized lightning protection for asset longevity. Energy sector regulations emphasize robust protection for grid-connected infrastructure. Queensland and New South Wales host significant wind and solar developments, requiring high-volume grounding materials and surge arresters.
Lightning Protection Products Market Key Industry Players
On the supply side, the industry is undergoing a structural shift, fragmenting from traditional hardware manufacturers towards more integrated, software-enabled solutions. This evolution creates distinct archetypes, including specialized component providers, comprehensive system integrators, and emerging service-based monitoring firms. Key competitive moves involve portfolio diversification into software and data services, alongside strategic partnerships to deliver end-to-end protection.
Specialists in advanced surge protection and integrated solutions include DEHN SE + Co KG, an internationally recognized entity known for its complex industrial surge protective devices. Eaton, a diversified electrical products company, exemplifies the integrated solutions archetype, leveraging its broad portfolio to provide comprehensive offerings for commercial buildings. nVent Electric Plc occupies a position as a provider of specialized grounding and bonding solutions, critical for complex electrical environments requiring robust earthing systems. These firms collectively anchor the market's premium and solution-oriented segments.
| Leading Market Players |
|---|
| ABB |
| A.N. Wallis |
| DEHN SE + Co KG |
| Harger Lightning & Grounding |
| Alltec LLC |
| nVent Electric Plc |
| Eaton |
| Schneider Electric |
| East Coast Lightning Equipment |
| Others |
Cost & Logistics Intelligence
Input cost volatility, particularly for copper, shapes both pricing tier spreads and the supply chain structure within the lightning protection products market. This commodity fluctuation directly influences material procurement strategies and impacts the final cost for end-users across various applications.
Pricing Analysis
The technology-generation pricing gap differentiates advanced surge protection devices from conventional hardware components. Project-based pricing dominates for integrated systems, while per-unit transactional models apply to individual components like air terminals. Price differentiation stems from certification levels, such as IEC 62305 compliance, and the performance tier required for sensitive electronics. Pricing pressure in the volume-centric grounding materials segment contrasts with higher margins for high-performance surge arresters. Non-critical commercial and residential sectors exhibit higher price sensitivity compared to critical infrastructure operators.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities play a role in managing cash flow for manufacturers and distributors. Supply concentration for advanced components centers in Germany, while general materials and basic components are sourced from China. Raw material dependencies include copper and aluminum for conductors, alongside semiconductor components for surge protective devices. Commodity price volatility, particularly for copper, represents a significant structural risk. Distribution runs through specialized engineering firms for complex projects and established electrical distributors for standard product lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, as incumbents must navigate the threat posed by lower-cost, often inadequate, plug-in surge protectors for less critical applications.
For Market Incumbents:Insulate core hardware revenues by integrating advanced monitoring and data analytics into product offerings. Invest in R&D for next-generation IoT-enabled surge protective devices to counter commoditization of basic components. Pursue strategic partnerships with software developers to offer comprehensive, integrated protection systems. Emphasize certification investment under revised standards like IEC 62305 to maintain a competitive edge against lower-tier alternatives.
For New Entrants and Emerging Players:Build out specialized solutions for emerging infrastructure segments like electric vehicle charging stations and smart city deployments. Target the Southeast Asian construction market, which presents concentrated demand due to high lightning frequency and rapid urbanization. A viable go-to-market angle involves offering integrated, software-enabled system solutions that prioritize predictive maintenance and asset longevity over simple hardware sales.
For Investors and Strategic Acquirers:The market sits at a growth phase that favors technology-forward specialists and service integrators over traditional hardware manufacturers. Long-term viability is strong, driven by the continuous expansion of critical digital infrastructure and renewable energy. Acquisition targets should include specialized software firms or engineering service providers with strong intellectual property in IoT-based monitoring. Watch for increasing adoption rates of predictive analytics platforms as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand IoT-integrated SPD portfolio | This enhances product intelligence and meets demand for advanced asset monitoring in industrial facilities. |
| Form partnerships with data analytics providers | This enables value-added services like predictive maintenance for data center operators and utility companies. |
| Invest in certified installer training programs | This addresses the skills gap for complex system integration, particularly for NFPA 780 compliance. |
| Target EV charging infrastructure protection | This captures an emerging, distributed network of vulnerable electrical assets in transportation hubs. |
| Develop recurring revenue service models | This shifts from one-time product sales to long-term contracts for system performance assurance. |
Research Approach
Findings reconcile primary fieldwork against secondary review of international standards like IEC 62305, national building codes, and industry association reports. Primary interviews involved electrical engineers, data center operators, renewable energy project managers, and building code officials. This approach ensured a robust understanding of market dynamics through both bottom-up and top-down triangulation of data points.
Forecast inputs considered include critical infrastructure expansion, digitalization trends, and regulatory mandates across the analysis window. The analytical framework modeled segmentation dimensions such as product type, application, installation type, end-user, and regional construction activity. Compound annual growth rates were derived by extrapolating historical trends and projecting future infrastructure development and renewable energy capacity additions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized software providers or integrated service firms would shift outcomes. Forecasts reflect assumptions regarding technological advancements and regulatory enforcement. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market