
 Body Armor Plates Market | 2026-2036
Body Armor Plates Market Size, Share, and Industry Trends Forecast 2026-2036
Body Armor Plates Market Intelligence
North American ceramic foundry capacity is restructuring as military demand outpaces legacy supply arrangements. BAE Systems plc sustains its position through captive material science programs and direct government contracting relationships. Ceradyne Inc. dominates technical ceramic plate production with vertically integrated boron carbide processing. Safariland, LLC competes across law enforcement channels with modular plate carrier integration capabilities.
Body armor plates are hardened protective inserts engineered to defeat ballistic threats through material deformation, fracture absorption, or fiber elongation mechanisms, typically manufactured from alumina, silicon carbide, boron carbide, or ultra-high-molecular-weight polyethylene composites. Ceramic plates achieve NIJ Level IV certification by combining a strike face with composite backing to defeat armor-piercing rifle rounds, while polyethylene systems offer multi-hit protection at reduced weights for mobile infantry applications. Composite material configurations command premium positioning due to weight-to-protection ratios demanded by special operations forces, whereas steel plates occupy economy tiers in civilian and training markets despite higher areal density penalties. Certification tier stratification creates distinct margin pools, with NIJ Level IV plates generating substantially higher unit economics than Level III equivalents due to raw material intensity and qualification testing burdens.
NIJ certification protocols in the United States, CEN standards across European defense procurement frameworks, and BIS technical specifications in India collectively shape product validation requirements and cross-border market access conditions. Regulatory divergence between NIJ and CEN testing methodologies forces manufacturers to maintain parallel qualification programs, elevating barriers for mid-scale producers lacking dedicated compliance infrastructure. Stakeholders must monitor evolving threat specifications from military end-users, as next-generation armor-piercing ammunition profiles threaten to obsolete current certification thresholds and trigger replacement investment cycles.
Market Dynamics
NATO threat reassessments are compressing replacement cycles for legacy ceramic systems while fragmenting procurement across bilateral defense agreements rather than consolidated block contracts.
Growth Catalysts
- NIJ Standard Updates:United States law enforcement agencies face mandated replacement timelines for pre-2023 ceramic and polyethylene plate inventories. State-level procurement offices are accelerating bulk purchase authorizations to meet compliance deadlines.
- Boron Carbide Processing Advances:Technical ceramic foundries achieving sub-micron grain refinement are extending multi-hit performance thresholds. Military special operations units are specifying these formulations for reduced-weight Level IV configurations.
- India:BIS technical specification harmonization with NATO STANAG protocols is opening import substitution opportunities for domestic manufacturers. Ministry of Defense indigenization mandates are redirecting plate procurement toward certified local suppliers.
Market Restraints
- Boron Carbide Supply Concentration:Primary feedstock processing capacity clusters in limited geographic zones, exposing plate manufacturers to raw material allocation disruptions during defense procurement surges.
- NIJ-CEN Testing Divergence:Parallel qualification requirements for United States and European defense contracts elevate fixed compliance costs for mid-scale producers lacking dedicated certification infrastructure.
- Steel Plate Substitution:Civilian and training market segments tolerate higher areal density penalties in exchange for unit cost reductions, compressing addressable margin pools for advanced composite suppliers.
Strategic Opportunities
- Modular Plate Carrier Integration:Law enforcement agencies are specifying interface-standardized plates compatible with multi-vendor carrier systems. Safariland and competing vendors are developing quick-detach mounting geometries to capture this specification-driven demand.
- European Defense Procurement Consolidation:EU joint procurement frameworks under the European Defence Fund are creating centralized tender opportunities spanning multiple member state requirements.
- Next-Generation Threat Specifications:Armor-piercing ammunition profiles exceeding current NIJ Level IV thresholds are triggering pre-emptive R&D investment cycles among prime contractors positioned for qualification contract awards.
Industry Challenges
- Ballistic Testing Engineer Scarcity:Qualified personnel capable of interpreting fragment dispersion patterns and backface deformation metrics are concentrated among legacy defense contractors, constraining independent validation capacity.
- Ceramic Sintering Capital Intensity:Hot isostatic pressing equipment for boron carbide densification requires seven-figure capital commitments with extended qualification timelines, favoring incumbent producers with amortized infrastructure.
- Legacy System Integration:Military end-users maintaining heterogeneous plate inventories face logistics complexity when fielding mixed ceramic-polyethylene-steel configurations across deployed units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Armor Plates Market |
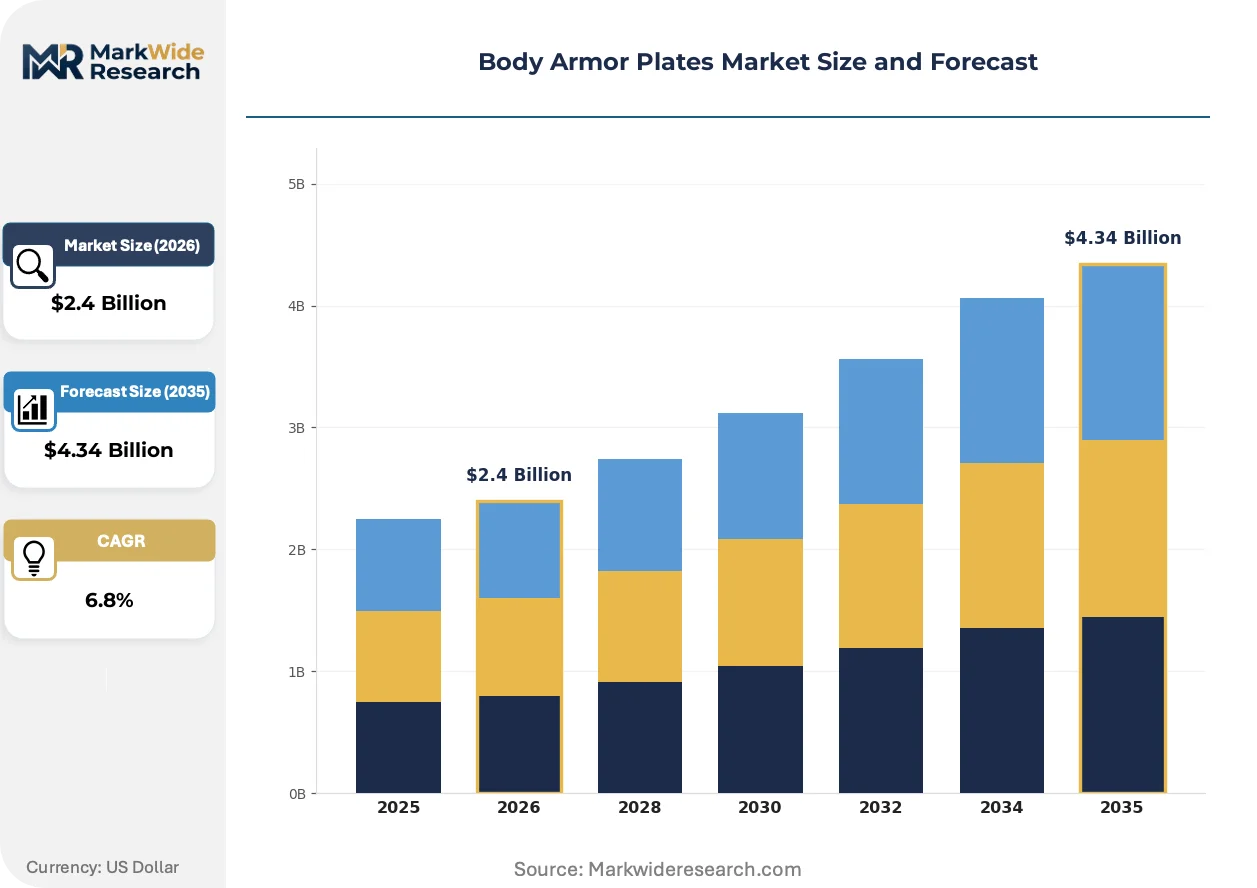
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Steel, Ceramic, Polyethylene, Composite Thickness: 3mm, 5mm, 10mm, 15mm Application: Military, Law Enforcement, Civilian, Security Certification: NIJ Level III, NIJ Level IV, CEN Level 1, CEN Level 2 |
| Companies Covered | Point Blank Enterprises, Inc., Safariland, LLC, BAE Systems plc, Armored Republic, LLC, Ceradyne Inc., AEGIS Engineering Systems, Pacific Safety Products, AR500 Armor, Kejo Limited Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Armor Plates Market Strategic Shifts & Innovations
Material science convergence with digital manufacturing is fragmenting traditional supply hierarchies while compressing development cycles for threat-specific plate configurations.
Ultra-high-molecular-weight polyethylene fiber layup automation is modularizing production economics for multi-hit rated plates. Special operations procurement offices are specifying these systems for dismounted infantry applications where weight thresholds dominate protection priorities. The technology is modularizing supplier entry barriers by reducing dependence on capital-intensive ceramic sintering infrastructure.
REACH chemical substance restrictions are forcing reformulation of composite matrix resins used in polyethylene backing layers. European manufacturers are qualifying alternative thermoset polymers to maintain CE marking eligibility for defense export contracts. Plate suppliers serving NATO dual-use markets are maintaining parallel resin inventories to satisfy divergent regulatory requirements.
Direct-to-agency contracting is displacing layered distribution for law enforcement plate purchases. Municipal procurement offices are leveraging federal grant programs to establish vendor relationships previously mediated by regional equipment distributors. This channel compression is most visible in United States state-level police modernization initiatives where bulk purchase authorization thresholds have risen substantially.
Body Armor Plates Market Segmentation
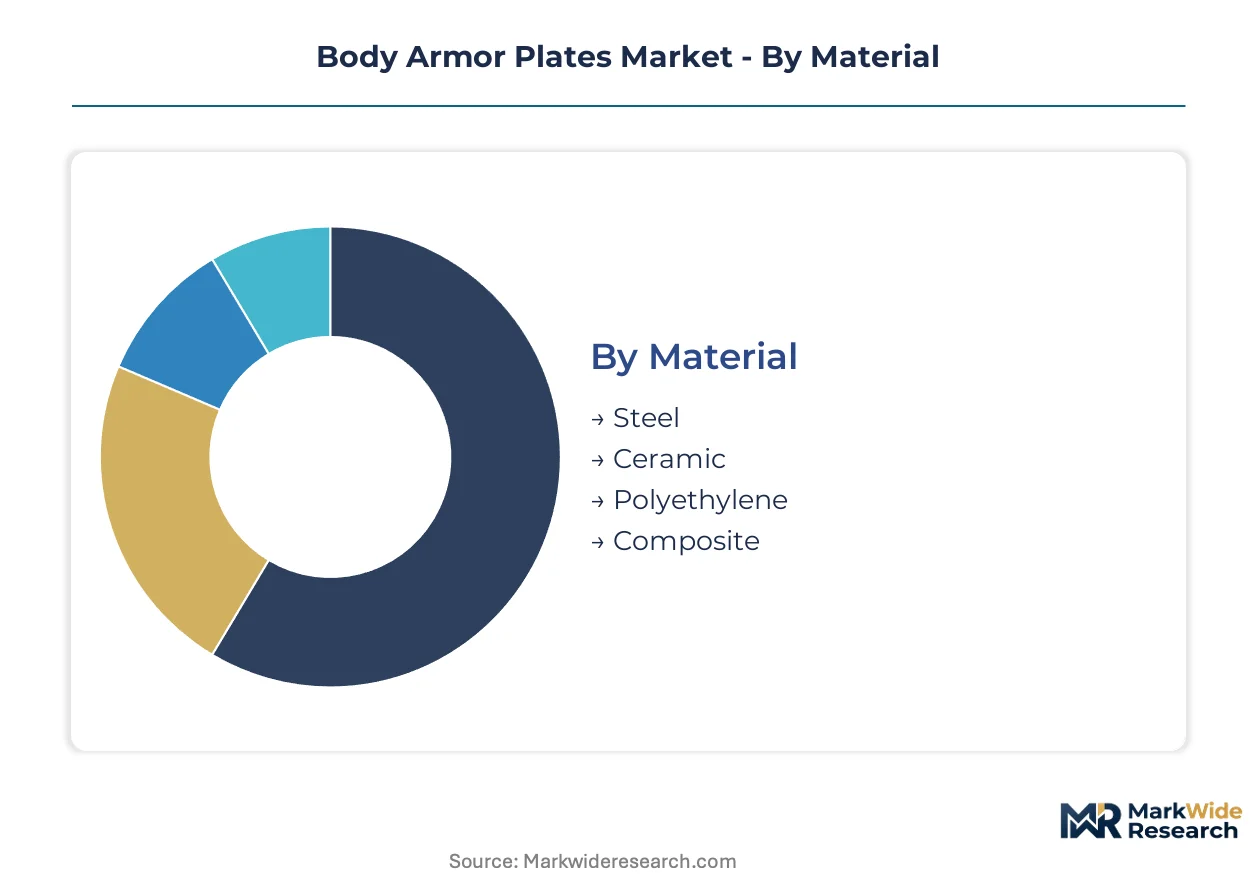
Body armor plate specifications fragment across threat levels, weight constraints, and procurement budgets. Material selection and certification tier determine unit economics and addressable customer pools.
Material:
Ceramic formulations and polymer composites dominate military procurement where weight-to-protection ratios dictate operational effectiveness.
- Steel:Fabricated from hardened alloy plates with highest areal density penalties. Civilian and training markets absorb volume where unit cost sensitivity outweighs mobility requirements.
- Ceramic:Alumina, silicon carbide, and boron carbide strike faces bonded to composite backing achieve NIJ Level IV certification against armor-piercing threats. United States Department of Defense modernization programs specify these configurations for infantry plate carriers.
- Polyethylene:Ultra-high-molecular-weight fiber layups deliver multi-hit protection at reduced weights. Special operations units prioritize these systems for dismounted patrol applications where load carriage limits mission duration.
- Composite:Hybrid ceramic-polyethylene or metal-ceramic laminates optimize specific threat profiles. Premium pricing reflects custom engineering for agency-specific ballistic requirements.
Ceramic leads on scale; polyethylene leads on momentum.
Thickness:
Plate thickness correlates directly with protection level and carrier compatibility constraints.
- 3mm:Handgun-rated inserts for concealed carry applications. Law enforcement undercover units specify these for low-visibility protection.
- 5mm:Intermediate rifle protection at reduced bulk. Security contractors operating in permissive environments favor this specification for extended wear comfort.
- 10mm:Standard infantry plate dimension balancing NIJ Level III coverage against mobility degradation. Bulk procurement contracts standardize on this thickness across NATO member state inventories.
- 15mm:Maximum protection configurations for static defensive positions or vehicle crew applications. Weight penalties restrict deployment to mounted operations.
10mm plates command procurement volume; 5mm configurations are climbing the fastest as security sector demand expands.
Application:
End-user requirements diverge sharply between military threat specifications and civilian legal constraints.
- Military:Armor-piercing defeat capabilities mandated under evolving STANAG protocols. Multi-billion dollar modernization cycles refresh plate inventories across allied defense forces.
- Law Enforcement:NIJ certification compliance drives replacement timelines for municipal and state agencies. Federal grant programs accelerate bulk purchase authorizations.
- Civilian:Legal restrictions vary by jurisdiction, concentrating demand in states with permissive body armor statutes. Steel plates dominate this price-sensitive segment.
- Security:Private sector guarding contracts specify intermediate protection levels. Corporate procurement offices prioritize carrier compatibility over maximum threat defeat.
Military applications anchor revenue concentration; security represents the steepest expansion trajectory as private sector guarding contracts proliferate.
Certification:
Validation tier stratification creates distinct margin pools and qualification barriers.
- NIJ Level III:Rifle-rated protection against standard ball ammunition. State police agencies standardize on this tier for patrol officer equipment.
- NIJ Level IV:Armor-piercing round defeat capability with composite backing requirements. Raw material intensity and testing burdens generate substantially higher unit economics.
- CEN Level 1:European baseline rifle protection standard. Procurement frameworks under the European Defence Fund reference this threshold for cross-border tender eligibility.
- CEN Level 2:Enhanced European specification approaching NIJ Level IV equivalence. Manufacturers maintaining parallel NIJ-CEN qualification programs capture dual-market access.
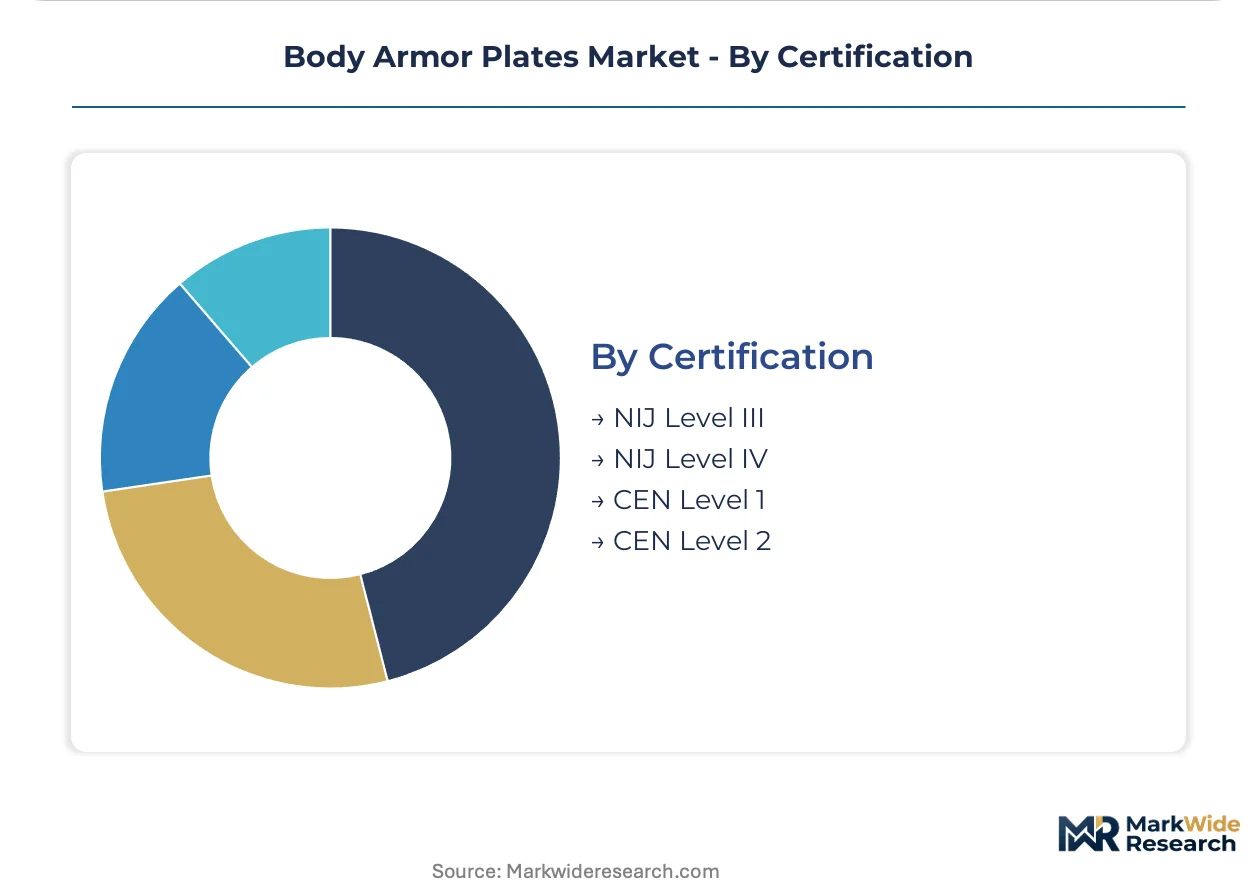
NIJ Level III dominates procurement volume; NIJ Level IV is gaining share fastest as threat assessments escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between NIJ and CEN testing protocols creates compliance-cost arbitrage, drawing production investment toward jurisdictions with consolidated certification pathways. Manufacturers optimize location decisions around proximity to defense procurement offices and ceramic feedstock processing infrastructure.
United States
Department of Defense modernization programs and state-level law enforcement upgrades drive procurement volume. NIJ standard updates mandate replacement timelines for pre-2023 ceramic and polyethylene inventories. Hot isostatic pressing capacity clusters in California and Texas, where technical ceramic foundries serve prime defense contractors.
Germany
European Defence Fund joint procurement frameworks consolidate tender opportunities across member states. REACH chemical substance restrictions force composite matrix resin reformulation for CE marking eligibility. Bavaria hosts advanced ceramics research clusters developing next-generation boron carbide formulations for NATO STANAG compliance.
United Kingdom
Revised threat assessments under bilateral NATO agreements accelerate plate replacement cycles. Ministry of Defence indigenization policies redirect procurement toward certified domestic suppliers. Greater Manchester and West Midlands concentrate law enforcement equipment distribution channels serving municipal agencies.
India
BIS technical specification harmonization with NATO protocols opens import substitution opportunities. Ministry of Defence mandates redirect plate procurement toward certified local manufacturers. Tamil Nadu and Maharashtra industrial corridors attract ceramic processing investment to serve domestic defense procurement.
France
EU joint procurement frameworks create centralized tender eligibility for cross-border defense contracts. ANSM and CNIL oversight extends to dual-use equipment export licensing. Île-de-France defense procurement offices coordinate multi-national plate specifications under European Defence Agency coordination.
Body Armor Plates Market Key Industry Players
United States producers anchor the premium certification tier; European specialists hold position through regulatory proximity to CEN standard-setting bodies. Market structure concentrates around vertically integrated ceramic processors and modular plate carrier integrators. Three archetypes dominate: captive material science programs with direct government contracting relationships, technical ceramic foundries with in-house boron carbide processing, and law enforcement channel specialists with quick-detach mounting geometries. Competitive moves center on parallel NIJ-CEN qualification program maintenance and modular carrier interface standardization.
Within the technical ceramic tier, Ceradyne Inc. and BAE Systems plc exemplify contrasting scale positions—Ceradyne occupying the specialized boron carbide processing niche, BAE Systems representing diversified defense prime contractor integration. Safariland, LLC sits within the law enforcement channel specialist archetype, its positioning tied to modular carrier compatibility specifications rather than raw material processing intensity.
| Leading Market Players |
|---|
| Point Blank Enterprises, Inc. |
| Safariland, LLC |
| BAE Systems plc |
| Armored Republic, LLC |
| Ceradyne Inc. |
| AEGIS Engineering Systems |
| Pacific Safety Products |
| AR500 Armor |
| Kejo Limited Company |
| Others |
Cost & Logistics Intelligence
Ballistic testing engineer scarcity in California and Texas clusters labor-cost differentials that widen pricing-tier spreads between NIJ Level IV premium plates and economy steel alternatives. Specialized sintering technicians command wage premiums that feed into finished plate margins, while law enforcement procurement offices absorb these costs through federal grant buffers.
Pricing Analysis
Distributor margin compression is accelerating direct-to-agency contracting as municipal procurement offices leverage federal grant programs to bypass regional equipment distributors. Three-tier pricing structure across premium, standard, and economy levels stratifies by NIJ certification grade and boron carbide content intensity. Pricing pressure stems from steel plate substitution in civilian markets where unit cost sensitivity outweighs mobility requirements. Security contractors exhibit highest price sensitivity due to corporate procurement budget constraints, while special operations units demonstrate lowest sensitivity given mission-critical weight-to-protection priorities.
Supply Chain Analysis
Regional distribution centers in California, Texas, and Bavaria concentrate finished plate inventory proximal to Department of Defense and NATO procurement offices. Boron carbide feedstock processing anchors in limited geographic zones across the United States and Germany, drawing from alumina and silicon carbide precursor supply chains in China and Australia. Single-source vulnerability in sub-micron grain refinement capacity exposes plate manufacturers to raw material allocation disruptions during defense procurement surges. Distribution runs through prime contractor logistics networks with direct government contracting relationships displacing layered wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through boron carbide processing advances that reduce raw material intensity per plate while commanding premium positioning for multi-hit rated configurations.
For Market Incumbents: Cement captive boron carbide processing capacity through hot isostatic pressing infrastructure expansion in California or Texas clusters, insulating against feedstock allocation disruptions during NATO procurement surges. Deepen parallel NIJ-CEN qualification program maintenance to capture European Defence Fund joint tender eligibility as EU procurement frameworks consolidate. Prioritize quick-detach mounting geometry patents to defend law enforcement channel positioning against modular carrier integrators. For New Entrants and Emerging Players: Ultra-high-molecular-weight polyethylene fiber layup automation offers entry pathways with reduced capital intensity versus ceramic sintering infrastructure. Target security sector guarding contracts in India where BIS technical specification harmonization with NATO STANAG protocols creates import substitution openings for certified local suppliers. Lead with carrier compatibility specifications rather than raw material processing to bypass incumbent foundry advantages. For Investors and Strategic Acquirers: Defense prime contractors with direct government contracting relationships are the most active acquirer in this space, seeking technical ceramic foundries with in-house boron carbide densification capabilities. Five-to-ten year viability hinges on next-generation threat specification readiness as armor-piercing ammunition profiles exceeding current NIJ Level IV thresholds trigger replacement investment cycles. Monitor Ministry of Defence indigenization mandate acceleration in India as inflection indicator for regional production investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Hot Isostatic Pressing Capacity Expansion | Captive boron carbide densification secures supply continuity during NATO procurement surges. |
| Parallel NIJ-CEN Qualification Investment | Dual certification opens European Defence Fund tenders spanning multiple member state requirements. |
| Modular Plate Carrier Interface Standardization | Quick-detach mounting geometries capture law enforcement specification-driven procurement volume. |
| Sub-Micron Grain Refinement R&D | Extended multi-hit performance thresholds attract special operations premium pricing. |
| Direct-to-Agency Contracting Channel Buildout | Federal grant program leverage displaces distributor margins in municipal police modernization. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ceramic foundry operations managers, Department of Defense procurement officers, NIJ certification laboratory directors, and law enforcement equipment purchasing coordinators alongside secondary validation. Customs trade data, SEC 10-K filings from defense prime contractors, NIJ compliance testing records, and NATO STANAG protocol documentation anchored supply-side and demand-side quantification. Bottom-up plate production estimates and top-down defense budget allocation analysis triangulated market sizing.
Historical reference periods spanning pre- and post-NIJ standard update implementation anchored the forecast window calibration across the projection horizon. Segmentation modeling incorporated material formulation, certification tier, thickness specification, and end-use application dimensions with regional procurement office proximity as an industry-specific overlay. CAGRs derived from threat assessment-driven replacement cycle compression and indigenization policy acceleration. Boron carbide processing capacity utilization rates and federal grant program authorization trajectories served as forward-looking inputs.
The model holds under sustained NATO threat reassessment trajectories and stable boron carbide feedstock allocation; deviation in REACH chemical substance restriction scope or armor-piercing ammunition specification thresholds would shift replacement cycle assumptions. Forecasts reflect documented base conditions with acknowledged sensitivity to ceramic sintering capital commitment delays and ballistic testing engineer availability constraints. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Physical Security
Europe Physical Security Market
Physical Security
Border Security Technologies Market
Physical Security
South America Data Center Physical Security Market
Physical Security
Tactical Lights Market
Physical Security
Europe Cargo Inspection Market
Physical Security
Body Armor Market
Physical Security
Security Guard Market
Physical Security
France Data Center Physical Security Market
Physical Security
Global Physical Security Information Management Market
Physical Security
Poland Data Center Physical Security Market
Physical Security
Policing Technologies Market
Physical Security
Tactical Vests Market
Physical Security
Physical Security Market
Physical Security
Smart Police Helmet Market
Physical Security
Bulletproof Glass Market
Physical Security
North America Physical Security Market