
 Safety IO Modules Market | 2026-2036
Safety IO Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Safety IO Modules Market Analytics
The capability gap between vertically integrated automation conglomerates and component-focused specialists is rotating capital allocation toward in-house semiconductor and firmware development. Siemens AG leverages its captive foundry relationships to sustain margin control across SIL 3-certified module lines. Rockwell Automation Inc. anchors North American demand through FactoryTalk-integrated safety I/O portfolios. Pilz GmbH & Co. KG differentiates by competing exclusively within machinery safety niches, occupying a defensible position in European automotive press lines.
Safety IO modules are electromechanical interface devices that condition, isolate, and transmit discrete or analog signals between field sensors and safety-rated controllers, typically achieving response times below 10 milliseconds and SIL 3/PLe certification under IEC 61508 and ISO 13849. These modules serve as the physical layer enabling emergency stop chains, light curtain monitoring, and safe torque-off circuits in automated environments. I/O modules dominate unit volume due to their ubiquity across every safety architecture, while Safety Instrumented Systems command premium positioning through specialized diagnostics and redundant channel architectures. Process automation applications absorb the largest value share, though emergency shutdown systems in hydrocarbon processing exhibit the steepest growth trajectory as brownfield facilities retrofit aging relay logic.
The EU Machinery Directive and CE marking requirements mandate third-party-validated safety functions for industrial equipment placed on the European market, directly conditioning module design and certification costs. In the United States, OSHA lockout/tagout enforcement and NHTSA-influenced factory safety protocols elevate demand for hardwired safety I/O in automotive assembly. China's GB standards and MIIT industrial safety guidelines are converging toward IEC harmonization, reshaping import qualification pathways. Stakeholders must monitor regulatory divergence between functional safety standards and cybersecurity mandates as modules gain native Ethernet connectivity.
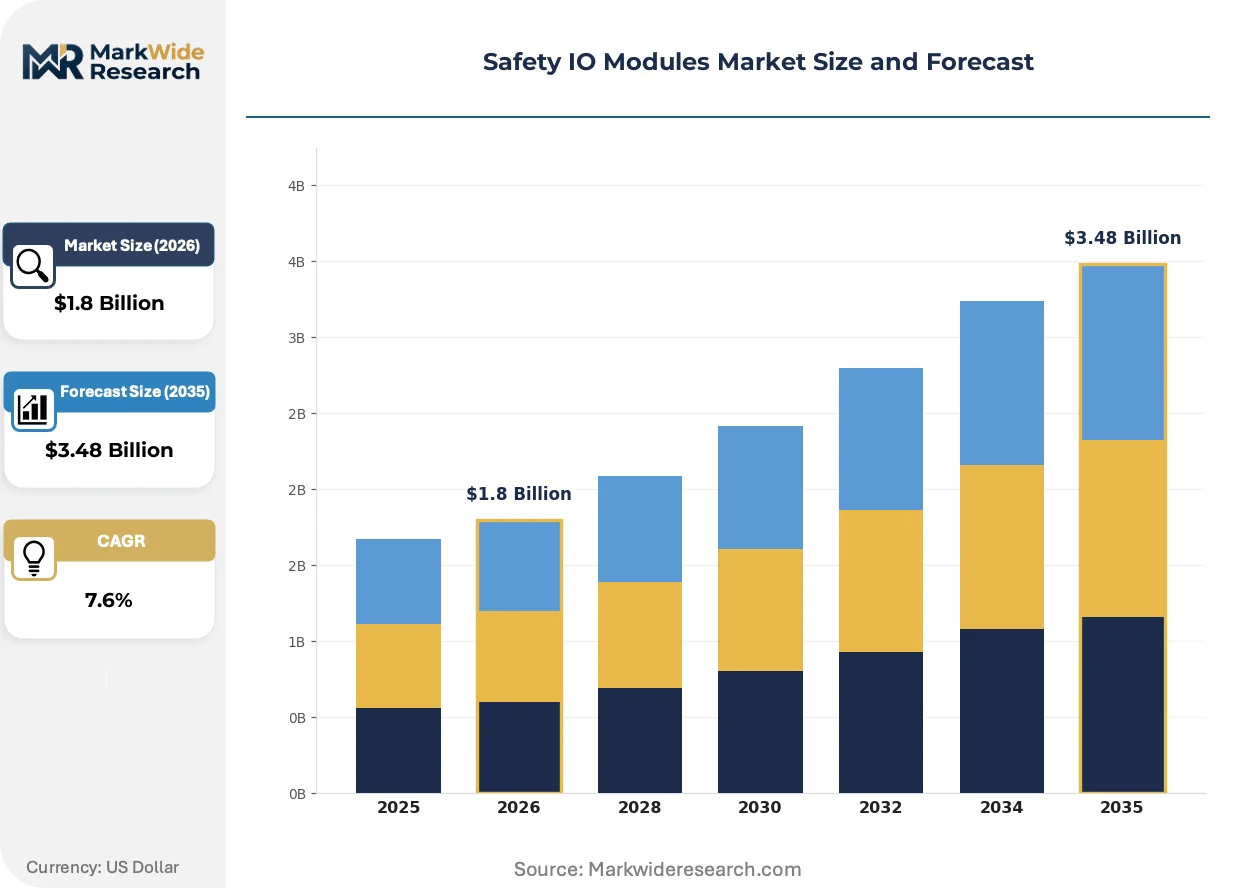
Market Dynamics
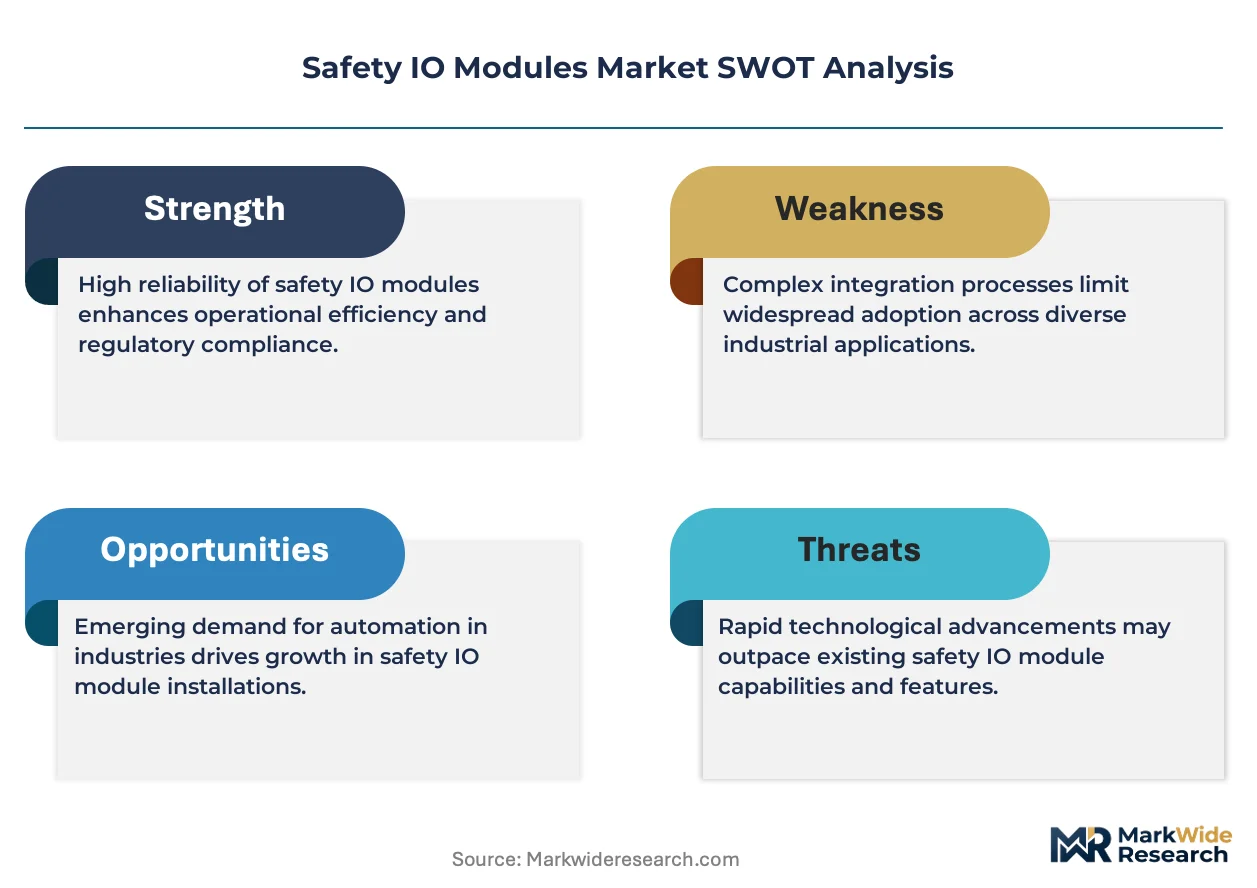
Functional safety certification under IEC 61508 and ISO 13849 is compressing vendor margins while fragmenting procurement authority between plant engineering teams and corporate IT security functions. This tension is forcing module suppliers to absorb firmware development costs that previously sat with system integrators.
Growth Catalysts
- EU Machinery Directive compliance:CE marking mandates for third-party-validated safety functions are accelerating replacement cycles in European automotive press lines and metalworking facilities.
- Brownfield hydrocarbon retrofit:Emergency shutdown system upgrades across aging North Sea and Gulf of Mexico platforms are absorbing SIL 3-certified distributed I/O architectures.
- China's chemical processing corridor:GB standard harmonization with IEC frameworks is opening import qualification pathways for certified modules in Sinopec and PetroChina facilities.
Market Restraints
- Semiconductor supply concentration:Captive foundry relationships at vertically integrated automation conglomerates limit second-source options for fabless safety module specialists.
- Firmware development cost inflation:SIL-rated diagnostic algorithms require specialized embedded engineering talent that concentrates in Germany and Japan.
- Relay logic substitution ceiling:Hardwired safety circuits in legacy automotive body shops resist Ethernet-IP retrofit due to technician familiarity and maintenance protocol inertia.
Strategic Opportunities
- India's PLI scheme for automation:Production-linked incentives for advanced manufacturing equipment are creating localized assembly demand for cost-optimized safety I/O modules.
- Cybersecurity-integrated certification:Convergence between IEC 62443 industrial security standards and functional safety protocols offers premium positioning for dual-certified module lines.
- Aftermarket diagnostics unbundling:Remote condition monitoring services are opening recurring revenue streams independent of hardware replacement cycles.
Industry Challenges
- Functional safety engineer scarcity:TÜV-certified firmware architects command compensation premiums that strain R&D budgets at mid-tier module suppliers.
- Legacy controller integration friction:Proprietary fieldbus protocols in installed base safety PLCs complicate multi-vendor I/O module deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety IO Modules Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: I/O Modules, Control Modules, Relay Modules, Signal Modules End User: Manufacturing Facilities, Oil & Gas Industries, Water Treatment Plants, Power Generation Units Technology: Distributed Control Systems, Programmable Logic Controllers, Safety Instrumented Systems, Supervisory Control and Data Acquisition Application: Process Automation, Industrial Safety, Monitoring Systems, Emergency Shutdown Systems |
| Companies Covered | ABB Ltd., Siemens AG, Rockwell Automation Inc., Schneider Electric, Honeywell International Inc., Advantech Co. Ltd., Weidmüller Interface GmbH & Co. KG, Pilz GmbH & Co. KG, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety IO Modules Market Evolving Landscape
Ethernet-APL physical layer technology is collapsing the distance between process instrumentation and safety controllers. This convergence is redrawing competitive boundaries between traditional discrete safety I/O vendors and process automation specialists.
Single-pair Ethernet with advanced physical layer (SPE-APL) is bifurcating the safety I/O market between high-density channel modules for greenfield facilities and retrofit adapters for legacy 4-20mA installations. Hydrocarbon processing operators in the North Sea are piloting SPE-APL safety instrumented functions at ten-kilometer cable runs. The technology is bifurcating procurement patterns as engineering contractors specify native SPE-APL modules for new builds while maintenance teams demand backward-compatible gateways for brownfield extensions.
The EU AI Act's risk classification framework is extending documentation requirements to safety I/O modules with embedded diagnostic algorithms. German automotive OEMs now require algorithmic transparency declarations for SIL-certified modules used in collaborative robot cells. Tier-1 suppliers are responding by segregating firmware development environments and engaging notified bodies earlier in the design cycle.
Buyer consolidation among European automotive OEMs is compressing vendor qualification timelines and unbundling after-sales service contracts from hardware procurement. Plant engineering teams at Volkswagen Group and Stellantis facilities are demanding fixed-price commissioning support separate from module unit pricing. This pattern is most visible in German and Czech assembly plants where multi-brand safety architectures complicate single-source maintenance agreements.
Safety IO Modules Market Segmentation
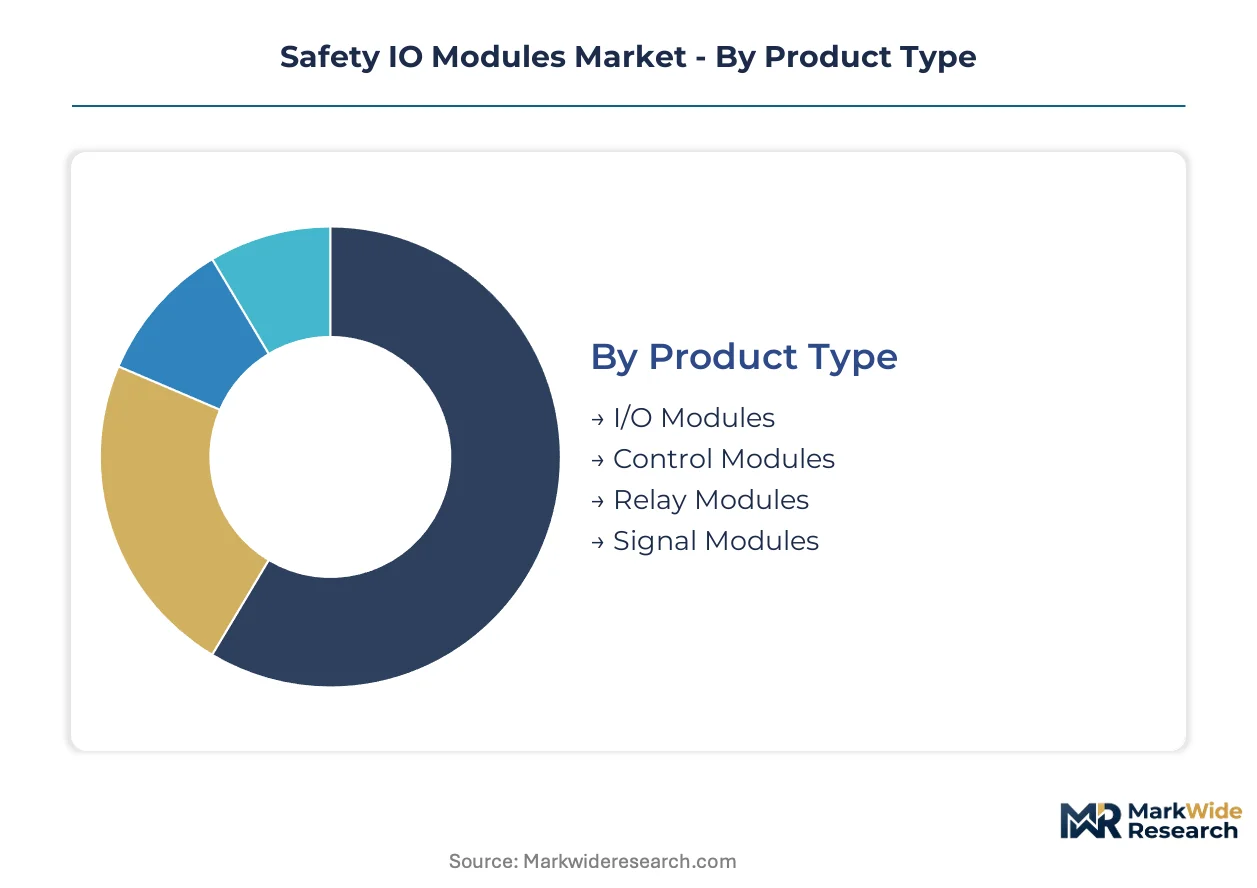
Margin pools in safety I/O modules concentrate where certification complexity meets high-channel-density requirements. Understanding how product architectures, end-use environments, and control technologies fragment demand reveals where suppliers can defend pricing power against commoditization pressure.
Product Type:
Margin concentration tracks directly to firmware complexity and diagnostic sophistication across module categories.
- I/O Modules:These electromechanical interfaces condition discrete and analog signals between field sensors and safety-rated controllers, achieving response times below 10 milliseconds. Demand concentrates in German and Japanese automotive manufacturing facilities expanding their adoption of safety-certified distributed I/O architectures. Tightening compliance requirements for SIL-rated modules under IEC 61508 elevate procurement scrutiny.
- Control Modules:Embedded processing units execute safety logic with redundant channel architectures and specialized diagnostic routines. China's chemical processing corridor absorbs the largest value share as Sinopec and PetroChina facilities retrofit aging relay logic with SIL 3-certified distributed systems.
- Relay Modules:Electromechanical switching devices providing galvanic isolation in hardwired safety circuits.
- Signal Modules:Conditioning units for analog transmission in legacy 4-20mA installations.
The dominant share belongs to I/O Modules, while Control Modules is closing the gap fastest.
End User:
Application severity and regulatory exposure determine willingness to pay for certified architectures across customer types.
- Manufacturing Facilities:Automotive press lines and metalworking facilities in Germany and the Czech Republic drive replacement cycles as EU Machinery Directive compliance mandates accelerate. Volkswagen Group and Stellantis facilities demand fixed-price commissioning support separate from hardware unit pricing.
- Oil & Gas Industries:Emergency shutdown system upgrades across aging North Sea and Gulf of Mexico platforms absorb SIL 3-certified distributed I/O architectures. Brownfield hydrocarbon retrofit exhibits the steepest expansion trajectory as facilities replace aging relay logic.
- Water Treatment Plants:Municipal and industrial facilities requiring SIL-rated monitoring for chemical dosing and filtration safety.
- Power Generation Units:Thermal and renewable generation assets with turbine protection and grid synchronization requirements.
Manufacturing Facilities commands the largest installed base, though Oil & Gas Industries is gaining share fastest on retrofit intensity.
Technology:
Procurement authority fragmentation between plant engineering and corporate IT security functions reshapes technology selection criteria.
- Distributed Control Systems:Architectures decentralizing I/O processing across field-mounted modules with centralized supervisory logic. German automotive OEMs now require algorithmic transparency declarations for SIL-certified modules used in collaborative robot cells under the EU AI Act's risk classification framework.
- Programmable Logic Controllers:Ruggedized controllers executing safety logic with deterministic scan times. North American demand anchors through FactoryTalk-integrated safety I/O portfolios as OSHA lockout/tagout enforcement elevates hardwired safety requirements.
- Safety Instrumented Systems:Purpose-built architectures with specialized diagnostics and redundant channel configurations commanding premium positioning.
- Supervisory Control and Data Acquisition:Layered monitoring platforms aggregating safety I/O data for enterprise visibility.
Distributed Control Systems holds the dominant position, while Safety Instrumented Systems is expanding most quickly on hydrocarbon sector demand.
Application:
Functional safety certification costs compress vendor margins most acutely where diagnostic requirements are most stringent.
- Process Automation:Continuous manufacturing environments requiring SIL-rated feedback loops for temperature, pressure, and flow control. GB standard harmonization with IEC frameworks in China is opening import qualification pathways for certified modules.
- Industrial Safety:Personnel protection systems including emergency stop chains, light curtain monitoring, and safe torque-off circuits. European automotive press lines absorb concentrated demand as CE marking mandates accelerate replacement cycles.
- Monitoring Systems:Condition-based maintenance platforms with predictive diagnostic capabilities.
- Emergency Shutdown Systems:Final element control for process isolation in high-consequence events.
Process Automation captures the largest value share, while Emergency Shutdown Systems is climbing the fastest on brownfield retrofit momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: German automotive OEMs prioritize SIL 3-certified distributed architectures, while Chinese chemical processors favor cost-optimized modules for brownfield retrofit, and US hydrocarbon operators absorb premium emergency shutdown systems for offshore platform upgrades.
Germany
Volkswagen Group and Stellantis facilities in Wolfsburg and Stuttgart drive concentrated demand for fixed-price commissioning support separate from hardware procurement. The EU Machinery Directive and CE marking requirements mandate third-party-validated safety functions for industrial equipment. Bavarian automotive press lines absorb the steepest replacement cycles as compliance mandates accelerate.
China
Sinopec and PetroChina facilities across the chemical processing corridor absorb the largest value share for SIL-rated modules. GB standards harmonization with IEC frameworks under MIIT industrial safety guidelines reshapes import qualification pathways. Yangtze River Delta chemical clusters retrofit aging relay logic with certified distributed I/O architectures.
United States
Emergency shutdown system upgrades across aging Gulf of Mexico platforms command premium positioning for SIL 3-certified architectures. OSHA lockout/tagout enforcement and NHTSA-influenced factory safety protocols elevate hardwired safety I/O demand in automotive assembly. Texas and Louisiana hydrocarbon processing facilities exhibit the steepest brownfield retrofit momentum.
Japan
METI industrial safety guidelines and JIS standards convergence with IEC 61508 elevate procurement scrutiny for certified modules. Automotive manufacturing facilities in Toyota City and Yokohama expand adoption of safety-certified distributed I/O architectures. Kanto and Chubu regions concentrate demand for sub-10-millisecond response time specifications.
India
Production-linked incentive schemes for advanced manufacturing equipment create localized assembly demand for cost-optimized safety I/O modules. BIS standards alignment with functional safety protocols conditions module design requirements. Maharashtra and Gujarat automotive clusters pilot SIL 2-certified architectures for collaborative robot cells.
Safety IO Modules Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with vertically incorporated automation conglomerates controlling captive semiconductor supply against fabless component specialists. Siemens AG leverages in-house foundry relationships to sustain margin control across certified module lines. Three archetypes dominate: integrated automation conglomerates with captive silicon supply, machinery safety specialists occupying defensible niches, and distributed control system anchors with FactoryTalk-integrated portfolios. Competitive moves concentrate on firmware development cost absorption and dual-certification convergence between functional safety and cybersecurity standards.
Among German-integrated conglomerates, Siemens AG and Pilz GmbH & Co. KG exemplify divergent strategic positioning. Siemens occupies the scale-driven tier through captive supply chain control, while Pilz represents the machinery safety specialist archetype competing exclusively within European automotive press lines. Rockwell Automation Inc. anchors North American demand architecture through integrated safety I/O portfolios. These three entities collectively illustrate how geographic origin and corporate structure shape competitive boundaries without requiring identical capability investments.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Rockwell Automation Inc. |
| Schneider Electric |
| Honeywell International Inc. |
| Advantech Co. Ltd. |
| Weidmüller Interface GmbH & Co. KG |
| Pilz GmbH & Co. KG |
| Emerson Electric Co. |
| Others |
Value Network & Pricing Analysis
IEC 61508 SIL certification gates both supplier qualification and price stratification, compressing margins for uncertified competitors while rewarding firmware-intensive module architectures with sustained pricing power. TÜV-validated diagnostic algorithms concentrate in German and Japanese engineering teams, creating geographic cost asymmetries that ripple through procurement negotiations.
Pricing Analysis
Long-term framework agreements dominate procurement between automotive OEMs and tier-1 module suppliers, though spot purchasing persists for brownfield retrofit projects. Pricing stratifies across SIL 3-certified premium tiers, SIL 2-standard configurations, and cost-optimized economy modules for non-safety applications. Cost compression in standard-tier modules is intensifying as Chinese chemical processors drive volume procurement. Manufacturing facilities in automotive press lines exhibit the lowest price sensitivity, while municipal water treatment operators in India demonstrate acute cost consciousness.
Supply Chain Analysis
Germany and Japan anchor firmware development and TÜV certification services for safety-rated diagnostic algorithms. Taiwan and South Korea feed semiconductor foundry capacity for embedded safety controllers. The supply chain draws from specialized analog component suppliers in the United States for galvanic isolation devices. Single-source vulnerability concentrates in TÜV-certified firmware architect talent pools. Distribution runs through authorized system integrator channels with direct OEM relationships in automotive and hydrocarbon sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of TÜV-certified functional safety engineers concentrates capability premiums in incumbent engineering teams, creating defensive moats that new entrants must circumvent through certification shortcuts or geographic arbitrage.
For Market Incumbents: Secure captive firmware development capacity in Germany and Japan to maintain margin control against fabless specialists. Deepen backward integration into semiconductor sourcing through foundry partnerships, insulating against supply concentration risks. Fortify SIL 3 certification portfolios as the EU AI Act extends documentation requirements to embedded diagnostic algorithms. For New Entrants and Emerging Players: TÜV Rheinland fast-track certification programs in India open qualification pathways for cost-optimized module lines targeting PLI scheme beneficiaries. India's automotive clusters in Maharashtra and Gujarat present the most penetrable white-space for SIL 2-certified collaborative robot applications. Pursue aftermarket diagnostics unbundling as a recurring revenue wedge independent of hardware replacement cycles. For Investors and Strategic Acquirers: The EU AI Act's risk classification framework reshapes the acquisition landscape by elevating algorithmic transparency requirements above pure hardware scale. Five-to-ten-year viability favors targets with dual IEC 61508 and IEC 62443 certification pipelines. Monitor GB standard harmonization progress in China as the inflection signal for import qualification pathway stability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Convergence | Simultaneous IEC 61508 and IEC 62443 validation opens premium positioning in German automotive OEM specifications. |
| Aftermarket Diagnostics Unbundling | Remote condition monitoring services generate recurring revenue independent of hardware replacement at Sinopec facilities. |
| SPE-APL Physical Layer Integration | Single-pair Ethernet modules capture ten-kilometer cable run specifications in North Sea hydrocarbon platforms. |
| India PLI Localization | Cost-optimized SIL 2 assembly for Maharashtra automotive clusters reduces import dependency exposure. |
| Captive Firmware Development | In-house TÜV-certified engineering teams in Stuttgart and Yokohama sustain margin control against fabless competitors. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at automotive OEMs, safety system integrators, TÜV certification auditors, and hydrocarbon facility maintenance directors, then refined through secondary validation. Sources included IEC 61508 certification databases, EU Machinery Directive enforcement records, SEC filings from listed automation conglomerates, and customs trade data for safety I/O module imports. Bottom-up channel checks across German automotive press lines and Chinese chemical processing corridors were triangulated against top-down market sizing.
Variance decomposition across product type, end-user vertical, control technology architecture, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers. Modeled inputs included SIL certification pipeline velocities, brownfield retrofit project backlogs in Gulf of Mexico platforms, and PLI scheme uptake rates in Indian automotive clusters.
Underlying assumptions cover sustained IEC 61508 harmonization with China's GB standards and stable semiconductor foundry pricing, with deviation risk concentrated in TÜV certification auditor availability and EU AI Act implementation timelines. Recalibration cycles align with material shifts in functional safety standard revisions and cybersecurity mandate convergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Protective Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
China Premium Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsic Safety Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market