
 Gas Mask Market | 2026-2036
Gas Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Mask Market Analysis
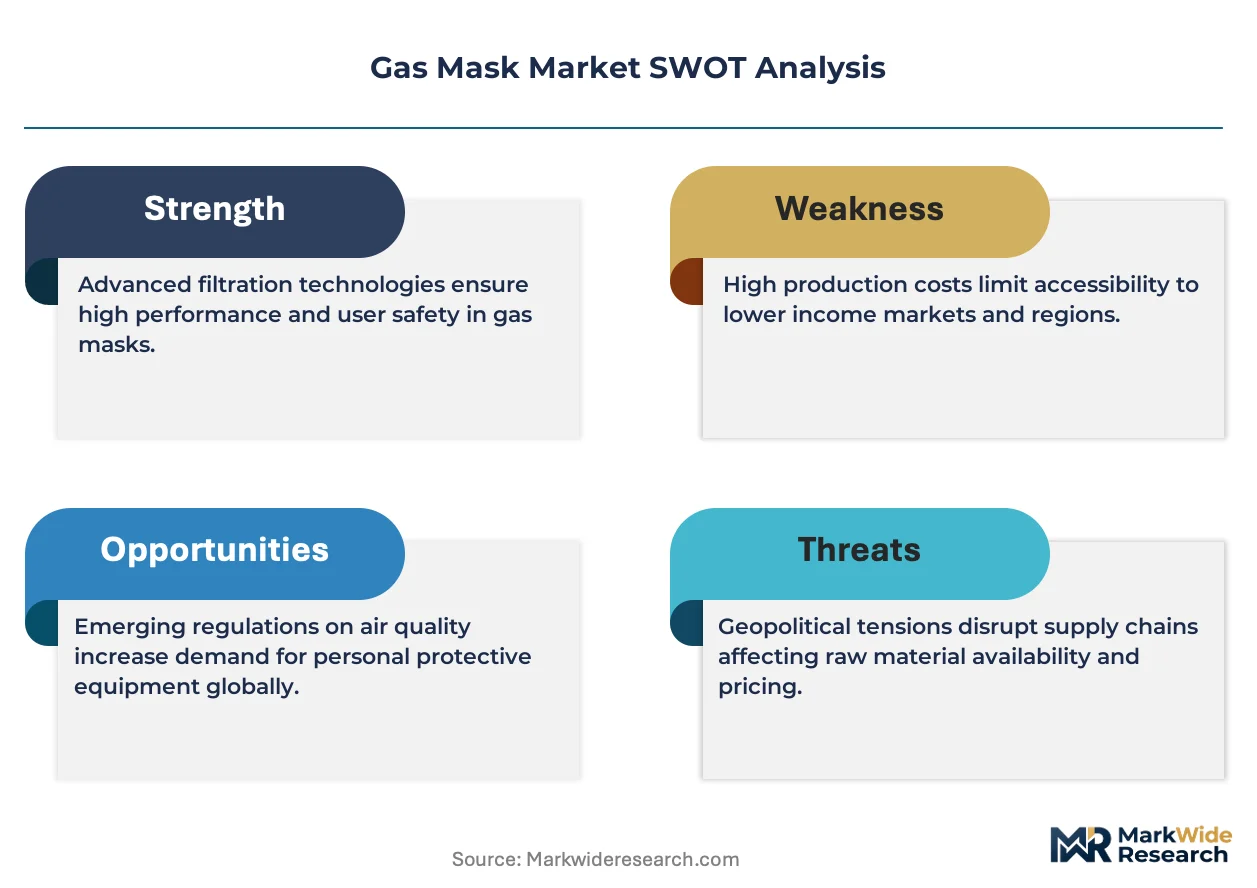
Industrial safety managers is rotating procurement emphasis from basic compliance-grade respirators toward integrated communication-enabled systems. MSA Safety Incorporated leverages its vertical integration in sensor technology to anchor premium positioning. Drägerwerk AG & Co. KGaA sustains manufacturing scale across European and North American plants. Honeywell International Inc. differentiates through dual-use platforms serving military and civilian emergency response channels.
A gas mask is a tight-fitting respiratory protective device employing activated carbon beds, HEPA filtration media, and elastomeric seals to remove airborne contaminants, toxic gases, and particulate matter from the breathing zone of the wearer. Full-face mask configurations dominate military and chemical defense applications due to superior eye protection and higher assigned protection factors, though powered air purifying respirators represent the fastest-growing category as industrial employers seek reduced breathing resistance during extended wear cycles. The activated carbon technology segment commands the largest share of material value, while chemical absorption systems capture margin pools in specialized threat scenarios requiring multi-gas capability.
NIOSH certification requirements in the United States and CE marking under the EU Personal Protective Equipment Regulation shape product development timelines and testing expenditures for manufacturers seeking cross-border market access. OSHA respiratory protection standards and EPA chemical emergency preparedness mandates compel industrial end users to maintain fit-tested inventory, sustaining replacement demand. Stakeholders must monitor evolving CBRN threat assessments and filter standard revisions to align R&D allocation with procurement specifications.
Market Dynamics
The convergence of military modernization cycles and industrial safety mandates is compressing replacement timelines while forcing dual-certification investments across NATO procurement frameworks and OSHA enforcement jurisdictions.
Growth Catalysts
- CBRN threat reassessment protocols:NATO member states are mandating refresh cycles for personal protective equipment inventories, driving volume commitments through defense procurement channels.
- OSHA respiratory protection enforcement:Industrial facility audits in the United States are compelling employers to upgrade from half-mask respirators to full-face configurations with higher assigned protection factors.
- Activated carbon bed engineering:Manufacturers are extending filter service life through improved impregnation chemistries, reducing total cost of ownership for hazardous materials response teams.
Market Restraints
- Butyl rubber supply concentration:Elastomeric seal production depends on petrochemical feedstocks concentrated in Gulf Coast refining clusters, exposing margin structures to feedstock volatility.
- NIOSH certification backlog:Testing laboratory capacity constraints in the United States are extending product launch timelines by eight to fourteen months for new filter cartridge designs.
- Powered air purifying respirator substitution:Industrial employers facing extended wear scenarios are redirecting capital toward battery-driven positive-pressure systems that reduce breathing resistance.
Strategic Opportunities
- Urban emergency preparedness programs:Civil defense agencies in Germany and France are building strategic stockpiles of civilian-grade masks, creating demand outside military procurement channels.
- Integrated communication architectures:Voice projection units and bone-conduction headsets are converging with mask platforms, enabling premium pricing for tactical law enforcement applications.
- EU PPE Regulation harmonization:CE marking mutual recognition agreements are simplifying cross-border distribution for manufacturers holding valid EU type-examination certificates.
Industry Challenges
- Fit testing technician scarcity:OSHA-compliant qualitative and quantitative fit testing requires certified personnel, creating bottlenecks for industrial end users managing large workforces.
- Legacy inventory interoperability:Filter cartridge threading standards vary across NATO, EN, and proprietary systems, complicating logistics for multinational defense contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Mask Market |
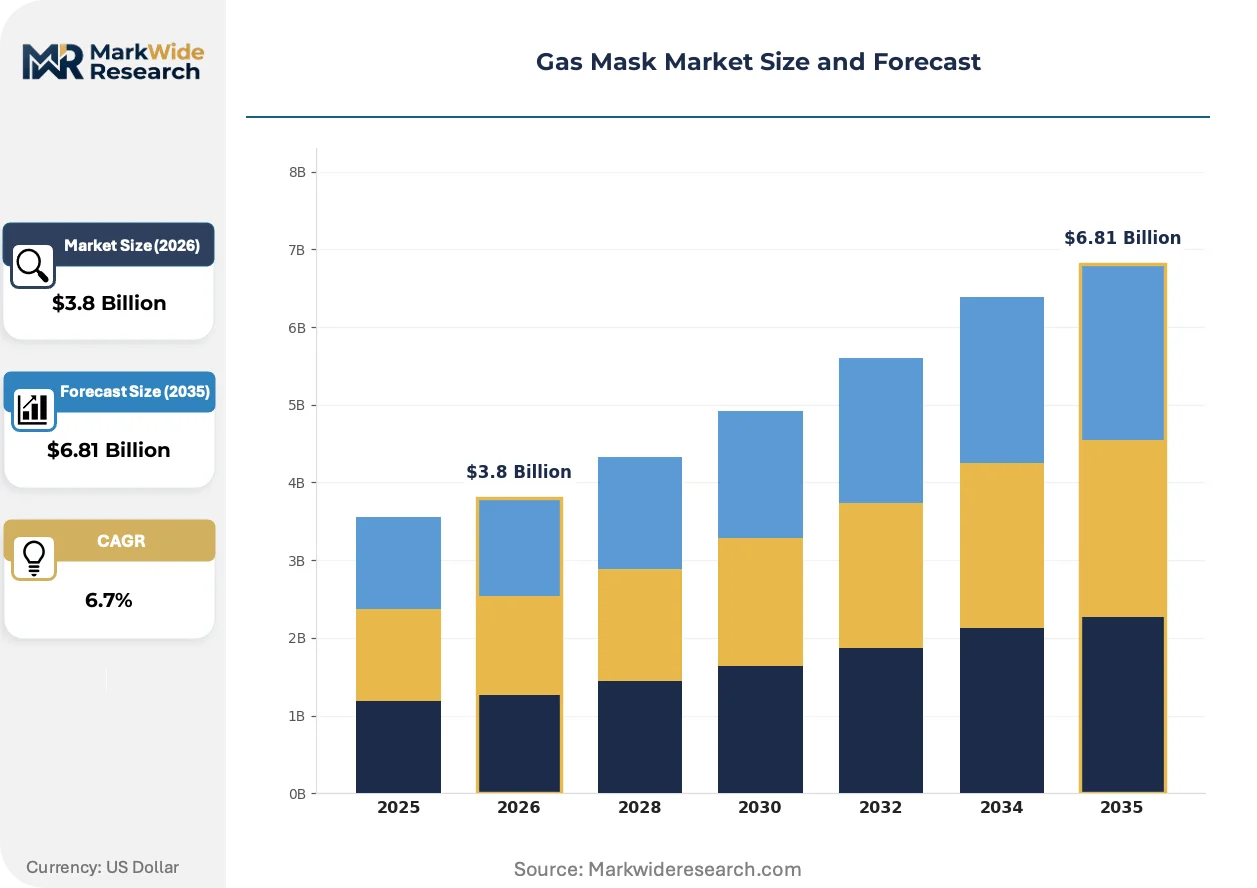
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Face Mask, Half-Face Mask, Powered Air Purifying Respirator, Escape Mask End User: Military, Firefighters, Industrial Workers, Emergency Responders Technology: Activated Carbon, HEPA Filters, Chemical Absorption, Air Supply Systems Usage: Chemical Defense, Biological Threats, Industrial Applications, Emergency Situations |
| Companies Covered | MSA Safety Incorporated, Bullard Enterprises, 3M Company, RPB Safety LLC, Moldex-Metric, Inc., Honeywell International Inc., Avon Protection, Gentex Corporation, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Mask Market Emerging Trajectories
Material science advances and regulatory harmonization efforts are reconfiguring product architectures while compressing the gap between military specification and industrial commercialization.
Modular filter cartridge systems are decomposing the traditional single-use paradigm by enabling field-replaceable components that extend platform service life. Chemical defense units in Poland and the Czech Republic are piloting these architectures for rapid threat adaptation. The technology is decomposing established supplier relationships by allowing third-party cartridge compatibility with legacy mask bodies.
REACH authorization requirements for chromium compounds are forcing reformulation of activated carbon impregnation chemistries used in multi-gas filters. Manufacturers are accelerating alternative metal salt development to maintain CE marking compliance. Specialty chemical defense procurement in the Netherlands and Belgium is experiencing the most acute transition pressure due to earlier adoption of strict exposure limits.
Industrial safety managers are unbundling mask procurement from filter supply contracts, creating separate vendor relationships for platform and consumable procurement. This pattern disrupts traditional full-system suppliers and elevates specialist filter manufacturers. The shift is most visible in United States petrochemical facilities along the Texas and Louisiana Gulf Coast, where volume purchasing consortia are consolidating filter procurement across multiple operating sites.
Gas Mask Market Segmentation
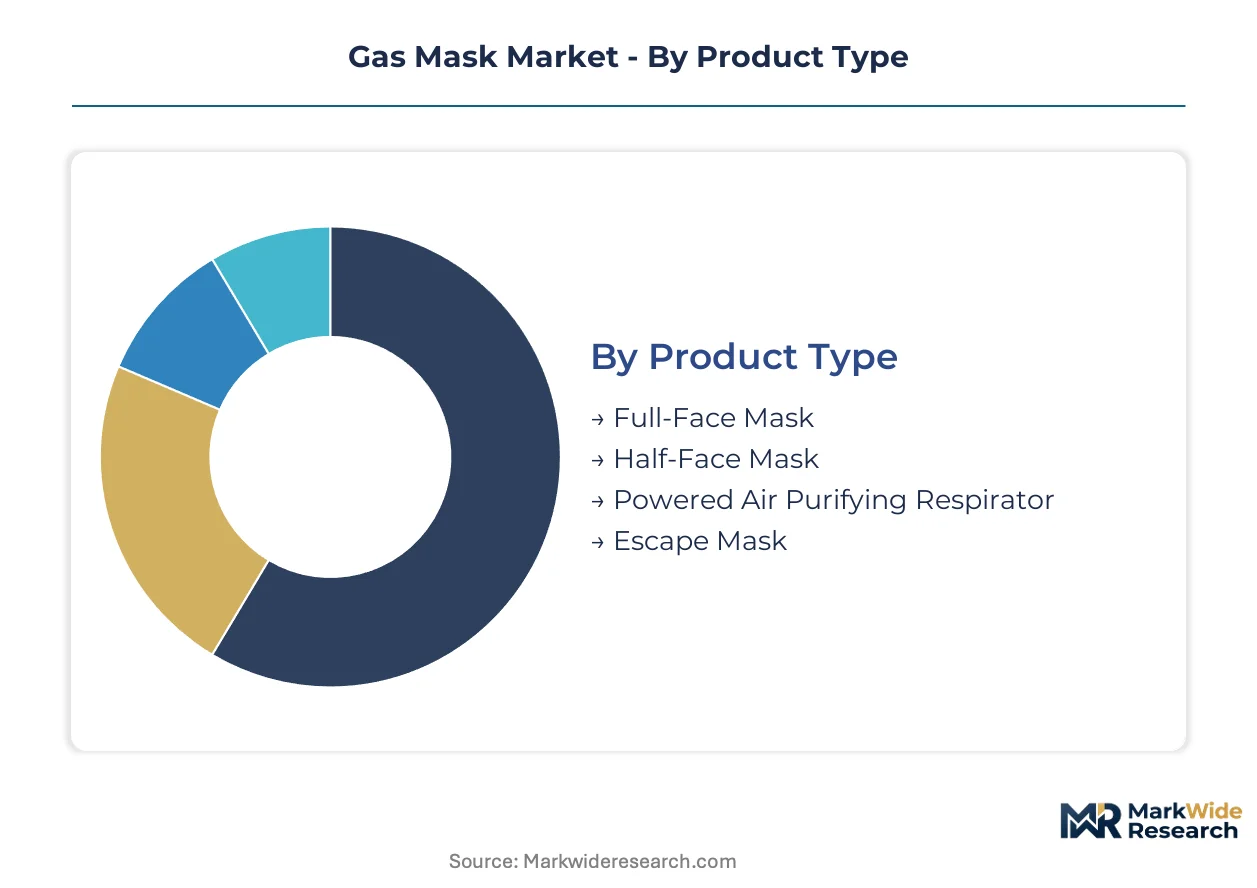
Gas mask procurement channels fragment sharply across certification regimes and threat scenarios. NIOSH, CE marking, and NATO standardization create distinct product qualification pathways that manufacturers must navigate simultaneously.
Product Type:
NIOSH assigned protection factors and CE marking categories differentiate mask architectures for military versus industrial deployment.
- Full-Face Mask:Elastomeric seals and panoramic visor configurations deliver the highest assigned protection factors under NIOSH 42 CFR 84. Military modernization programs in the United States and Germany concentrate procurement here due to integrated eye protection requirements against CBRN threats.
- Powered Air Purifying Respirator:Battery-driven positive-pressure systems reduce breathing resistance through motor-assisted airflow. Industrial employers in Texas and Louisiana petrochemical corridors are redirecting capital toward these platforms for extended wear scenarios.
- Half-Face Mask:Lightweight elastomeric designs serve industrial compliance at lower price points.
- Escape Mask:Compact single-use units target emergency egress from contaminated facilities.
Full-face configurations handle the majority of defense procurement volume; powered air purifying respirators are expanding most quickly in industrial channels.
End User:
Customer procurement cycles diverge across defense budgeting timelines and OSHA enforcement rhythms.
- Military:NATO member states mandate refresh cycles for personal protective equipment inventories, driving multi-year volume commitments through defense procurement frameworks. Poland and Czech Republic chemical defense units are piloting modular cartridge architectures for rapid threat adaptation.
- Industrial Workers:OSHA respiratory protection standards compel facility managers to maintain fit-tested inventory across hazardous materials handling operations. Texas and Louisiana Gulf Coast petrochemical facilities are consolidating filter procurement through volume purchasing consortia.
- Firefighters:Urban emergency preparedness programs in Germany and France are building strategic stockpiles of civilian-grade masks for civil defense agencies.
- Emergency Responders:Hazmat teams require rapid-deployment capabilities with multi-gas filter compatibility.
Military end users dominate absolute procurement value; industrial worker segments are climbing the fastest on replacement cycle compression.
Technology:
Material science advances and REACH authorization requirements are forcing reformulation of core filtration chemistries.
- Activated Carbon:Impregnated carbon beds remove toxic gases through physical adsorption and chemical reaction. REACH authorization requirements for chromium compounds are forcing alternative metal salt development to maintain CE marking compliance, with Dutch and Belgian specialty chemical defense procurement experiencing acute transition pressure.
- Chemical Absorption:Multi-gas capability filters capture margin pools in specialized threat scenarios requiring protection against ammonia, chlorine, and hydrogen sulfide simultaneously. These systems command premium positioning in chemical defense applications.
- HEPA Filters:High-efficiency particulate arresting media target biological aerosol threats.
- Air Supply Systems:Self-contained breathing apparatus configurations serve oxygen-deficient environments.
Activated carbon platforms anchor the majority of installed base value; chemical absorption systems are gaining share fastest in specialized defense procurement.
Usage:
Threat assessment protocols and industrial safety mandates create distinct performance specification tiers.
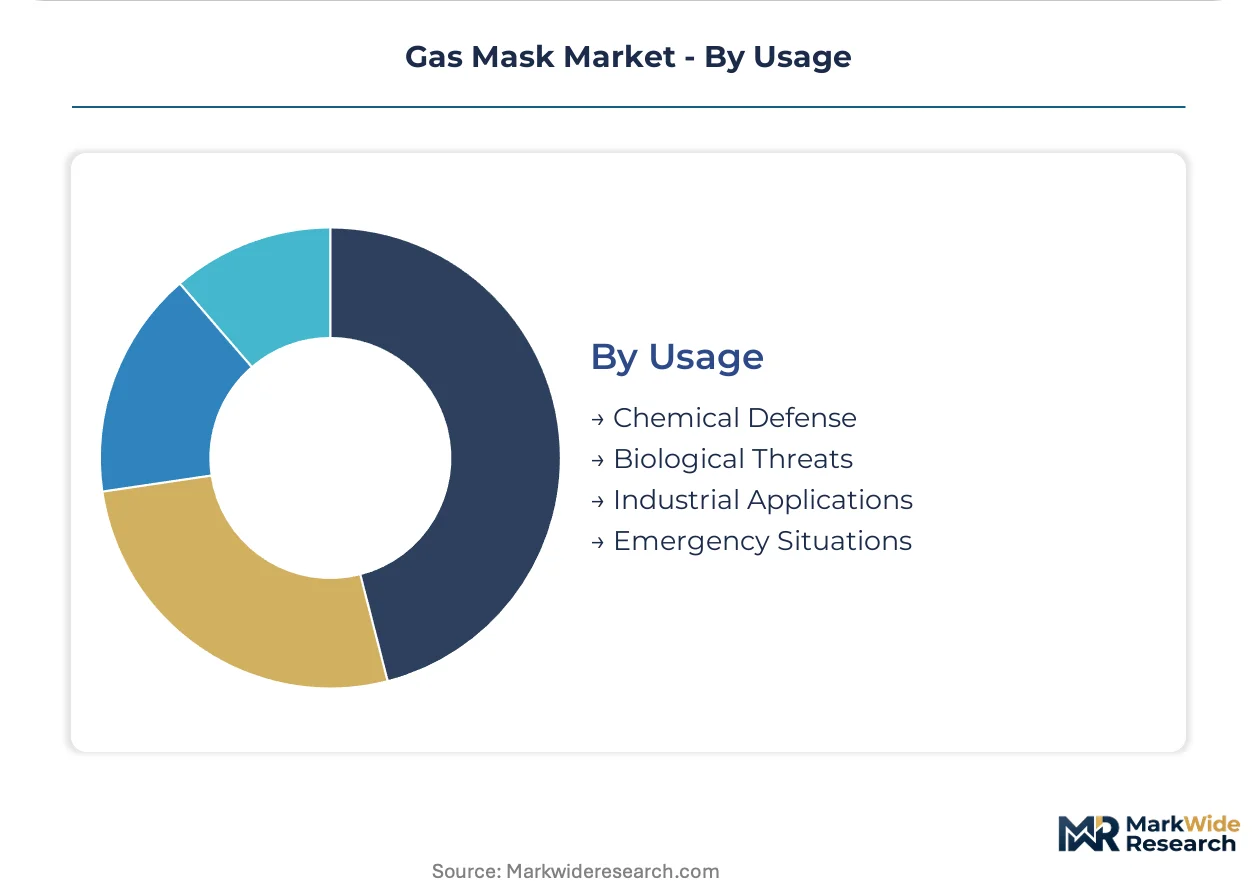
- Chemical Defense:NATO standardization frameworks require interoperability across member state inventories, complicating logistics for multinational defense contractors due to varying filter cartridge threading standards. Full-face mask configurations with panoramic visors dominate this application.
- Industrial Applications:OSHA enforcement audits in the United States are compelling employers to upgrade from half-mask respirators to full-face configurations with higher assigned protection factors. Fit testing technician scarcity creates bottlenecks for large workforce management.
- Biological Threats:HEPA filtration integration addresses pandemic preparedness and bioterrorism scenarios.
- Emergency Situations:Escape mask deployment targets rapid egress from contaminated environments.
Industrial applications absorb the largest replacement demand volume; chemical defense procurement is expanding fastest on NATO refresh cycle mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement officers and industrial safety managers concentrate demand across NATO member states and OSHA-enforced jurisdictions, with chemical defense refresh cycles and petrochemical facility upgrades driving replacement timelines.
United States
Military modernization programs and industrial safety enforcement compress replacement cycles for full-face configurations. OSHA respiratory protection standards mandate fit-tested inventory maintenance across hazardous materials handling operations. Texas and Louisiana Gulf Coast petrochemical facilities consolidate filter procurement through volume purchasing consortia.
Germany
Urban emergency preparedness programs build strategic stockpiles of civilian-grade masks for civil defense agencies. CE marking under the EU Personal Protective Equipment Regulation shapes product development timelines for cross-border market access. Bavaria-based chemical defense units pilot modular cartridge architectures for rapid threat adaptation.
France
Specialty chemical defense procurement experiences acute transition pressure from REACH authorization requirements for chromium compounds. The country's national civil defense agency expands civilian mask stockpiles beyond military procurement channels. Île-de-France hosts testing laboratories extending product launch timelines for new filter cartridge designs.
Poland
Chemical defense units drive volume commitments through NATO procurement frameworks. EU PPE Regulation harmonization simplifies cross-border distribution for manufacturers holding valid type-examination certificates. Warsaw-region defense contractors manage legacy inventory interoperability challenges from varying filter cartridge threading standards.
Netherlands
Earlier adoption of strict exposure limits accelerates alternative metal salt development for activated carbon impregnation chemistries. The country's national chemical defense procurement prioritizes multi-gas capability filters. Rotterdam industrial safety managers redirect capital toward powered air purifying respirators for extended wear scenarios.
Gas Mask Market Vendor Landscape
Player mix skews toward diversified safety conglomerates with dual-use military-civilian platforms. Market structure concentrates around vertically integrated manufacturers controlling sensor technology and filter cartridge production. Three archetypes dominate: full-system suppliers with captive filter production, platform specialists outsourcing consumables, and component manufacturers supplying third-party compatible cartridges. Competitive moves center on backward integration into activated carbon supply and strategic partnerships for integrated communication architectures.
Within the full-system supplier tier, MSA Safety Incorporated and Drägerwerk AG & Co. KGaA exemplify vertically integrated positioning across European and North American manufacturing footprints. Honeywell International Inc. occupies a position bridging military specification and civilian emergency response channels. Among specialists in modular cartridge compatibility, RPB Safety LLC and Moldex-Metric, Inc. represent the unbundling trend separating platform procurement from filter supply relationships. Gentex Corporation and Avon Protection anchor the defense-contractor archetype with panoramic visor configurations for CBRN applications. Bullard Enterprises and 3M Company sit within the industrial safety conglomerate grouping leveraging distribution scale across OSHA-enforced jurisdictions.
| Leading Market Players |
|---|
| MSA Safety Incorporated |
| Bullard Enterprises |
| 3M Company |
| RPB Safety LLC |
| Moldex-Metric, Inc. |
| Honeywell International Inc. |
| Avon Protection |
| Gentex Corporation |
| Drägerwerk AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at Gulf Coast butyl rubber refineries anchors margin structures across elastomeric seal production, concentrating supply-side pricing power among petrochemical processors while forcing mask manufacturers to absorb feedstock volatility through long-term offtake arrangements.
Pricing Analysis
Cost-plus contracts with butadiene indexation dominate procurement between filter manufacturers and activated carbon suppliers. Pricing stratifies across NATO specification, CE-marked industrial, and basic OSHA compliance tiers. Cost compression in standard-grade half-mask configurations is intensifying because industrial employers are consolidating volume through purchasing consortia. Municipal fire departments exhibit the highest price sensitivity due to constrained civil defense budgets, while military procurement channels tolerate premium positioning for CBRN-rated full-face systems with integrated communication architectures.
Supply Chain Analysis
Strait of Hormuz transit underwrites global activated carbon feedstock flows, exposing impregnation chemistry production to geopolitical disruption. Manufacturing concentrates in the United States, Germany, and China, with filter cartridge assembly drawing from specialty chemical inputs including chromium compounds, copper salts, and zinc oxide coatings. Single-source vulnerability concentrates in butyl rubber elastomer production tethered to Gulf Coast refining clusters. Distribution runs through defense procurement frameworks, industrial safety distributors, and civil defense agencies with divergent certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas mask market is recovering from procurement cycle compression triggered by NATO personal protective equipment refresh mandates, with replacement demand accelerating as member states align inventories with revised CBRN threat assessments.
For Market Incumbents: Compound defensive positioning through backward integration into activated carbon impregnation chemistry production, securing supply continuity as REACH authorization requirements force reformulation timelines. Lock in multi-year NATO framework agreements before modular cartridge architectures disrupt proprietary threading standards and erode captive filter revenue streams.
For New Entrants and Emerging Players: Differentiate on modular cartridge compatibility with legacy mask bodies, targeting Polish and Czech chemical defense units piloting rapid threat adaptation systems. Enter through specialist filter manufacturing rather than full-system supply, exploiting the unbundling trend separating platform procurement from consumable relationships in United States petrochemical facilities.
For Investors and Strategic Acquirers: Component manufacturers with third-party cartridge certification and established CE marking pathways represent the most defensible acquisition profile against supply chain consolidation. Monitor NIOSH testing laboratory capacity expansion as the inflection signal for new product launch velocity and filter innovation cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Activated Carbon Supply | Captures margin pools in impregnation chemistry as REACH reformulation accelerates alternative metal salt development. |
| Modular Cartridge Architecture Development | Enables rapid threat adaptation for NATO chemical defense units while disrupting proprietary supplier relationships. |
| Integrated Communication System Partnership | Supports premium positioning for tactical law enforcement applications through voice projection and bone-conduction convergence. |
| NIOSH Certification Pre-Investment | Reduces product launch timeline exposure from testing laboratory capacity constraints in United States facilities. |
| Urban Civil Defense Stockpile Contracting | Accesses demand outside military procurement channels through German and French emergency preparedness program expansion. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade records, and defense procurement announcements. Defense procurement officers, industrial safety managers at Texas and Louisiana petrochemical facilities, fit testing technicians, and activated carbon chemical engineers provided qualitative inputs. OSHA enforcement data, NATO standardization documents, EPA chemical emergency preparedness mandates, and EU PPE Regulation implementation guidance supplied secondary validation. Bottom-up unit demand estimates triangulate against top-down defense budget allocation analysis.
Segmentation dimensions modeled include product architecture, end-user procurement channel, filtration technology chemistry, and application threat scenario across the projection horizon. CAGRs derive from replacement cycle analysis, regulatory enforcement trajectory, and material science innovation diffusion. NATO refresh cycle mandates, REACH authorization timelines for chromium compounds, and NIOSH certification backlog dynamics inform scenario-weighted outputs.
Material uncertainties — CBRN threat reassessment frequency, feedstock price volatility, and testing laboratory capacity expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding defense budget continuity and regulatory harmonization progress. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Human Airbag Wearable Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Explosion-Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Self-Contained Breathing Apparatus Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market