
 Middle East and Africa Process Safety Services Market | 2026-2036
Middle East and Africa Process Safety Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Process Safety Services Market Foresight
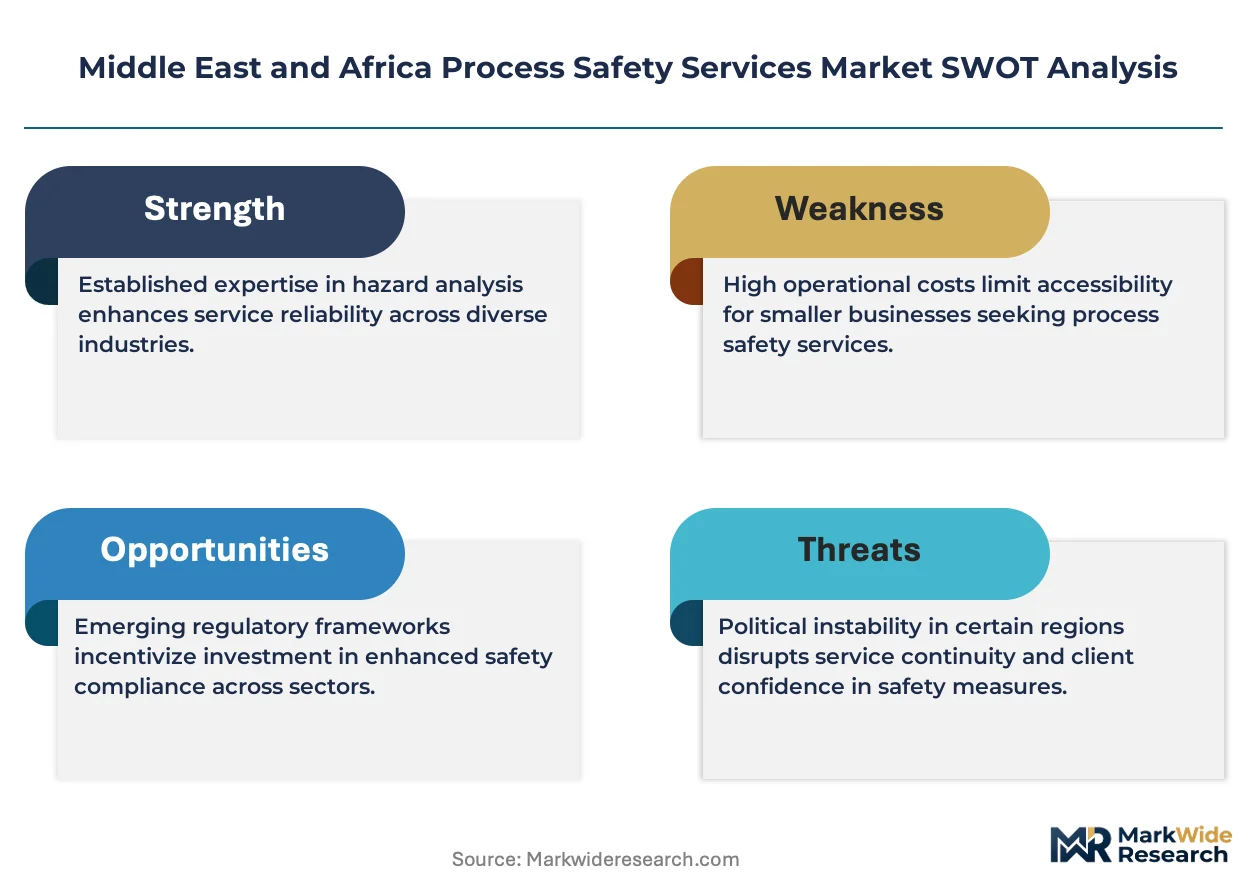
Buyer concentration among national oil companies and integrated petrochemical groups is realigning procurement priorities across the Middle East and Africa. DNV GL AS leverages its maritime and offshore heritage to anchor large-scale safety verification contracts in Abu Dhabi and Qatar. Bureau Veritas competes through its extensive laboratory network and local certification authority across North and West Africa. Honeywell International Inc. dominates integrated control system safety architectures, embedding process safety within automation infrastructure.
Process safety services encompass systematic hazard identification, risk quantification, and operational safeguard verification for facilities handling flammable, toxic, or high-pressure materials. These services apply layers of protection analysis, safety instrumented system validation, and consequence modeling to prevent catastrophic releases in continuous process industries. Risk Assessment services lead revenue generation due to mandatory revalidation cycles tied to plant modifications and aging infrastructure across Gulf refineries. Safety Audits represent the fastest-expanding category as Saudi Aramco and ADNOC tighten internal assurance protocols beyond baseline regulatory requirements. Compliance Support commands durable margins where local legislation diverges from international standards, requiring specialized interpretation for market access.
SFDA in Saudi Arabia and MOHAP in the UAE enforce occupational safety frameworks that mandate third-party process safety audits for high-hazard facilities. The F-Gas Regulation from Europe influences Gulf petrochemical exporters through supply chain compliance requirements for EU-bound products. ISO 45001 certification has become a de facto procurement filter for international engineering firms selecting local safety partners. Stakeholders must monitor how carbon border adjustments and emerging hydrogen economy codes reshape safety service specifications across African project development corridors.
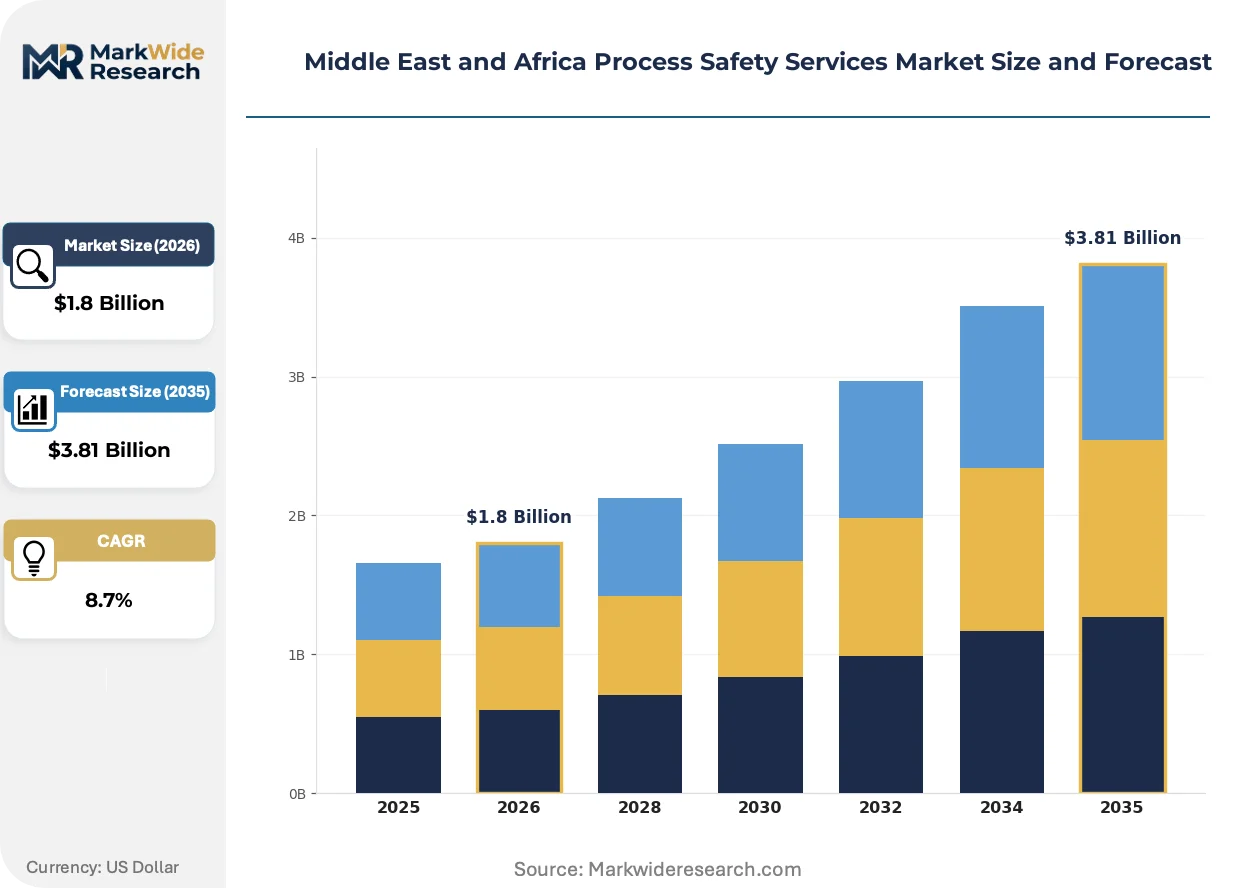
Market Dynamics
Downstream expansion across GCC petrochemical corridors is intensifying demand for specialized process safety verification, as Saudi Arabia and the UAE commission complex integrated refining facilities requiring layered protection analysis and safety instrumented system validation.
Growth Catalysts
- SFDA audit mandates:Saudi Arabia's national pharmaceutical and industrial safety regulator now requires third-party process safety audits for high-hazard facilities, creating recurring revenue streams for specialized verification services.
- Hydrogen economy codes:Emerging safety specifications for hydrogen production and ammonia cracking facilities across the Gulf are generating demand for consequence modeling and blast radius analysis.
- Aging Gulf refinery infrastructure:Plants commissioned during the 1970s-1980s construction wave require mandatory revalidation cycles tied to equipment replacement and capacity debottlenecking projects.
Market Restraints
- Specialized engineering talent scarcity:The shallow pool of certified functional safety engineers across Egypt, Nigeria, and East Africa limits service capacity expansion and drives compensation inflation.
- Imported software licensing costs:Proprietary consequence modeling tools from European vendors impose fixed cost burdens on local consultancies, compressing project margins.
- Extended certification timelines:ISO 45001 accreditation processes through Gulf-based certification bodies average 14-18 months, delaying market entry for new service providers.
Strategic Opportunities
- Egypt's chemicals corridor:The Suez Canal Economic Zone's emerging specialty chemicals cluster lacks mature local safety consulting capacity, creating first-mover positioning for integrated service providers.
- Digital twin convergence:Integration of process simulation with real-time sensor networks enables predictive safety monitoring, opening subscription-based revenue models beyond traditional project delivery.
- Carbon border adjustment preparedness:EU-bound petrochemical exporters require documented process safety and emissions verification to satisfy emerging supply chain due diligence requirements under the EU Green Deal framework.
Industry Challenges
- Legacy control system integration:Safety instrumented system upgrades in operational Gulf refineries must interface with 1990s-era distributed control architectures, complicating validation protocols and extending commissioning schedules.
- Multilingual documentation standards:ADNOC and Saudi Aramco require safety case submissions in Arabic-English dual formats, creating quality assurance bottlenecks and revision cycle delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Process Safety Services Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Risk Assessment, Compliance Support, Training Services, Safety Audits End User: Oil & Gas, Chemical Manufacturing, Pharmaceuticals, Food & Beverage Delivery Model: On-site Consulting, Remote Audits, Managed Services, Customized Solutions Compliance Standard: ISO 45001, OSHA Regulations, Process Safety Management, Local Legislation |
| Companies Covered | Bureau Veritas, ABB Group, DNV GL AS, Emerson Electric Co., Honeywell International Inc., SGS SA, Intertek Group plc, Rockwell Automation, Johnson Controls International plc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Process Safety Services Market Shifts & Advancements
Process safety service delivery across the Middle East and Africa is digitizing rapidly, with cloud-based hazard analysis platforms and remote verification protocols compressing project timelines while raising questions about data sovereignty and on-site inspection requirements.
Machine learning algorithms trained on historical incident databases are expanding into predictive hazard identification for continuous process operations. ADNOC and QatarEnergy pilot facilities deploy these tools for real-time deviation detection. The technology is expanding into pre-commissioning safety reviews, compressing traditional HAZOP study durations by identifying high-risk scenarios algorithmically before structured team sessions.
The F-Gas Regulation from Europe now influences Gulf petrochemical exporters through supply chain compliance requirements for EU-bound fluorinated gas products. Facilities must document leak detection and repair protocols to maintain market access. Saudi downstream operators have responded by embedding F-Gas management modules within broader process safety management systems, creating integrated service bundles.
Buyer concentration among national oil companies has compressed vendor qualification cycles and intensified pre-qualification requirements. International engineering firms now mandate ISO 45001 certification as a de facto filter when selecting local safety partners for EPC contracts. This certification-driven preference shift favors established regional players with documented track records, raising barriers for new market entrants across Abu Dhabi, Doha, and Kuwait City project corridors.
Middle East and Africa Process Safety Services Market Segmentation
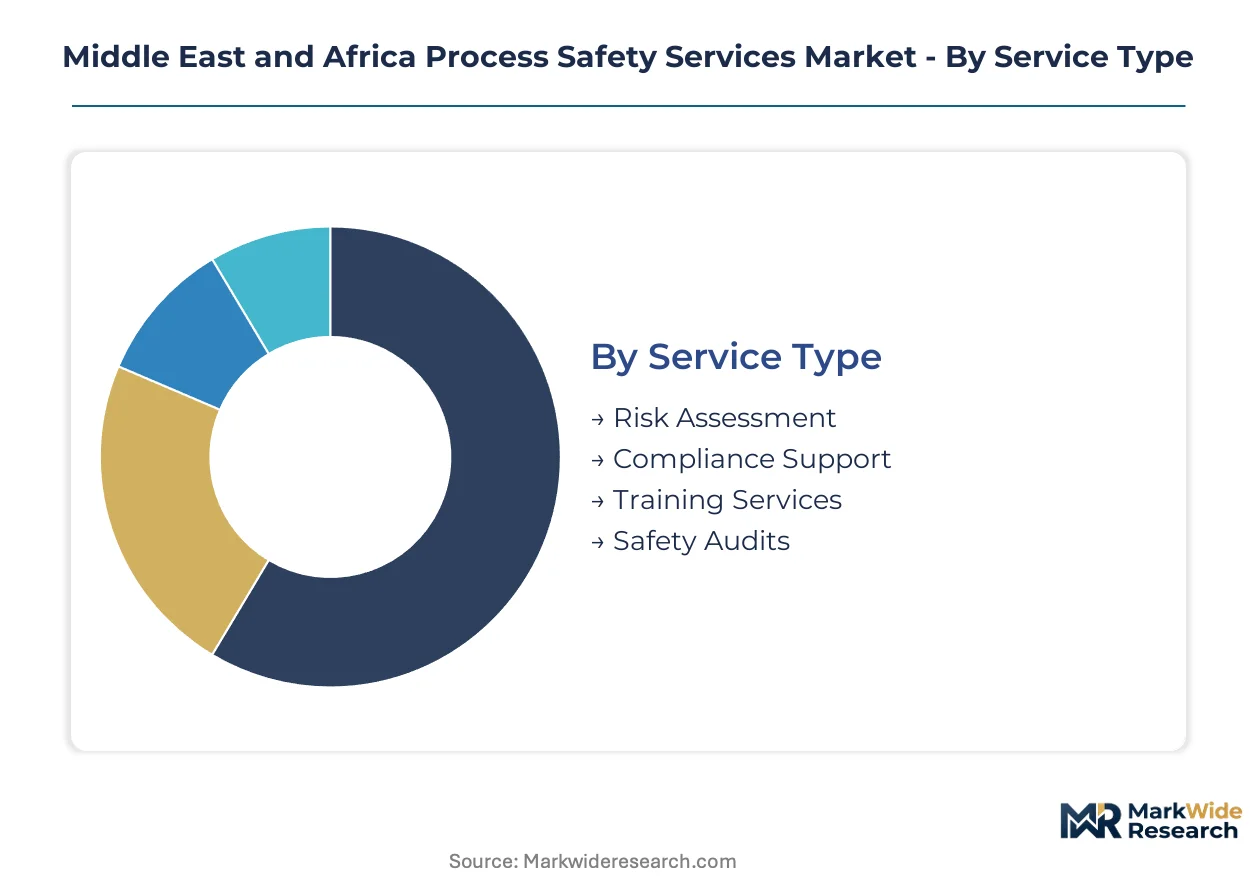
Process safety services fragment across four distinct dimensions that shape procurement patterns and margin structures. Service type determines technical depth and revalidation frequency, while end-user verticals impose sector-specific hazard profiles. Delivery models reflect digital adoption rates and client risk tolerance, and compliance standards anchor pricing power through certification complexity.
Service Type:
Risk Assessment services occupy the standardization end of this spectrum with templated methodologies and recurring revalidation cycles, while Safety Audits demand heavy customization to facility-specific hazard registers and operator maturity levels.
- Risk Assessment:Systematic hazard identification, consequence modeling, and layers of protection analysis for continuous process operations. Mandatory revalidation tied to plant modifications and equipment replacement cycles across aging Gulf refineries in Saudi Arabia and Kuwait generates durable recurring revenue.
- Safety Audits:Independent verification of safety management system effectiveness against regulatory and internal standards. SFDA and ADNOC tightening assurance protocols beyond baseline requirements in Saudi Arabia and Abu Dhabi accelerates demand for specialized third-party verification.
- Compliance Support:Interpretation of local legislation diverging from international standards for market access.
- Training Services:Competency development for functional safety engineering and hazard analysis team leadership.
Leading the category by volume: Risk Assessment. Growing fastest: Safety Audits.
End User:
Customer concentration varies sharply across this dimension, with national oil companies commanding integrated multi-service contracts while food and beverage processors purchase discrete compliance modules.
- Oil & Gas:Upstream, midstream, and downstream operations handling flammable hydrocarbons under high pressure. Saudi Aramco and ADNOC downstream expansion across integrated refining and petrochemical complexes concentrates demand for layered protection analysis and safety instrumented system validation.
- Chemical Manufacturing:Specialty and commodity chemical production with toxic release and runaway reaction hazards. Egypt's Suez Canal Economic Zone emerging chemicals cluster lacks mature local safety consulting capacity, creating first-mover positioning opportunities.
- Pharmaceuticals:Batch processing with potent compound handling and cross-contamination controls.
- Food & Beverage:Process safety applications focused on thermal processing and dust explosion prevention.
Highest contract values: Oil & Gas. Steepest expansion trajectory: Chemical Manufacturing.
Delivery Model:
Volume concentration sits with established on-site consulting, though margin expansion is concentrating in technology-enabled remote and managed service formats.
- On-site Consulting:Embedded technical specialists conducting hazard studies and verification activities at client facilities. Legacy control system integration requirements in operational Gulf refineries extend commissioning schedules and sustain demand for physical presence.
- Remote Audits:Cloud-based document review and virtual witness testing protocols. ADNOC and QatarEnergy pilot programs for real-time deviation detection expand applicability, though data sovereignty concerns limit adoption in sensitive facilities.
- Managed Services:Long-term safety management system operation and continuous improvement partnerships.
- Customized Solutions:Bespoke tool development and integrated digital twin implementations for predictive safety monitoring.
Dominant by revenue: On-site Consulting. Gaining share fastest: Remote Audits.
Compliance Standard:
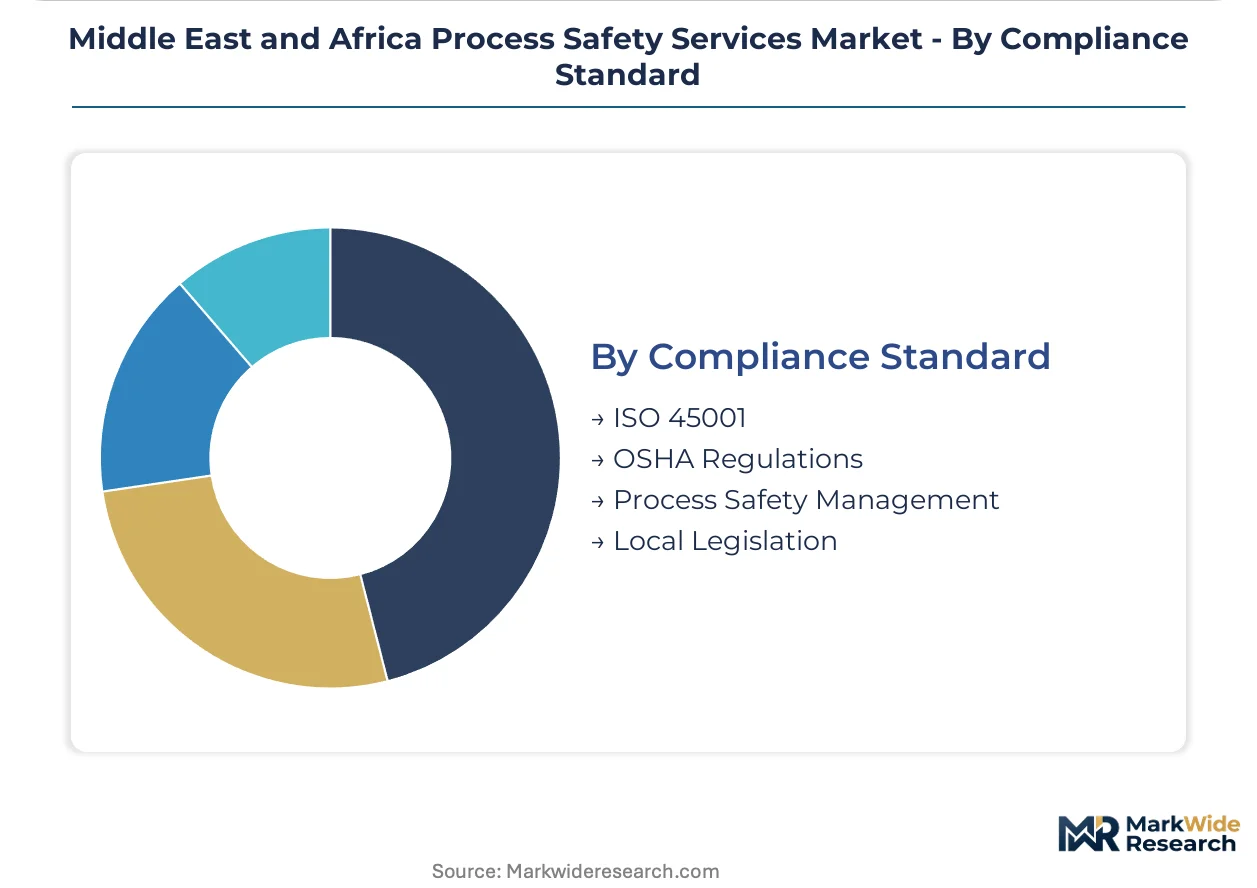
Certification complexity and geographic applicability create tiered pricing structures, with international standards commanding premiums over local legislation interpretation.
- ISO 45001:Occupational health and safety management system certification. International engineering firms mandate this as a de facto procurement filter when selecting local safety partners for EPC contracts across Abu Dhabi, Doha, and Kuwait City.
- OSHA Regulations:US-origin standards applied to multinational operator subsidiaries and export-oriented facilities. Limited direct applicability in Middle East and Africa markets outside specific operator mandates.
- Process Safety Management:Systematic framework for preventing catastrophic releases in high-hazard industries.
- Local Legislation:Country-specific safety codes including SFDA frameworks in Saudi Arabia and MOHAP requirements in the UAE.
Widest adoption: ISO 45001. Expanding most quickly: Local Legislation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer concentration among Saudi Aramco, ADNOC, and QatarEnergy concentrates procurement power across the Gulf. Egypt's chemicals corridor and South Africa's industrial base diversify demand geography. SFDA and MOHAP frameworks reshape compliance requirements across national boundaries.
Saudi Arabia
Downstream expansion at Jazan and Yanbu integrated refining complexes drives layered protection analysis demand. SFDA mandates third-party process safety audits for high-hazard facilities, creating recurring verification revenue streams. The Eastern Province concentration of 1970s-era refineries requires mandatory revalidation cycles tied to equipment replacement programs.
United Arab Emirates
ADNOC's tightening internal assurance protocols accelerate specialized safety audit procurement beyond baseline regulatory requirements. MOHAP enforces occupational safety frameworks requiring documented safeguard verification for Abu Dhabi and Dubai industrial zones. The Ruwais refining and petrochemical complex anchors concentrated demand for safety instrumented system validation services.
Egypt
The Suez Canal Economic Zone's emerging specialty chemicals cluster lacks mature local safety consulting capacity. The country's national industrial safety regulator applies evolving frameworks to high-hazard process operations. Ain Sokhna and Alexandria industrial corridors attract first-mover positioning from integrated service providers seeking early contract anchoring.
Qatar
QatarEnergy's North Field expansion projects generate demand for consequence modeling and blast radius analysis at scale. The national energy corporation pilots machine learning algorithms for real-time deviation detection at operational facilities. Ras Laffan Industrial City's concentrated hydrocarbon processing infrastructure sustains embedded technical specialist requirements.
South Africa
Sasol's Secunda and Sasolburg synthetic fuels complexes require specialized process safety verification for high-pressure syngas operations. The country's occupational health and safety regulator maintains inspection protocols for major hazard installations. The Durban-Pinetown chemicals belt represents the continent's most mature process safety consulting market outside the Gulf.
Middle East and Africa Process Safety Services Market Competitive Landscape
European verification specialists anchor one tier; American automation-integrated providers hold another. The market structure tiers across risk assessment standardizers, audit customization specialists, and compliance interpretation boutiques. Strategic archetypes include maritime-heritage technical verifiers, laboratory-network certifiers, and control-system-embedded safety architects. Dominant competitive moves encompass geographic license partnerships with local certification bodies and predictive safety monitoring technology licensing.
Among European-origin verification houses, Bureau Veritas exemplifies the laboratory-network archetype across North and West Africa. DNV GL AS occupies the maritime-heritage technical verifier position, anchoring large-scale safety verification contracts in Abu Dhabi and Qatar. Honeywell International Inc. represents the control-system-embedded safety architect archetype, dominating integrated safety architectures within automation infrastructure. These three players illustrate how heritage specialization maps to procurement segmentation across national oil company buyers.
| Leading Market Players |
|---|
| Bureau Veritas |
| ABB Group |
| DNV GL AS |
| Emerson Electric Co. |
| Honeywell International Inc. |
| SGS SA |
| Intertek Group plc |
| Rockwell Automation |
| Johnson Controls International plc |
| Others |
Supply & Pricing Matrix
Certified functional safety engineers concentrated in the UAE and Saudi Arabia command compensation premiums that compress project margins for Egyptian and Nigerian consultancies, widening the spread between premium-tier international verification houses and local standard-tier providers.
Pricing Analysis
Volume concentrates in project-based risk assessment contracts while margin expansion sits with subscription digital-twin monitoring services. Pricing stratifies across premium certification-grade verification, standard methodology-driven consulting, and economy-tier documentation support. Cost compression in the economy tier is intensifying because proprietary European consequence modeling software imposes fixed licensing burdens on local consultancies. National oil companies exhibit the lowest price sensitivity, while Egyptian specialty chemical ventures in the Suez Canal Economic Zone represent the most price-constrained buyer segment.
Supply Chain Analysis
Workforce availability constraints in Egypt, Nigeria, and East Africa limit service capacity expansion across the continent's project corridors. Engineering talent draws from Saudi Arabia, the UAE, and South Africa as primary supply nodes, with specialized functional safety competency resting on European training certification pathways. Single-source vulnerability sits with proprietary hazard analysis software from European vendors. Distribution runs through embedded technical specialist deployment at operational Gulf refineries, supplemented by emerging remote audit platforms for document-intensive verification phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as automation-integrated providers pursue backward control over safety instrumented system hardware to capture margin from control system upgrades.
For Market Incumbents: Extend predictive safety monitoring capabilities through machine learning algorithm licensing to defend against pure-play digital entrants. Deepen embedded specialist presence at Saudi Aramco and ADNOC facilities to lock out audit competitors. Acquire boutique compliance interpretation firms in Egypt to preempt first-mover positioning in the Suez Canal Economic Zone chemicals corridor.
For New Entrants and Emerging Players: Enter via the safety audit category where SFDA and ADNOC tightening of assurance protocols creates demand growth exceeding established verification capacity. Target Egypt's emerging specialty chemicals cluster with Arabic-English dual-format documentation capabilities. Lead with ISO 45001 certification as a procurement filter bypass for EPC contract access.
For Investors and Strategic Acquirers: Re-rating potential sits with digital-twin-enabled managed service providers given ADNOC and QatarEnergy pilot programs validating real-time deviation detection. Long-term viability centers on subscription revenue models displacing project-based delivery. Monitor hydrogen economy code finalization across Gulf regulators as inflection indicator for consequence modeling demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Algorithm Licensing | ADNOC pilot programs validate predictive hazard identification compressing traditional HAZOP study timelines. |
| Backward Integration into Safety Instrumented Hardware | Honeywell's embedded safety architectures capture margin from legacy control system upgrade cycles. |
| ISO 45001 Certification Investment | International engineering firms mandate this filter for local safety partner selection across Abu Dhabi and Doha. |
| Arabic-English Documentation Capability Buildout | ADNOC and Saudi Aramco dual-format requirements create quality assurance bottlenecks for mono-lingual competitors. |
| Hydrogen Economy Code Preparedness | Emerging Gulf safety specifications for ammonia cracking facilities generate blast radius analysis demand. |
Research Methodology
Document review covered SFDA audit mandate filings, ADNOC procurement guidelines, and EU F-Gas Regulation compliance frameworks, complemented by interviews with process safety directors at national oil companies, functional safety engineering leads at certification bodies, EPC contract procurement managers, and industrial zone regulatory affairs officers. Secondary validation drew from customs data on safety system imports, SEC filings of automation-integrated providers, and project development databases tracking Gulf refinery expansion timelines. Bottom-up service provider revenue estimates were cross-referenced against top-down end-user procurement budget disclosures.
Historical contract value trajectories were cross-referenced against expert panel input from verification house executives and national oil company technical assurance leads. The analytical framework modeled service type, end-user vertical, delivery model, and compliance standard dimensions across the projection horizon. CAGRs were derived from revalidation cycle frequencies tied to aging Gulf refinery equipment replacement programs and hydrogen economy infrastructure development curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended ISO 45001 accreditation timelines or accelerated hydrogen code implementation. Forecasts reflect assumptions regarding SFDA enforcement consistency and ADNOC internal assurance protocol tightening. Material deviation in European software vendor licensing terms or Gulf workforce mobility restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Body Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above the Waist PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market