
 Military Personal Protective Equipment (PPE) Market | 2026-2036
Military Personal Protective Equipment (PPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Military Personal Protective Equipment (PPE) Market Intelligence
Market Context
Defense buyer concentration is pivoting toward integrated platform contracts that bundle body armor, helmets, and situational awareness gear under single vendor relationships. DuPont leverages its Kevlar fiber dominance to anchor upstream supply for ballistic fabric mills serving Tier 1 integrators. Avon Protection competes through its respiratory and head protection integration, while Gentex Corporation specializes in helmet-mounted displays that extend beyond passive protection into mission systems.
Technical Definition and Segment Structure
Military personal protective equipment encompasses engineered garments, headgear, and wearable systems designed to attenuate ballistic, blast, chemical, and thermal threats through materials meeting specified V50 ballistic limits and backface deformation thresholds. Tactical vests incorporating ceramic plates and modular soft armor panels constitute the largest product value pool, whereas nano-enhanced fabrics represent the fastest-growing technology segment as manufacturers pursue weight reduction without sacrificing NIJ Level III/IV stopping power. Combat operations generate the dominant application demand, though peacekeeping missions are emerging as a distinct procurement channel with lighter protection requirements and faster deployment cycles.
Regulatory Framework and Outlook
The U.S. National Institute of Justice (NIJ) sets ballistic resistance standards that determine product eligibility for Department of Defense contracts, while NATO STANAG agreements harmonize testing protocols across allied procurement agencies. The U.S. Army's Product Manager Soldier Protective Equipment enforces additional environmental and durability criteria that shape vendor qualification timelines. Stakeholders must monitor how the EU AI Act and emerging autonomous system integrations will redefine protective equipment requirements as soldier-worn computing becomes standard.
Market Dynamics
The U.S. Army's Modular Scalable Vest program is compressing supplier qualification timelines while forcing material transitions from legacy aramid fibers to hybrid ceramic-composite systems. This procurement concentration is reshaping how Tier 1 integrators structure their captive manufacturing versus outsourced component sourcing.
Growth Catalysts
- NIJ ballistic standard revisions:Updated backface deformation thresholds are accelerating adoption of next-generation polyethylene and ceramic hybrid plates. Defense procurement officers now require Level III+ stopping power at sub-5 pound plate weights.
- Special Operations Command modernization:USSOCOM's integrated soldier system programs are bundling body armor with helmet-mounted displays and respiratory protection under single-vendor relationships.
- NATO STANAG harmonization:Allied procurement agencies are converging on unified testing protocols, enabling cross-border vendor qualification and reducing duplicate certification costs for European suppliers.
Market Restraints
- Ceramic precursor supply concentration:High-purity alumina and boron carbide feedstock production clusters in limited Chinese and German chemical processing facilities, creating input cost volatility.
- DuPont Kevlar upstream dominance:Single-source dependency for para-aramid fiber constrains pricing leverage for ballistic fabric mills serving vest integrators.
- REACH chemical registration burdens:European Union substance authorization requirements for novel nano-enhanced coatings extend product launch timelines by 18-24 months.
Strategic Opportunities
- Peacekeeping mission procurement channels:United Nations and African Union rapid-deployment forces require lighter, faster-cycling protection systems with streamlined logistics footprints.
- Soldier-worn computing convergence:Integration of power distribution, data transmission, and thermal management into vest platforms creates new value pools beyond passive ballistic protection.
- U.S. congressional defense appropriations:Sustained plus-ups in Army and Marine Corps equipment accounts provide multi-year visibility for vendors meeting Product Manager Soldier Protective Equipment qualification standards.
Industry Challenges
- Ballistic materials engineering talent scarcity:Specialized expertise in V50 testing protocol design and trauma plate ceramic matrix optimization concentrates in a limited pool of defense laboratory veterans.
- NIJ certification timeline compression:Accelerated program schedules force vendors to parallel-track environmental durability testing with ballistic qualification, elevating capital risk.
- Legacy system integration friction:New vest platforms must interface with existing load carriage equipment and radio mounting systems, constraining design freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Personal Protective Equipment (PPE) Market |
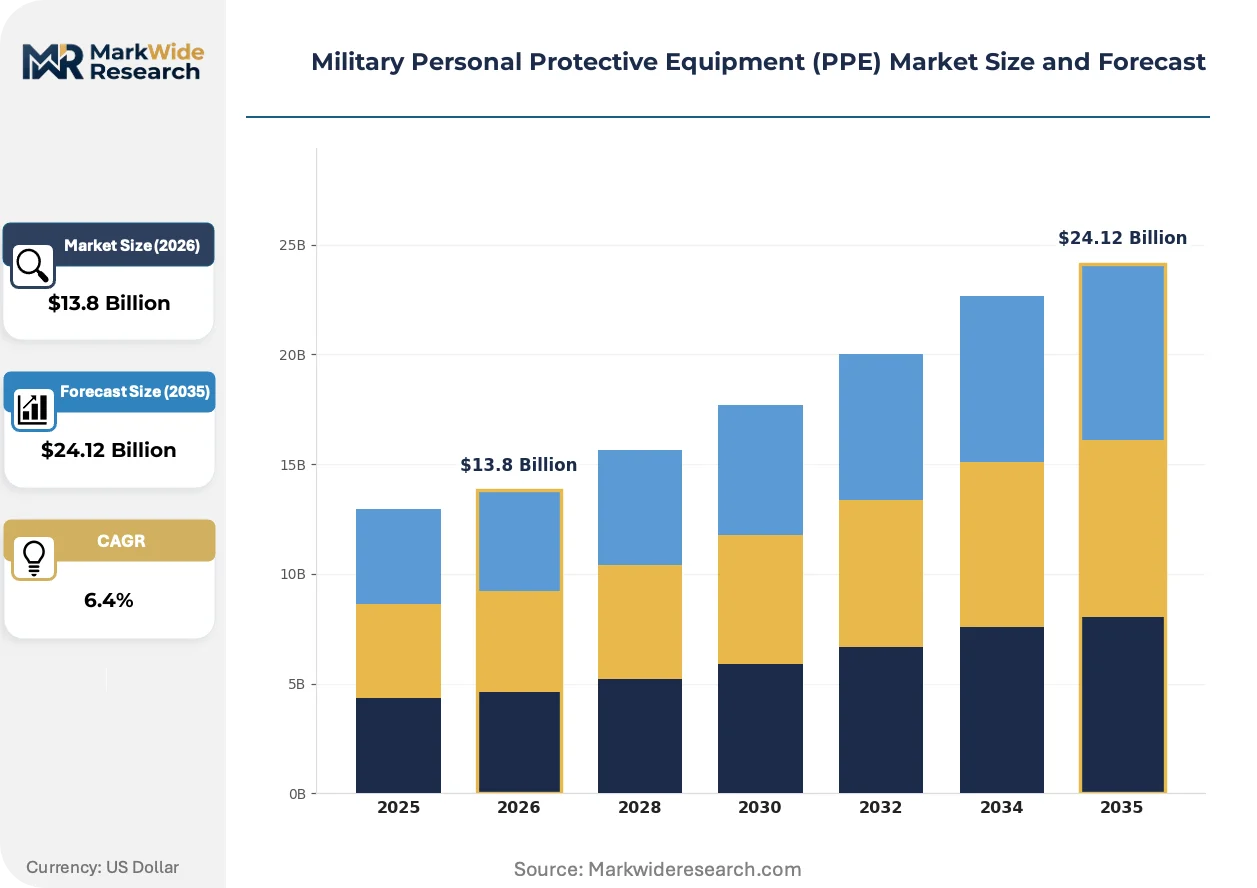
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Helmets, Tactical Vests, Chemical Suits, Eye Protection, Hearing Protection Application: Combat Operations, Training Exercises, Peacekeeping Missions, Disaster Response, Surveillance End User: Infantry Units, Special Forces, Military Police, Paramilitary Groups, Defense Contractors Technology: Kevlar Fiber, Ceramic Plates, Nano-Enhanced Fabrics, Modular Design, Electric Cooling Systems |
| Companies Covered | DuPont, Avon Protection, 3M, ArmorSource, MSA Safety, Honeywell International, Gentex Corporation, Revision Military, BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Personal Protective Equipment (PPE) Market Strategic Shifts & Innovations
Material science breakthroughs are compressing the weight-performance frontier while regulatory harmonization and procurement model evolution are restructuring how protection systems reach end-users. These forces are converging to redefine competitive advantage around integrated platform capabilities rather than discrete component performance.
Nano-enhanced polyethylene fibers are electrifying the soft armor segment by delivering NIJ Level IIIA protection at 30% lower areal density than traditional aramid weaves. U.S. Army and Marine Corps procurement officers are fast-tracking field trials of these materials for scalable vest configurations. The technology is electrifying vendor R&D priorities, forcing accelerated investment in hybrid ceramic-polyethylene plate architectures that were previously considered uneconomical at volume.
The EU AI Act is introducing conformity assessment requirements for autonomous threat detection systems integrated into helmet-mounted displays. European defense procurement agencies must now verify algorithmic transparency and human oversight protocols before fielding sensor-fused protection gear. This regulatory overlay most affects vendors like Gentex Corporation supplying NATO allies, which are restructuring software development workflows to satisfy both CE marking and military environmental standards.
Consolidated platform contracting is displacing discrete component purchasing across U.S. defense acquisition. Program offices now award single-vendor agreements bundling vests, helmets, and situational awareness gear, compressing the supplier base. This pattern is most visible in Special Operations Command acquisitions, where integrators must demonstrate subsystem interoperability under unified logistics support rather than competing on individual item specifications.
Military Personal Protective Equipment (PPE) Market Segmentation
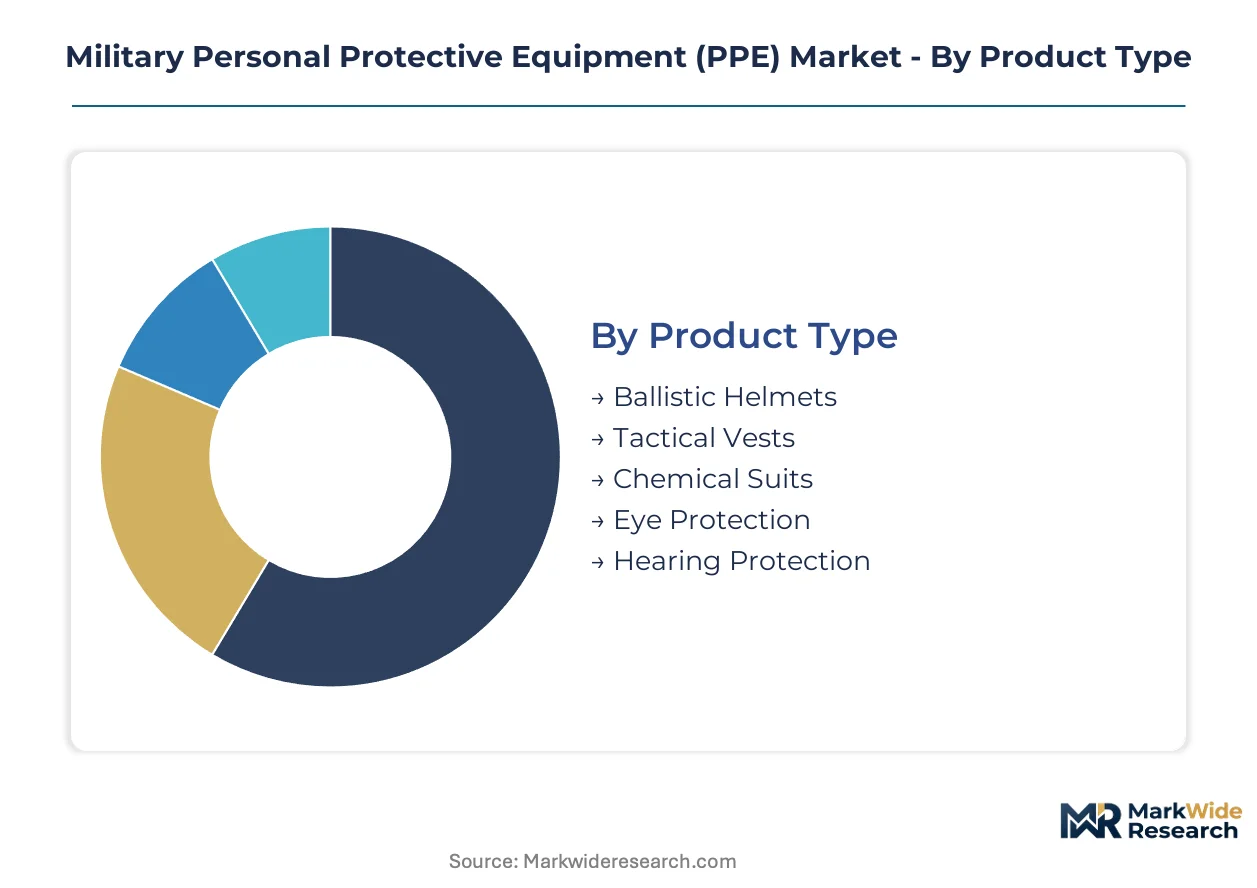
Military PPE procurement channels fragment across threat profiles, operational tempo, and qualification standards. Certification requirements from NIJ and NATO STANAG create divergent compliance burdens that reshape vendor targeting strategies across each segment axis.
Product Type:
NIJ Level III/IV certification governs hard armor plates and tactical vests, while ballistic helmets face additional environmental durability testing under Army Product Manager Soldier Protective Equipment protocols. Chemical suits and eye protection operate under distinct OSHA and CE marking frameworks that compress supplier margins differently.
- Tactical Vests:Modular platforms integrating ceramic plates and soft armor panels constitute the dominant procurement spend. U.S. Army Modular Scalable Vest program demand concentrates in hybrid ceramic-polyethylene configurations driven by congressional defense appropriations.
- Ballistic Helmets:Advanced combat helmets with helmet-mounted display integration require dual certification under NIJ ballistic standards and FCC electromagnetic compliance. USSOCOM modernization programs are bundling head protection with situational awareness systems under single-vendor contracts.
- Chemical Suits:Respiratory-integrated ensembles face REACH chemical registration burdens that extend European launch timelines.
- Eye Protection:Ballistic-rated eyewear operates under lighter certification frameworks with faster fielding cycles.
- Hearing Protection:Electronic hearing protection with communications integration requires electromagnetic compatibility testing alongside acoustic attenuation validation.
Tactical vests sit at the top of the volume ranking, with nano-enhanced fabric variants climbing the fastest.
Application:
Operational intensity directly determines protection tier requirements and replacement frequency. Combat operations demand Level III/IV stopping power with 5-year service life specifications, while peacekeeping missions accept lighter configurations with compressed logistics footprints.
- Combat Operations:Full-spectrum protection against ballistic, blast, and thermal threats requires integrated platform architectures. U.S. Army and Marine Corps equipment accounts concentrate procurement in scalable vest configurations with ceramic-composite plate systems.
- Peacekeeping Missions:United Nations and African Union rapid-deployment forces prioritize weight reduction and streamlined supply chains over maximum protection levels. Procurement cycles run shorter with faster vendor qualification pathways.
- Training Exercises:High-wear environments drive demand for cost-optimized protection with reduced ballistic ratings.
- Disaster Response:Chemical and thermal protection dominates procurement for humanitarian assistance operations.
- Surveillance:Extended wear requirements favor lightweight soft armor with integrated power distribution for sensor systems.
Combat operations anchor procurement volume, though peacekeeping missions are gaining share fastest as multilateral force commitments expand.
End User:
Customer type determines contract structure and technical specification rigor. Special Operations Command programs enforce subsystem interoperability standards that constrain design freedom, while paramilitary procurement operates under lighter qualification frameworks.
- Special Forces:USSOCOM integrated soldier system programs bundle body armor, helmets, and respiratory protection under unified logistics support. Mission profiles demand sub-5 pound plate weights with Level III+ stopping power.
- Infantry Units:Conventional Army and Marine Corps forces drive volume procurement through Product Manager Soldier Protective Equipment qualification pathways. Congressional plus-ups provide multi-year program visibility.
- Military Police:Domestic security operations prioritize mobility and extended wear comfort over maximum ballistic protection.
- Paramilitary Groups:Border security and counter-insurgency units operate under national procurement frameworks with reduced NATO STANAG harmonization.
- Defense Contractors:Private security details drive commercial demand for NIJ-certified equipment outside formal military acquisition channels.
Infantry units command the largest contract values, with special forces segments expanding most quickly through bundled platform awards.
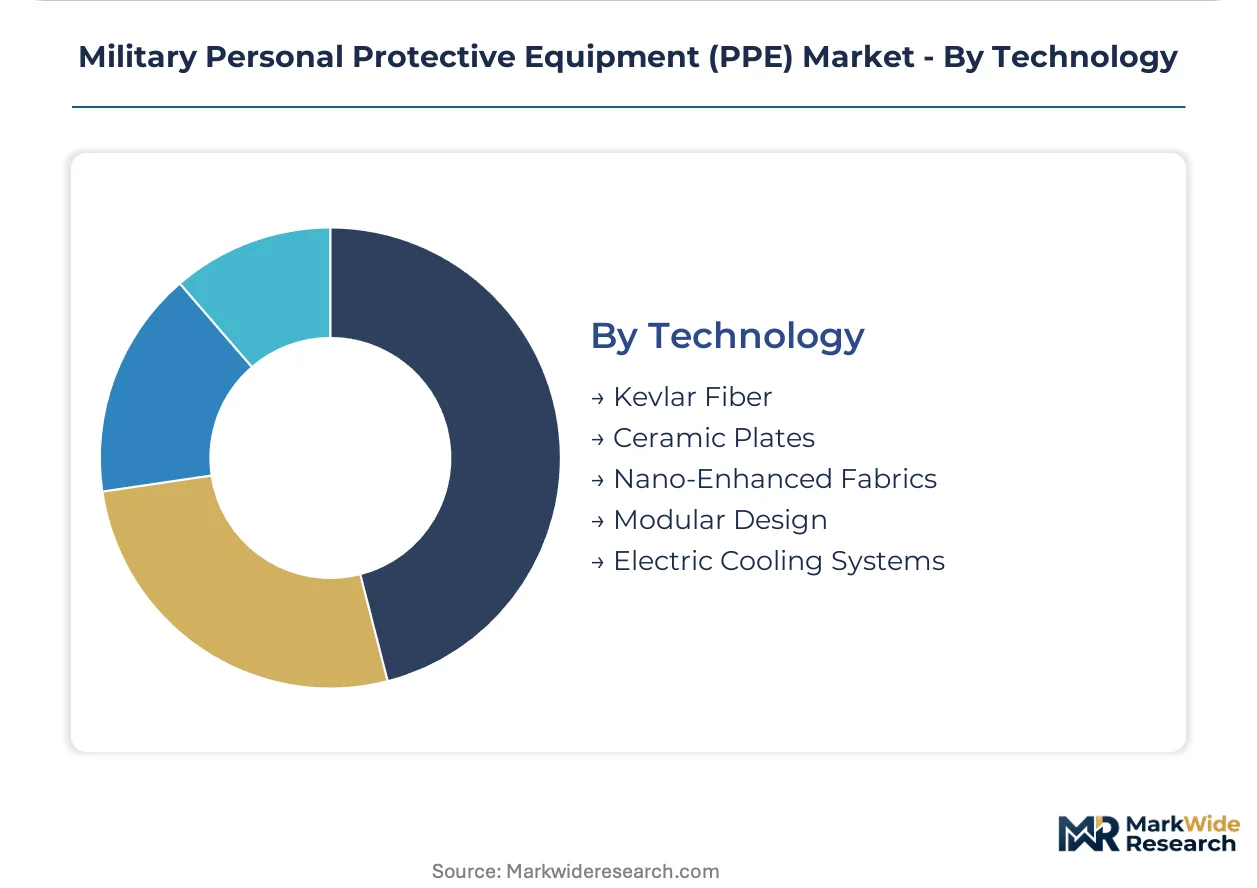
Technology:
Material science advancement is compressing the weight-performance frontier while creating new supply concentration risks. Ceramic precursor feedstock clusters in limited chemical processing facilities, constraining pricing leverage for plate integrators.
- Ceramic Plates:High-purity alumina and boron carbide matrix composites deliver NIJ Level IV protection against armor-piercing threats. Chinese and German precursor supply concentration creates input cost volatility for U.S. vest manufacturers.
- Nano-Enhanced Fabrics:Ultra-high molecular weight polyethylene fibers with nanoscale coatings achieve 30% areal density reduction versus traditional aramid weaves. U.S. Army field trials are fast-tracking adoption for scalable vest configurations.
- Kevlar Fiber:DuPont's upstream dominance in para-aramid supply constrains pricing flexibility for ballistic fabric mills.
- Modular Design:Scalable protection architectures enable mission-specific configuration without full system replacement.
- Electric Cooling Systems:Active thermal management integration addresses heat stress in soldier-worn computing platforms.
Ceramic plates retain the highest revenue concentration, with nano-enhanced fabrics showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement specialists and ballistic materials engineers cluster around military R&D hubs and major defense contractor facilities. Their geographic concentration shapes where qualification standards emerge and where vendor relationships consolidate.
United States
Congressional defense appropriations and USSOCOM modernization programs drive procurement volume. The NIJ sets ballistic resistance standards that determine DoD contract eligibility. Aberdeen Proving Ground in Maryland anchors testing and qualification protocols for next-generation soldier systems.
Germany
Bundeswehr equipment modernization and NATO STANAG harmonization efforts concentrate demand. REACH chemical registration requirements from ECHA extend product launch timelines for novel materials. Bavaria hosts major defense integrators coordinating cross-border vendor qualification pathways.
United Kingdom
Ministry of Defence integrated soldier system programs bundle body armor with situational awareness gear. DSTL (Defence Science and Technology Laboratory) enforces additional environmental and durability criteria. South West England clusters specialist suppliers serving NATO procurement agencies.
France
DGA (Direction Générale de l'Armement) procurement frameworks prioritize subsystem interoperability standards. EU AI Act conformity assessments now apply to autonomous threat detection integrations. Paris-Saclay defense research cluster advances helmet-mounted display technologies.
Israel
Ministry of Defense rapid fielding cycles and combat-proven validation requirements compress development timelines. National ballistic standards often exceed NATO STANAG thresholds. Tel Aviv metropolitan area concentrates R&D facilities for lightweight ceramic-composite systems.
Military Personal Protective Equipment (PPE) Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across material supply, subsystem integration, and platform assembly tiers. The vendor base separates into fiber and chemical producers, component fabricators, and end-system integrators. Three archetypes dominate: upstream material suppliers controlling critical feedstock, mid-tier armor assemblers managing NIJ certification pathways, and full-platform integrators bundling multiple protection subsystems. Competitive moves center on captive supply arrangements for ceramic precursors and strategic partnerships to satisfy consolidated platform contracting requirements.
Among material science conglomerates, DuPont anchors upstream para-aramid fiber supply. Avon Protection and Gentex Corporation exemplify the platform integration archetype, with the former representing respiratory-head protection bundling and the latter occupying a position in helmet-mounted mission systems. These three companies illustrate how competitive positioning separates feedstock control from subsystem integration and full-platform assembly capabilities.
| Leading Market Players |
|---|
| DuPont |
| Avon Protection |
| 3M |
| ArmorSource |
| MSA Safety |
| Honeywell International |
| Gentex Corporation |
| Revision Military |
| BAE Systems |
| Others |
Cost & Logistics Intelligence
Hybrid ceramic-polyethylene plate architectures are simultaneously compressing per-unit manufacturing economics and concentrating procurement leverage around Tier 1 integrators with captive testing infrastructure. This materials transition elevates capital barriers for mid-tier assemblers while rewarding vendors who have secured NIJ certification pathways ahead of Modular Scalable Vest program timelines.
Pricing Analysis
Bundled platform contracts versus discrete component purchasing now defines the dominant pricing split. Three-tier pricing structure across premium, standard, and economy levels separates USSOCOM-integrated soldier systems from conventional Army vest configurations and training-grade equipment. Cost compression in standard-tier ceramic plates is intensifying because Chinese and German precursor supply concentration limits pricing leverage for non-integrated mills. Paramilitary procurement channels exhibit highest price sensitivity due to national budget constraints, while Special Operations Command programs prioritize performance thresholds over unit cost.
Supply Chain Analysis
High-purity alumina and boron carbide feedstock rests on Chinese and German specialty chemical processing facilities, with DuPont's para-aramid fiber production anchoring soft armor supply in the United States. Raw material dependencies span ceramic precursors, nano-enhanced polyethylene fibers, and ballistic-rated composite resins. Single-source vulnerability in Kevlar upstream supply constrains pricing flexibility for vest integrators lacking backward integration into fiber production. Distribution runs through defense contractor prime relationships rather than open commercial channels, with Product Manager Soldier Protective Equipment qualification serving as the gatekeeping mechanism for vendor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by congressional defense appropriations shifting toward sub-5 pound Level III+ plate specifications that command premium positioning.
For Market Incumbents: Anchor qualification advantage by deepening captive supply arrangements for boron carbide precursors and accelerating environmental durability testing parallel to ballistic certification. DuPont's upstream fiber dominance threatens margin leverage for non-integrated mills, making NIJ certification pathway control the critical defensive lever against Tier 1 integrator consolidation. For New Entrants and Emerging Players: NATO STANAG harmonization across European procurement agencies opens a window for cross-border vendor qualification with reduced duplicate certification costs. Peacekeeping mission channels represent the most penetrable white-space target, requiring lighter protection systems with streamlined logistics footprints and faster deployment cycles. A direct sales model to United Nations rapid-deployment forces bypasses incumbent prime contractor relationships. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier armor assemblers with NIJ certification assets because consolidated platform contracting is compressing the supplier base and rewarding scaled testing infrastructure. The 5-10 year viability window favors targets with demonstrated Product Manager Soldier Protective Equipment qualification rather than pure materials science IP. Congressional plus-up announcements in Army and Marine Corps equipment accounts serve as the signal to watch for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Precursor Backward Integration | Captive supply of high-purity alumina reduces exposure to Chinese and German chemical processing concentration. |
| NIJ Certification Parallel-Tracking | Simultaneous environmental durability and ballistic testing compresses vendor qualification timelines for Modular Scalable Vest programs. |
| Peacekeeping Channel Direct Sales | United Nations rapid-deployment procurement operates outside incumbent prime contractor networks with faster fielding cycles. |
| Helmet-Mounted Display Integration | EU AI Act conformity assessments for autonomous threat detection systems create new compliance-based differentiation. |
| Nano-Enhanced Fabric Scale-Up | U.S. Army field trials for 30% areal density reduction position early movers for scalable vest configuration awards. |
Research Approach
Coverage spans the United States, Germany, the United Kingdom, France, and Israel, with primary inputs from each defense procurement cluster. The analysis combines structured interviews with Product Manager Soldier Protective Equipment officials, ballistic materials engineers at Aberdeen Proving Ground, defense contractor procurement leads, and ceramic precursor chemical processing specialists. Secondary validation draws from congressional defense appropriations records, NIJ ballistic standard documentation, NATO STANAG protocol publications, and EU AI Act regulatory filings. Bottom-up demand modeling triangulates against top-down defense budget allocation analysis.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include protection level tier, operational application intensity, end-user qualification pathway, and materials technology platform. CAGRs derive from defense procurement schedule visibility and replacement cycle analysis, with specific weighting for congressional plus-up timing and USSOCOM modernization program phasing. Nano-enhanced fabric adoption curves and ceramic plate weight-performance frontiers serve as technology-specific forecast inputs.
Revisions become necessary when congressional appropriation delays, ceramic precursor supply disruptions, or NIJ standard revision timelines materialize differently than modeled. Forecasts reflect assumptions about defense budget continuity and allied procurement harmonization progress. A small set of named triggers—congressional continuing resolution frequency, REACH chemical registration enforcement intensity, and autonomous system integration regulatory clarity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
China Premium Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Africa Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market