
 Lightning Protection Systems Market | 2026-2036
Lightning Protection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Lightning Protection Systems Market Outlook
NFPA 780 certification cycles for lightning protection system installers is unwinding the competitive field, raising barriers for uncredentialed contractors. DEHN SE + Co KG leverages its German engineering heritage to dominate European surge protection supply. nVent Electric Plc anchors North American distribution through extensive channel partnerships with electrical contractors. ABB Ltd. competes on integrated power infrastructure platforms that bundle lightning protection with broader grid solutions.
Lightning protection systems encompass air terminals, surge protective devices, grounding electrodes, and conductor networks engineered to intercept, conduct, and dissipate atmospheric electrical discharges safely to earth. Copper and aluminum alloys with specified conductivity thresholds form the core conductor materials, while grounding resistance must typically fall below 25 ohms for effective dissipation per IEC 62305 design parameters. Surge protectors command the largest product type revenue pool due to recurring replacement cycles and electronics density growth. Industrial facilities represent the fastest-growing end user segment as automated production lines multiply vulnerability points. Retrofit installations now outpace new construction in mature building stock regions, concentrating margin capture with specialized service providers.
NFPA 780, IEC 62305, and UL 96A collectively govern product performance benchmarks and installation methodologies across the United States, Europe, and industrialized Asia-Pacific economies. The US National Electrical Code adoption by state jurisdictions creates fragmented compliance timelines that shape regional demand pulses. EMA and CE marking requirements in Europe enforce consistent surge protector safety thresholds for cross-border equipment shipments. Stakeholders must monitor evolving grid hardening mandates tied to climate adaptation funding flows rather than awaiting uniform federal standardization.
Market Dynamics
Retrofit installation demand in mature building stock regions is compressing project timelines and favoring specialized service providers with rapid-deployment capabilities over traditional electrical contractors.
Growth Catalysts
- IEC 62305 compliance mandates:European industrial facilities face mandatory surge protection upgrades for automated production lines, expanding replacement cycles for grounding electrode arrays.
- Data center density expansion:United States hyperscale operators are procuring advanced surge protection arrays to safeguard server rack power distribution units against transient overvoltages.
- Copper conductor specification tightening:German engineering standards for conductivity thresholds in lightning protection networks are elevating material grade requirements across Central European procurement.
Market Restraints
- Copper price volatility:Conductor material cost swings compress margin stability for installation contractors locked into fixed-price retrofit contracts.
- Specialized installer concentration:NFPA 780 certification scarcity in North American secondary markets extends project lead times and raises labor allocation costs.
- Grounding resistance technical floors:Subsurface soil conductivity limitations in rocky terrain regions prevent achieving IEC 62305 target thresholds without expensive deep-drilling electrode arrays.
Strategic Opportunities
- India industrial corridor buildout:BIS standards adoption for lightning protection in manufacturing zones under PLI scheme incentives creates specification-setting windows for early entrants.
- Solar-plus-storage integration:Convergence of photovoltaic array grounding with battery inverter surge protection opens bundled installation service contracts.
- Direct-to-facility digital channels:Industrial facility managers in Germany are bypassing traditional electrical distributor networks for specification-grade component procurement.
Industry Challenges
- NFPA 780 installer certification pipelines:Training program capacity constraints in United States secondary markets delay contractor qualification expansion.
- Legacy building structural integration:Historical masonry structures in European urban cores require non-invasive conductor routing that complicates standard installation methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightning Protection Systems Market |
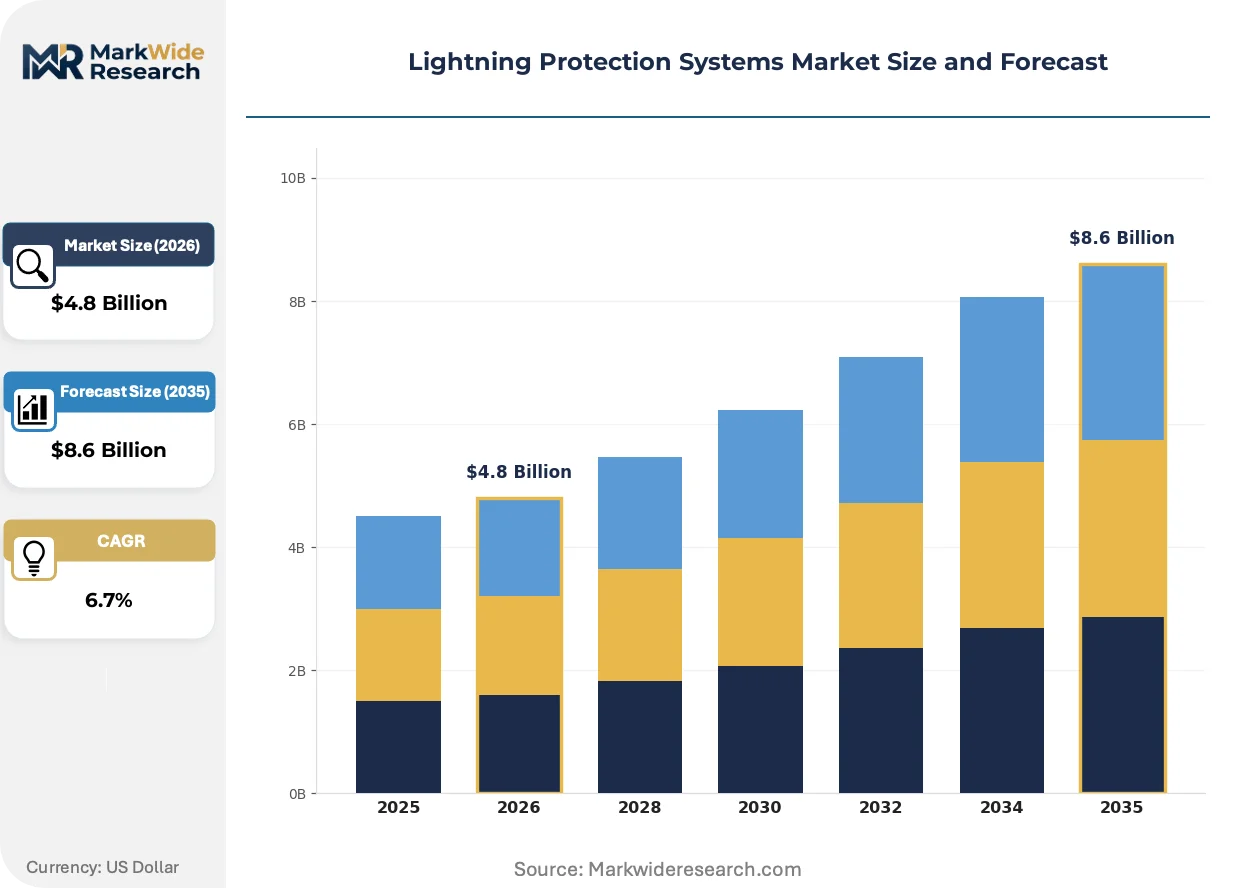
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Terminals, Surge Protectors, Grounding Systems, Cables End User: Commercial Buildings, Industrial Facilities, Residential Properties, Telecommunications Installation Type: New Installations, Retrofits, Upgrades, Maintenance Service Type: Design Services, Consulting, Installation Services, Inspection |
| Companies Covered | A.N. Wallis & Co. Ltd., ABB Ltd., DEHN SE + Co KG, ALLTEC LLC, Pentair, Harger Lightning & Grounding, Lightning Master Corporation, nVent Electric Plc, Raycap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightning Protection Systems Market Strategic Shifts
Active monitoring systems are displacing passive protection architectures, enabling predictive maintenance contracts and real-time impedance verification that reshape service revenue models across industrial end-uses.
Early Streamer Emission air terminals are decomposing traditional Franklin rod specifications in Middle Eastern petrochemical facilities. Saudi Aramco and ADNOC procurement divisions specify ESE systems for tank farm protection. This technology is decomposing the historical price premium commanded by conventional mesh cage designs in high-risk explosive atmosphere zones.
EMA surge protector safety thresholds under revised CE marking protocols enforce consistent impulse current ratings across cross-border equipment shipments. European industrial distributors must reconcile inventory to unified 10/350 µs waveform specifications. German testing houses in Munich and Stuttgart report certification queue extensions as manufacturers adapt legacy product lines.
Facility managers now bundle lightning protection with broader electrical infrastructure maintenance contracts rather than procuring standalone installation services. United States data center operators consolidate vendor relationships under integrated facility management agreements. This consolidation concentrates specification authority with procurement teams in Northern Virginia and Dallas-Fort Worth metro clusters.
Lightning Protection Systems Market Segmentation
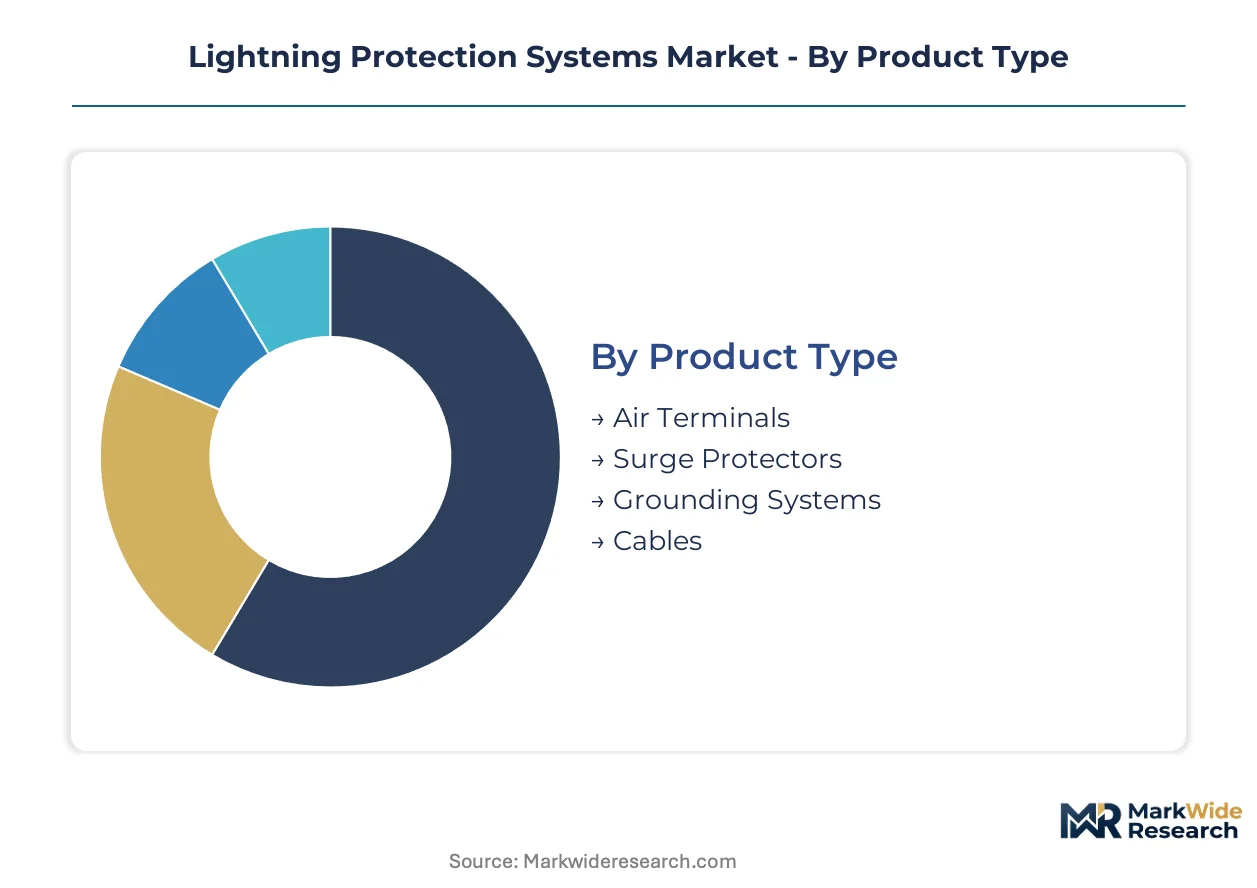
Lightning protection procurement fragments across four distinct category axes, each governed by divergent specification standards and replacement cycles. Product type selection drives material cost structures, while end-user verticals determine compliance stringency and service attachment rates.
Product Type:
Surge protectors face mounting substitution pressure from integrated power distribution units with built-in transient voltage suppression, threatening standalone component positioning.
- Air Terminals:Franklin rods and mesh cage systems fabricated from copper or aluminum alloys serve as primary interception points on structure rooftops. Saudi Aramco tank farm specifications in the Middle East are pivoting toward Early Streamer Emission variants, eroding traditional rod market share in petrochemical zones.
- Surge Protectors:Metal oxide varistor assemblies and gas discharge tubes clamp transient overvoltages across power and data lines. United States hyperscale data center operators in Northern Virginia are procuring advanced arrays with 10/350 µs waveform ratings to protect server rack PDUs.
- Grounding Systems:Electrode arrays and bonding networks achieve specified earth resistance thresholds per IEC 62305 parameters.
- Cables:Conductors with defined conductivity specifications interconnect terminal, grounding, and surge protection elements.
Surge protectors retain volume leadership; air terminals hold the steepest expansion curve.
End User:
Cost tier stratification separates specification-grade industrial procurement from price-sensitive residential installations.
- Industrial Facilities:Automated production lines with distributed control systems multiply vulnerability points requiring zone-based protection architectures. German manufacturing zones under tightened engineering standards are driving retrofit demand for grounding electrode upgrades.
- Commercial Buildings:Office towers and retail complexes balance aesthetic constraints with NFPA 780 compliance mandates. Dallas-Fort Worth metro clusters consolidate vendor relationships under integrated facility management agreements spanning lightning protection with broader electrical maintenance.
- Residential Properties:Single-family and multi-unit dwellings face sporadic code enforcement and owner-funded installation decisions.
- Telecommunications:Cellular towers and central office facilities require coordinated protection across RF transmission and DC power systems.
Industrial facilities command premium pricing tiers; commercial buildings generate the largest installed base volume.
Installation Type:
Application context determines labor allocation intensity and margin capture potential across project types.
- New Installations:Greenfield construction allows integrated design from structural steel erection through final commissioning. United States data center builds in Ashburn and Plano embed lightning protection specifications into electrical contractor bid packages.
- Retrofits:Mature building stock modifications compress timelines and favor specialized service providers with rapid-deployment capabilities. German industrial facility retrofit rates are climbing as IEC 62305 compliance deadlines approach.
- Upgrades:Partial system enhancements address specific vulnerability gaps without full replacement.
- Maintenance:Periodic inspection and component replacement contracts provide recurring revenue streams.
Retrofits are expanding most quickly; new installations anchor absolute revenue contribution.
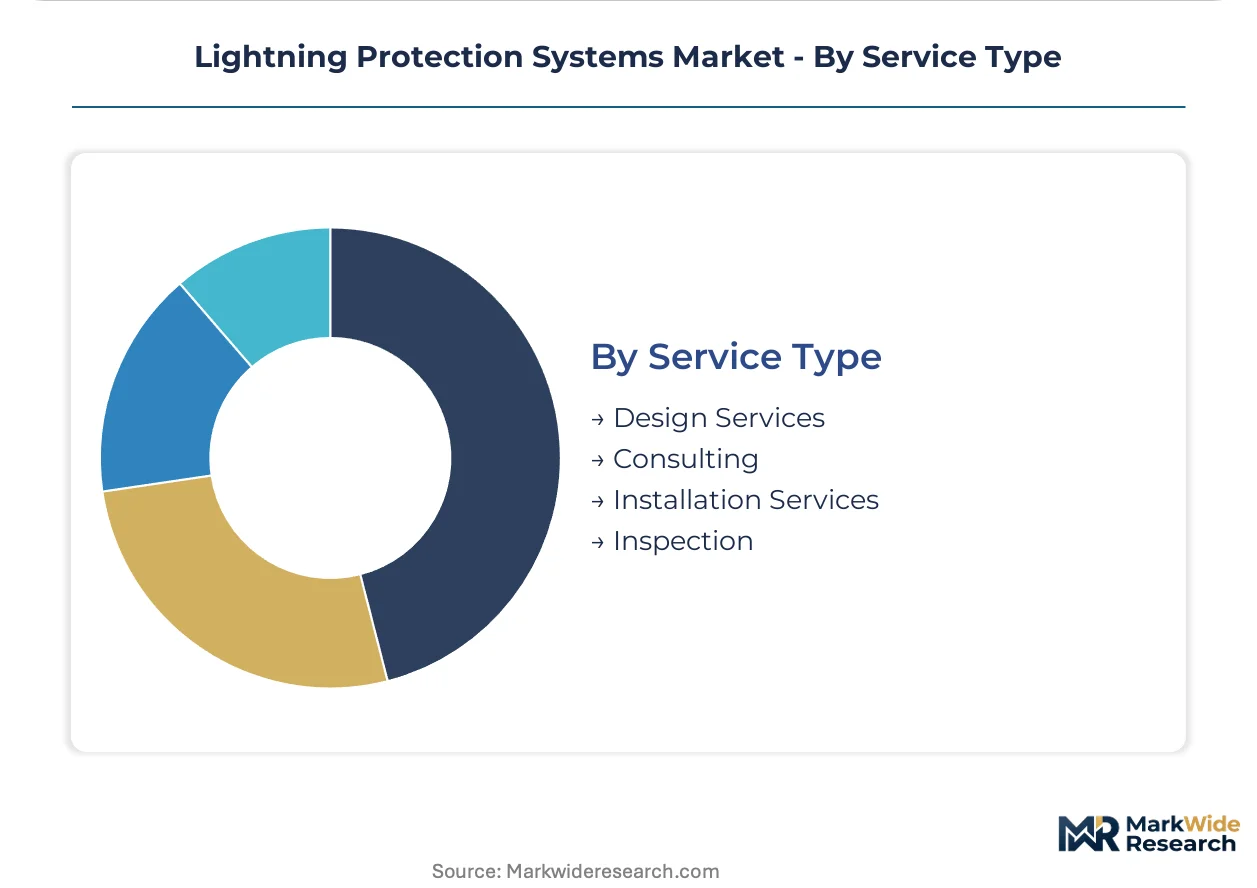
Service Type:
Customer type differentiation separates owner-operated facilities from third-party-managed properties with divergent procurement authority structures.
- Design Services:Engineering firms produce site-specific protection zone maps and component specifications. Munich and Stuttgart testing houses extend certification queues as manufacturers adapt legacy surge protector lines to revised EMA safety thresholds.
- Installation Services:Contractor crews execute physical mounting, bonding, and grounding work. NFPA 780 certification scarcity in United States secondary markets extends project lead times and raises labor allocation costs.
- Consulting:Advisory engagements assess existing system adequacy and compliance gaps.
- Inspection:Third-party verification services validate post-installation performance and ongoing integrity.
Installation services dominate current revenue; design services are gaining share fastest as specification complexity rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure resilience grants in the United States are accelerating lightning protection retrofits across critical facility portfolios. IEC 62305 adoption deadlines in Germany are compressing procurement timelines for industrial grounding upgrades. India's PLI scheme incentives are embedding BIS standards into new manufacturing zone specifications.
United States
Hyperscale data center expansion in Northern Virginia and Dallas-Fort Worth is driving surge protection array procurement for server rack power distribution units. NFPA 780 certification requirements are tightening installation compliance timelines and raising barriers for uncredentialed contractors. Ashburn and Plano electrical contractor bid packages now embed lightning protection specifications from structural steel erection through commissioning.
Germany
Industrial facility retrofit rates are climbing as automated production lines multiply vulnerability points requiring zone-based protection architectures. Engineering standards for copper conductor conductivity thresholds are elevating material grade requirements across Central European procurement. Munich and Stuttgart testing houses report certification queue extensions as manufacturers adapt legacy surge protector lines to revised EMA safety thresholds.
India
Manufacturing zone buildouts under PLI scheme incentives are creating specification-setting windows for lightning protection early entrants. BIS standards adoption is embedding surge protection mandates into new industrial corridor electrical infrastructure. Maharashtra and Gujarat industrial clusters are seeing bundled procurement of grounding electrodes with broader electrical contractor packages.
Saudi Arabia
Petrochemical tank farm protection specifications are pivoting toward Early Streamer Emission air terminal systems. Saudi Aramco procurement divisions are specifying ESE technology for explosive atmosphere zones, eroding traditional Franklin rod market share. Eastern Province industrial facilities are driving this specification shift across Middle Eastern high-risk installations.
China
Dual carbon goals are accelerating solar-plus-storage integration, converging photovoltaic array grounding with battery inverter surge protection. GB standards adoption is tightening lightning protection specifications for renewable energy infrastructure. Yangtze River Delta manufacturing zones are seeing bundled installation service contracts for combined grounding and surge protection systems.
Lightning Protection Systems Market Competitive Environment
Player mix skews toward integrated electrical infrastructure conglomerates with captive distribution networks. Tiered competitive positioning separates specification-grade engineering specialists from volume-driven component fabricators. Three archetypes dominate: German-engineered surge protection specialists, North American channel-anchored electrical contractors, and integrated power infrastructure platform providers. Geographic expansion through distributor partnerships and portfolio diversification into active monitoring systems represent the dominant competitive moves.
Within the German-engineered specialist tier, DEHN SE + Co KG exemplifies engineering heritage positioning, while ABB Ltd. occupies a position as an integrated platform provider bundling lightning protection with broader grid solutions. nVent Electric Plc anchors the North American channel-focused archetype through extensive electrical contractor partnerships. These three represent the competitive spectrum from pure-play surge protection through integrated infrastructure platforms.
| Leading Market Players |
|---|
| A.N. Wallis & Co. Ltd. |
| ABB Ltd. |
| DEHN SE + Co KG |
| ALLTEC LLC |
| Pentair |
| Harger Lightning & Grounding |
| Lightning Master Corporation |
| nVent Electric Plc |
| Raycap |
| Others |
Value Chain & Pricing Dynamics
NFPA 780 certification cycles gate both contractor qualification and project pricing power simultaneously, compressing margins for uncredentialed installers while elevating premium capture for credentialed specialists in United States secondary markets.
Pricing Analysis
Certification level creates the primary spread between installation tiers. Three-tier pricing structure across premium, standard, and economy levels reflects NFPA 780 credential status, copper alloy grade specifications, and bundled maintenance contract attachment. Cost compression in economy-tier residential retrofits is intensifying because aluminum conductor substitution erodes material cost premiums. Data center operators in Northern Virginia exhibit lowest price sensitivity due to equipment density risk exposure.
Supply Chain Analysis
Copper smelter concentration in Chile and Peru underwrites conductor material availability for lightning protection system fabricators. German and Chinese manufacturers dominate surge protective device assembly, drawing from rare earth oxide deposits for metal oxide varistor production. Single-source vulnerability in IEC 62305-certified testing house capacity creates certification queue bottlenecks. Distribution runs through electrical contractor networks in North America and industrial distributor channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where NFPA 780 and IEC 62305 certification scarcity creates switching-cost moats for credentialed installers.
For Market Incumbents: Consolidate certification pipeline control by acquiring training program capacity in United States secondary markets where NFPA 780 installer scarcity extends project lead times. Deepen backward integration into copper alloy drawing operations to buffer conductor material cost volatility from Chilean smelter output fluctuations. Active monitoring system R&D represents the priority capability investment as predictive maintenance contracts displace passive protection architectures. For New Entrants and Emerging Players: Lead with direct-to-facility digital channels targeting German industrial facility managers who are bypassing traditional electrical distributor networks for specification-grade component procurement. White-space concentration sits with solar-plus-storage bundled installation services in China's Yangtze River Delta manufacturing zones. Early Streamer Emission air terminal technology offers the most penetrable wedge into Middle Eastern petrochemical specifications where Saudi Aramco procurement divisions are specifying ESE systems. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrical infrastructure service platforms holding NFPA 780-certified installer networks in fragmented United States secondary markets. Long-term viability hinges on regulatory entrenchment durability rather than technology disruption exposure. Monitor IEC 62305 compliance deadline extensions in European industrial corridors as the inflection signal for retrofit demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Acquisition | NFPA 780 training program capacity in United States secondary markets captures scarce installer labor pools. |
| Active Monitoring System Launch | Predictive maintenance contracts with German industrial facilities reshape recurring revenue attachment rates. |
| Copper Alloy Backward Integration | In-house conductor drawing operations insulate margin stability from Chilean smelter price volatility. |
| Direct-to-Facility Digital Channel | Bypassing electrical distributors in Germany concentrates specification authority with procurement teams. |
| ESE Technology Licensing | Saudi Aramco tank farm specifications in Eastern Province accelerate Middle Eastern petrochemical adoption. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with lightning protection system installers, electrical contractor procurement leads, industrial facility maintenance directors, and surge protective device manufacturing engineers; and secondary validation through NFPA 780 certification registries, IEC 62305 testing house certification queues, United States National Electrical Code adoption databases, and copper alloy trade flow customs records. Bottom-up project pipeline tracking and top-down facility stock modeling were triangulated against manufacturer shipment data.
Across the analysis window, projections integrate product type segmentation by air terminal, surge protector, grounding system, and cable categories; end-user verticals spanning industrial facilities, commercial buildings, residential properties, and telecommunications; and installation type splits between new construction and retrofit applications. CAGRs were derived from facility stock aging curves, regulatory compliance deadline schedules, and copper price scenario modeling.
Forecasts assume regulatory continuity in NFPA 780 adoption timelines across United States state jurisdictions and IEC 62305 enforcement patterns in European industrial zones; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as copper price volatility and certification pipeline capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Saudi Arabia Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Chemical Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market