
 Welding Helmets Market | 2026-2036
Welding Helmets Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Helmets Market Analysis
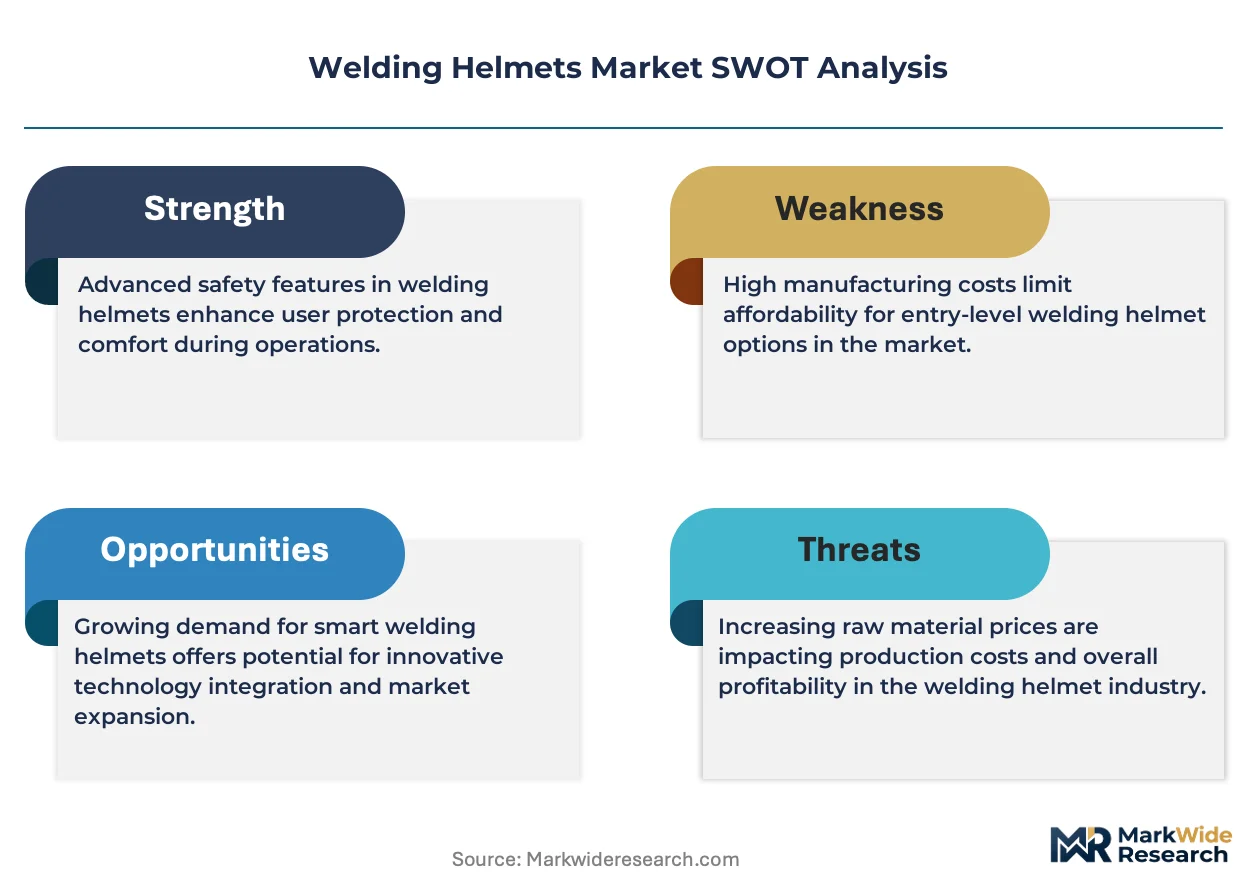
Polycarbonate is repositioning fiberglass in mid-tier welding helmets by cutting shell weight without sacrificing impact resistance. Lincoln Electric leverages captive lens technology to sustain premium positioning across North American distribution. ESAB dominates European channels through specialized optical controls for precision arc processes. 3M competes on respiratory integration, bundling powered air-purifying systems with helmet platforms to extend average revenue per user.
Welding helmets are personal protective equipment comprising a rigid shell, auto-darkening or fixed-shade lens assembly, and adjustable headgear designed to shield the face and eyes from ultraviolet radiation, infrared radiation, and molten metal spatter during fusion welding, cutting, and grinding operations. Auto-darkening variants employ liquid crystal display technology with arc sensors achieving dark-state switching speeds below 0.00004 seconds to prevent flash burn. The product type landscape shows passive helmets retaining share in price-sensitive developing markets while specialized configurations for plasma cutting and oxy-fuel applications capture margin pools in oil and gas end use. Material selection bifurcates along thermal performance lines, with nylon formulations gaining ground in lightweight designs for extended-wear construction tasks where operator fatigue directly influences productivity.
OSHA enforces ANSI Z87.1 impact and optical clarity standards that dictate minimum lens performance thresholds for workplace compliance across the United States. The EU's PPE Regulation 2016/425 mandates CE marking and third-party certification for welding helmets entering European markets, while India's BIS QCO order phases in compulsory quality control for domestically sold protective equipment. China's GB standards for welding PPE are tightening optical class requirements, pressuring exporters to upgrade testing protocols. Stakeholders must monitor how divergent certification timelines across these jurisdictions reshape sourcing strategies and inventory segmentation for multinational fleet deployments.
Market Dynamics
Auto-darkening liquid crystal technology is compressing replacement cycles as construction and shipbuilding fleets upgrade from passive fixed-shade systems to meet tightening workplace safety mandates.
Growth Catalysts
- India's BIS QCO mandate:Compulsory quality control certification phases in across 2024-2026, forcing domestic and imported helmet inventories toward ANSI Z87.1-equivalent optical performance.
- Vietnam shipbuilding clusters:Haiphong and Ba Ria-Vung Tau yards are standardizing on arc-sensor helmets for stick and MIG processes as export contract specifications harden.
- Polycarbonate shell substitution:Nylon and polycarbonate formulations displace fiberglass in mid-tier construction helmets, cutting headgear weight by 30-40% for extended-wear productivity.
Market Restraints
- Lithium battery supply concentration:Auto-darkening helmet power systems depend on cylindrical cell supply chains centered in East Asia, exposing OEMs to cell chemistry allocation constraints.
- Optical class testing bottlenecks:CE marking under EU PPE Regulation 2016/425 requires notified body intervention for lens assemblies, extending time-to-market for new LCD filter designs.
- Passive helmet price anchoring:Fixed-shade polycarbonate units retain 40-50% share in price-sensitive developing markets, compressing margin expansion for sensor-equipped variants.
Strategic Opportunities
- Brazil OSHA-style enforcement:Emerging market regulatory alignment creates replacement demand in São Paulo and Rio de Janeiro industrial corridors previously served by uncertified equipment.
- Respiratory-helmet convergence:Powered air-purifying respirator integration with auto-darkening platforms opens margin pools in confined-space fabrication and tank welding.
- Direct procurement platforms:Industrial distributors and fleet operators are consolidating supplier relationships through volume-based e-procurement, bypassing traditional welding supply retail.
Industry Challenges
- Arc sensor calibration expertise:Field service networks lack technicians trained to diagnose photodiode array failures and liquid crystal degradation in multi-sensor helmet configurations.
- Dual certification complexity:Manufacturers targeting both EU and Indian markets face divergent testing protocols for optical switching speed and ultraviolet transmittance, duplicating validation spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Helmets Market |
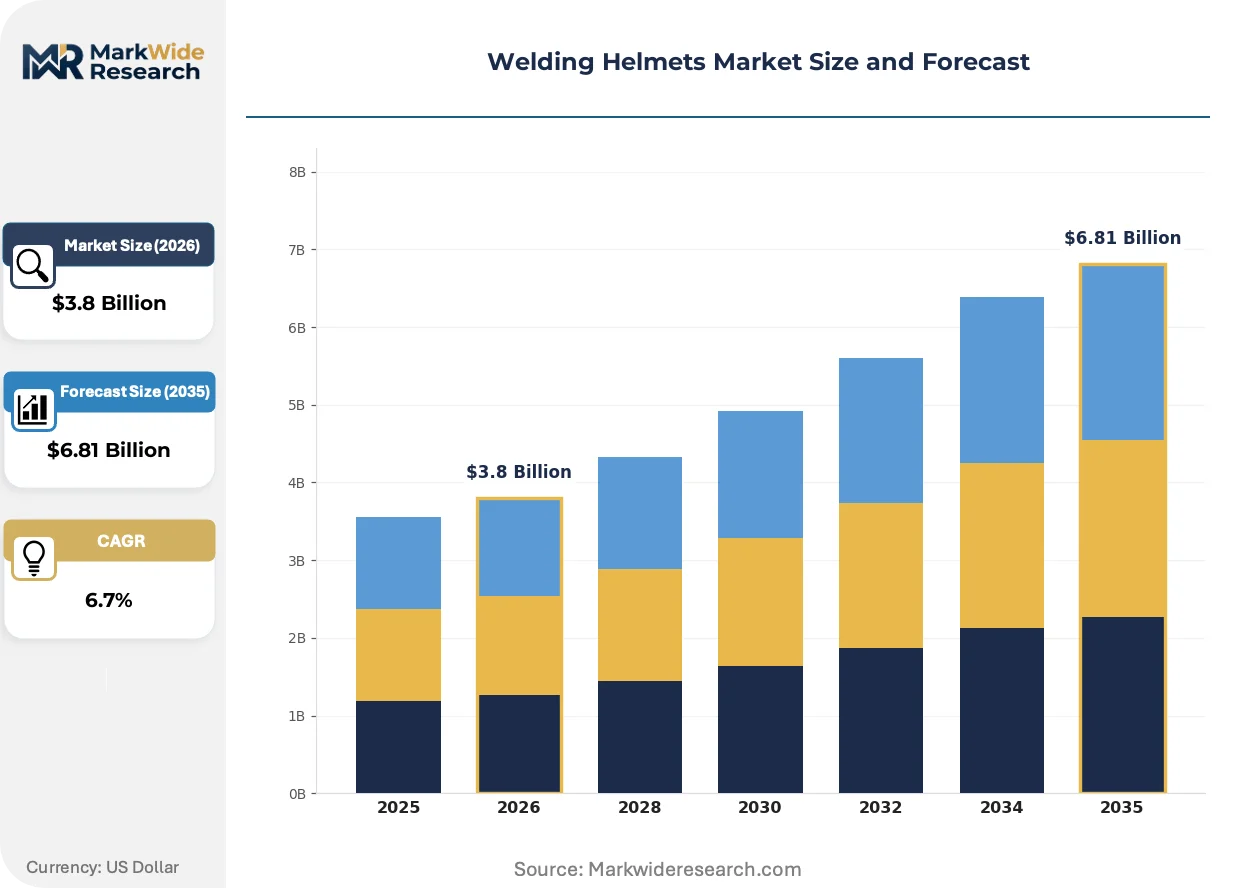
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto-Darkening, Passive, Lift Front, Specialized End User: Manufacturing, Construction, Automotive, Oil & Gas Material: Polycarbonate, Nylon, Fiberglass, Steel Feature: Anti-Fog, UV Protection, Adjustable, Lightweight |
| Companies Covered | 3M, Honeywell, Lincoln Electric, Fronius International, Jackson Safety, Illinois Tool Works (ITW), Optrel AG, GYS, ESAB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Helmets Market Emerging Trajectories
Helmet functionality is expanding beyond eye protection toward integrated respiratory and communication systems, while material science and regulatory harmonization reshape competitive positioning.
Grind mode functionality is integrating into base auto-darkening platforms, allowing operators to switch between welding dark states and grinding visibility without removing headgear. Fabrication shops in Germany and the US Midwest are specifying this as standard for multi-process workstations. The convergence is compressing demand for standalone grinding shields and forcing suppliers to bundle capabilities at mid-tier price points.
China's GB standards for welding PPE are tightening optical class requirements for lens assemblies, pressuring exporters to upgrade testing protocols or exit the market. The State Administration for Market Regulation is aligning domestic certification with ISO 16321 performance benchmarks. European and North American OEMs serving Chinese industrial customers must now duplicate optical clarity validation under SAMR-recognized laboratories.
Fleet operators in Southeast Asian construction are consolidating helmet procurement through project-level safety contracts rather than individual operator purchase. Large contractors in Vietnam and Indonesia are specifying auto-darkening helmets as a condition of subcontractor qualification. This concentrates purchasing authority with safety managers and compresses the role of traditional welding supply distributors in volume accounts.
Welding Helmets Market Segmentation
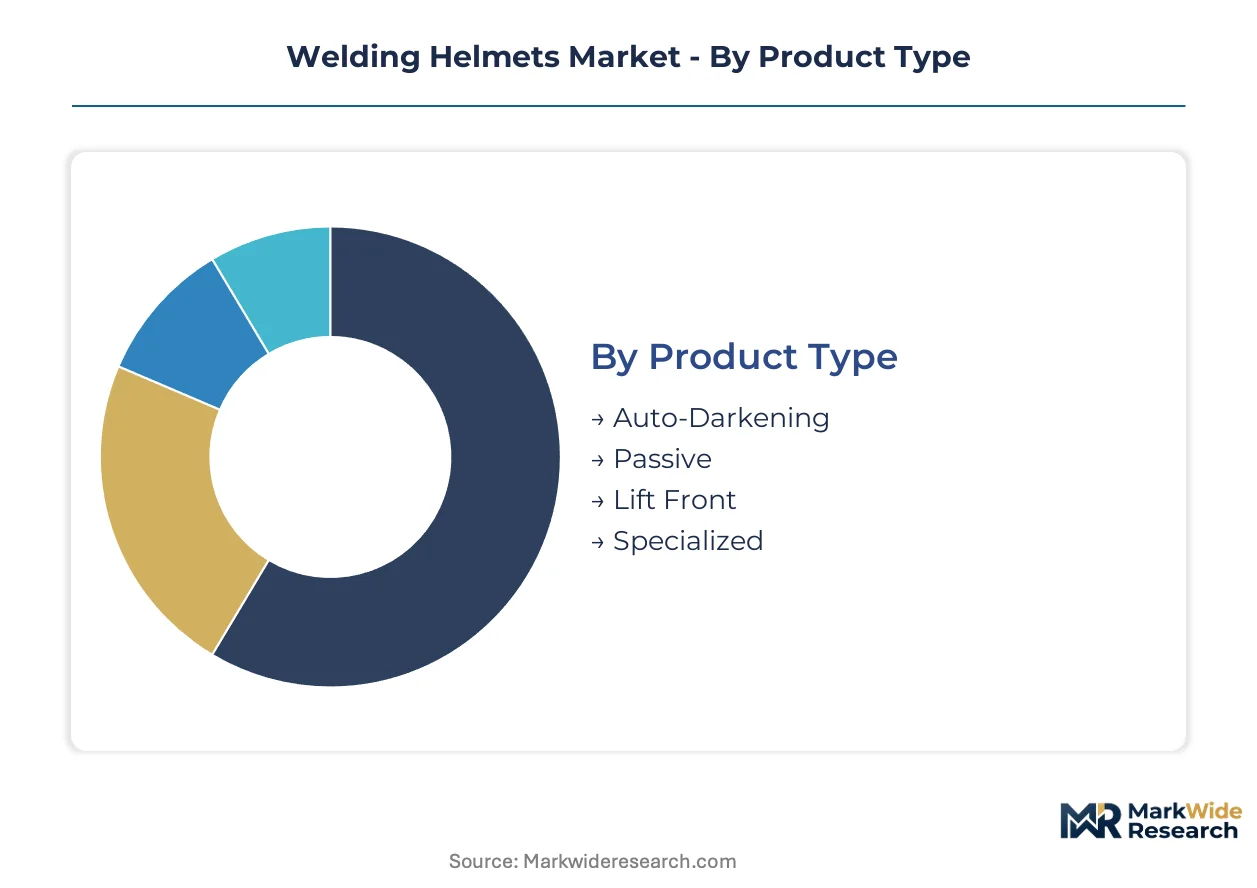
Welding helmet procurement increasingly segments by certification grade rather than price point alone. Fleet operators now specify ANSI Z87.1 or CE marking compliance before considering optical class or shell material, reshaping supplier qualification criteria across industrial channels.
Product Type:
Auto-darkening variants carry the heaviest certification burden under EU PPE Regulation 2016/425 and India's BIS QCO mandate, while passive helmets face lighter optical testing requirements in price-sensitive markets.
- Auto-Darkening:Liquid crystal display assemblies with arc sensors achieve dark-state switching below 0.00004 seconds. Demand concentrates in Vietnam's shipbuilding zones where Haiphong yards mandate arc-sensor helmets for stick and MIG processes under export contract specifications.
- Passive:Fixed-shade polycarbonate units retain dominant share in developing markets where operator purchase decisions prioritize upfront cost over productivity features. Brazil's OSHA-style enforcement is compressing this segment's addressable market in São Paulo industrial corridors.
- Lift Front:Mechanical shade adjustment mechanism suits occasional welders in maintenance and repair operations. India's BIS certification push is forcing lift-front suppliers toward ANSI-equivalent optical performance.
- Specialized:Configurations for plasma cutting and oxy-fuel applications target oil and gas end use with enhanced spatter resistance and extended neck coverage.
Leading the category by volume: Passive. Growing fastest: Auto-Darkening.
End User:
Construction and shipbuilding fleets drive volume procurement through consolidated safety contracts, while automotive and oil and gas segments prioritize specialized optical performance for precision processes.
- Manufacturing:Fabrication shops in Germany and the US Midwest specify grind mode functionality as standard for multi-process workstations, compressing demand for standalone grinding shields.
- Construction:Southeast Asian contractors are consolidating helmet procurement through project-level safety contracts rather than individual operator purchase, concentrating buying authority with safety managers. Large contractors in Vietnam and Indonesia specify auto-darkening helmets as a condition of subcontractor qualification.
- Automotive:Precision arc processes require specialized optical controls for consistent weld quality, favoring helmets with adjustable sensitivity and delay settings.
- Oil & Gas:Confined-space fabrication and tank welding operations drive respiratory-helmet convergence, with powered air-purifying respirator integration opening margin pools in this segment.
Construction commands the largest procurement volumes. Oil and Gas shows the steepest expansion trajectory for integrated respiratory platforms.
Material:
Weight reduction imperatives in extended-wear applications are accelerating substitution away from traditional fiberglass toward engineered thermoplastics.
- Polycarbonate:Impact-resistant thermoplastic cuts shell weight without sacrificing structural integrity. Nylon and polycarbonate formulations displace fiberglass in mid-tier construction helmets, reducing headgear weight by 30-40% for extended-wear productivity.
- Nylon:Lightweight formulations gain ground in construction tasks where operator fatigue directly influences daily output. India's industrial corridors show particular appetite for nylon-shell helmets in high-temperature fabrication environments.
- Fiberglass:Traditional composite retains position in premium thermal performance tiers but loses share to thermoplastics in volume construction applications.
- Steel:Heavy-duty shell material persists in foundry and heavy fabrication settings where molten metal exposure risk exceeds weight considerations.
Polycarbonate leads material selection by unit volume. Nylon climbs fastest as construction fleets prioritize operator endurance.
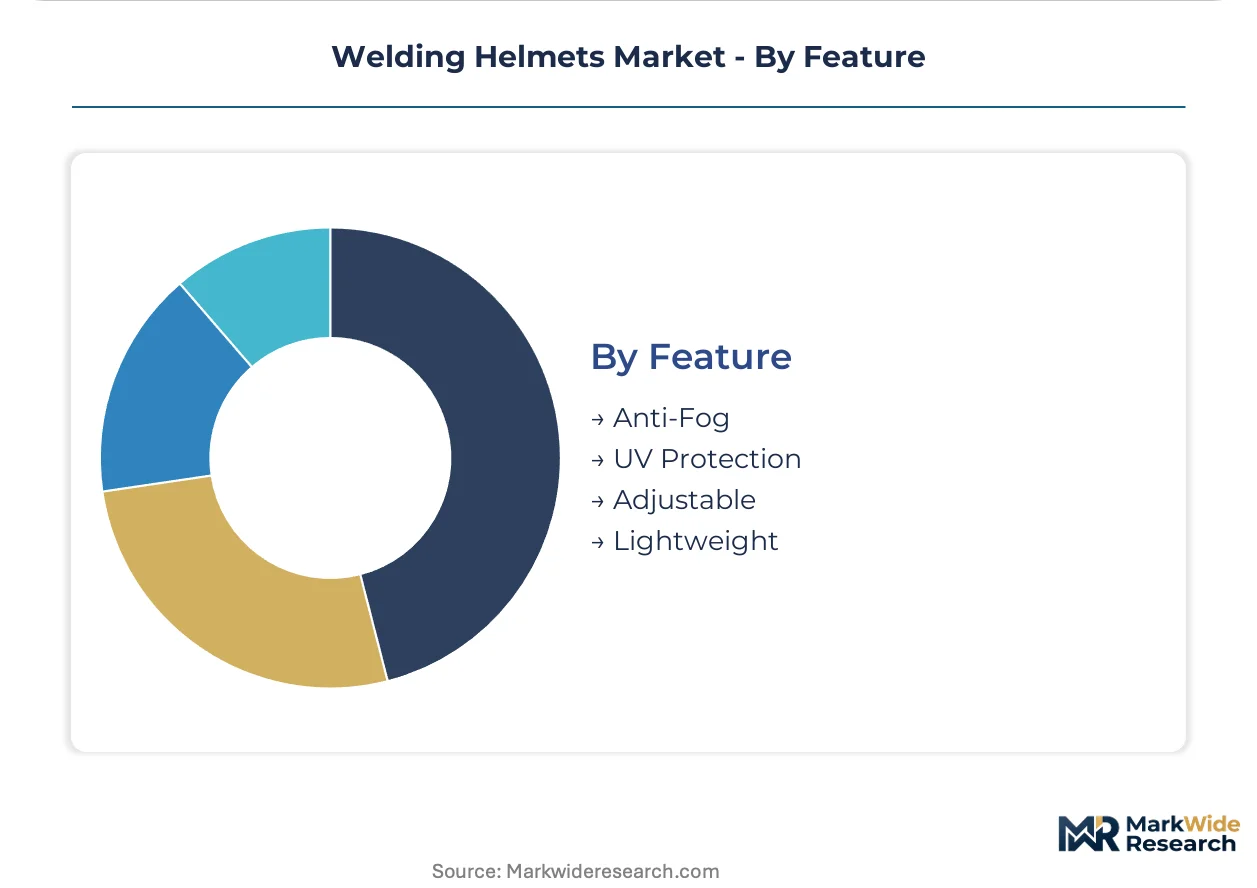
Feature:
Feature bundling now follows end-use hazard profiles rather than price tiering, with respiratory integration and communication systems commanding premium positioning.
- Anti-Fog:Ventilation engineering and hydrophobic coatings address humidity challenges in tropical construction markets and confined-space operations. Southeast Asian procurement specifications increasingly mandate anti-fog performance.
- UV Protection:Ultraviolet transmittance standards under China's tightening GB requirements pressure exporters to upgrade testing protocols. CE marking and BIS QCO both specify UV attenuation thresholds.
- Adjustable:Ratcheting headgear and multiple pivot points accommodate diverse operator anthropometrics, reducing fit-related compliance failures in multinational fleet deployments.
- Lightweight:Shell mass reduction through material substitution and structural optimization targets extended-shift productivity in construction and shipbuilding applications.
Lightweight features dominate procurement specifications. Anti-Fog capabilities expand most quickly in tropical and confined-space applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Vietnam and India's industrial corridors concentrate welding helmet demand as export-oriented manufacturing expands. Brazil's OSHA-style enforcement and China's GB standard tightening reshape procurement patterns across emerging markets.
United States
OSHA enforces ANSI Z87.1 standards that dictate minimum lens performance thresholds for workplace compliance. Fabrication shops in the US Midwest specify grind mode functionality as standard for multi-process workstations. Construction fleets in Texas and the Southeast consolidate procurement through volume-based e-procurement platforms.
Germany
CE marking under EU PPE Regulation 2016/425 mandates third-party certification for welding helmets entering European markets. The country's fabrication sector drives demand for specialized optical controls in precision arc processes. Industrial clusters in North Rhine-Westphalia standardize on auto-darkening platforms with respiratory integration for confined-space operations.
India
BIS QCO mandates phase in compulsory quality control certification across 2024-2026, forcing inventories toward ANSI Z87.1-equivalent optical performance. The regulator's tightening requirements accelerate replacement cycles in Maharashtra and Gujarat industrial corridors. Tamil Nadu's automotive fabrication clusters specify auto-darkening helmets as subcontractor qualification conditions.
Vietnam
Haiphong and Ba Ria-Vung Tau shipbuilding yards standardize on arc-sensor helmets for stick and MIG processes under export contract specifications. The country's SEZ incentives attract fabrication investment that drives fleet procurement. Construction contractors in Ho Chi Minh City consolidate helmet purchasing through project-level safety contracts rather than individual operator acquisition.
Brazil
OSHA-style workplace requirements in São Paulo and Rio de Janeiro industrial corridors accelerate replacement of uncertified equipment. ANVISA-aligned safety enforcement creates demand for certified protective equipment previously served by informal supply chains. Petrobras-linked fabrication yards in Rio de Janeiro state specify auto-darkening helmets with enhanced spatter resistance for oil and gas applications.
Welding Helmets Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier optical technology concentrating among European and North American incumbents while Asian fabricators dominate volume production of passive helmet shells. The market exhibits tiered structure around certification grade rather than price point alone. Three archetypes anchor positioning: integrated industrial conglomerates with captive distribution, specialized PPE pure-plays with optical expertise, and contract manufacturers serving private-label retail. Dominant competitive moves include backward integration into lens assembly production and geographic expansion through distributor acquisition in Southeast Asian construction markets.
Among diversified industrial conglomerates, 3M and Honeywell exemplify scale-driven positioning that bundles respiratory systems with helmet platforms to extend revenue per user. Lincoln Electric occupies a position within the welding equipment-integrated tier, leveraging captive technology to sustain premium positioning across North American channels. ESAB represents the specialized optical control archetype, dominating European distribution through precision arc process expertise.
| Leading Market Players |
|---|
| 3M |
| Honeywell |
| Lincoln Electric |
| Fronius International |
| Jackson Safety |
| Illinois Tool Works (ITW) |
| Optrel AG |
| GYS |
| ESAB |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in East Asian manufacturing clusters anchor supply-side discipline, translating captive lens-assembly capabilities into pricing power that resists commoditization pressure from passive-helmet imports.
Pricing Analysis
Short lead-time premiums separate urgent fleet replacement orders from standard procurement cycles, with construction contractors in Vietnam's shipbuilding zones paying markups for certified auto-darkening inventory. Three-tier pricing structure across premium, standard, and economy levels aligns with optical class certification under ANSI Z87.1 and CE marking tiers. Price differentiation rests on arc-sensor calibration precision and respiratory integration bundling. Cost compression in economy passive helmets is intensifying because polycarbonate shell oversupply from Chinese fabricators floods spot markets. Individual operators in India's informal construction sector exhibit highest price sensitivity, while oil and gas fleet managers in Brazil prioritize certification compliance over unit cost.
Supply Chain Analysis
Direct-to-fleet channels handle consolidated procurement from Southeast Asian construction contractors, bypassing traditional welding supply distributors. Manufacturing concentrates in China, South Korea, and Vietnam, with polycarbonate resin and liquid crystal display assemblies drawing from East Asian chemical and electronics feedstocks. Lithium cylindrical cell supply for auto-darkening power systems sources from concentrated East Asian battery producers, creating single-source vulnerability for OEMs without dual-qualified cell vendors. Distribution runs through industrial safety distributors, e-procurement platforms, and direct OEM relationships with multinational fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification mandate acceleration across India and Brazil is compressing margins for uncertified inventory holders, forcing consolidation among passive-helmet specialists unable to fund ANSI-equivalent optical testing.
For Market Incumbents: Deploy backward integration into arc-sensor calibration facilities to capture service revenue from fleet operators lacking field technician networks. Incumbents must consolidate distributor relationships in Vietnam's shipbuilding corridors before regional champions lock project-level safety contracts. The threat of respiratory-helmet convergence from 3M and Honeywell demands captive R&D investment in powered air-purifying integration to defend premium positioning. For New Entrants and Emerging Players: E-procurement platforms offer the lowest-friction entry path for certified auto-darkening variants targeting mid-tier construction fleets in Indonesia and Philippines. White-space concentrates in lift-front configurations for India's maintenance and repair segment, where BIS QCO compliance gaps persist among domestic suppliers. A direct-to-fleet digital sales model with volume-based pricing undercuts traditional distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor optical-technology specialists with CE marking infrastructure in Poland and Czech Republic manufacturing zones. Long-term viability hinges on regulatory harmonization momentum across EU PPE Regulation 2016/425 and India's BIS QCO timelines. The inflection signal to watch is accelerated notified body queue clearance for LCD lens assemblies, indicating capacity for certification-driven replacement volume.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lens Assembly | Captive optical production secures CE marking speed for EU market access. |
| Respiratory Platform Convergence | PAPR integration captures oil and gas confined-space fabrication margins. |
| Direct Fleet E-Procurement Launch | Bypassing distributors concentrates pricing power with safety managers. |
| Dual Certification Investment | Parallel ANSI Z87.1 and BIS QCO testing unlocks India replacement demand. |
| Regional Distributor Acquisition | Vietnam and Indonesia channel control secures shipbuilding contract flow. |
Methodological Framework
Trade databases, regulatory filing repositories, and industrial safety equipment customs records formed the secondary backbone, cross-referenced with primary interviews of welding equipment procurement managers, fleet safety directors, optical component suppliers, and notified body certification specialists. Bottom-up and top-down triangulation validated volume estimates against polycarbonate resin consumption patterns and auto-darkening LCD panel shipment data.
Bottom-up modeling anchored projections in segment-level unit economics across product type, material formulation, and end-use application, while top-down cross-checks applied macro industrial production indices from construction and shipbuilding sectors. Segmentation dimensions included certification grade, shell material, optical technology, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to replacement cycle compression rates under tightening OSHA-style mandates. Industry-specific inputs incorporated arc-sensor switching speed benchmarks and lithium cell supply allocation constraints.
The model holds under steady regulatory enforcement trajectories; deviation in certification timeline delays or raw material supply shocks would shift replacement cycle assumptions. Forecasts reflect base-case assumptions regarding BIS QCO phase-in adherence and EU notified body capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Shock Trouser Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Sports Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsically Safe Lighting Market