
 Anti-Fatigue Mats Market | 2026-2036
Anti-Fatigue Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Fatigue Mats Market Intelligence
Healthcare facilities is redrawing procurement priorities as the fastest-expanding buyer archetype in the anti-fatigue mats landscape. M+A Matting leverages its specialized healthcare-grade product lines to capture this shift. 3M Corporation sustains technology leadership through advanced polyurethane formulations that reduce joint stress metrics. Smart Step Flooring anchors its position in commercial kitchen and retail segments where slip-resistant surfaces command premium placement.
Anti-fatigue mats are engineered floor coverings constructed from foam, rubber, gel, or polyurethane composites designed to reduce musculoskeletal strain during prolonged standing through controlled compression and energy return. These products typically incorporate beveled edges, antimicrobial surface treatments, and grease-proof backing to meet commercial and industrial safety requirements. Foam mats dominate current volume due to cost efficiency in high-turnover commercial environments, while gel mats capture the fastest expansion in healthcare facilities where pressure-distribution performance justifies higher unit economics. Rubber mats retain stable industrial demand where chemical resistance and durability thresholds override comfort prioritization, with margin pools concentrating in custom-sized and logo-imprinted commercial applications.
OSHA workplace safety standards and the Americans with Disabilities Act accessibility provisions directly shape product specifications and facility compliance budgets across the United States. The National Floor Safety Institute certification requirements and state-level workers compensation cost pressures further tighten the specification environment for matting procurement. Stakeholders must monitor evolving ergonomic assessment protocols and standing-desk adjacency trends that are redefining product form factors beyond traditional workstation boundaries.
Market Dynamics
OSHA workplace safety enforcement around standing-duration limits is compressing replacement cycles and expanding specification budgets across warehouse, logistics, and healthcare facilities. This regulatory pressure is redefining procurement priorities away from commodity floor coverings toward engineered ergonomic solutions with certified performance metrics.
Growth Catalysts
- Warehouse automation expansion:Distribution center buildouts in the United States are mandating anti-fatigue matting at every standing workstation to comply with OSHA ergonomic guidelines. Facility managers are specifying gel-composite surfaces for high-velocity picking zones.
- Americans with Disabilities Act accessibility provisions:ADA Title III requirements for accessible design are driving retrofits in retail and hospitality environments. Beveled-edge mat specifications with slip-resistant certification are becoming standard in customer-facing commercial spaces.
- Polyurethane formulation advances:New energy-return composites are reducing joint stress metrics by measurable margins in healthcare settings. Hospital procurement committees are prioritizing pressure-distribution performance over unit cost in surgical suite and pharmacy applications.
Market Restraints
- Petrochemical input volatility:Polyurethane and synthetic rubber feedstock prices fluctuate with crude oil indices, compressing margin stability for mid-tier manufacturers. Formulation cost hedging remains underdeveloped across the supplier base.
- Asia-Pacific production concentration:Foam mat manufacturing clusters in southeastern China dominate global volume, creating freight cost exposure and tariff vulnerability for North American and European distributors.
- Durability-performance tradeoff:Gel-based comfort layers degrade faster than rubber alternatives in high-traffic industrial environments, limiting addressable market share in chemical processing and heavy manufacturing verticals.
Strategic Opportunities
- India manufacturing and logistics buildout:PLI scheme incentives for warehouse infrastructure are creating first-mover advantage for anti-fatigue mat suppliers with BIS-certified product lines. Domestic fulfillment center expansion is outpacing ergonomic equipment penetration.
- Smart mat sensor integration:Convergence of pressure-mapping technology with IoT connectivity is enabling real-time ergonomic monitoring. Occupational health departments in German automotive plants are piloting connected matting systems.
- Standing-desk adjacency expansion:Corporate wellness programs in United Kingdom financial services are specifying anti-fatigue surfaces for open-plan office retrofits. This application category remains underpenetrated relative to industrial end-uses.
Industry Challenges
- NFSI certification timeline compression:National Floor Safety Institute testing protocols require extended slip-resistance validation cycles that delay product launches. Manufacturers face backlog at accredited testing laboratories.
- Antimicrobial additive compliance fragmentation:EPA registration requirements for surface treatments differ from state-level chemical disclosure mandates in California and New York. Formulation teams must maintain multiple product variants.
- Custom sizing capex intensity:Die-cutting equipment for logo-imprinted commercial applications requires dedicated production lines with limited utilization rates. Smaller fabricators struggle to amortize specialized machinery investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Fatigue Mats Market |
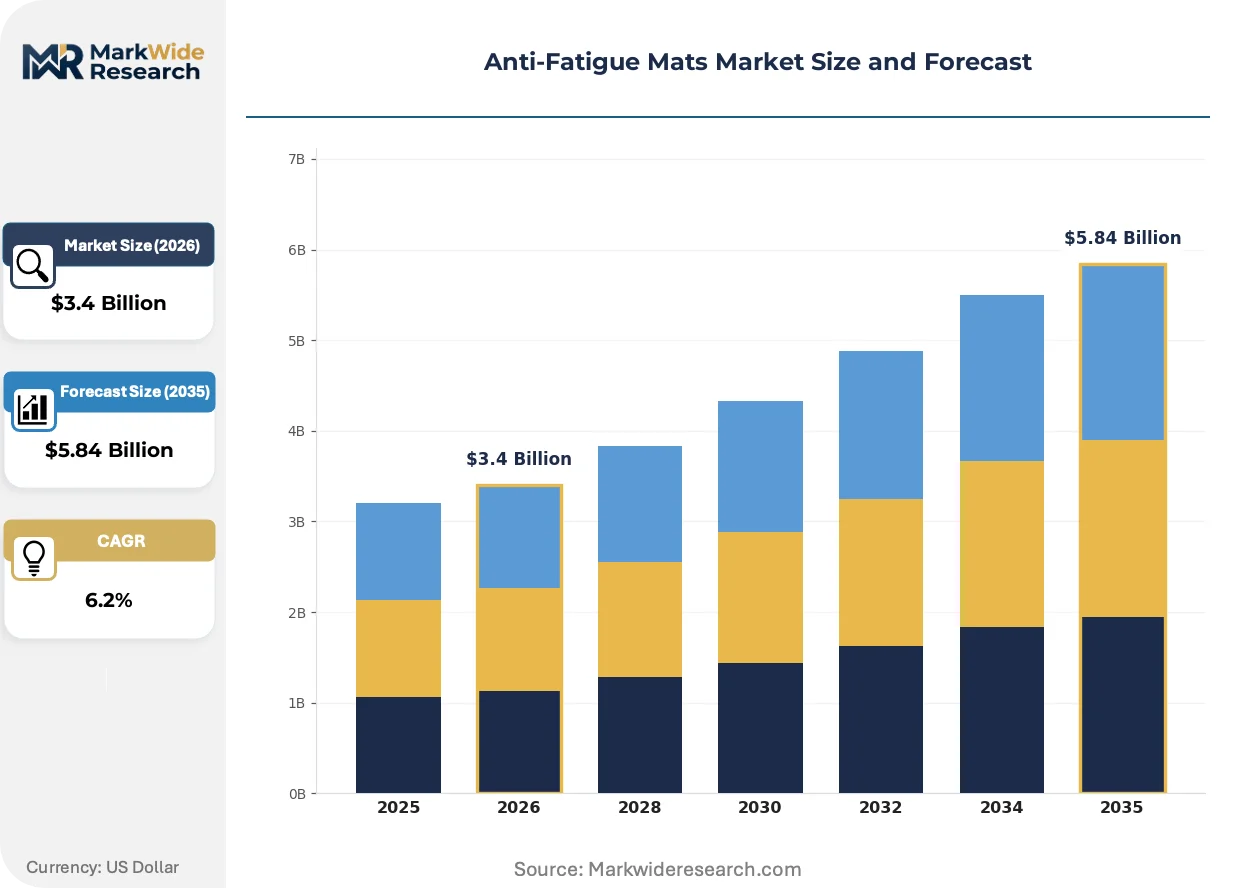
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Mats, Rubber Mats, Gel Mats, Vinyl Mats Application: Commercial Use, Industrial Use, Home Use, Healthcare Facilities Size: Small, Medium, Large, Extra Large Material: Foam, Rubber, Polyurethane, Fabric |
| Companies Covered | Smart Step Flooring, Cintas Corporation, NoTrax, M+A Matting, Euronics Industries Pvt Ltd, 3M Corporation, Durable Corporation, UniFirst Corporation, Wearwell, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Fatigue Mats Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory precision are converging to redefine performance benchmarks across comfort, durability, and safety certification dimensions. Suppliers are racing to integrate sensor capabilities while compressing formulation costs.
Micro-cellular polyurethane foam is miniaturizing internal cell structures to achieve denser energy-return profiles without weight penalties. Healthcare facilities in the United States are adopting these advanced composites for surgical team comfort during prolonged procedures. The technology is miniaturizing the performance gap between premium gel systems and cost-efficient foam alternatives.
EU REACH restrictions on isocyanate exposure in manufacturing processes are forcing reformulation of conventional polyurethane production lines. German and Polish mat producers are investing in closed-mold injection systems to maintain CE marking compliance. Industrial-grade rubber matting categories face the steepest cost adjustments as alternative curing agents undergo efficacy validation.
Corporate procurement departments are consolidating vendor relationships through multi-site framework agreements that bundle matting with scheduled deep-cleaning services. Third-party facility management providers in Japan are displacing direct manufacturer relationships in pharmaceutical manufacturing plants. This consolidation pattern is most visible in metropolitan Osaka and Tokyo industrial corridors where centralized purchasing authority has concentrated.
Anti-Fatigue Mats Market Segmentation
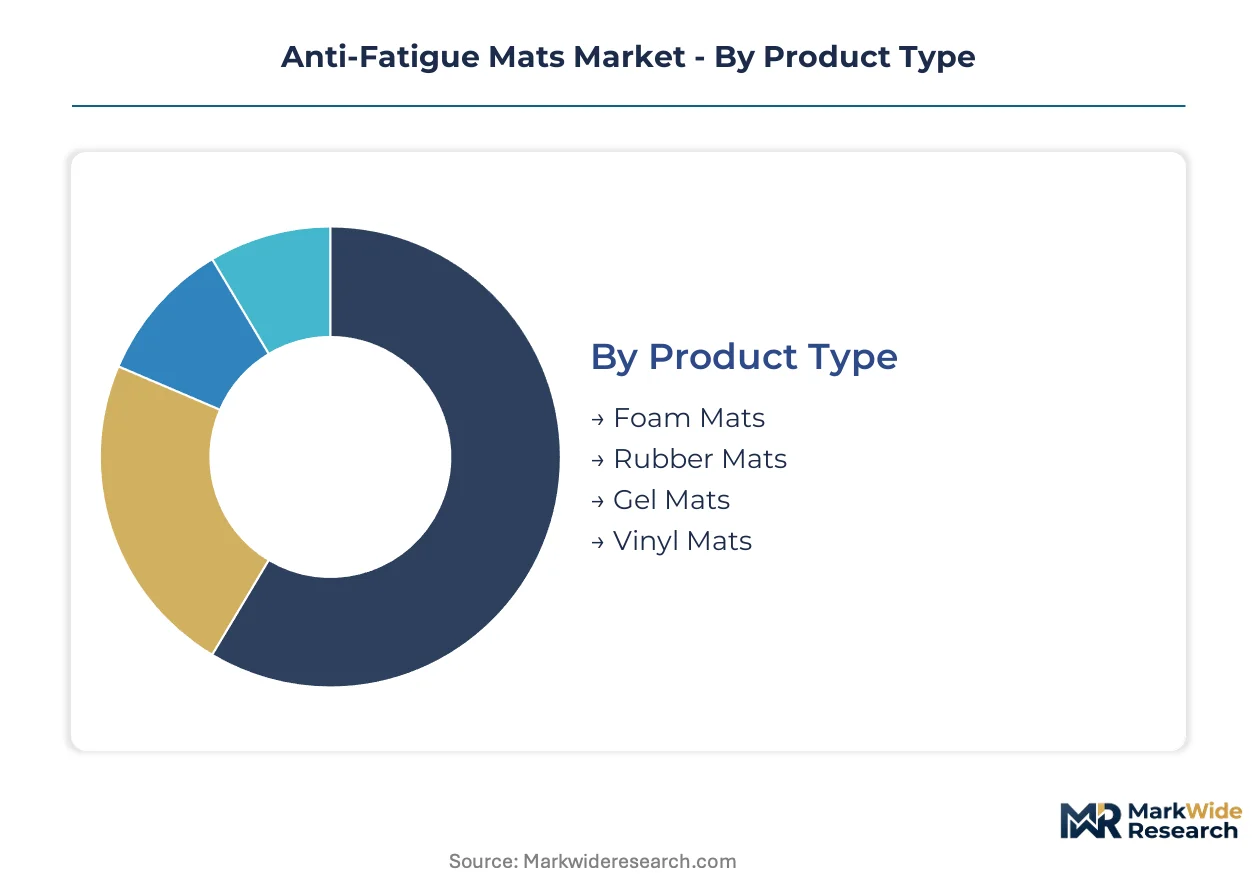
Segmentation reveals how procurement channels fragment across performance tiers and compliance requirements. Buyers route foam volumes through industrial distributors while gel and healthcare-grade specifications flow through specialized ergonomic dealers with certification support.
Product Type:
Channel mix splits sharply: foam and rubber move through broadline industrial distributors, while gel and vinyl specifications route through ergonomic specialists and healthcare-focused dealers with NSF and NFSI certification capabilities.
- Foam Mats:Constructed from closed-cell EVA or PVC composites with moderate compression resistance. Warehouse and logistics operators in the United States specify these for high-turnover picking stations where replacement cycles compress under OSHA standing-duration enforcement.
- Gel Mats:Layered viscoelastic cores with polyurethane encapsulation distribute pressure across standing surfaces. Healthcare facilities concentrate demand here for surgical suites and pharmacy workstations where joint stress reduction justifies premium unit economics and extended procurement timelines.
- Rubber Mats:Nitrile or SBR compounds deliver chemical resistance in heavy manufacturing environments. Industrial buyers prioritize durability thresholds over comfort metrics.
- Vinyl Mats:PVC substrates with welded construction suit wet-area commercial kitchens and food processing lines where grease-proof backing and heat resistance prove essential.
Foam Mats dominate installed base across warehouse and logistics footprints. Gel Mats is where expansion concentrates as healthcare procurement committees elevate ergonomic performance specifications.
Application:
Cost tier stratification separates commodity commercial deployments from engineered healthcare and industrial specifications with certified performance documentation.
- Commercial Use:Retail, hospitality, and corporate office environments specify beveled-edge mats with slip-resistant certification for ADA Title III compliance. Facility managers prioritize visual integration and logo-imprinting capabilities over maximum comfort performance.
- Healthcare Facilities:Hospital procurement committees mandate pressure-distribution testing and antimicrobial surface treatments for surgical suites, pharmacies, and diagnostic stations. These specifications carry the steepest unit economics and longest vendor qualification timelines.
- Industrial Use:Manufacturing plants and chemical processing facilities demand chemical-resistant rubber formulations with drainage channels and grease-proof backing.
- Home Use:Standing-desk adjacency and kitchen workstation applications drive consumer channel volumes through e-commerce platforms and office furniture retailers.
Commercial Use holds the broadest installed base across retail and hospitality retrofits. Healthcare Facilities is climbing the fastest as surgical ergonomics and staff retention priorities reshape procurement budgets.
Size:
Volume concentration tracks workstation standardization versus custom fabrication requirements across facility buildout and retrofit cycles.
- Large:Standard 2x3 foot and 3x5 foot dimensions capture warehouse workstation and commercial kitchen volumes where facility managers specify modular coverage for standing zones. United States distribution center buildouts drive repeat procurement of these standardized formats.
- Medium:2x2 foot and 20x36 inch formats suit individual workstations and reception desks where space constraints limit coverage area.
- Small:Compact formats target home office standing-desk adjacency and single-user kitchen applications.
- Extra Large:Custom linear footage and interlocking systems cover assembly lines and continuous production zones requiring seamless coverage.
Large formats dominate warehouse and logistics procurement volumes. Extra Large specifications are gaining share fastest in automated distribution centers with continuous pick paths.
Material:
Supply concentration and margin structure diverge sharply between petrochemical-dependent synthetics and specialized composite formulations.
- Polyurethane:Micro-cellular and energy-return formulations from German and Polish producers command premium placement in healthcare and automotive assembly applications. REACH compliance requirements on isocyanate exposure are forcing reformulation investments that compress mid-tier competitor margins.
- Foam:EVA and PVC closed-cell structures from southeastern China manufacturing clusters supply cost-efficient commercial and home use volumes with compressed margins and freight cost exposure.
- Rubber:Nitrile and SBR compounds retain stable industrial demand where chemical resistance thresholds override comfort prioritization.
- Fabric:Woven surface layers with foam or rubber substrates address aesthetic requirements in corporate reception and hospitality environments.
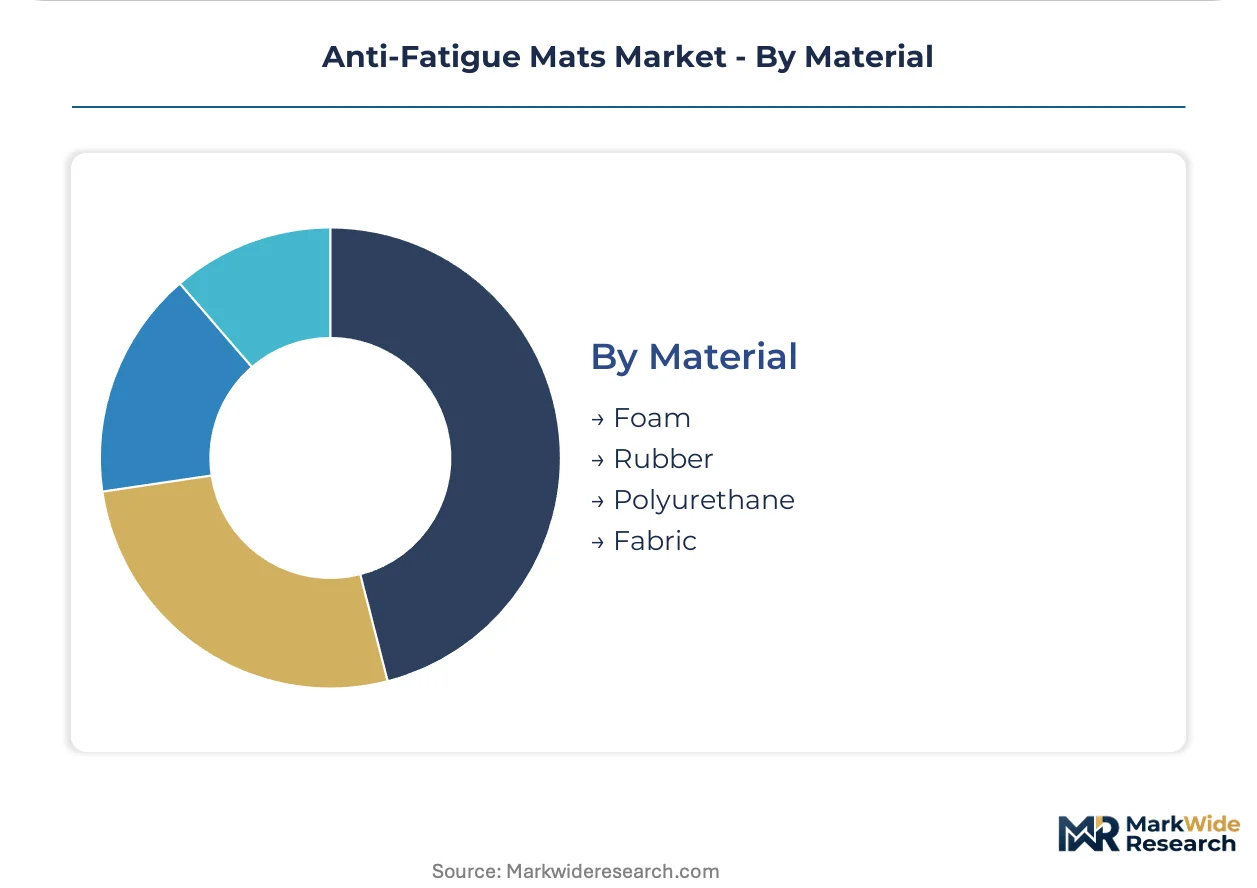
Foam holds the deepest installed base across commercial and home applications. Polyurethane is expanding most quickly as healthcare procurement elevates performance specifications over unit cost.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Warehouse and logistics operators concentrate procurement in the United States, while healthcare facilities drive expansion in Germany and Japan. Industrial manufacturing clusters in China and India are emerging as volume centers as workplace safety enforcement tightens across Asia-Pacific.
United States
Distribution center buildouts and e-commerce fulfillment expansion dominate procurement volumes. OSHA workplace safety enforcement around standing-duration limits compresses replacement cycles and elevates specification budgets. The Ohio River Valley logistics corridor and Texas distribution hubs are mandating gel-composite surfaces for high-velocity picking zones.
Germany
Automotive assembly plants and pharmaceutical manufacturing drive demand for pressure-mapping sensor integration. EU REACH restrictions on isocyanate exposure force reformulation of polyurethane production lines. The Stuttgart industrial region and Bavarian manufacturing belt are piloting connected matting systems with real-time ergonomic monitoring.
China
Foam mat manufacturing clusters in southeastern China supply global commercial volumes with compressed margins. GB standards for workplace ergonomics are tightening enforcement in state-owned enterprises. The Yangtze River Delta and Pearl River Delta logistics zones are retrofitting automated distribution centers with standardized workstation matting.
India
PLI scheme incentives for warehouse infrastructure create first-mover advantage for BIS-certified product lines. Domestic fulfillment center expansion outpaces ergonomic equipment penetration in Mumbai and Delhi-NCR. The Maharashtra and Gujarat industrial corridors are specifying modular mat coverage for continuous pick paths.
Japan
Third-party facility management providers displace direct manufacturer relationships in pharmaceutical manufacturing plants. METI guidelines for occupational health are elevating procurement specifications in Osaka and Tokyo industrial corridors. Corporate wellness programs in metropolitan financial services are driving standing-desk adjacency retrofits.
Anti-Fatigue Mats Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with matting as a specialty division alongside pure-play ergonomic specialists. The vendor base concentrates in three tiers: petrochemical-integrated formulators commanding healthcare premiums, regional fabricators serving commercial logistics, and facility management bundlers capturing multi-site service contracts. Strategic moves center on certification acquisition for NFSI and NSF compliance, plus backward integration into polyurethane resin production to hedge feedstock volatility.
Within the diversified industrial tier, 3M Corporation and Cintas Corporation exemplify scale-driven positioning through broad safety equipment portfolios. M+A Matting occupies a specialist position in healthcare-grade product lines. Smart Step Flooring anchors the commercial kitchen and retail segment where slip-resistant certification commands placement premiums. Euronics Industries Pvt Ltd represents India-based regional fabrication capacity serving price-sensitive logistics procurement.
| Leading Market Players |
|---|
| Smart Step Flooring |
| Cintas Corporation |
| NoTrax |
| M+A Matting |
| Euronics Industries Pvt Ltd |
| 3M Corporation |
| Durable Corporation |
| UniFirst Corporation |
| Wearwell, LLC |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements with polyurethane resin suppliers lock in both feedstock access and price visibility for tier-one mat manufacturers serving OSHA-mandated warehouse deployments. These contracts typically index to crude oil derivatives, transferring petrochemical volatility risk downstream while securing volume commitments from southeastern China foam clusters.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate procurement between foam manufacturers and logistics operators. Three-tier pricing structure across premium gel, standard polyurethane, and economy foam levels separates healthcare certification tiers from commodity commercial grades. Pricing pressure stems from feedstock volatility compressing mid-tier margins, while hospital procurement committees show least price sensitivity due to joint-stress performance mandates.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane elevate inbound logistics costs for North American distributors sourcing from Guangdong and Zhejiang manufacturing clusters. Raw material dependencies center on MDI isocyanates, polyether polyols, and synthetic rubber feedstocks. Tariff exposure on Chinese foam imports creates structural risk, while distribution runs through industrial distributors for commercial volumes and ergonomic specialists for healthcare-grade specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected matting platforms with IoT sensor integration are creating platform-economics inflection, as German automotive plants pilot real-time ergonomic monitoring systems that interoperability requirements will standardize across occupational health departments.
For Market Incumbents: Secure NFSI certification backlog capacity before testing laboratory queues extend further. Invest in closed-mold injection systems to maintain CE marking compliance under EU REACH isocyanate restrictions. Backward integration into polyurethane resin production hedges feedstock volatility threatening mid-tier competitors. For New Entrants and Emerging Players: Lead with BIS-certified product lines into India's PLI-subsidized warehouse buildout, where domestic fulfillment center expansion outpaces ergonomic equipment penetration. Target modular interlocking systems for continuous pick paths in Maharashtra and Gujarat industrial corridors. Position through facility management bundlers displacing direct manufacturer relationships. For Investors and Strategic Acquirers: Capital is best deployed toward sensor-integrated matting specialists with pilot deployments in German automotive plants. Long-term viability hinges on convergence of pressure-mapping technology with corporate wellness program budgets. Watch standing-desk adjacency penetration rates in United Kingdom financial services as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Enables real-time ergonomic monitoring for OSHA compliance in German automotive plants. |
| Backward Integration | Captive polyurethane resin supply hedges petrochemical volatility for healthcare-grade lines. |
| Certification Acceleration | Fast-tracks NFSI slip-resistance validation to bypass testing laboratory backlogs. |
| Geographic Manufacturing Footprint | BIS-certified India production captures PLI-subsidized warehouse infrastructure buildout. |
| Platform Integration | Bundles matting with scheduled deep-cleaning services through third-party facility managers. |
Research Approach
A spread of perspectives from warehouse safety managers, hospital procurement committees, polyurethane formulation chemists, and industrial distribution channel heads converged on the working assumptions. Primary interviews combined with secondary validation from OSHA enforcement records, NFSI certification databases, customs trade data, and SEC filings from diversified industrial conglomerates. Bottom-up facility deployment estimates triangulated against top-down petrochemical feedstock demand models.
Segmentation dimensions modeled include product type, application vertical, material composition, and geographic regulatory cluster across the projection horizon. CAGRs derived from facility buildout pipelines, replacement cycle compression under standing-duration enforcement, and healthcare procurement committee budget trajectories. Industry-specific inputs incorporate polyurethane formulation cost curves and BIS certification timeline data.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement intensity or petrochemical price stability would require recalibration. Forecasts reflect documented assumptions around warehouse automation expansion rates and healthcare ergonomic specification elevation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Mask Particulate Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Law Enforcement and Military Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market