
 Global Collision Avoidance System Market | 2026-2036
Global Collision Avoidance System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Collision Avoidance System Market Intelligence
The bundling of discrete safety functions into integrated ADAS packages by automakers is realigning buyer choice in the collision avoidance system market. Robert Bosch GmbH leverages its extensive portfolio to offer comprehensive sensor and software solutions to major OEMs. Mobileye Global Inc. specializes in vision-based systems, establishing a strong position in camera processing technology. Continental AG competes through its development of a wide range of radar, LiDAR, and camera technologies for diverse vehicle platforms.
A collision avoidance system is an automotive safety technology designed to prevent or reduce the severity of accidents. These systems utilize sensors such as LiDAR, radar, or cameras to detect potential collisions with other vehicles, pedestrians, or obstacles, triggering alerts or autonomous actions like emergency braking. Their primary purpose is to enhance vehicle and road user safety. Camera-based systems are foundational in the passenger car segment, while LiDAR technology is gaining traction for advanced automation. The commercial trucks segment represents the fastest-growing vehicle type, driven by fleet operator demand for enhanced safety and operational efficiency.
Regulations from bodies like the United States' NHTSA and the United Nations Economic Commission for Europe (UNECE) mandate features such as Autonomous Emergency Braking. These safety standards directly compel OEM integration of collision avoidance systems into new vehicle models to achieve high safety ratings and ensure market access. The critical decision for suppliers involves balancing investment between maturing radar technologies and next-generation solid-state LiDAR to secure future OEM design wins.
Market Dynamics
The convergence of stringent safety regulations from government bodies and commercial fleet operator demand for enhanced operational uptime is the central force shaping the collision avoidance system market. This dual pressure accelerates the transition from optional features to standard equipment across vehicle classes.
Growth Catalysts
- Regulatory Mandates:Directives from bodies like the UNECE requiring Autonomous Emergency Braking (AEB) in new vehicle types compel OEM integration, creating a foundational, non-discretionary demand for collision avoidance systems to achieve market access and safety ratings.
- Commercial Fleet Demand:Fleet operators in the commercial truck segment are actively adopting these systems to reduce accident-related costs, lower insurance premiums, and maximize vehicle uptime, creating strong demand independent of passenger car cycles.
- Intelligent Vehicle Initiatives:National industrial strategies, particularly within China's automotive sector, promote the development and integration of intelligent and connected vehicle technologies, establishing a large-scale testbed and market for advanced ADAS.
Market Restraints
- High System Cost:The significant cost of advanced sensors, particularly LiDAR, remains a barrier to widespread adoption in economy and mid-range passenger vehicles, limiting market penetration to premium segments or optional packages.
- Performance in Adverse Conditions:The reliability of sensor systems, including cameras and LiDAR, can be compromised by environmental factors such as heavy rain, snow, fog, or direct sun glare, creating performance inconsistencies that hinder full autonomy.
- System Integration Complexity:Integrating data from multiple sensor types (radar, camera, LiDAR) and ensuring flawless software interoperability presents a significant engineering and validation challenge for OEMs and Tier 1 suppliers.
Strategic Opportunities
- Aftermarket Fleet Solutions:The large existing parc of commercial vehicles in regions like Latin America and Southeast Asia presents an opportunity for aftermarket retrofit solutions, enabling fleet owners to upgrade safety capabilities without purchasing new trucks.
- Non-Automotive Applications:Technology developed for automotive collision avoidance is transferable to adjacent industries such as mining, agriculture, and logistics for use in autonomous haulage trucks, tractors, and warehouse robotics.
- V2X Communication:The development of Vehicle-to-Everything (V2X) communication standards creates an opportunity for systems that receive data from infrastructure and other vehicles, enabling predictive and cooperative collision avoidance beyond line-of-sight sensing.
Industry Challenges
- Data Standardization:A lack of global standards for sensor output formats and software communication protocols complicates component sourcing for OEMs, increases integration costs, and slows down development cycles across the industry.
- Talent Scarcity:A persistent shortage of software engineers and data scientists with specialized expertise in sensor fusion, artificial intelligence, and machine learning algorithms constrains the development capacity of suppliers and automakers.
- Validation and Certification Burden:The immense amount of real-world and simulated testing required to validate the safety and reliability of collision avoidance systems for regulatory bodies like the KBA in Germany is time-consuming and capital-intensive.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Collision Avoidance System Market |
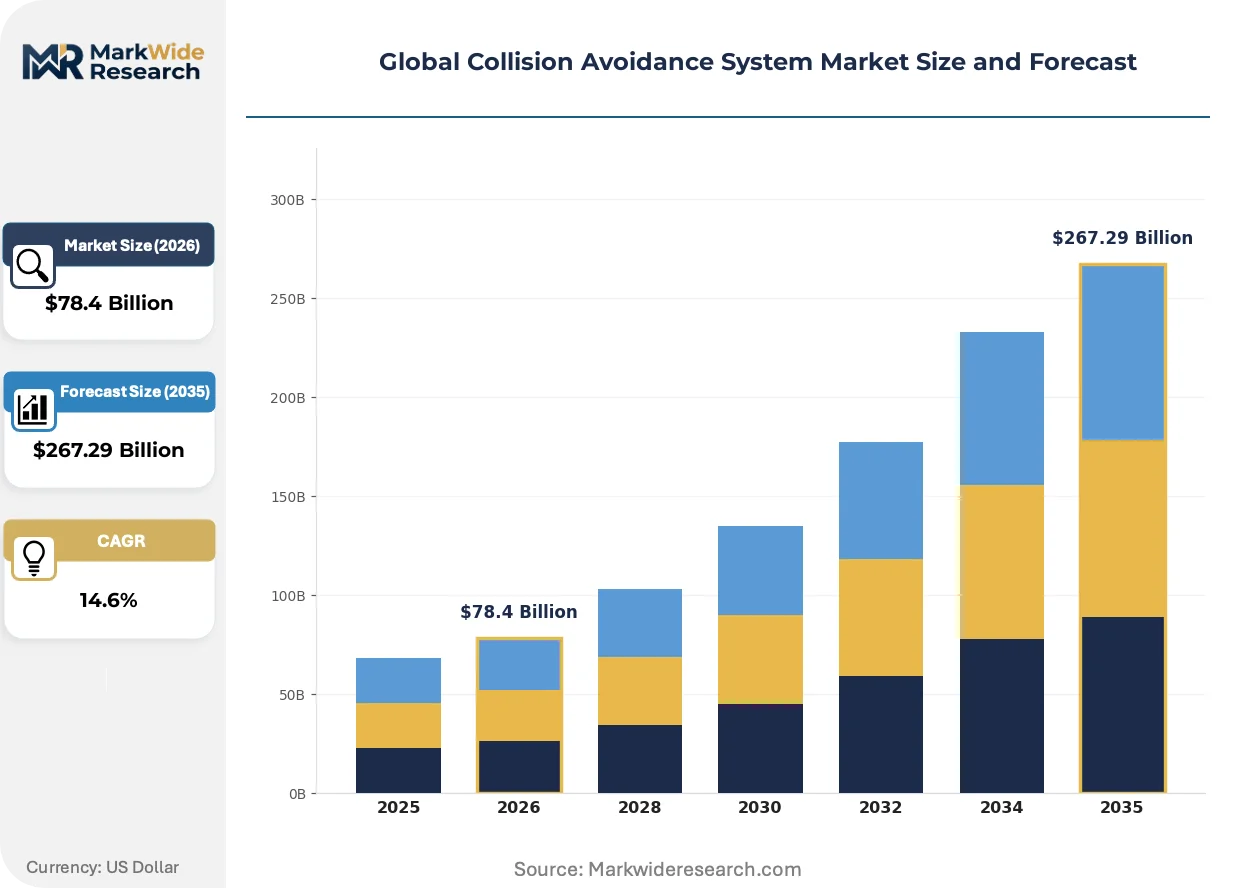
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $267.29 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Commercial Trucks, Buses, Motorcycles Technology: LiDAR, Radar, Camera-Based Systems, Ultrasonic Sensors End User: OEMs, Aftermarket Providers, Fleet Operators, Government Agencies Application: Parking Assistance, Lane Departure Warning, Adaptive Cruise Control, Emergency Braking |
| Companies Covered | Denso Corporation, Aptiv Plc, ZF Friedrichshafen AG, Honeywell International Inc., Autoliv Inc., Robert Bosch GmbH, Continental AG, Magna International Inc., Mobileye Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Collision Avoidance System Market Strategic Shifts & Innovations
Software-defined functionality is transforming collision avoidance systems from fixed-function hardware into upgradable platforms. This shift prioritizes sensor fusion algorithms and over-the-air update capabilities, allowing for continuous improvement in safety performance throughout a vehicle's lifecycle.
Solid-state LiDAR technology provides high-resolution, three-dimensional environmental mapping without mechanical moving parts, increasing system durability. Automakers in the premium vehicle segment are adopting this technology for advanced automated driving functions. The technology is expanding into the commercial truck segment, where its long-range detection capabilities enhance safety for high-speed highway operation.
China's Ministry of Industry and Information Technology (MIIT) continues to advance its "Intelligent Connected Vehicle (ICV)" standards framework. This policy compels automakers operating in the country to incorporate progressively sophisticated ADAS features to meet market regulations. The passenger car segment is most directly impacted, forcing OEMs to accelerate the deployment of advanced camera and radar systems to comply with the new domestic technical requirements.
A notable behavioral shift is occurring as commercial fleet operators demand customizable, data-centric safety packages rather than accepting standard OEM configurations. This disrupts the traditional sales model, favoring suppliers who provide telematics integration and post-deployment software updates. This trend is most prominent in North America and Europe, where large logistics firms leverage safety data for driver coaching and insurance negotiations.
Global Collision Avoidance System Market Segmentation
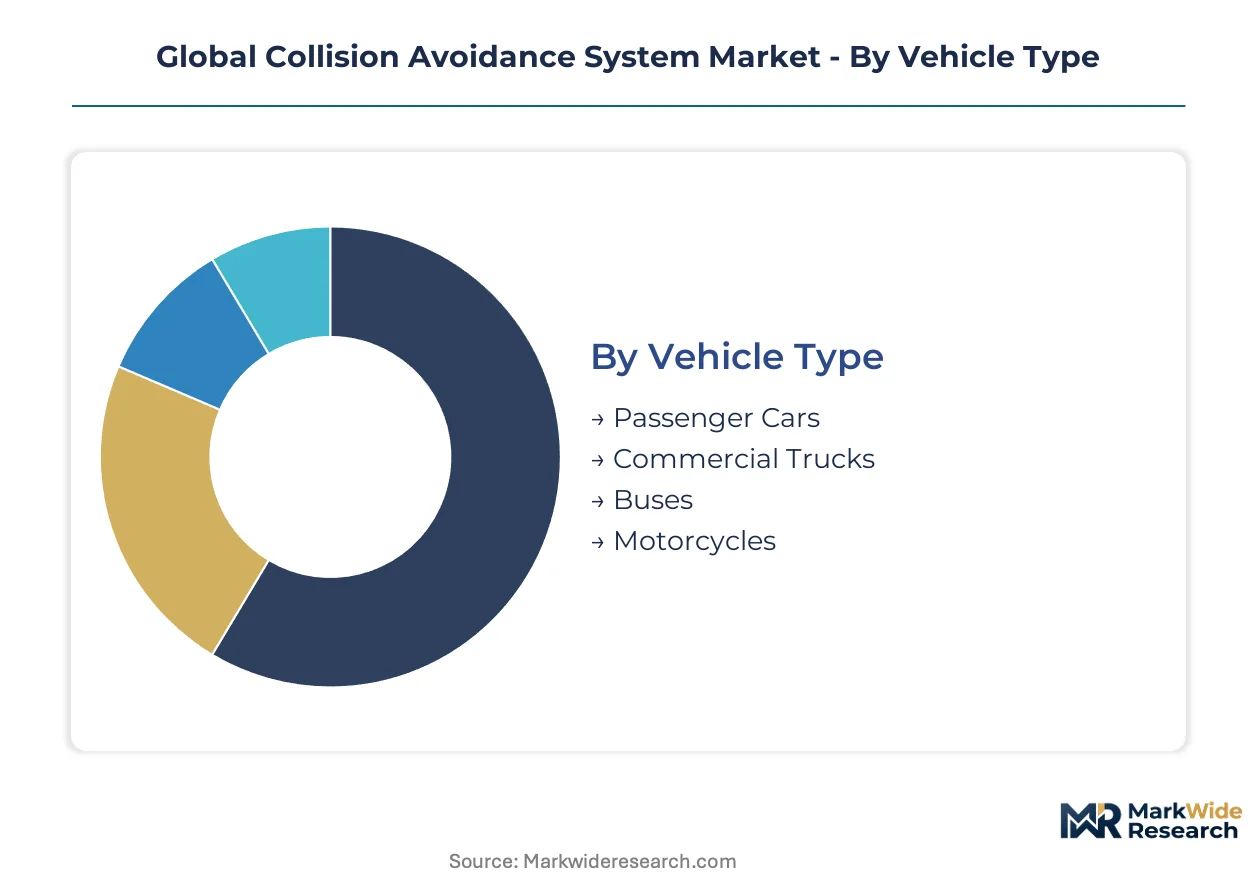
Understanding the collision avoidance system market through segmentation provides clarity on diverse technological adoption, end-user priorities, and application-specific demands. This granular view highlights where innovation and investment are concentrating across the automotive safety landscape.
Vehicle Type:
The vehicle type segmentation highlights the differing demands for collision avoidance systems, ranging from highly standardized features in mass-market passenger cars to more customized solutions for specialized commercial applications.
- Commercial Trucks:These vehicles integrate advanced collision avoidance systems to reduce accident-related costs, lower insurance premiums, and maximize operational uptime for fleet operators. Their demand for enhanced safety often incorporates LiDAR technology for long-range detection, especially in high-speed highway operations.
- Passenger Cars:This segment represents the foundational market for collision avoidance systems, driven by stringent regulatory mandates from bodies like the NHTSA and UNECE. Camera-based systems are prevalent, providing essential features such as Autonomous Emergency Braking to achieve high safety ratings.
- Buses:Collision avoidance systems in buses prioritize public transport safety in urban and intercity environments, often focusing on pedestrian and cyclist detection to mitigate accidents.
- Motorcycles:This segment presents unique challenges for collision avoidance, requiring compact and lightweight sensor solutions to enhance rider safety without compromising vehicle dynamics.
Leading the category by volume: Passenger Cars. Growing fastest: Commercial Trucks.
Technology:
Technology choices for collision avoidance systems reflect a spectrum of maturity and cost, influencing their deployment across various vehicle segments and functional requirements.
- Camera-Based Systems:These systems utilize optical sensors for object detection, lane keeping, and traffic sign recognition, forming the backbone of many entry-level and mid-range ADAS packages due to their cost-effectiveness. Mobileye Global Inc. specializes in vision-based processing, establishing a strong position in this segment.
- LiDAR:This technology provides high-resolution, three-dimensional environmental mapping without mechanical moving parts in solid-state configurations, increasingly adopted in premium vehicles for advanced automated driving functions. Its long-range detection capabilities are expanding into the commercial truck segment.
- Radar:Radar technology offers robust all-weather performance for distance measurement and speed detection, making it a reliable component in Adaptive Cruise Control and blind-spot monitoring systems. Continental AG develops a wide range of radar technologies for diverse vehicle platforms.
- Ultrasonic Sensors:These short-range sensors are primarily used for parking assistance and low-speed obstacle detection, providing cost-effective proximity sensing in congested environments.
Volume is dominated by Camera-Based Systems, while LiDAR technology drives technological advancement.
End User:
The end-user segmentation reveals distinct procurement patterns for collision avoidance systems, driven by varying operational needs and regulatory compliance requirements.
- OEMs:Original Equipment Manufacturers integrate collision avoidance systems directly into new vehicle models, driven by regulatory mandates and consumer demand for safety features. Robert Bosch GmbH supplies comprehensive sensor and software solutions to major OEMs.
- Fleet Operators:Commercial fleet operators actively adopt these systems to reduce accident-related costs, lower insurance premiums, and maximize vehicle uptime, prioritizing data-centric safety packages for driver coaching. This demand is prominent in North America and Europe.
- Aftermarket Providers:These providers offer retrofit solutions for existing vehicle fleets, particularly in regions like Latin America and Southeast Asia, enabling owners to upgrade safety capabilities without purchasing new trucks.
- Government Agencies:Government entities procure collision avoidance systems for their specialized vehicle fleets, focusing on public safety and adherence to high operational standards.
Demand for new vehicle integration primarily originates from OEMs, whereas Fleet Operators shape ongoing operational safety requirements.
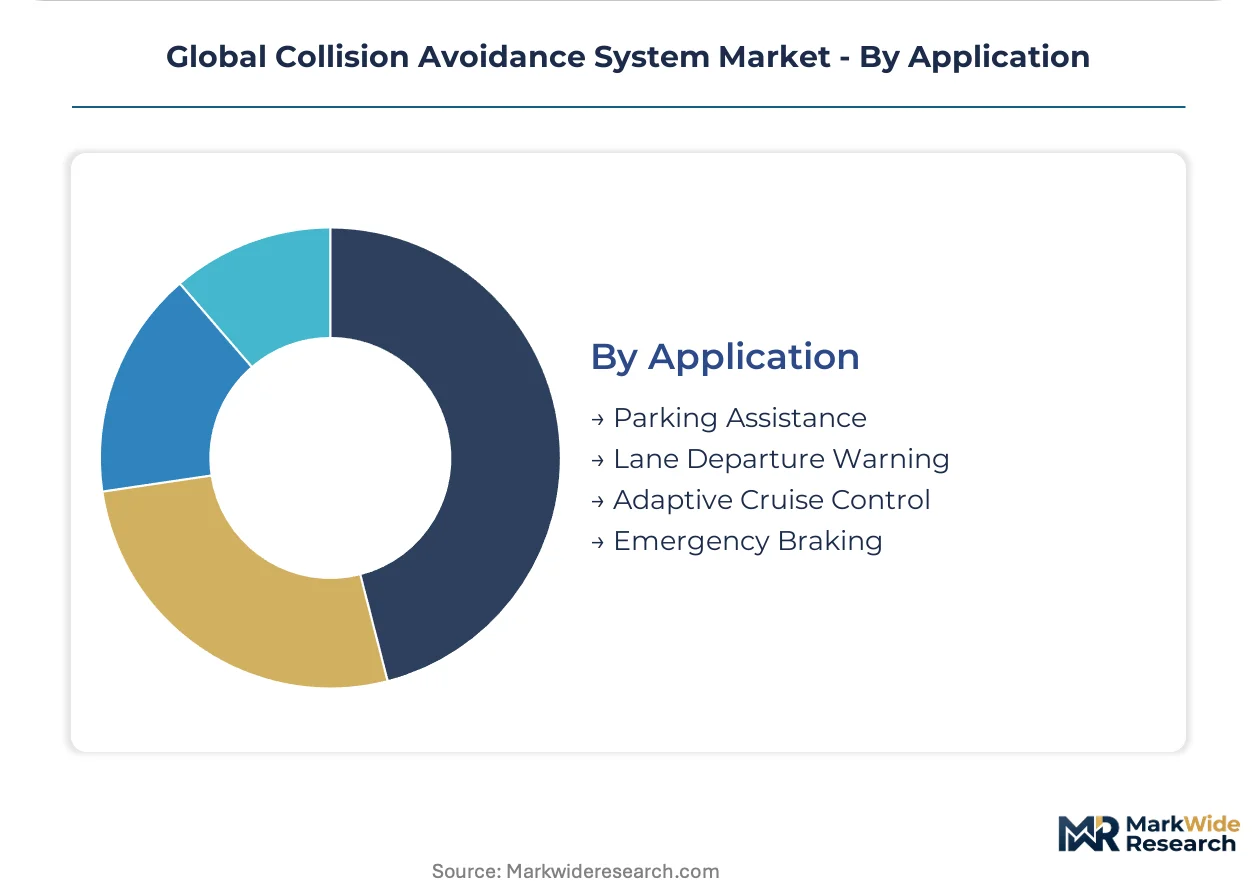
Application:
Applications for collision avoidance systems span a range of functional complexities, from basic driver aids to advanced autonomous interventions that enhance vehicle safety.
- Emergency Braking:This critical safety application autonomously applies brakes to prevent or mitigate collisions when a driver fails to react, often mandated by regulations from bodies like the UNECE. These systems utilize radar and camera sensors to detect obstacles.
- Lane Departure Warning:These systems alert drivers when their vehicle drifts out of its lane without an intentional signal, enhancing road safety and preventing accidents caused by distraction or fatigue. Camera-based systems are foundational for this application.
- Adaptive Cruise Control:This application automatically adjusts vehicle speed to maintain a safe following distance from the vehicle ahead, improving driver comfort and reducing collision risks in traffic. Radar technology plays a central role in distance sensing.
- Parking Assistance:This application aids drivers in maneuvering into parking spaces by detecting nearby obstacles and providing alerts, often relying on ultrasonic sensors for close-range detection.
Core safety regulations prioritize Emergency Braking, while Parking Assistance enhances driver convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global collision avoidance system market exhibits a distinct geographic split between manufacturing hubs and high-demand consumption regions. China's expansive automotive base and intelligent vehicle push drive both production and adoption. Meanwhile, advanced safety mandates in the United States and Europe shape demand for sophisticated systems.
China
Demand for advanced ADAS features originates from China's national industrial strategies. The Ministry of Industry and Information Technology (MIIT) promotes Intelligent Connected Vehicle (ICV) standards, compelling OEM integration. Major automotive manufacturing centers like the Yangtze River Delta are testbeds for these advanced technologies.
United States
Commercial fleet operators in the United States prioritize collision avoidance systems to enhance operational uptime. The National Highway Traffic Safety Administration (NHTSA) mandates specific safety features, compelling OEM adoption. Automotive clusters in Michigan and California drive innovation in sensor and software development.
Germany
Stringent safety regulations from the United Nations Economic Commission for Europe (UNECE) compel collision avoidance system integration in Germany. The KBA (Federal Motor Transport Authority) validates system safety and reliability for market access. Major automotive engineering centers in Bavaria and Baden-Württemberg focus on radar and LiDAR advancements.
Japan
Japan's automotive industry focuses on integrating advanced safety features into new vehicle models. The Ministry of Economy, Trade and Industry (METI) supports research into autonomous driving technologies. Tokyo and Nagoya serve as key hubs for sensor manufacturing and software development for collision avoidance.
India
Commercial vehicle fleet expansion in India creates demand for cost-effective collision avoidance solutions. The Bureau of Indian Standards (BIS) is developing safety norms for automotive electronics. Automotive production clusters in Chennai and Pune are exploring local manufacturing of these systems.
Global Collision Avoidance System Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists to capture market share in collision avoidance systems. The market exhibits a tiered structure, with established Tier 1 suppliers dominating OEM integration and niche players innovating in specific sensor technologies. Strategic partnerships between hardware manufacturers and software developers are common to integrate complex systems. Companies frequently expand their portfolios through technology licensing and targeted acquisitions to offer comprehensive solutions across vehicle types.
Within the established Tier 1 supplier segment, German-based Robert Bosch GmbH exemplifies a comprehensive sensor and software solutions provider, leveraging its extensive portfolio for major OEMs. Continental AG, also a German conglomerate, represents a broad developer of radar, LiDAR, and camera technologies for diverse vehicle platforms. Mobileye Global Inc., conversely, anchors the pure-play vision-based systems segment, focusing on advanced camera processing technology and establishing a strong position in camera-based ADAS. These companies illustrate the diverse approaches to market leadership, from broad integration to specialized technological focus.
| Leading Market Players |
|---|
| Denso Corporation |
| Aptiv Plc |
| ZF Friedrichshafen AG |
| Honeywell International Inc. |
| Autoliv Inc. |
| Robert Bosch GmbH |
| Continental AG |
| Magna International Inc. |
| Mobileye Global Inc. |
| Others |
Cost & Logistics Intelligence
Stringent regulatory mandates from the NHTSA and UNECE compel OEMs to integrate collision avoidance systems, which in turn drives suppliers to innovate and manage component costs to meet market pricing expectations.
Pricing Analysis
Cost-down pressure on camera-based systems accelerates because OEMs seek to standardize ADAS features across mid-range vehicle segments. The dominant pricing structure is tiered, reflecting the complexity and performance of the systems. Price differentiation stems from sensor resolution and reliability, alongside bundled after-sales software update services. Passenger car OEMs in the economy segment exhibit the highest price sensitivity, while premium vehicle manufacturers prioritize advanced LiDAR capabilities.
Supply Chain Analysis
China's MIIT Intelligent Connected Vehicle standards, promoting local content, are reshaping sourcing strategies for collision avoidance system components. Geographic supply concentrates in China for manufacturing, Germany for advanced R&D, and Japan for specialized sensor production. The industry relies heavily on semiconductors and precision optical components. Single-source vulnerability for critical sensor chips poses a structural risk. Distribution runs through direct sales channels to OEMs and specialized aftermarket providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The collision avoidance system market is navigating a technology-transition phase, where solid-state LiDAR technology is gradually replacing older mechanical scanning solutions for advanced applications. This shift demands strategic adjustments across the value chain.
For Market Incumbents: Deploy strategic partnerships to integrate cutting-edge software with established hardware platforms, countering the threat from pure-play vision system specialists. Invest in next-generation solid-state LiDAR R&D to maintain a technological edge against emerging sensor technologies. Focus on comprehensive system validation and certification to meet evolving regulatory demands from bodies like the KBA. This approach mitigates margin pressure from increasingly standardized camera-based solutions.
For New Entrants and Emerging Players: The significant price-point gap between premium LiDAR-based systems and economy camera-based solutions offers an opportunity for new entrants. Target the aftermarket commercial truck segment in regions like Southeast Asia with cost-effective retrofit solutions. Focus on non-automotive applications such as autonomous haulage in mining, offering specialized sensor packages. A go-to-market angle emphasizing rapid deployment and telematics integration can capture immediate demand.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized sensor fusion software developers given the increasing complexity of integrating diverse sensor data. The market exhibits long-term viability, driven by sustained regulatory mandates and consumer demand for enhanced vehicle safety over the next decade. Acquisition targets include innovative solid-state LiDAR startups and AI-driven perception software firms. OEM design wins for next-generation sensor technologies serve as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Development | This enables continuous system improvements and feature upgrades throughout a vehicle's lifecycle. |
| Solid-State LiDAR Investment | This provides high-resolution 3D mapping capabilities for advanced automated driving functions. |
| Aftermarket Retrofit Expansion | This extends safety benefits to existing commercial fleets in regions like Latin America. |
| V2X Communication Integration | This allows predictive collision avoidance by leveraging data from infrastructure and other vehicles. |
| Talent Acquisition in AI/ML | This addresses the scarcity of specialized engineers required for advanced sensor fusion algorithms. |
Research Approach
Multi-period observation of vehicle production volumes and regulatory compliance rates anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary interviews included OEM platform engineers, Tier 1 procurement managers, and fleet operations directors. Secondary validation utilized NHTSA safety ratings, UNECE regulatory documents, and automotive production databases, ensuring robust bottom-up and top-down triangulation.
An input-output matrix provided the foundational structure for modeling market dynamics and projecting future growth across the analysis window. The model segmented by vehicle type, technology, end-user, application, and regulatory compliance level. Compound annual growth rates derived from historical adoption trends and projected OEM integration rates. Key forecast inputs included new vehicle model launches and evolving ADAS feature mandates.
Inputs from publicly available regulatory reports and company disclosures were available through the study window; gaps in real-time OEM production data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory enforcement pace and sensor cost reduction. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium High Security Doors Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Cones Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market