
 Blast Monitoring Equipment Market | 2026-2036
Blast Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Blast Monitoring Equipment Market Analytics
OSMRE ground vibration standards is consolidating the competitive landscape around vendors with certified calibration networks and in-house sensor production. Orica Limited leverages its integrated explosives-to-monitoring workflow to anchor large mining contracts across North America. Instantel Inc. competes through specialized seismograph hardware that dominates tunneling and quarry applications in Canada. Campbell Scientific Inc. sustains a diversified instrumentation portfolio that extends beyond blast monitoring into structural and environmental sensing.
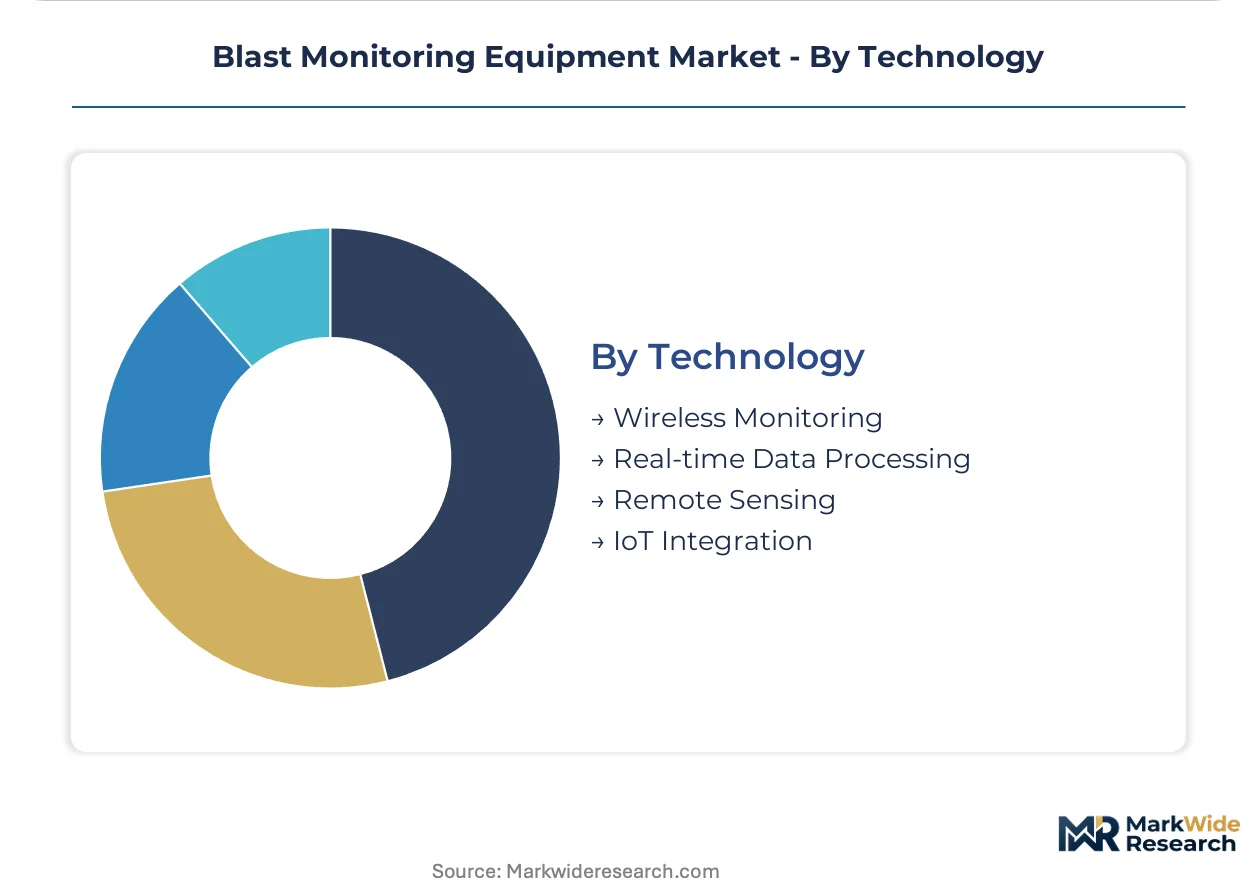
Blast monitoring equipment comprises sensors, data acquisition systems, and analytical software engineered to measure peak particle velocity, air overpressure, and frequency content from explosive detonations, typically sampling at rates exceeding 1,024 samples per second to capture transient waveforms. These systems protect nearby structures, ensure regulatory compliance, and optimize fragmentation outcomes in surface and underground operations. Seismic sensors occupy the largest product segment due to universal regulatory mandates for ground vibration measurement, while monitoring software represents the fastest-expanding category as mines shift toward cloud-based analytics and automated threshold alerting. Wireless monitoring technology leads the technology dimension by eliminating cabling hazards in active blast zones and enabling real-time data transmission from remote benches.
The US EPA coordinates with OSHA on fugitive dust and noise exposure limits that intersect with blast monitoring protocols, while the EU F-Gas Regulation indirectly pressures quarries to minimize repeated blasting through tighter environmental controls. In China, MEE enforcement of ambient vibration standards for urban-adjacent construction is creating new compliance obligations for equipment suppliers. Stakeholders must weigh certification breadth against sensor specialization when allocating R&D budgets across fragmented national standards.
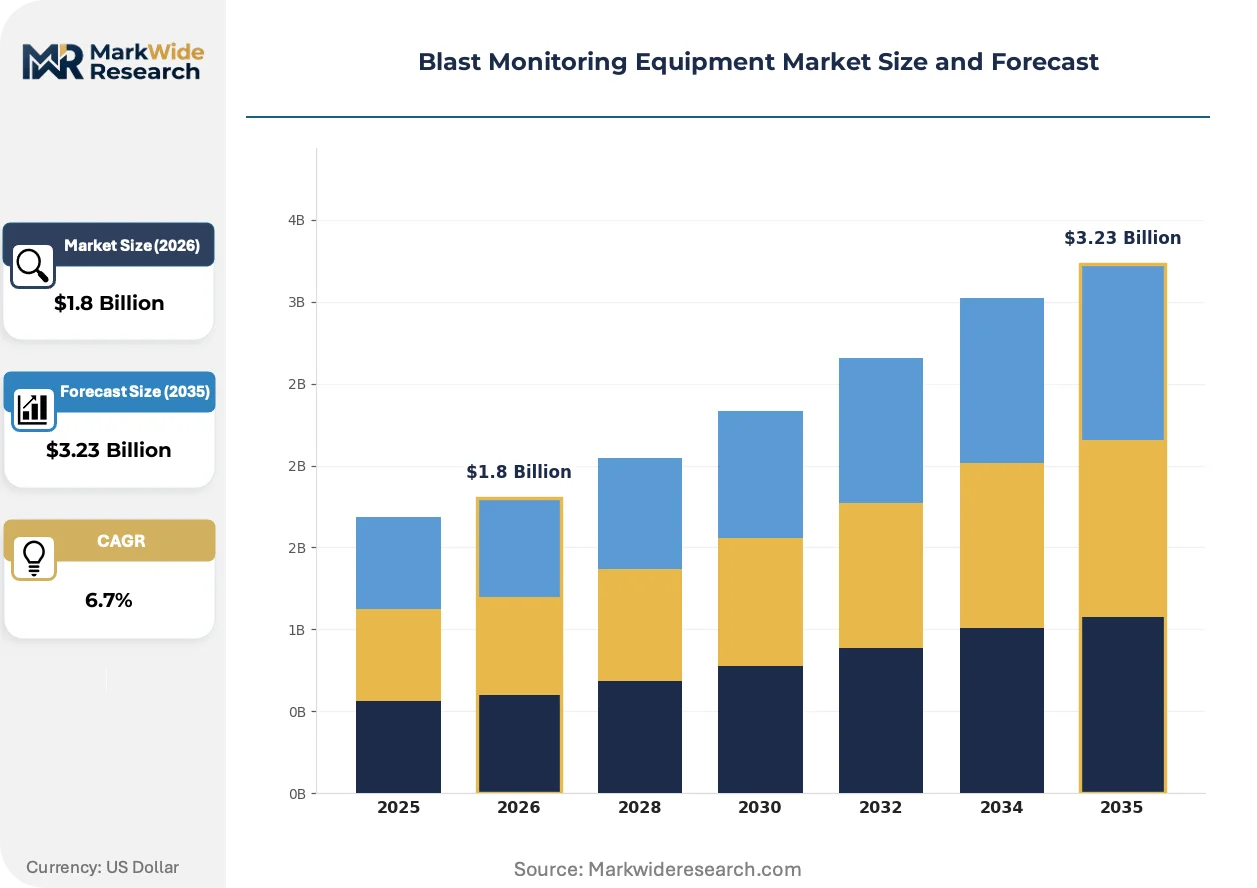
Market Dynamics
Wireless sensor networks are compressing deployment cycles in active blast zones, eliminating cabling hazards while forcing incumbent vendors to absorb cloud infrastructure costs or cede contracts to software-native competitors.
Growth Catalysts
- OSMRE vibration mandates:US surface mining operations must upgrade legacy seismograph fleets to meet tightened ground motion limits, creating replacement demand for calibrated sensor arrays.
- Pit-wall stability monitoring:Australian iron ore producers in Western Australia's Pilbara region are deploying wireless geophone networks to detect wall movement precursors before catastrophic failures.
- Cloud analytics platforms:Mining operators are migrating from on-premise blast analysis software to subscription-based threshold alerting systems that integrate with mine planning software.
Market Restraints
- MEMS sensor supply concentration:High-precision accelerometer production concentrates among a handful of Japanese and German component suppliers, exposing equipment makers to allocation risk during semiconductor shortages.
- Calibration labor intensity:Regulatory bodies in Canada and Australia require traceable calibration certificates that demand specialized technicians, limiting vendor scaling speed.
- Optical fiber sensing substitution:Distributed acoustic sensing cables are displacing point-source geophones in tunneling applications where linear coverage matters more than point precision.
Strategic Opportunities
- Urban construction compliance:China's MEE enforcement of ambient vibration standards for metro-adjacent building projects is creating first-time demand among civil contractors previously exempt from blast monitoring.
- Drone-mounted overpressure sensors:UAV platforms carrying transient pressure transducers are enabling aerial blast cloud mapping that ground-based sensors cannot capture.
- EU F-Gas Regulation:Quarries facing tighter environmental controls are reducing blast frequency and investing in higher-fidelity monitoring to maximize fragmentation efficiency per detonation event.
Industry Challenges
- Seismologist talent scarcity:Vendors struggle to hire waveform analysts capable of distinguishing blast-induced vibrations from natural seismic events, slowing technical support scaling.
- Legacy system integration:Mines running decades-old data loggers face firmware incompatibility when connecting to modern cloud dashboards, requiring costly middleware development.
- Multi-jurisdiction certification:Equipment must simultaneously satisfy OSHA electrical safety, FCC wireless emissions, and country-specific metrology standards, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blast Monitoring Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seismic Sensors, Pressure Sensors, Data Loggers, Monitoring Software Application: Mining Operations, Construction Sites, Quarry Management, Earthquake Studies End User: Mining Companies, Construction Firms, Research Institutions, Government Agencies Technology: Wireless Monitoring, Real-time Data Processing, Remote Sensing, IoT Integration |
| Companies Covered | Instantel Inc., Orica Limited, Dyno Nobel Inc., Campbell Scientific Inc., GeoSonics/Vibra-Tech Inc., Hexagon AB, Acoem, Applied Seismology Consultants, Texcel Technology Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blast Monitoring Equipment Market Evolving Landscape
Edge computing architectures are migrating blast waveform processing from central servers to sensor nodes, reducing latency for real-time threshold violations while compressing data transmission costs in bandwidth-constrained pit environments.
Machine learning classification algorithms trained on historical blast signatures are automating the distinction between controlled detonation vibrations and unintended ground instability events, reducing false-positive alerts that previously triggered costly production halts. Canadian underground hard-rock mines are deploying these systems at scale, with pit operations in Nevada and Western Australia piloting integration with autonomous drill fleets to enable dynamic blast pattern adjustment.
REACH chemical restrictions on explosive formulations are forcing quarries across Germany and France to adopt lower-velocity blasting agents that produce more complex frequency signatures, requiring seismograph vendors to expand their calibration libraries. Equipment suppliers are responding with modular sensor heads that swap filtering profiles rather than replacing entire hardware units.
Buyers are unbundling hardware procurement from software subscriptions, with Australian mining houses negotiating direct sensor purchases while sourcing analytics dashboards through separate SaaS agreements. This bifurcation is compressing hardware margins while elevating recurring revenue streams for cloud-native monitoring platforms, most visibly in Western Australia's iron ore district where major operators now specify API-first architectures in tender documents.
Blast Monitoring Equipment Market Segmentation
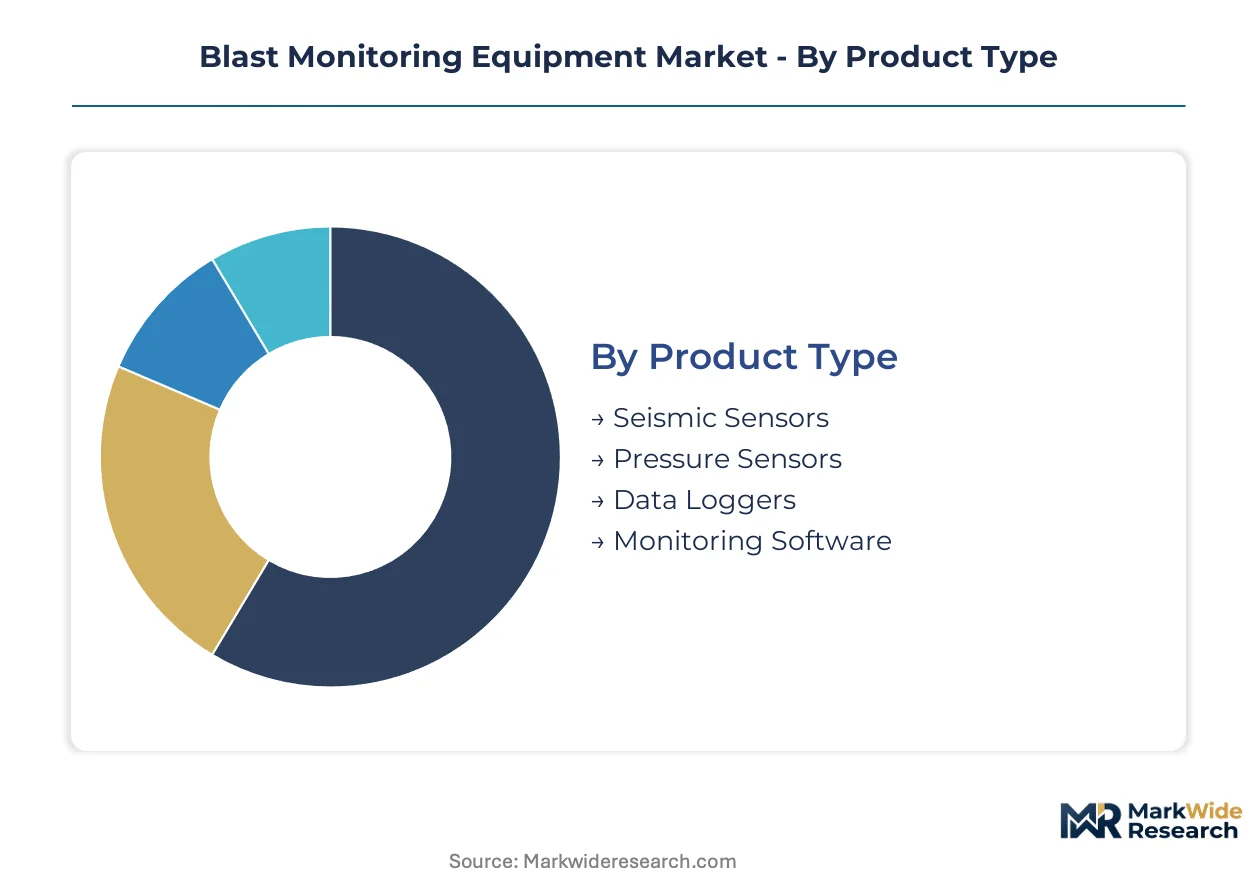
Blast monitoring equipment vendors configure product portfolios across four distinct segmentation axes. Each dimension reflects divergent buyer priorities: regulatory compliance mandates, operational environment constraints, technical integration requirements, and procurement budget cycles.
Product Type:
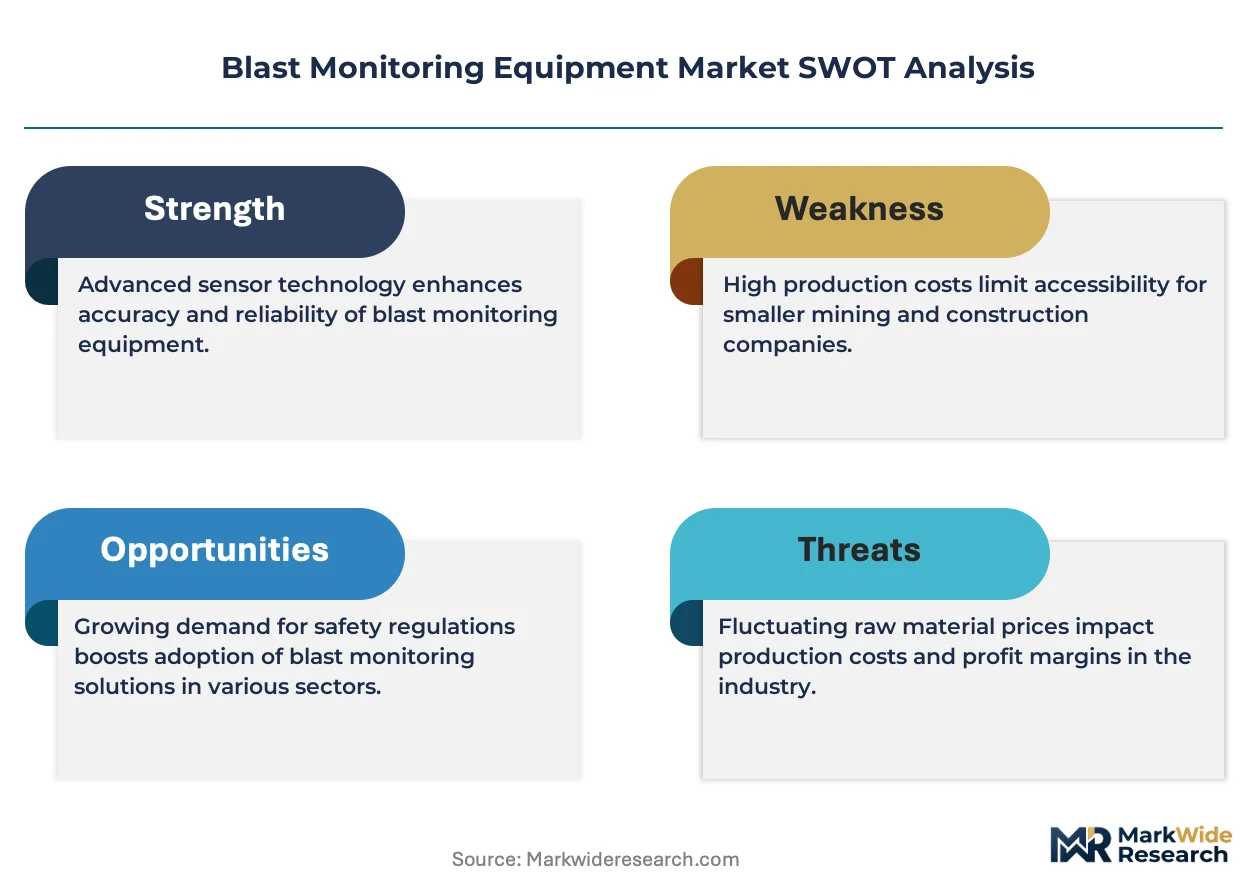
Component supply concentrates among Japanese and German MEMS foundries, forcing equipment assemblers to secure long-term allocation agreements for high-precision accelerometer cores.
- Seismic Sensors:Geophones and triaxial accelerometers measure peak particle velocity with sampling rates exceeding 1,024 samples per second. Western Australia's Pilbara iron ore district accounts for the densest installed base, driven by OSMRE-mandated ground vibration compliance for pit-wall stability programs.
- Monitoring Software:Cloud-native analytics platforms deliver automated threshold alerting and API integration with mine planning systems. Australian mining houses are unbundling hardware procurement from SaaS subscriptions, compressing upfront capital outlays while elevating recurring revenue streams for platform vendors.
- Pressure Sensors:Transient pressure transducers capture air overpressure from blast clouds, typically deployed in arrays for tunneling projects.
- Data Loggers:Ruggedized field units aggregate multi-channel sensor inputs with GPS time synchronization.
Seismic sensors absorb the bulk of installed capacity; monitoring software is expanding most quickly.
Application:
End-use demand clusters around extractive industries where regulatory exposure intersects with catastrophic failure risk.
- Mining Operations:Surface and underground blast monitoring protects nearby infrastructure while optimizing fragmentation. Canadian hard-rock mines deploy machine learning classification to distinguish controlled detonation signatures from ground instability precursors.
- Construction Sites:Urban tunneling and foundation work in China trigger MEE ambient vibration enforcement for metro-adjacent projects, creating first-time compliance obligations among civil contractors.
- Quarry Management:EU F-Gas Regulation pressures German and French operators to reduce blast frequency, elevating monitoring fidelity requirements per detonation event.
- Earthquake Studies:Research networks repurpose blast monitoring hardware for induced seismicity cataloging near geothermal and wastewater injection sites.
Mining operations command the deepest sensor penetration; construction sites are climbing the fastest as urbanization tightens vibration limits.
End User:
Procurement authority varies sharply by organization scale and regulatory directness.
- Mining Companies:Tier-one operators in Nevada and Western Australia specify API-first architectures and wireless geophone networks for autonomous drill fleet integration.
- Construction Firms:Civil contractors face sporadic compliance exposure, driving rental and managed service models over capital purchases.
- Research Institutions:Universities and geological surveys prioritize open data formats and modular calibration libraries for academic reproducibility.
- Government Agencies:National regulators and environmental ministries procure reference-grade instrumentation for enforcement benchmarking.
Mining companies dominate capital expenditure; construction firms are gaining share fastest through operational lease structures.
Technology:
Technology selection determines deployment velocity, data latency, and lifecycle cost structure in bandwidth-constrained pit environments.
- Wireless Monitoring:Eliminates cabling hazards in active blast zones while enabling real-time transmission from remote benches. Australian iron ore producers are standardizing this architecture across Pilbara operations.
- IoT Integration:Sensor-to-cloud pipelines feed mine-wide digital twins, though legacy data logger firmware incompatibility forces costly middleware development.
- Real-time Data Processing:Edge computing architectures migrate waveform analysis to sensor nodes, reducing latency for threshold violations.
- Remote Sensing:Drone-mounted overpressure sensors enable aerial blast cloud mapping beyond ground-based sensor reach.
Wireless monitoring carries the largest installed base; IoT integration shows the steepest expansion trajectory as mines digitize operational technology stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia's Pilbara Special Economic Zone concentrates iron ore blast monitoring procurement, with tax incentives for automation technology accelerating wireless sensor deployment across open-pit operations.
United States
Nevada gold and copper mines drive demand for real-time threshold alerting systems. The US Office of Surface Mining Reclamation and Enforcement tightened ground vibration mandates, forcing equipment upgrades across Appalachian coal regions. Arizona's copper belt hosts the densest concentration of legacy seismograph replacement cycles.
Australia
Pilbara iron ore producers anchor wireless geophone network procurement for pit-wall stability programs. The country's national mining regulator enforces traceable calibration certificates for ground vibration measurement. Queensland's Bowen Basin coal operations are piloting edge-computing sensor nodes for autonomous drill fleet integration.
Canada
Ontario and Quebec hard-rock mines deploy machine learning classification to distinguish blast signatures from ground instability. Health Canada coordinates with provincial authorities on fugitive dust exposure limits intersecting blast protocols. Sudbury's nickel district represents the most advanced adoption of cloud-native analytics platforms.
China
Urban tunneling projects in metro-adjacent construction trigger first-time compliance obligations under MEE ambient vibration enforcement. The country's Ministry of Ecology and Environment standards now cover civil contractors previously exempt from monitoring requirements. Yangtze River Delta infrastructure projects account for the steepest expansion in construction-site sensor deployment.
Germany
Quarries across Bavaria and North Rhine-Westphalia reduce blast frequency under EU F-Gas Regulation pressure, elevating monitoring fidelity per detonation. REACH chemical restrictions force adoption of lower-velocity blasting agents with complex frequency signatures. The Ruhr industrial corridor hosts the most intensive calibration library expansion for modular sensor heads.
Blast Monitoring Equipment Market Competitive Landscape
Australian producers anchor one tier; North American specialists hold calibrated service networks. The vendor structure concentrates around integrated explosives-to-monitoring workflows and certified calibration capabilities. Two strategic archetypes dominate: diversified instrumentation portfolios extending beyond blast sensing, and focused seismograph hardware specialists. Competitive moves center on cloud infrastructure absorption and API-first architecture development for mine planning integration.
Within the integrated workflow tier, Orica Limited exemplifies end-to-end explosives and monitoring bundling. Instantel Inc. and Campbell Scientific Inc. represent specialized hardware and diversified instrumentation archetypes respectively. These three companies occupy positions across the spectrum from explosive-manufacturing integration to multi-sensor environmental platforms, with each anchoring distinct procurement preferences among tier-one mining operators and research institutions.
| Leading Market Players |
|---|
| Instantel Inc. |
| Orica Limited |
| Dyno Nobel Inc. |
| Campbell Scientific Inc. |
| GeoSonics/Vibra-Tech Inc. |
| Hexagon AB |
| Acoem |
| Applied Seismology Consultants |
| Texcel Technology Plc |
| Others |
Value Network & Pricing Analysis
Backward integration into MEMS accelerometer sourcing anchors vendor pricing power in this market, with Japanese and German component foundries commanding allocation premiums that equipment assemblers pass through to mining operators in Western Australia and Nevada.
Pricing Analysis
Short lead-time availability commands measurable premiums in the blast monitoring equipment market, with Australian Pilbara operators paying elevated rates for expedited wireless sensor deployment during pit-wall stability emergencies. Three-tier pricing structure across certified-calibration, standard-compliance, and basic-monitoring levels stratifies procurement, with ISO/IEC 17025 certification tiers extracting the widest spreads. Pricing pressure stems from cloud-native competitors absorbing infrastructure costs to capture SaaS recurring revenue, compressing hardware margins for legacy vendors. Construction firms exhibit the highest price sensitivity due to sporadic compliance exposure, while tier-one mining houses prioritize calibration traceability over unit economics.
Supply Chain Analysis
Specialized technician availability constrains manufacturing scale-up in Canada and Australia, where traceable calibration certificate production demands geoscience-trained labor pools that universities struggle to replenish. High-precision MEMS accelerometer fabrication concentrates in Japan and Germany, with equipment assemblers drawing from concentrated component suppliers for triaxial sensor cores. Supply chain risk centers on single-source vulnerability for aviation-grade pressure transducers used in drone-mounted overpressure systems. Distribution runs through direct vendor-to-mine relationships for tier-one operators, with rental intermediaries serving sporadic construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS foundry capacity constraints prop equipment pricing, with semiconductor allocation cycles creating sustained supply tightness that favors vendors with captive component agreements.
For Market Incumbents: Deepen calibration service network density in Western Australia's Pilbara district to defend against cloud-native competitors offering automated threshold alerting without field technician deployment. Secure long-term MEMS allocation agreements with Japanese foundries to mitigate semiconductor shortage recurrence. Invest in edge-computing firmware development to bridge legacy data logger incompatibility with modern API architectures. For New Entrants and Emerging Players: Begin with urban construction compliance in China's Yangtze River Delta, where MEE ambient vibration enforcement creates first-time demand among civil contractors lacking established vendor relationships. Target rental and managed service models for construction firms facing sporadic compliance exposure rather than capital sales cycles. Differentiate through drone-mounted overpressure sensor integration that incumbent seismograph vendors have underdeveloped. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays, with cloud-native monitoring dashboards commanding premium multiples relative to hardware-centric vendors. Long-term viability favors vendors with API-first architectures that integrate with autonomous mine planning systems. Watch for inflection in optical fiber sensing adoption rates in tunneling applications, as distributed acoustic sensing cable displacement of point-source geophones would revalue hardware-dependent business models.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | OSMRE-mandated traceability requirements in the US create defensive moats for certified service infrastructure. |
| Cloud-Native Platform Migration | Australian mining houses now specify API-first architectures in tender documents, elevating SaaS revenue visibility. |
| MEMS Supply Agreement Securement | Japanese foundry allocation priority determines vendor scaling speed during semiconductor constraint periods. |
| Edge Computing Firmware Development | Legacy data logger incompatibility with modern dashboards forces costly middleware investment for retention. |
| Drone Sensor Integration | UAV-mounted overpressure transducers enable blast cloud mapping beyond ground-based geophone reach. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across mine operations engineers, calibration technicians, seismograph procurement managers, and explosives manufacturing specialists. Bottom-up triangulation against top-down regulatory mandate sizing validated volume estimates, with OSMRE enforcement records and MEE compliance databases providing installation base benchmarks.
Reconciliation of equipment shipment data, SaaS subscription disclosures, and pit-wall stability program budgets informed value projections across the projection horizon. Segmentation dimensions modeled include product type, application environment, end-user procurement authority, and wireless versus wired technology architecture. CAGRs derived from regulatory mandate phase-in schedules and replacement cycle analysis for legacy seismograph fleets, with cloud analytics adoption curves and MEMS supply allocation patterns as industry-specific forecast inputs.
Underlying measurement precision varies by segment; seismic sensor hardware carries tighter precision than nascent drone-mounted pressure sensor categories. Forecasts reflect documented assumptions regarding OSMRE enforcement continuity, MEMS foundry capacity expansion, and cloud infrastructure cost trajectories. Material deviation in semiconductor allocation priority, optical fiber sensing substitution rates, or seismologist labor availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Panic Exit Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Explosion Proof Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market