
 Global Smart PPE Market | 2026-2036
Global Smart PPE Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart PPE Market Outlook
Aftermarket service revenue from connected safety platform subscriptions is reconfiguring margin pools away from one-time hardware sales. 3M Company leverages its respiratory protection installed base to extend software analytics contracts across industrial accounts. Honeywell International Inc. anchors its position through integrated gas detection and body-worn sensor ecosystems. MSA Safety Incorporated competes on firefighter-focused smart helmet architectures that dominate North American municipal procurement channels.
Smart PPE denotes personal protective equipment augmented with embedded sensors, wireless connectivity modules, and real-time data processing capabilities to monitor environmental hazards, physiological states, and location parameters. Units typically integrate accelerometers, gas detectors, temperature sensors, and low-power radio transmitters operating on Bluetooth Low Energy or private LTE networks to stream telemetry to centralized safety dashboards. Smart Helmets currently occupy the largest revenue share due to head protection mandates across heavy industries, while Sensor Technology represents the fastest-expanding technology segment as multi-parameter biometric monitoring displaces single-function alert systems. The Oil & Gas end-user segment sustains premium pricing through explosion-proof certification requirements and remote asset monitoring needs.
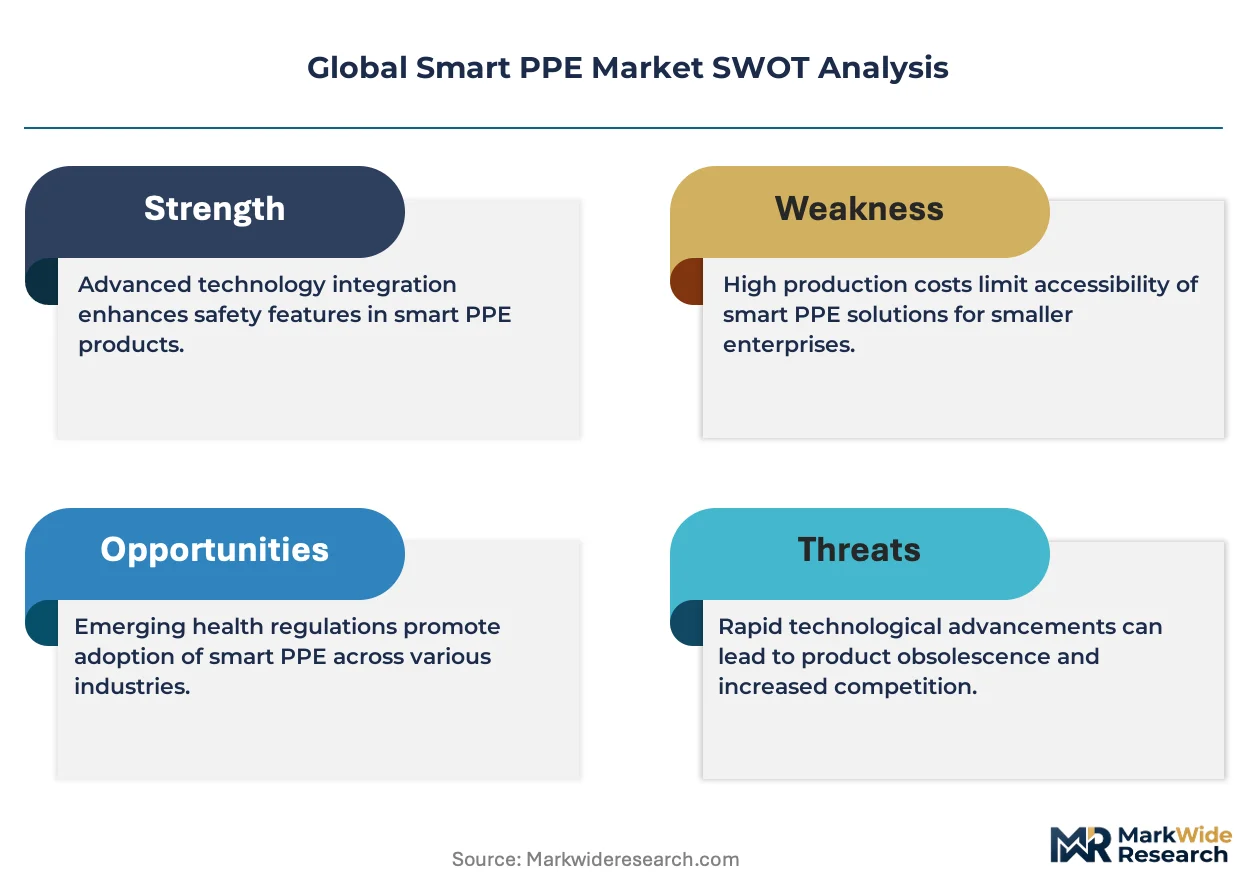
OSHA, the EU AI Act, and Japan's METI industrial safety digitization guidelines are collectively mandating predictive hazard detection capabilities that legacy passive PPE cannot satisfy. CE marking under the EU Machinery Directive now requires documented connectivity interoperability for smart safety devices sold in European member states. Stakeholders must monitor evolving cybersecurity certification requirements for body-worn IoT devices as regulatory scope expands beyond physical protection into data governance and network resilience standards.
Market Dynamics
The transition from passive protective gear to sensor-enabled connected worker platforms is restructuring competitive advantage around real-time data services rather than physical equipment durability alone.
Growth Catalysts
- OSHA digitization mandates:US workplace safety rules now require predictive hazard detection capabilities that only instrumented PPE can deliver, forcing industrial employers toward connected platforms.
- Explosion-proof certification:Oil & Gas operators in remote extraction sites demand certified smart helmets and gas detectors that stream telemetry to centralized monitoring stations.
- Bluetooth Low Energy integration:Ultra-low-power radio modules enable continuous biometric streaming without battery weight penalties, accelerating adoption among construction site operators.
Market Restraints
- Semiconductor supply concentration:MEMS accelerometers and gas sensors rely on fabrication capacity concentrated in Taiwan and South Korea, creating input vulnerability.
- EU AI Act compliance friction:Conformity assessment procedures for AI-enabled hazard prediction algorithms extend product launch timelines by 12-18 months.
- Passive PPE substitution:Unconnected hard hats and respirators retain 60-70% cost advantage in price-sensitive municipal procurement.
Strategic Opportunities
- India industrial safety digitization:Factory Act modernization and state-level EHS mandates create first-mover advantage for connected worker platform providers.
- Private LTE networks:Convergence of body-worn sensors with campus-wide 5G/LTE infrastructure eliminates Bluetooth range limitations in sprawling industrial complexes.
- Aftermarket analytics subscriptions:Safety-as-a-service models transform one-time hardware margins into recurring revenue streams across German automotive manufacturing clusters.
Industry Challenges
- Cybersecurity certification gaps:No harmonized standards exist for penetration testing of body-worn IoT devices, forcing vendors to navigate fragmented national requirements.
- Legacy SCADA integration:Smart PPE telemetry protocols rarely interoperate with existing plant control systems without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart PPE Market |
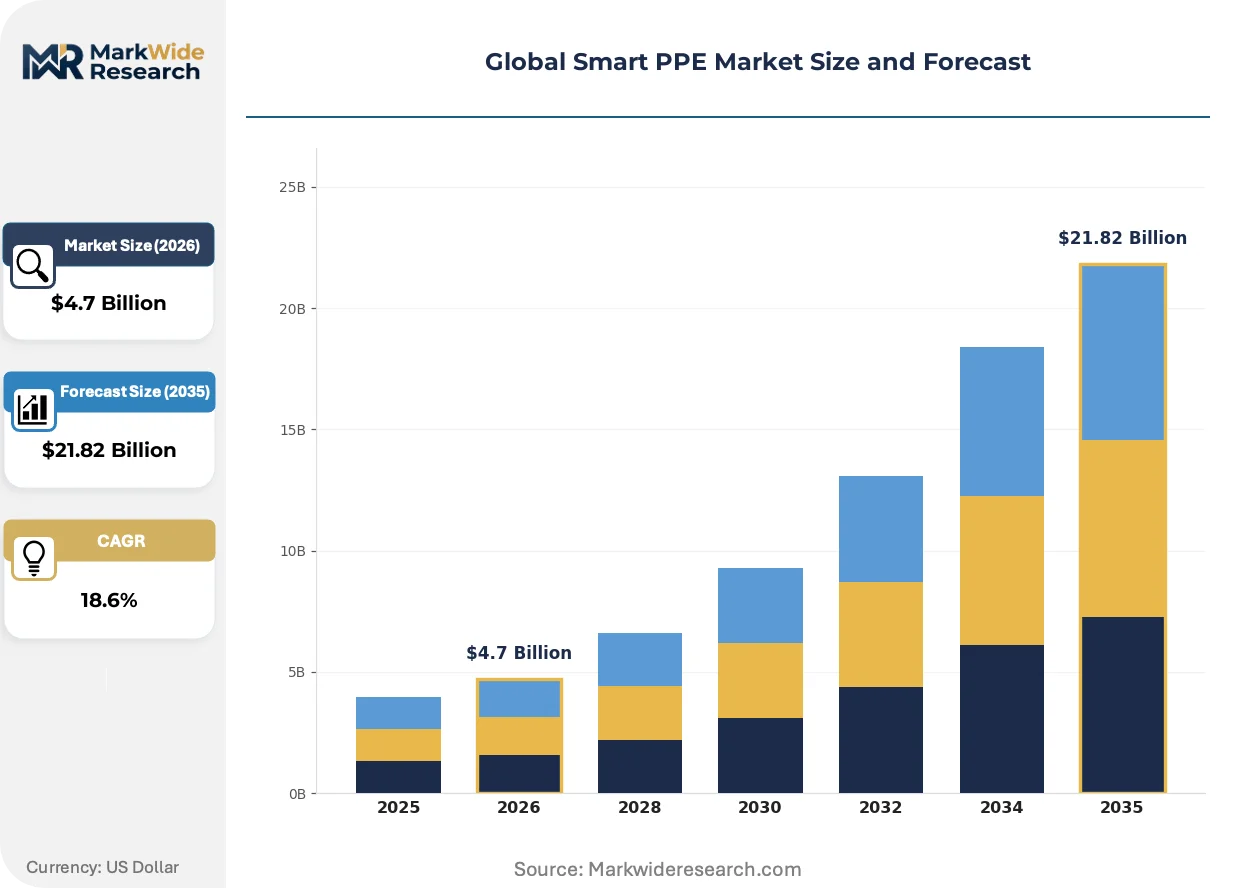
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Helmets, Smart Gloves, Smart Goggles, Smart Vests Technology: IoT, RFID, AR, Sensor Technology End User: Construction, Oil & Gas, Healthcare, Manufacturing Installation: On-Site, Off-Site, Remote, Custom |
| Companies Covered | 3M Company, Honeywell International Inc., MSA Safety Incorporated, Ansell Ltd., DuPont de Nemours Inc., Uvex Group, Drägerwerk AG & Co. KGaA, Vuzix Corporation, Delta Plus Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart PPE Market Strategic Shifts
Hardware commoditization is pushing value creation toward predictive analytics software, while regulatory mandates accelerate the obsolescence of unconnected protective equipment.
Multi-parameter biometric monitoring is migrating from single-function alert systems to integrated physiological dashboards. Mining and heavy construction operators now deploy vests combining heart rate, core temperature, and exertion metrics. This convergence is compressing vendor margins on standalone sensors while expanding addressable spend for integrated platform subscriptions.
The EU AI Act's risk classification framework now governs AI-enabled hazard prediction algorithms embedded in smart helmets. Industrial safety equipment with automated decision-making capabilities faces mandatory conformity assessment and post-market monitoring. German chemical manufacturers and French nuclear operators are front-loading compliance investments to secure CE marking ahead of enforcement deadlines.
Buyer organizations now unbundle hardware procurement from analytics service contracts, treating connected safety platforms as operational technology rather than protective equipment. Industrial facility managers in Japan and the United States separately negotiate sensor hardware, connectivity infrastructure, and predictive software tiers. This purchasing pattern fragmentation favors vendors with modular architecture over integrated stack providers.
Global Smart PPE Market Segmentation
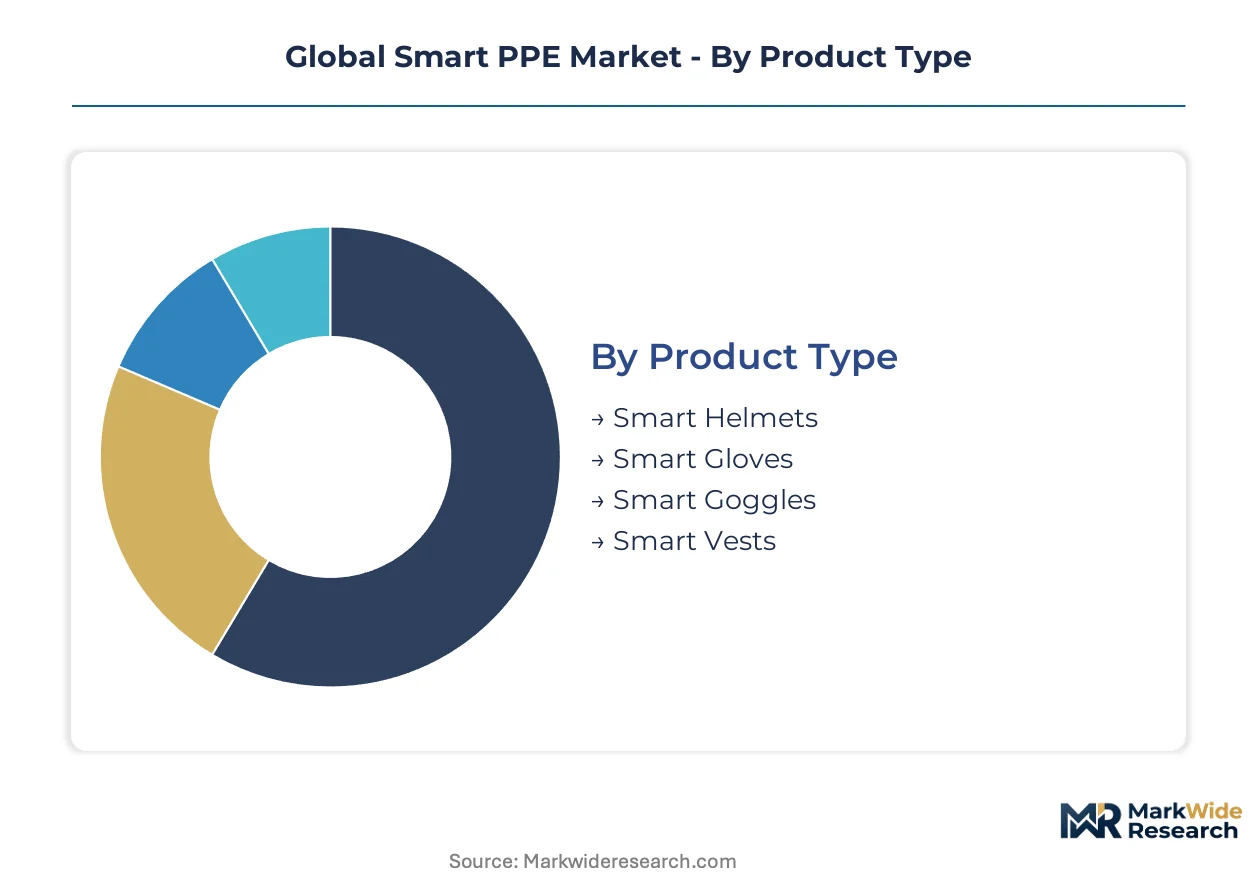
Smart PPE segmentation reveals how hardware form factors, connectivity architectures, and deployment contexts reshape procurement patterns. Buyers now unbundle sensor hardware from analytics platforms, creating distinct purchasing tiers across industrial verticals.
Product Type:
Smart PPE form factors span the full hazard protection spectrum from head-mounted systems to full-body monitoring garments.
- Smart Helmets:Integrated head protection combines accelerometers, gas detectors, and Bluetooth Low Energy transmitters for real-time impact and atmospheric hazard alerts. Construction site operators in Germany and municipal fire departments across the United States anchor demand through mandatory head protection protocols and connected worker platform rollouts.
- Smart Gloves:Haptic feedback and force-sensing fabrics enable dexterity tracking alongside chemical exposure detection. Automotive assembly lines in Japan and chemical handling facilities in France are concentrating procurement around ergonomic strain prevention and solvent permeation monitoring.
- Smart Goggles:AR-enabled vision systems overlay hazard annotations and procedural guidance for maintenance technicians.
- Smart Vests:Biometric monitoring garments track core temperature, heart rate, and exertion metrics for heat stress prevention.
The dominant share belongs to Smart Helmets, while Smart Vests are closing the gap fastest.
Technology:
Technology segmentation tracks the shift from passive identification toward predictive hazard intelligence.
- IoT:Mesh-networked sensor arrays stream telemetry to centralized safety dashboards through private LTE or campus-wide 5G infrastructure. Oil & Gas extraction sites in remote locations drive premium deployment for explosion-proof certified connectivity.
- Sensor Technology:Multi-parameter biometric chips integrate accelerometry, thermal sensing, and electrochemical gas detection on single low-power modules. Mining operators in Australia and heavy construction consortia in Canada are displacing standalone alert systems with integrated physiological monitoring.
- RFID:Proximity-based personnel tracking enables zone-based access control and mustering automation.
- AR:Optical see-through displays project contextual hazard data and remote expert guidance.
Sensor Technology commands the steepest expansion trajectory as multi-function integration displaces discrete single-purpose devices.
End User:
End-user segmentation reflects divergent certification requirements and connectivity infrastructure maturity.
- Oil & Gas:Explosion-proof certification mandates under ATEX and IECEx frameworks sustain premium pricing for smart helmets and portable gas detectors. Remote extraction assets in the North Sea and Permian Basin require continuous telemetry streaming to centralized monitoring stations.
- Construction:Connected worker platforms integrate fall detection, proximity alerts, and equipment collision warnings. General contractors in the United States and Japan are accelerating adoption through OSHA digitization mandates and METI industrial safety guidelines.
- Healthcare:Biosafety monitoring for infectious disease exposure and ergonomic strain tracking.
- Manufacturing:Machine guarding integration and quality assurance through operator attention monitoring.
Oil & Gas retains the highest value per unit, while Construction is scaling volume fastest through platform standardization.
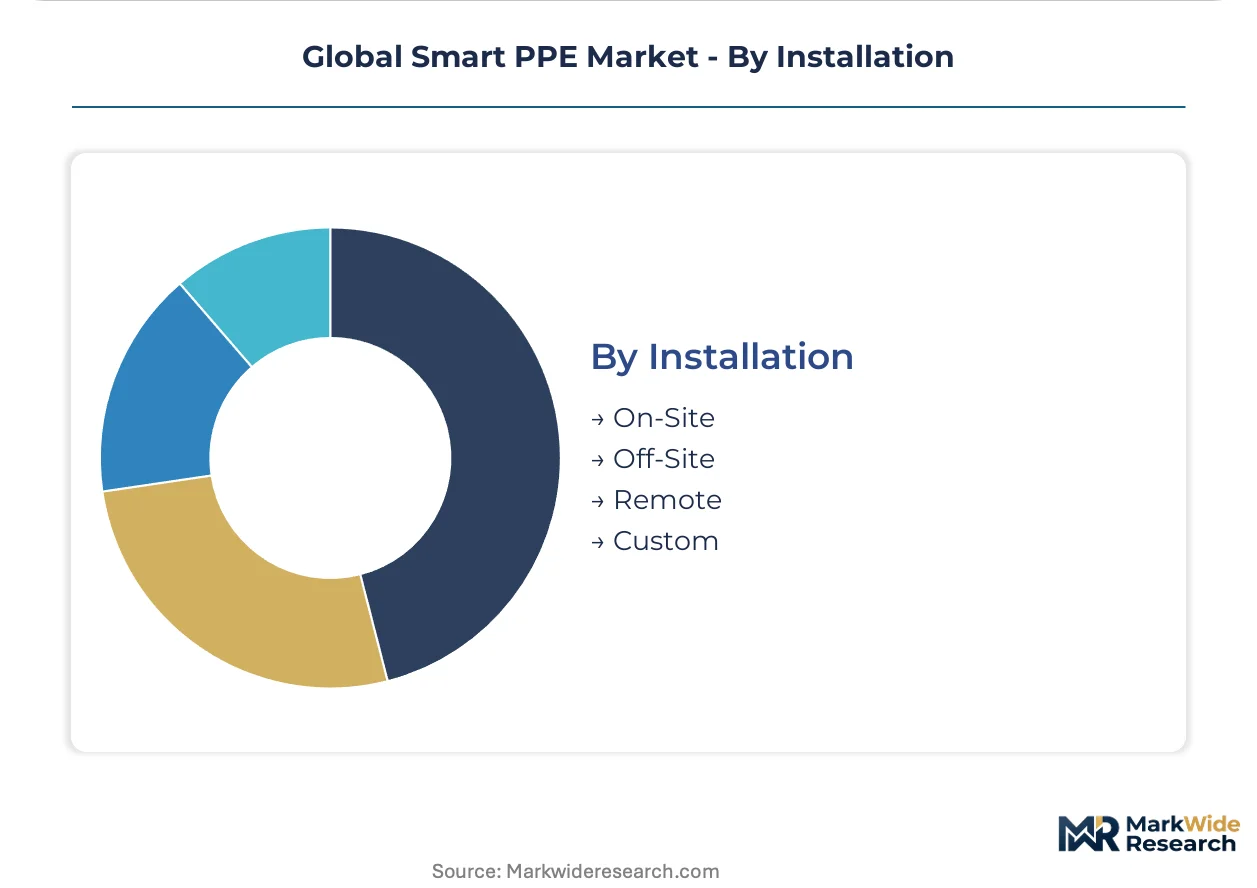
Installation:
Installation segmentation captures how deployment location shapes system architecture and service contract structures.
- On-Site:Fixed infrastructure integration with plant SCADA and building management systems requires middleware development for protocol translation. German automotive manufacturing clusters and Japanese steel mills anchor demand through captive private networks.
- Remote:Satellite or cellular backhaul enables hazard monitoring for geographically dispersed assets without local connectivity infrastructure. Pipeline operators in Kazakhstan and offshore platforms in Brazil concentrate procurement around autonomous telemetry buffering and store-and-forward architectures.
- Off-Site:Pre-configured systems deployed through third-party safety service providers.
- Custom:Bespoke integration for specialized hazard profiles or legacy equipment retrofit.
On-Site deployments dominate current revenue, though Remote installations are expanding most quickly through distributed asset digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, absorbing premium costs for integrated analytics platforms, while municipal procurement channels in the United States and construction consortia in India remain highly sensitive to unit hardware costs.
United States
OSHA digitization mandates drive predictive hazard detection procurement across industrial employers. The Department of Labor's connected worker platform requirements force compliance upgrades in heavy manufacturing. Houston's petrochemical corridor and Pittsburgh's steel heritage regions anchor smart helmet deployments for explosion-proof monitoring.
Germany
Automotive manufacturing clusters absorb premium pricing for safety-as-a-service subscription models. The EU AI Act's conformity assessment deadlines accelerate CE marking investments ahead of enforcement. Bavarian chemical parks and Baden-Württemberg automotive assembly lines concentrate demand for integrated physiological monitoring vests.
Japan
METI industrial safety digitization guidelines mandate real-time biometric streaming for construction and heavy industry operators. Japanese facility managers unbundle hardware from analytics contracts, favoring modular procurement. Osaka-Kansai manufacturing belts and Nagoya's industrial corridors lead smart glove adoption for ergonomic strain prevention.
India
Factory Act modernization and state-level EHS mandates create first-mover opportunities for connected worker platform providers. Price-sensitive municipal construction procurement favors basic sensor hardware over integrated analytics. Maharashtra's Mumbai-Pune industrial belt and Gujarat's chemical zones concentrate early smart vest deployments for heat stress monitoring.
United Kingdom
Post-Brexit regulatory divergence creates compliance complexity for CE-marked smart safety equipment. North Sea oil and gas operators sustain premium demand for ATEX-certified remote telemetry systems. Aberdeen's energy services cluster and Teesside's process industries anchor explosion-proof smart helmet procurement.
Global Smart PPE Market Competitive Environment
Integrated platform providers and specialized safety equipment manufacturers split the market between recurring analytics revenue and certified hardware margins. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates extending software services from respiratory and gas detection installed bases; pure-play safety specialists competing on firefighter-focused helmet architectures; and emerging AR hardware developers targeting maintenance technician vision systems. Dominant competitive moves include backward integration into sensor module production and strategic partnerships with private LTE network infrastructure providers.
Within the diversified industrial tier, 3M Company and Honeywell International Inc. represent archetypes leveraging broad protective equipment portfolios to anchor software subscription contracts. MSA Safety Incorporated exemplifies the specialist model with focused smart helmet architectures. These three entities occupy positions spanning municipal procurement channels, industrial accounts, and hazardous environment certifications without overlapping segment dominance.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Ansell Ltd. |
| DuPont de Nemours Inc. |
| Uvex Group |
| Drägerwerk AG & Co. KGaA |
| Vuzix Corporation |
| Delta Plus Group |
| Others |
Value Chain & Pricing Dynamics
Semiconductor supply concentration in Taiwan and South Korea determines both the premium spread for explosion-certified smart helmets and the geographic clustering of final assembly capacity. Buyers absorbing MEMS sensor cost volatility face tiered hardware pricing that separates ATEX-certified configurations from standard industrial units.
Pricing Analysis
Aftermarket analytics subscriptions now drive lifetime value across German automotive manufacturing clusters and Japanese steel mills. Three-tier pricing structure across premium, standard, and economy levels separates explosion-proof certified units with private LTE backhaul from Bluetooth-only configurations. Cost compression in the municipal procurement tier intensifies because unconnected hard hats retain substantial unit cost advantages. Construction consortia in India exhibit the highest price sensitivity, while German chemical manufacturers absorb premium safety-as-a-service contracts with minimal elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for gas sensor module procurement. MEMS accelerometer fabrication concentrates in Taiwan and South Korea, while final helmet assembly clusters in China and Mexico for North American delivery. Raw material dependencies span lithium-polymer cells, flame-retardant polycarbonate resins, and electrochemical sensing substrates. Distribution runs through industrial safety distributors and direct OEM contracts rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement tiers creates entry niches as buyers unbundle hardware from analytics contracts and negotiate connectivity infrastructure separately.
For Market Incumbents: Entrench platform stickiness through backward integration into sensor module production and captive private LTE infrastructure partnerships. 3M and Honeywell should deepen software subscription attach rates across respiratory protection installed bases before modular competitors displace integrated stack providers. Certification investment in EU AI Act conformity assessment procedures secures CE marking continuity ahead of enforcement deadlines. For New Entrants and Emerging Players: Mid-market construction operators in India and state-level EHS mandate jurisdictions represent the most penetrable entry point for basic sensor hardware without bundled analytics. Target heat stress monitoring vests for Maharashtra's Mumbai-Pune industrial belt where Factory Act modernization creates first-mover windows. A direct-to-plant safety manager go-to-market angle bypasses distributor markups and accelerates pilot deployments. For Investors and Strategic Acquirers: EU AI Act enforcement reshapes the acquisition landscape toward vendors with documented conformity assessment capabilities and post-market monitoring infrastructure. Long-term viability centers on recurring revenue attachment rates rather than hardware shipment volumes. Watch cybersecurity certification harmonization progress as the inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Modules | Captive MEMS supply from Taiwan fabs reduces input vulnerability for 3M and Honeywell. |
| Private LTE Infrastructure Partnership | Campus-wide 5G convergence eliminates Bluetooth range limits for German automotive clusters. |
| EU AI Act Conformity Assessment | Documented algorithm risk classification secures CE marking for MSA Safety firefighter helmets. |
| Modular Architecture Development | Unbundled hardware-software-procurement matches Japanese buyer purchasing fragmentation. |
| Heat Stress Monitoring Platform Launch | Integrated biometric vests capture Australian mining and Canadian heavy construction demand. |
Study Parameters
Operator-level perspectives from plant safety managers, connected worker platform engineers, industrial gas detection specialists, and municipal procurement officers anchored the qualitative base. Primary interviews combined with secondary validation against OSHA regulatory filings, EU Machinery Directive technical documentation, METI industrial safety digitization guidelines, and SEC 10-K equipment revenue disclosures. Bottom-up unit shipment estimates triangulated against top-down industrial safety digitization budget projections.
Scenario-bracketing around OSHA enforcement intensity and EU AI Act compliance timeline uncertainty shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, connectivity architecture, end-user industry certification requirements, and regional regulatory cluster. CAGRs derived from weighted average of historical adoption curves and mandated compliance upgrade schedules, with specific inputs from construction site operator platform rollout timelines and oil and gas remote asset monitoring deployment cycles.
Practitioners should monitor semiconductor supply allocation shifts and cybersecurity certification harmonization progress for early signals of hardware cost trajectory and platform consolidation timing. Forecasts reflect assumptions about regulatory enforcement consistency and industrial employer compliance budget availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Edge Protector Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Firefighter Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market