
 Riot Gear Market | 2026-2036
Riot Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Riot Gear Market Analytics
Market Dynamics
NIJ Level IIIA ballistic protection is reorganizing procurement standards across municipal and federal agencies. Safariland leverages its vertically integrated armor manufacturing to sustain premium positioning in North American government contracts. Rheinmetall AG anchors European supply through its established relationships with German federal police and export programs. Axon Enterprise differentiates by integrating less-lethal systems with connected body-worn platforms, extending its influence beyond traditional hardware.
Product Segmentation
Riot gear encompasses protective equipment engineered to withstand blunt force trauma, chemical exposure, and projectile impact, typically constructed from molded polycarbonate shields, aramid fiber composites, and padded nylon carriers rated for specific threat levels. Body armor commands the largest revenue share within product type segmentation due to recurring replacement cycles and escalating protection ratings, while polycarbonate shields represent the fastest-growing material application as agencies prioritize transparent coverage for crowd visibility. Government contracts dominate distribution channel structure, capturing volume through multi-year procurement frameworks that lock in supplier relationships and suppress price competition from wholesale or direct retail alternatives.
Regulatory Environment
NIJ certification standards govern United States ballistic performance requirements, while CE marking under the EU PPE Regulation and Germany's KBA-equivalent technical approvals shape European market access. The EU AI Act and emerging digital surveillance frameworks are beginning to intersect with body-worn equipment categories, complicating compliance for integrated sensor platforms. Stakeholders must monitor how dual-use export controls and human rights due diligence legislation reshape cross-border sales eligibility for crowd-control technologies.
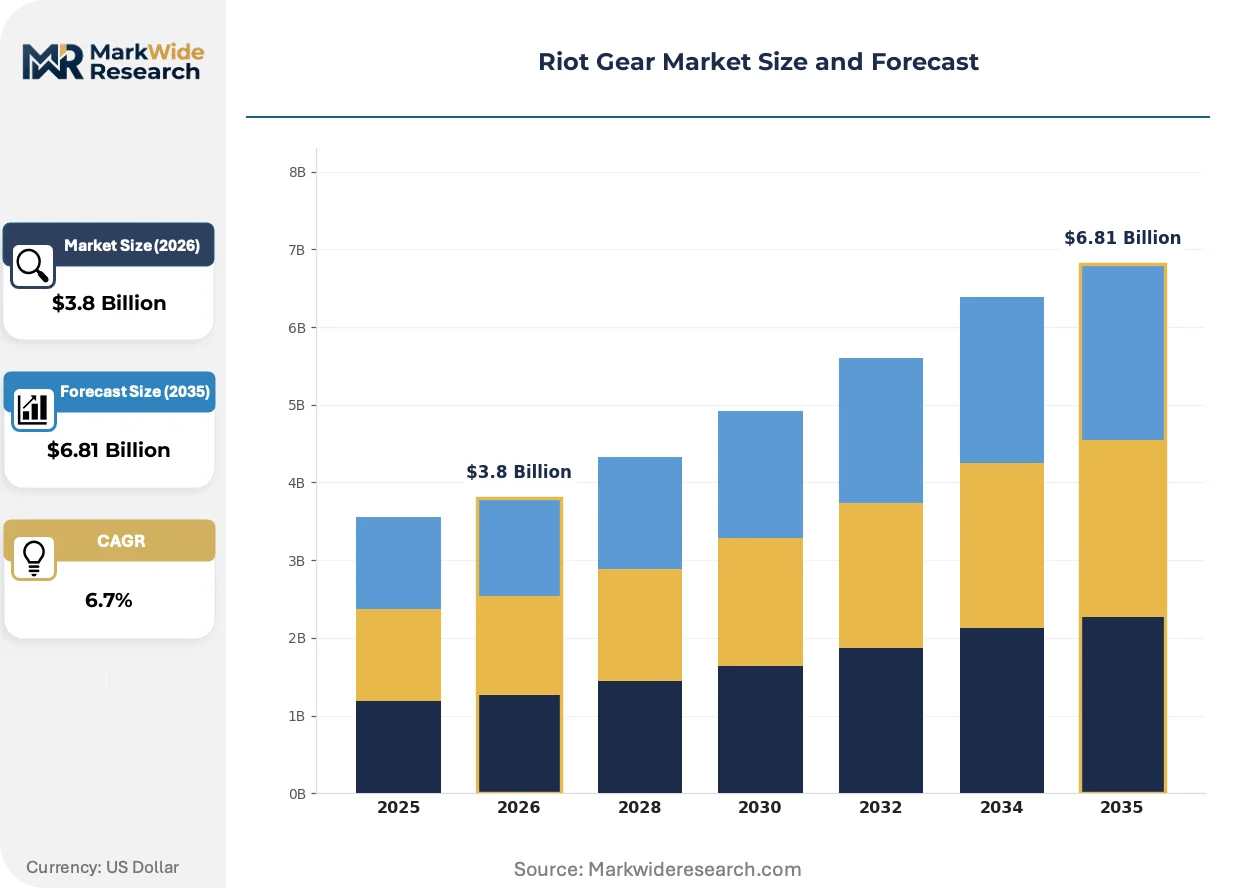
Market Dynamics
NIJ Level IIIA ballistic protection standards are forcing rapid equipment turnover across municipal and federal agencies, compressing replacement cycles and elevating certification requirements for incumbent suppliers.
Growth Catalysts
- Federal procurement programs:United States municipal police departments are accelerating modernization cycles through Department of Justice equipment grants, creating sustained demand pull for certified protective systems.
- EU PPE Regulation:CE marking requirements under the EU's personal protective equipment framework are mandating upgraded impact resistance testing, compelling agencies across Germany, France, and Italy to refresh legacy inventories.
- Aramid fiber composites:Advanced woven materials are achieving NIJ Level IIIA ratings at reduced weight profiles, enabling extended wear duration for riot control personnel during prolonged crowd management operations.
Market Restraints
- Polycarbonate resin price volatility:Shield manufacturers face margin pressure from petrochemical feedstock fluctuations, particularly acrylonitrile and bisphenol-A spot market swings that propagate through molding supply chains.
- German supply concentration:Ballistic testing infrastructure and KBA-equivalent certification bodies cluster in Bavaria and Baden-Württemberg, creating geographic chokepoints for European market access.
- Weight-protection tradeoff:Current aramid-polyethylene hybrid laminates cannot simultaneously achieve Level IIIA ratings below 1.2 kg per square meter, limiting officer mobility in extended deployments.
Strategic Opportunities
- Integrated sensor platforms:Convergence of body-worn cameras with biometric monitoring and real-time positioning creates white space for vendors capable of bundling hardware with data analytics subscriptions.
- India state police modernization:BIS certification pathways and central government internal security funds are opening procurement channels previously dominated by unorganized local suppliers.
- EU AI Act compliance services:Emerging digital surveillance frameworks are mandating algorithmic transparency for facial recognition-enabled helmet systems, creating advisory revenue streams for certification consultancies.
Industry Challenges
- NIJ certification backlog:Ballistic testing laboratory capacity constraints are extending type approval timelines to 14-18 months, delaying product launches and freezing R&D amortization schedules.
- Legacy carrier integration:New hard armor plates require retrofitting of existing nylon MOLLE webbing systems, creating field compatibility failures and return authorization costs for distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riot Gear Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shields, Helmets, Body Armor, Baton Material: Polycarbonate, Kevlar, Nylon, Steel End User: Law Enforcement, Military, Private Security, Emergency Services Distribution Channel: Online Retail, Wholesalers, Direct Sales, Government Contracts |
| Companies Covered | Combined Systems, Axon Enterprise, Safariland, Paulson Manufacturing, DMS Plastics, Chase Tactical, Damascus, Amtec Less Lethal Systems, Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riot Gear Market Evolving Landscape
Transparent polycarbonate shield technology is advancing rapidly, with manufacturers embedding anti-fog coatings and edge lighting to maintain visibility in chemical spray environments while preserving ballistic integrity.
Shear-thickening fluid armor inserts are supplanting traditional rigid plates in select municipal agency trials. Chicago and Los Angeles police departments have piloted soft armor systems for bicycle and mounted units where flexibility outweighs maximum threat protection. This material transition is compressing the addressable market for conventional ceramic-composite suppliers while opening procurement slots for specialty chemical formulators.
CE marking under the EU PPE Regulation is tightening impact test protocols for visor and shield assemblies. German federal police procurement specifications now mandate multi-hit blunt trauma resistance at velocities exceeding previous EN 166 standards. French National Gendarmerie contracts are prioritizing suppliers with in-house certification capabilities, accelerating consolidation among mid-tier European manufacturers.
Municipal agencies are unbundling after-sales service from initial equipment purchases. Texas and Florida sheriff departments now contract third-party armor inspection services separately from manufacturer warranties, shifting lifecycle revenue from original vendors to independent maintenance providers. This disintermediation is most pronounced in Sun Belt states with aggressive privatization mandates and limited in-house forensic equipment capabilities.
Riot Gear Market Segmentation
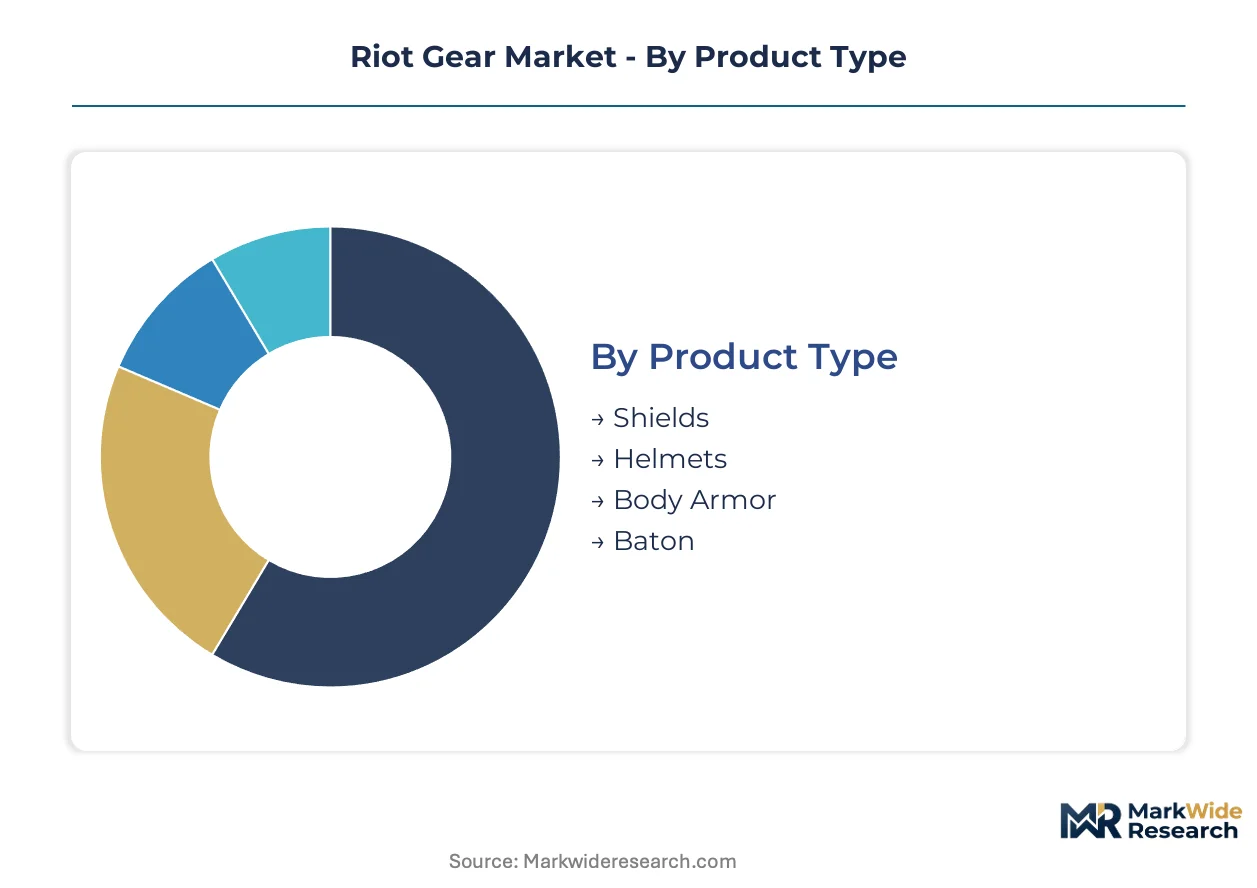
Riot gear procurement splits along protection level, deployment duration, and institutional buyer type. Understanding these fault lines reveals where certification requirements and replacement cycles concentrate commercial value.
Product Type:
Margin pools concentrate in body armor where NIJ recertification mandates create recurring revenue streams, while shields capture premium positioning through optical clarity specifications.
- Shields:Molded polycarbonate and transparent aramid composites form the protective barrier, rated for blunt trauma and chemical exposure. Texas and Florida municipal agencies are prioritizing anti-fog coatings and edge-lit visibility systems for nighttime crowd operations, driving specification upgrades beyond baseline ballistic ratings.
- Body Armor:Aramid fiber and polyethylene composite panels rated NIJ Level IIIA dominate procurement volumes, with carriers integrating MOLLE webbing for modular equipment attachment. Federal Department of Justice equipment grants are accelerating replacement cycles across United States municipal police departments, compressing amortization schedules for incumbent suppliers.
- Helmets:High-cut and mid-cut ballistic designs with integrated visor mounting points address facial protection requirements.
- Baton:Expandable and fixed-length impact weapons constructed from aircraft-grade aluminum or reinforced polymers.
The dominant share belongs to Body Armor, while Shields is closing the gap fastest.
Material:
Cost tier stratification separates premium aramid systems from commodity-grade alternatives, with raw material volatility reshaping supplier margins.
- Polycarbonate:Thermoplastic resin shields and visor assemblies offer optical transparency with impact resistance, though acrylonitrile and bisphenol-A feedstock price swings compress molding margins. Chicago and Los Angeles police departments have piloted advanced formulations for bicycle and mounted unit flexibility requirements.
- Kevlar:DuPont's para-aramid fiber remains the reference standard for soft armor panels, achieving NIJ Level IIIA ratings through woven laminate construction. German federal police procurement specifications under KBA-equivalent technical approvals mandate multi-hit performance that favors established aramid suppliers with in-house ballistic testing capabilities.
- Nylon:Ballistic carriers and padded backing systems utilize Cordura and similar high-denier woven fabrics for abrasion resistance.
- Steel:Hard armor plates and riot shield frames employ alloy compositions for cost-sensitive applications where weight tolerance permits.
Kevlar retains institutional preference for certified protection, though Polycarbonate applications are expanding most quickly.
End User:
Customer type determines procurement route and specification intensity, with government buyers imposing certification barriers that exclude commercial channels.
- Law Enforcement:Municipal police departments and federal agencies constitute the primary demand center, with multi-year procurement frameworks locking in supplier relationships. India's state police modernization through BIS certification pathways is opening centralized procurement channels previously fragmented across unorganized local vendors.
- Military:Defense ministry contracts impose additional environmental and interoperability standards beyond civilian police requirements.
- Private Security:Corporate and event security operators purchase through wholesale and direct retail channels with reduced certification overhead.
- Emergency Services:Fire and medical first responders require specialized chemical and thermal protection integration.
Law Enforcement commands the dominant procurement volume, while Military specifications are climbing fastest in technical complexity.
Distribution Channel:
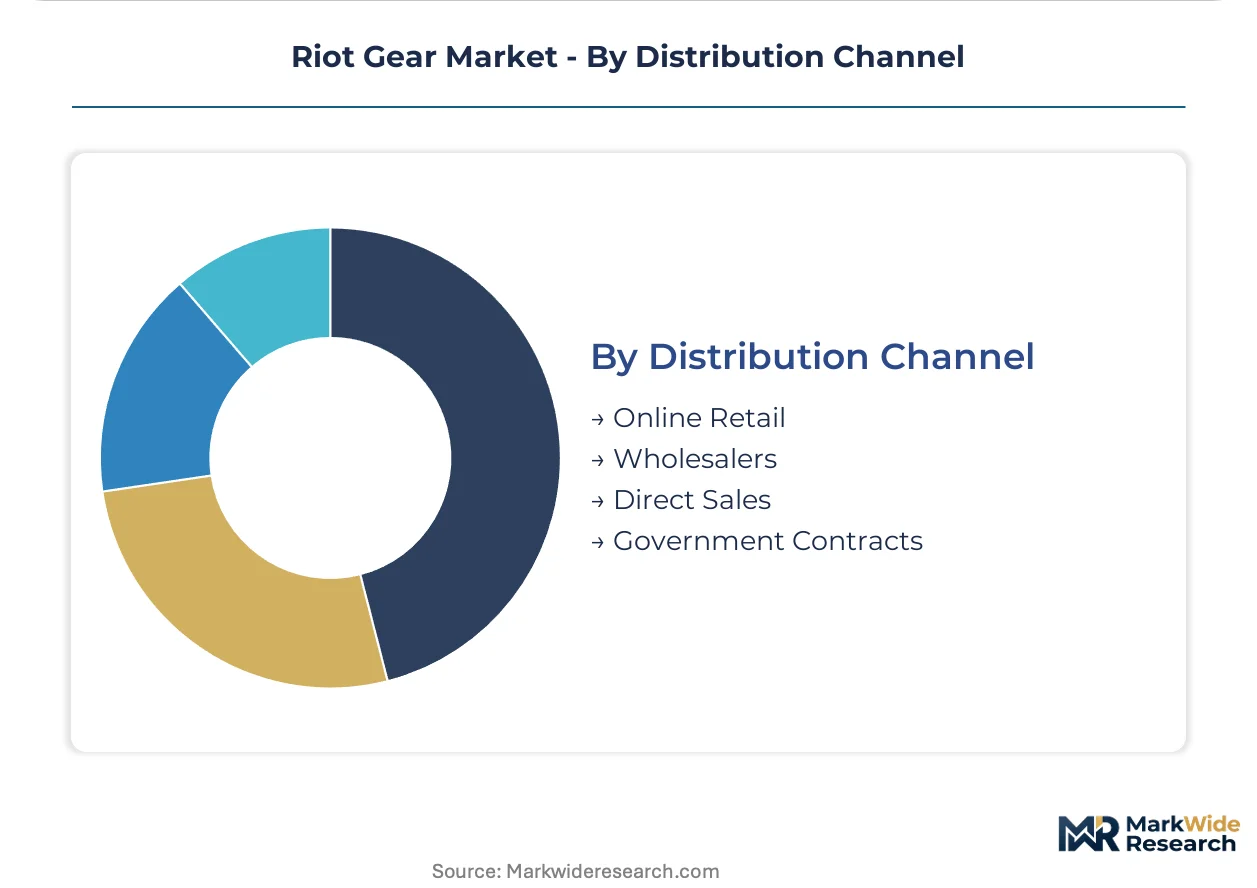
Supply concentration in government contracting creates structural barriers for alternative channels, with certification requirements filtering market access.
- Government Contracts:Multi-year procurement frameworks at federal and state levels capture volume through pre-qualified vendor lists, suppressing price competition. CE marking under EU PPE Regulation and Germany's KBA-equivalent approvals favor suppliers with established European testing relationships, consolidating access among incumbent manufacturers.
- Direct Sales:Manufacturer-to-agency relationships bypass distributor margins for large-volume municipal and federal accounts.
- Wholesalers:Regional distributors serve mid-tier agencies with inventory pooling and consolidated logistics.
- Online Retail:E-commerce channels address private security and individual officer purchases with limited configuration options.
Government Contracts dominate channel value, while Direct Sales is gaining share fastest among large agency consolidations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ballistic testing infrastructure and KBA-equivalent certification bodies cluster in southern Germany, creating geographic chokepoints for European market access. United States federal procurement programs and India's state police modernization are redistributing demand centers away from traditional Western concentration.
United States
Department of Justice equipment grants accelerate municipal police department modernization cycles. NIJ certification standards govern ballistic performance requirements for all federal and state agency procurement. Texas and Florida sheriff departments lead third-party armor inspection contracting, shifting lifecycle revenue from manufacturers to independent maintenance providers.
Germany
German federal police procurement specifications mandate multi-hit blunt trauma resistance exceeding previous EN 166 standards. CE marking under EU PPE Regulation and KBA-equivalent technical approvals shape continental market access. Bavaria and Baden-Württemberg host the concentrated ballistic testing infrastructure that European suppliers must navigate.
India
Central government internal security funds are opening procurement channels previously fragmented across unorganized local vendors. BIS certification pathways establish centralized procurement frameworks for state police forces. Maharashtra and Delhi-NCR police departments drive initial demand for internationally certified protective systems.
France
French National Gendarmerie contracts prioritize suppliers with in-house certification capabilities, accelerating consolidation among mid-tier European manufacturers. CE marking requirements under EU PPE Regulation mandate upgraded impact resistance testing. The Paris metropolitan area concentrates procurement decision-making for national law enforcement agencies.
China
Domestic security expenditure priorities channel procurement through state-owned enterprise frameworks with limited international supplier penetration. GB standards and SAMR oversight apply to protective equipment categories. Yangtze River Delta manufacturing clusters supply polycarbonate shield components to regional law enforcement agencies.
Riot Gear Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Vertically integrated armor manufacturers sustain premium positioning through captive supply chains and certification relationships. Specialized shield fabricators compete on optical clarity specifications and rapid customization turnaround. The dominant competitive moves involve strategic partnerships with testing laboratories and geographic expansion into India's emerging certification pathways.
Within the integrated-systems tier, Rheinmetall AG anchors European supply through established relationships with German federal police and export programs. Axon Enterprise occupies a position exemplifying convergence between less-lethal hardware and connected platform integration. Safariland represents the vertically integrated archetype with in-house armor manufacturing sustaining premium positioning in North American government contracts.
| Leading Market Players |
|---|
| Combined Systems |
| Axon Enterprise |
| Safariland |
| Paulson Manufacturing |
| DMS Plastics |
| Chase Tactical |
| Damascus |
| Amtec Less Lethal Systems |
| Rheinmetall AG |
| Others |
Value Network & Pricing Analysis
Fourteen-to-eighteen-month NIJ certification timelines compress inventory turns and amplify pricing power for pre-qualified armor suppliers with captive testing relationships. This lead-time band concentrates procurement leverage among incumbent vendors while forcing municipal buyers into premium contract structures that absorb certification risk.
Pricing Analysis
NIJ Level IIIA certification dictates the pricing tier structure across municipal and federal procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates vertically integrated armor manufacturers with in-house ballistic testing from distributors sourcing commodity panels and unbranded shield fabricators. Cost compression in the standard tier is intensifying because polycarbonate resin feedstock volatility propagates through molding supply chains. Private security operators exhibit the highest price sensitivity due to absent certification mandates, while federal agencies prioritize performance guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of aramid fiber and polycarbonate resin dominates inventory strategy among tier-one armor manufacturers seeking insulation from petrochemical spot market swings. Raw material supply concentrates in the United States, Germany, and China, with DuPont's para-aramid production anchoring soft armor panel availability and Yangtze River Delta clusters feeding shield component demand. Component dependencies rest on acrylonitrile and bisphenol-A derivatives, plus woven nylon carrier fabrics. Single-source vulnerability in German KBA-equivalent certification infrastructure creates geographic chokepoints for European market access. Distribution runs through multi-year government procurement frameworks that suppress wholesale channel development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering through municipal police department modernization cycles funded by federal equipment grants. Procurement volume compression during prior budget austerity is reversing as agencies refresh legacy inventories to meet elevated NIJ protection standards.
For Market Incumbents: Secure captive ballistic testing capacity to defend against certification backlog delays that freeze competitor product launches. Deepen upstream control over aramid fiber weaving operations to offset raw material margin pressure from petrochemical volatility. Rheinmetall AG's established KBA relationships exemplify how European certification anchoring insulates pricing power.
For New Entrants and Emerging Players: Anchor in India's state police modernization through BIS certification pathways that bypass entrenched Western supplier relationships. Target Maharashtra and Delhi-NCR departments with internationally certified protective systems priced below legacy import premiums. Pursue direct sales relationships with large municipal consolidations to circumvent government contract pre-qualification barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates seeking to divest non-core protective equipment divisions amid portfolio rationalization. Long-term viability hinges on sustained federal procurement commitment rather than cyclical municipal budget elasticity. Watch NIJ certification laboratory capacity expansion announcements as the signal indicating whether supply constraints will persist or ease.
| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Certification Investment | In-house ballistic testing capability compresses type-approval timelines from 18 months to under 12. |
| Aramid Fiber Backward Integration | Captive para-aramid weaving insulates margin structures from DuPont supply allocation decisions. |
| Integrated Sensor Platform Development | Convergence of body-worn cameras with biometric monitoring opens recurring SaaS revenue streams. |
| India BIS Certification Pathway | Centralized state police procurement channels displace fragmented local vendor relationships. |
| Third-Party Armor Inspection Services | Lifecycle revenue capture shifts from manufacturers to independent maintenance providers in Sun Belt states. |
Research Methodology
The analysis maps body armor, shields, helmets, and baton segments, each validated through procurement officers at municipal police departments, federal equipment grant administrators, ballistic testing laboratory directors, and protective equipment distributors. Primary interviews with these stakeholders combined with secondary validation from NIJ compliance publications, Department of Justice equipment grant disclosures, EU PPE Regulation guidance documents, and BIS certification records. Bottom-up shipment estimates and top-down federal budget allocation analysis provided cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include protection level tier, deployment duration category, institutional buyer type, and material composition grade. CAGRs were derived from equipment replacement cycle analysis and federal procurement schedule trajectories. Forecast inputs incorporated NIJ recertification mandate timelines and municipal budget elasticity assumptions.
Decision-makers should treat outputs as directional under sustained federal equipment grant authorization; material deviation would warrant model refresh. Specific risk factors include polycarbonate resin price volatility, certification laboratory capacity constraints, and municipal budget austerity reversals. Revision becomes warranted when NIJ backlog duration crosses 24-month thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsic Safety Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Arc Flash Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Remote Breathalyzer Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market