
 Road Flares Market | 2026-2036
Road Flares Market Size, Share, and Industry Trends Forecast 2026-2036
Road Flares Market Analytics
Emergency roadside visibility product revenue is reshaping competitive positioning across the supply base. Grote Industries leverages its automotive lighting heritage to dominate electronic flare development for commercial fleets. Orion Safety Products anchors its position through deep relationships with government procurement channels. Cyalume Technologies specializes in chemical illumination chemistry, sustaining relevance in military and tactical overflow segments.
Road flares are pyrotechnic or electroluminescent devices designed to emit high-intensity visible light, typically producing 70–150 candela for chemical variants and 100–300 lumens for LED units, primarily to warn oncoming traffic of stationary hazards or emergency scenes. LED flares now capture the fastest expansion pool as lithium battery costs decline and departments face pressure to eliminate perchlorate soil contamination. Chemical flares retain stubborn share in cold-climate jurisdictions where battery performance degrades, while towing services represent a concentrated margin segment due to high replacement frequency and roadside immediacy.
OSHA workplace safety mandates, EPA perchlorate groundwater monitoring rules, and DOT Federal Highway Administration work zone standards collectively dictate product compliance thresholds and procurement specifications. The EPA's emerging restrictions on perchlorate discharge are accelerating municipal fleet transitions toward rechargeable electronic alternatives. Stakeholders must monitor pending state-level bans on single-use chemical flares to anticipate inventory obsolescence risks and retool manufacturing lines ahead of enforcement timelines.
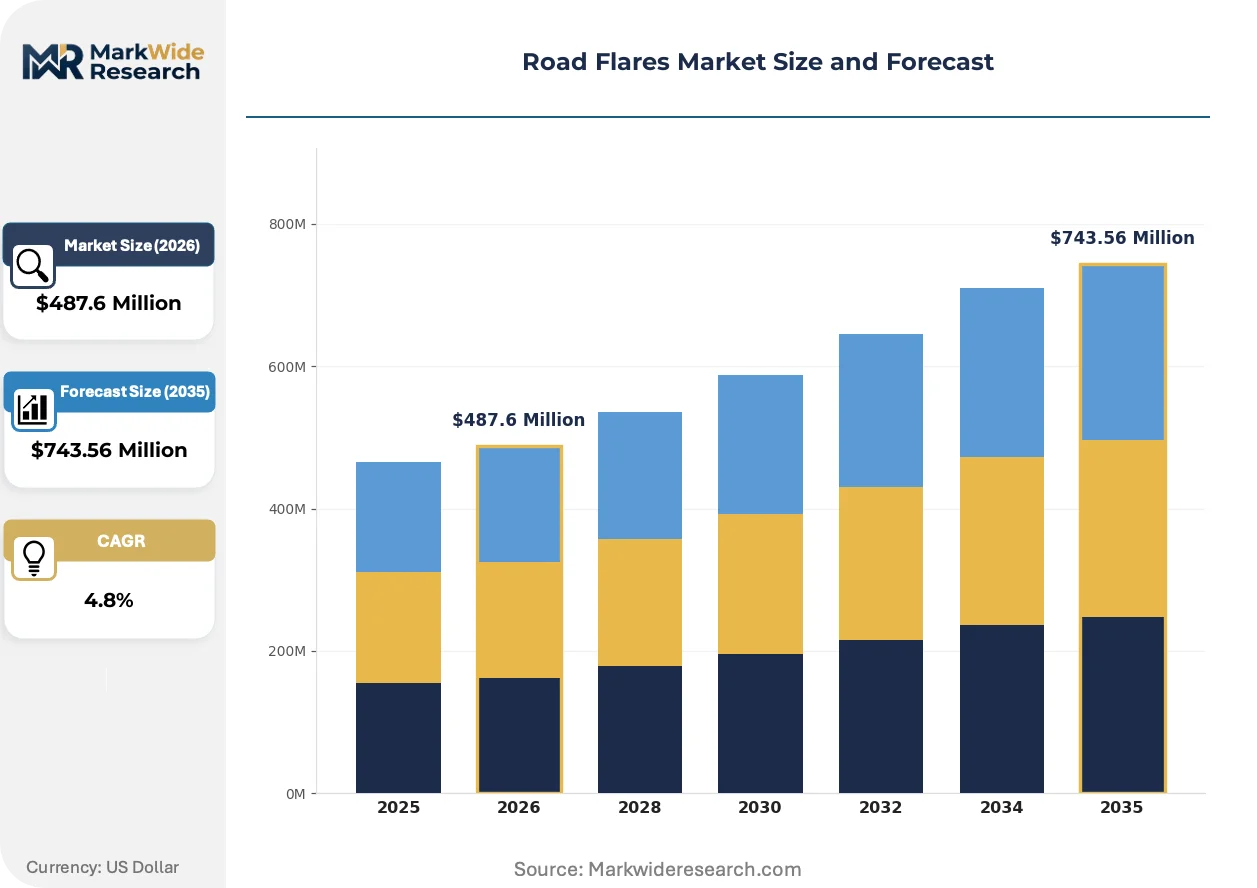
Market Dynamics
The EPA's emerging restrictions on perchlorate discharge are forcing municipal fleet transitions toward rechargeable electronic alternatives, reshaping procurement specifications and manufacturing priorities across the supply base.
Growth Catalysts
- NFPA 1901 Visibility Standards:State transportation departments across the United States are mandating electronic LED alternatives to traditional magnesium perchlorate flares, creating immediate replacement demand.
- Sun Belt Highway Construction:Year-round infrastructure projects in Arizona, Texas, and Florida accelerate flare consumption rates due to extreme heat conditions and continuous work zones.
- Lithium Battery Cost Decline:Falling battery prices are eliminating the cost premium for LED units, enabling broader adoption by budget-constrained municipal fleets.
Market Restraints
- Battery Performance Degradation:Cold-climate jurisdictions in Minnesota and North Dakota retain chemical flare share due to lithium-ion capacity loss below freezing temperatures.
- Perchlorate Inventory Stranding:Municipalities face write-down risks on existing chemical flare stockpiles as state-level bans advance through legislative committees.
- Specialized Disposal Infrastructure:Chemical flare end-of-life handling requires hazardous waste certification that many rural departments lack access to.
Strategic Opportunities
- Smart Fleet Integration:Telematics-enabled flares with GPS tracking and remote activation are penetrating commercial towing operator segments seeking dispatch coordination.
- Solar Recharging Docks:Highway maintenance depots in California and Nevada are piloting solar-powered charging stations for electronic flare inventories.
- OSHA Work Zone Mandates:Expanding federal safety requirements for temporary traffic control devices are widening the addressable market beyond traditional emergency services.
Industry Challenges
- NFPA Certification Timelines:Electronic flare manufacturers face 18-24 month approval cycles for new product variants, delaying revenue recognition on R&D investments.
- Legacy Equipment Interoperability:Departments with mixed chemical and electronic inventories struggle with standardized training protocols and storage segregation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Flares Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Flares, Electronic Flares, LED Flares, Signal Flares Application: Road Safety, Emergency Services, Construction Sites, Towing Services End User: Government Agencies, Transport Companies, Automotive Sector, Individual Consumers Distribution Channel: Online Retail, Distributors, Direct Sales, Specialty Stores |
| Companies Covered | Aervoe Industries, MF Optoelectronics, Grote Industries, Cortina, Cyalume Technologies, Wagan Tech, Orion Safety Products, Buyers Products, OSRAM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Flares Market Evolving Landscape
Active virtualization of illumination hardware, tightening environmental compliance frameworks, and compressed replacement cycles are redefining how roadside visibility products are specified, procured, and deployed.
LED-based electronic flares are virtualizing the traditional chemical illumination stack by replacing pyrotechnic chemistry with programmable solid-state arrays. State DOT procurement offices are adopting these units at accelerating pace for highway maintenance contracts. The technology is virtualizing inventory management by enabling reusable asset tracking rather than single-use consumption models.
REACH restrictions on perchlorate precursors are extending from European chemical manufacturing into supply chain due diligence requirements for US importers. Industrial consequence includes mandatory substance disclosure documentation for any flare containing magnesium perchlorate. Municipal procurement departments in coastal states are responding by pre-emptively excluding chemical alternatives from RFP eligibility.
Fleet managers are consolidating supplier relationships from fragmented local distributors toward direct manufacturer contracts with volume-based pricing and technical service bundling. This channel compression displaces traditional safety equipment wholesalers who lack electronic product support capabilities. The shift is most visible in California and Texas where large municipal fleet sizes justify dedicated vendor management resources.
Road Flares Market Segmentation
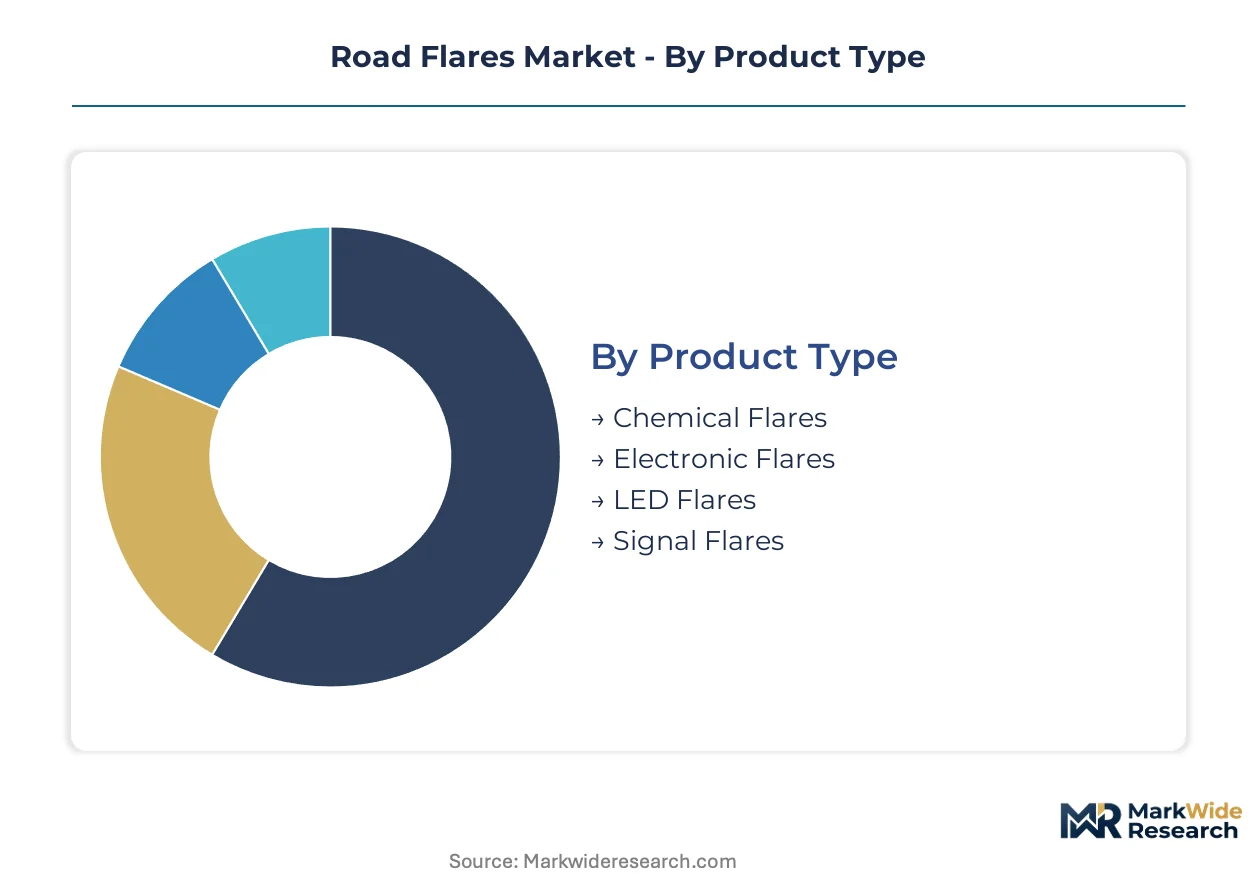
Road flare procurement patterns diverge sharply across user types and deployment contexts. Product specifications, regulatory compliance tiers, and replacement cycles vary significantly between highway maintenance fleets and individual emergency preparedness buyers.
Product Type:
Mature pyrotechnic chemistry coexists with emerging solid-state alternatives as municipalities navigate environmental compliance timelines.
- Electronic Flares:Rechargeable lithium-powered units delivering 100-300 lumens through programmable LED arrays. State DOTs in Arizona and Texas are standardizing procurement around these units to meet EPA perchlorate discharge restrictions while reducing single-use inventory costs.
- Chemical Flares:Magnesium perchlorate formulations generating 70-150 candela through sustained combustion. Cold-climate jurisdictions in Minnesota and North Dakota retain these for sub-zero reliability where lithium-ion capacity degrades.
- LED Flares:Battery-operated solid-state devices with magnetic mounting and sequential flash patterns. Towing operators favor these for roadside durability and immediate redeployment capability.
- Signal Flares:Compact pyrotechnic projectiles designed for aerial visibility in remote terrain. Forestry services and search-and-rescue units maintain stockpiles for backcountry emergency signaling.
Electronic Flares handles the majority of throughput; LED Flares is the fastest mover on share.
Application:
Volume concentrates in infrastructure maintenance while margin pools in immediate-response services.
- Road Safety:Highway work zone illumination meeting FHWA temporary traffic control standards. Continuous Sun Belt construction cycles in Florida and Texas drive replacement frequency.
- Towing Services:Rapid-deployment visibility for roadside assistance operators. High replacement rates and emergency immediacy support premium pricing.
- Emergency Services:Fire and ambulance fleet readiness for incident scene perimeter marking. NFPA 1901 visibility mandates shape procurement specifications.
- Construction Sites:OSHA work zone compliance for private infrastructure contractors. Expanding federal safety requirements widen addressable market beyond public agencies.
Road Safety commands the volume base; Towing Services captures the steepest margin expansion.
End User:
Procurement sophistication separates institutional buyers from discretionary purchasers.
- Government Agencies:State transportation departments and municipal fleets operating under federal compliance frameworks. EPA perchlorate monitoring rules accelerate transition timelines.
- Transport Companies:Commercial trucking and logistics fleets managing driver safety protocols. Telematics integration is penetrating this segment for dispatch coordination.
- Automotive Sector:Vehicle manufacturers and aftermarket suppliers bundling emergency kits. OEM specifications increasingly exclude chemical alternatives.
- Individual Consumers:Personal emergency preparedness and recreational vehicle owners. Price sensitivity dominates with minimal regulatory pressure.
Government Agencies anchor procurement volume; Transport Companies are expanding most quickly on fleet standardization.
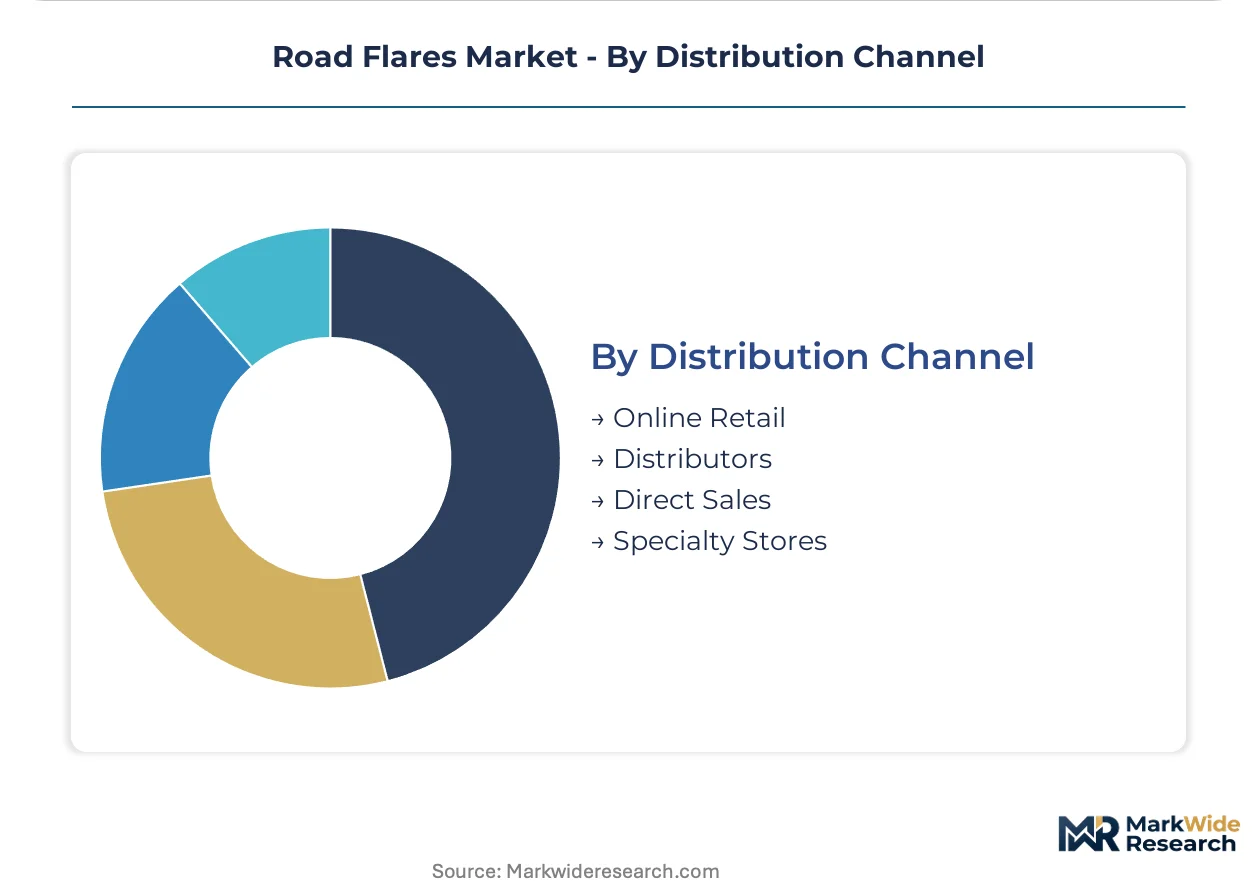
Distribution Channel:
Channel compression is displacing fragmented local supply relationships.
- Direct Sales:Manufacturer contracts with volume pricing and technical service bundling. Large municipal fleets in California justify dedicated vendor management resources.
- Distributors:Traditional safety equipment wholesalers facing displacement where electronic product support capabilities are lacking.
- Online Retail:E-commerce platforms serving individual consumers and small fleet operators. Product comparison transparency pressures pricing.
- Specialty Stores:Regional automotive and emergency equipment retailers. Inventory depth constraints limit electronic flare assortment.
Direct Sales captures the institutional procurement shift; Online Retail is climbing the fastest on consumer segment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between jurisdictions with year-round highway construction cycles and those facing extreme cold where battery chemistry falters. Sun Belt states deploy flares at triple the per-mile rate of northern counterparts, while EPA enforcement intensity separates early electronic adopters from lagging chemical holdouts.
United States
State transportation departments in Arizona, Texas, and Florida drive replacement volume through continuous work zone activity. EPA perchlorate groundwater monitoring rules under the Safe Drinking Water Act accelerate municipal fleet transitions toward rechargeable alternatives. Los Angeles County operates North America's largest electronic flare deployment, with over 12,000 units across highway maintenance divisions.
Canada
Provincial transportation ministries in Alberta and Saskatchewan balance cold-climate reliability needs against federal environmental directives. Health Canada's PMRA regulates chemical flare importation through pesticide-like substance controls. Calgary's municipal fleet maintains hybrid inventories, deploying chemical units only when temperatures drop below minus 20 Celsius.
Germany
Autobahn maintenance authorities prioritize high-visibility LED systems for nighttime construction zones along high-speed corridors. ECHA REACH restrictions on perchlorate precursors extend into supply chain due diligence for imported safety equipment. Bavaria's highway police standardize procurement through centralized state purchasing cooperatives.
China
Ministry of Transport directives mandate upgraded temporary traffic control devices for expressway expansion projects across the Yangtze River Delta. NMPA-equivalent standards for hazardous chemical handling tighten manufacturing compliance for pyrotechnic flare producers. Shenzhen's smart highway pilots integrate GPS-enabled electronic flares into connected infrastructure systems.
Australia
State road authorities in Queensland and Western Australia face extreme heat and remote deployment distances that favor durable electronic alternatives. Infrastructure Australia funding programs require environmental impact assessments that disadvantage chemical perchlorate products. Perth's mining corridor maintenance fleets operate solar recharging depots for remote electronic flare inventories.
Road Flares Market Competitive Landscape
Capability concentration sits with specialized lighting and safety equipment manufacturers; scale advantage sits with diversified industrial conglomerates serving broader transportation infrastructure markets. The supply base organizes into three tiers: automotive heritage specialists with LED engineering depth, government procurement incumbents with certification relationships, and chemical illumination chemists defending tactical overflow segments. Consolidation pressure favors direct manufacturer contracts over fragmented distribution. Capacity expansion concentrates in rechargeable electronic assembly. Strategic partnerships link flare producers with telematics platform providers.
Within the automotive lighting heritage tier, Grote Industries exemplifies capability concentration through its commercial fleet focus. Orion Safety Products anchors government procurement channel relationships. Cyalume Technologies occupies the chemical specialization position for military and tactical applications. These three represent distinct competitive archetypes rather than direct substitutes, each commanding different specification authority across end-use segments.
| Leading Market Players |
|---|
| Aervoe Industries |
| MF Optoelectronics |
| Grote Industries |
| Cortina |
| Cyalume Technologies |
| Wagan Tech |
| Orion Safety Products |
| Buyers Products |
| OSRAM |
| Others |
Value Network & Pricing Analysis
EPA perchlorate discharge restrictions determine both the three-tier pricing structure across premium, standard, and economy certification levels and the geographic reconfiguration of component sourcing. Municipal procurement offices now face compressed margins on legacy chemical inventories while lithium battery cost curves reshape electronic flare affordability thresholds.
Pricing Analysis
Long-term municipal offtake contracts dominate institutional procurement, with state DOTs negotiating volume-based pricing for NFPA 1901 certified electronic units. Price differentiation separates UL-certified premium tiers from economy-grade alternatives lacking telematics integration. Cost compression in the standard tier intensifies as Chinese battery cell manufacturers expand capacity. Individual consumers exhibit highest price sensitivity, while commercial towing operators accept premium positioning for immediate roadside reliability.
Supply Chain Analysis
Lithium carbonate feedstock draws from Chilean and Australian mining operations, with Chinese cell manufacturing commanding downstream assembly. Magnesium perchlorate chemical inputs rest on domestic US specialty chemical producers facing EPA production quota constraints. Single-source vulnerability concentrates in lithium refining capacity, where Chinese processors control majority global throughput. Distribution runs through direct manufacturer contracts for institutional buyers, supplemented by regional safety equipment distributors serving fragmented municipal fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Road flares sit at early-cycle expansion as EPA enforcement timelines accelerate fleet replacement velocity beyond historical replacement rates.
For Market Incumbents: Harden certification moats by accelerating NFPA 1901 pre-approval investments ahead of state-level chemical flare bans. Secure backward integration into lithium battery pack assembly to defend margin position against commodity cell volatility. Channel control through direct municipal contracts displaces distributor intermediaries lacking electronic product technical support capabilities. For New Entrants and Emerging Players: Cold-climate jurisdictions in Minnesota and North Dakota represent the most penetrable entry point for hybrid chemical-electronic offerings addressing lithium-ion capacity degradation below freezing. Telematics-enabled flares with GPS tracking and remote activation offer differentiated positioning for commercial towing operator segments seeking dispatch coordination integration. For Investors and Strategic Acquirers: Pending state-level perchlorate discharge prohibitions reshape the acquisition landscape toward electronic flare specialists with established NFPA certification relationships. Five-to-ten year viability favors manufacturers with rechargeable assembly capacity and municipal procurement channel access. Monitor California and Texas legislative committee advance dates as inflection indicators for inventory obsolescence velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NFPA Certification Acceleration | Pre-approval investments capture replacement demand ahead of state chemical flare bans. |
| Lithium Battery Backward Integration | In-house pack assembly insulates margin from Chinese cell commodity price swings. |
| Telematics Platform Partnership | GPS-enabled flare integration penetrates commercial towing dispatch coordination segments. |
| Solar Recharging Infrastructure | Highway depot pilots in Nevada and California reduce field deployment operational costs. |
| Direct Municipal Contracting | Volume pricing with technical service bundling displaces fragmented distributor relationships. |
Research Methodology
A standing panel of state DOT procurement officers, municipal fleet managers, commercial towing operators, and NFPA certification engineers provided ongoing calibration against market developments. Primary interviews with safety equipment distributors and lithium battery procurement specialists combined with secondary validation through EPA enforcement action databases, state legislative tracking systems, and FHWA work zone safety filings. Bottom-up unit demand modeling triangulated against top-down municipal budget allocation analysis.
Scenario-bracketing framed volume projections across the analysis window, with segmentation dimensions spanning product type, application context, end-user procurement sophistication, and distribution channel structure. CAGRs derived from replacement cycle compression analysis and regulatory transition timeline probability weighting. Industry-specific inputs included lithium battery cost curve trajectories and perchlorate discharge restriction enforcement probability assessments.
Practitioners should monitor state legislative committee vote schedules and EPA Safe Drinking Water Act enforcement actions for early signals of forecast revision triggers. Forecasts reflect assumptions around lithium battery performance reliability in extreme temperature conditions and municipal budget continuity for fleet replacement programs. Material shifts in federal infrastructure spending allocation or breakthrough solid-state battery commercialization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safety and Eyewash Shower Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Functional Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market