
 Global Anti-Vibration Gloves Market | 2026-2036
Global Anti-Vibration Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Vibration Gloves Market Foresight
Buyer concentration among heavy machinery operators is consolidating as fleet operators standardize procurement across national construction contracts. Ansell leverages its chemical-resistant portfolio to cross-sell vibration-dampening lines into mining procurement frameworks. Superior Glove anchors Canadian forestry supply chains through direct distributor relationships with provincial equipment lessors. Ergodyne differentiates via gel-palm engineering targeted at maintenance technicians in wind-energy servicing.
Anti-vibration gloves incorporate viscoelastic polymer layers, typically chloroprene or nitrile-butadiene rubber composites, engineered to attenuate frequencies between 8 and 1000 Hz transmitted through powered hand tools. Their primary purpose is reducing hand-arm vibration syndrome incidence among workers operating jackhammers, chainsaws, and angle grinders for sustained shifts. Nitrile-coated products lead volume due to oil resistance and dexterity retention in metal fabrication environments, while leather variants sustain premium positioning in welding-adjacent construction tasks. Neoprene segments compete on thermal stability for cold-climate forestry applications across Nordic supply chains.
OSHA enforces permissible exposure limits for hand-arm vibration under 29 CFR 1910.95 general duty clause interpretations, compelling construction contractors to document glove deployment in tool-time audits. The EU Machinery Directive 2006/42/EC mandates vibration emission declarations, pushing German and Italian OEMs to bundle certified hand protection with new equipment sales. Japan's Ministry of Health, Labour and Welfare maintains JIS T 8116 standards that classify glove damping performance by frequency band, creating tiered product acceptance thresholds. Stakeholders must monitor whether emerging battery-powered tool platforms alter vibration signatures sufficiently to obsolete current glove certification categories.
Market Dynamics
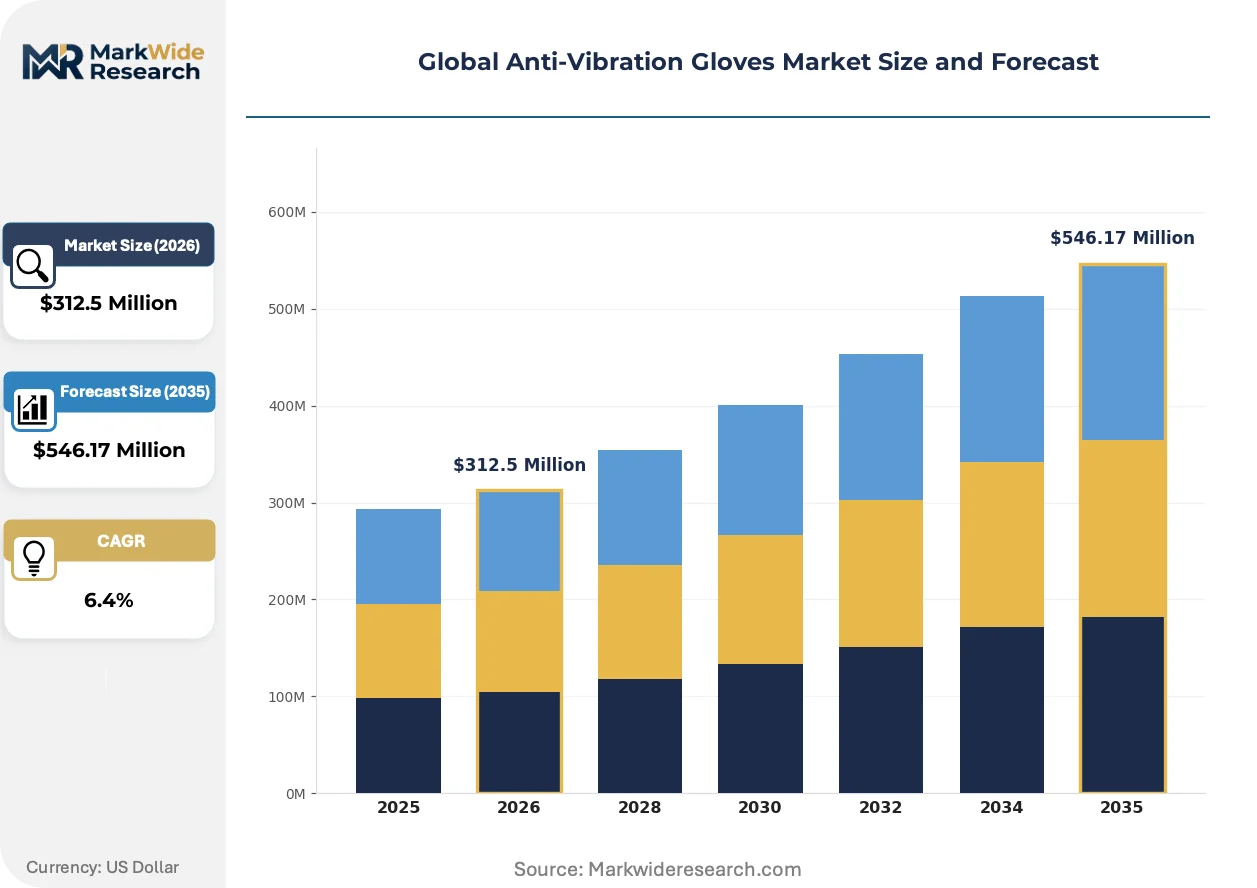
OSHA hand-arm vibration enforcement is compressing contractor compliance timelines, forcing construction fleet operators to standardize certified glove procurement across multi-state equipment contracts rather than site-by-site purchasing.
Growth Catalysts
- 29 CFR 1910.95 general duty clause:US construction contractors face escalating inspection frequency, mandating documented vibration control measures for jackhammer and compactor operators. This regulatory pressure converts reactive glove purchases into systematic procurement programs.
- EU Machinery Directive 2006/42/EC:German and Italian OEMs now bundle certified hand protection with new angle grinder and demolition equipment sales, embedding gloves into capital expenditure workflows rather than aftermarket replacement cycles.
- Battery-powered tool platforms:Altered vibration signatures from cordless rotary hammers and chainsaws require recalibrated damping materials, creating replacement demand for glove portfolios optimized to emerging frequency profiles.
Market Restraints
- Chloroprene feedstock concentration:Viscoelastic polymer supply clusters in East Asian petrochemical corridors, exposing manufacturers to freight cost volatility and tariff friction on nitrile-butadiene rubber composites.
- JIS T 8116 frequency-band classification:Japan's tiered damping performance thresholds fragment product acceptance criteria, forcing suppliers to maintain multiple certification streams for equivalent glove constructions.
- Anti-vibration tool mounts:Spring-dampened handles and active isolation systems on premium breakers substitute partial glove functionality, capping price ceilings for palm-dampening products in high-specification mining procurement.
Strategic Opportunities
- Wind-energy servicing technicians:Turbine maintenance crews in Denmark and Spain operate angle grinders at height for extended durations, creating demand for gel-palm engineering with tether compatibility and cut resistance.
- India's construction labor formalization:Infrastructure project scale-up under central government employment codes exposes unprotected workers to hand-arm vibration syndrome, opening volume markets for entry-certified nitrile-coated variants.
- CE marking harmonization with ISO 10819:Converging European and international mechanical vibration standards simplifies cross-border certification, reducing time-to-market for suppliers targeting multi-jurisdictional fleet operators.
Industry Challenges
- ISO 10819 frequency-specific testing capacity:Third-party laboratories with 8-1000 Hz vibration table certification face 12-16 week queue times, delaying product launches and contract qualification cycles.
- Gel-polymer formulation expertise:Viscoelastic layer engineering for thermal stability in Nordic forestry applications requires polymer science specialization scarce among traditional leather-glove manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Vibration Gloves Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrile Coated, Leather, Neoprene, Rubber, Foam, PVC Application: Construction, Metal Fabrication, Forestry, Mining, Manufacturing, Maintenance End User: Heavy Machinery Operators, Power Tool Users, Assembly Line Workers, Maintenance Technicians, Equipment Inspectors Distribution Channel: Specialty Stores, Online Retailers, Industrial Suppliers, Direct Sales, Safety Equipment Distributors |
| Companies Covered | Ansell, Garmor, Ergodyne, 3M, SHOWA GROUP, Superior Glove, Protective Industrial Products, Youngstown Glove, HexArmor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Vibration Gloves Market Shifts & Advancements
Material science convergence with connected worker platforms is redefining how damping performance gets validated and procured, shifting competitive advantage from chemical formulation to real-time exposure monitoring integration.
Shear-thickening gel composites embedded between nitrile palm coatings and knit liners are automating frequency-specific attenuation adjustments based on tool vibration intensity. Mining contractors in Western Australia deploy these adaptive layers in 24-hour continuous operations, reducing the inventory burden of maintaining multiple glove grades for varying equipment types. This material intelligence is compressing the traditional trade-off between damping performance and manual dexterity.
REACH Annex XVII restrictions on N-nitrosamines in rubber processing chemicals are forcing reformulation of chloroprene-based damping layers across European supply chains. Compounders must substitute alternative vulcanization accelerators without degrading viscoelastic properties across the 31.5-125 Hz band critical for rotary hammer protection. German automotive supplier spillover is accelerating this transition, leveraging existing nitrosamine-free process knowledge from seal manufacturing.
Consolidated fleet procurement through national equipment lessors is displacing distributor-led spot purchasing in Canadian forestry and US pipeline construction. Buyers now specify certified glove inclusion in multi-year operator rental agreements, converting product selection authority from site supervisors to centralized safety compliance officers. This concentration is most visible in Alberta oil sands operations and British Columbia coastal logging tenures.
Global Anti-Vibration Gloves Market Segmentation
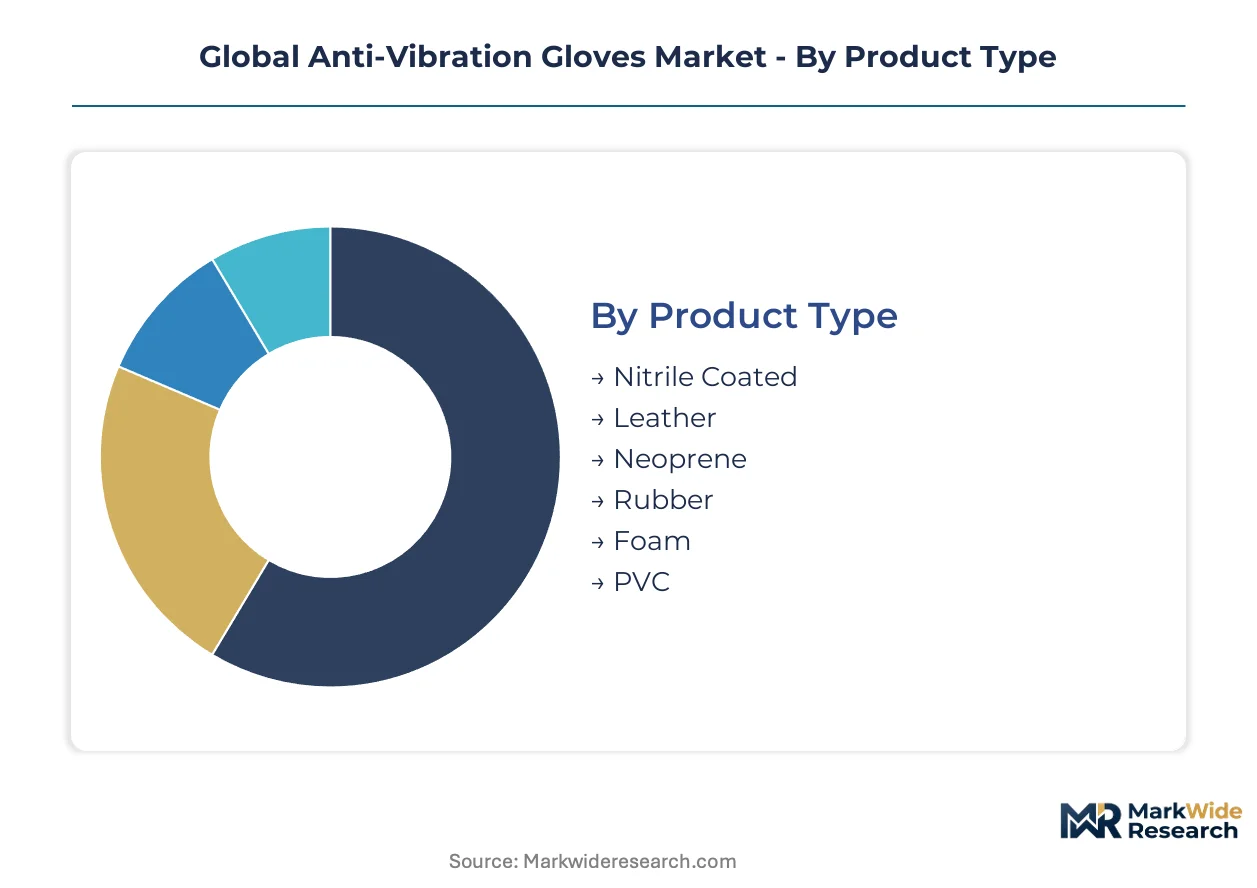
Material composition determines damping performance across frequency bands, while procurement channel consolidation is shifting purchase authority from site supervisors to centralized safety officers. Application-specific vibration signatures—rotary hammers versus chainsaws versus angle grinders—demand calibrated polymer formulations that trade dexterity against attenuation.
Product Type:
Buyers select coating chemistry based on oil exposure, thermal range, and tactile precision requirements for specific tool interfaces.
- Nitrile Coated:Nitrile-butadiene rubber composites deliver oil resistance and frequency attenuation optimized for metal fabrication environments. German precision engineering shops and Japanese automotive stamping plants specify these variants for rotary hammer and angle grinder operations where chemical exposure coexists with vibration hazard.
- Leather:Full-grain cowhide and goatskin constructions with integrated viscoelastic layers sustain premium positioning in welding-adjacent construction tasks. US pipeline contractors and Canadian oil sands operators accept reduced damping performance for spark resistance and seam durability in high-heat fabrication.
- Neoprene:Chloroprene-based damping layers compete on thermal stability for Nordic forestry applications.
- Rubber:Natural and synthetic rubber blends serve general-purpose maintenance with cost-sensitive procurement profiles.
- Foam:Open-cell polyurethane inserts target entry-level construction markets with disposable replacement cycles.
- PVC:Polyvinyl chloride coatings address chemical processing environments with limited vibration exposure.
Volume sits with nitrile formulations; growth tilts toward shear-thickening gel composites that automate frequency-specific adjustments.
Application:
Regulatory enforcement intensity varies sharply by sector, converting compliance pressure into systematic procurement programs versus spot replacement purchasing.
- Construction:OSHA 29 CFR 1910.95 enforcement compresses contractor compliance timelines, forcing fleet operators to standardize certified glove deployment across multi-state equipment contracts. US infrastructure contractors now document glove inclusion in tool-time audits for jackhammer and compactor operators.
- Metal Fabrication:EU Machinery Directive 2006/42/EC mandates vibration emission declarations, pushing German and Italian OEMs to bundle certified hand protection with new angle grinder sales.
- Forestry:Cold-climate operations in Sweden and Finland demand neoprene thermal stability for chainsaw operators.
- Mining:Western Australian iron ore and copper operations prioritize adaptive gel-palm engineering for 24-hour continuous use.
- Manufacturing:Assembly-line stamping and pressing operations in South Korea and Mexico drive volume for nitrile-coated variants.
- Maintenance:Wind turbine technicians in Denmark and Spain require tether-compatible designs with cut resistance for height work.
Construction commands current procurement volume; wind-energy maintenance is climbing the fastest as offshore installation scales.
End User:
Job function determines exposure duration, tool variety, and dexterity requirements that segment product specification authority.
- Heavy Machinery Operators:Fleet standardization across national construction contracts consolidates demand for certified multi-tool compatibility.
- Power Tool Users:Carpentry and mechanical trades prioritize tactile feedback retention in palm-dampening designs.
- Assembly Line Workers:High-frequency repetitive exposure in automotive stamping plants drives replacement volume for disposable-grade foam variants.
- Maintenance Technicians:Gel-palm engineering with tether compatibility addresses turbine servicing at height in North Sea and Iberian wind farms.
- Equipment Inspectors:Intermittent exposure patterns favor lightweight neoprene solutions with quick-don characteristics.
Heavy machinery operators anchor current volume; maintenance technicians are gaining share fastest as renewable infrastructure expands.
Distribution Channel:
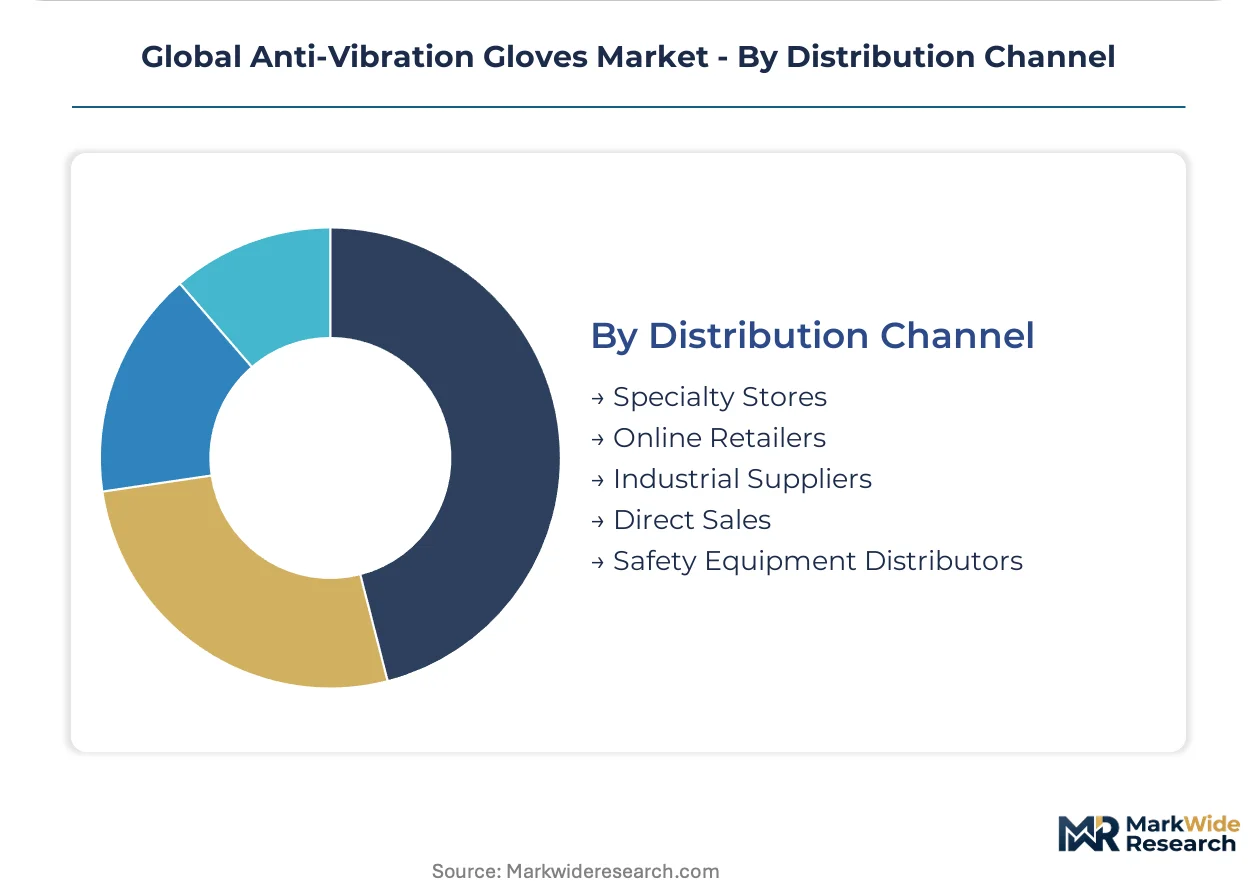
Channel selection reflects procurement centralization versus site-level autonomy in safety equipment acquisition.
- Specialty Stores:Independent safety suppliers serve smaller contractors with immediate replacement needs and limited inventory carrying capacity.
- Online Retailers:E-commerce penetration accelerates for standardized nitrile-coated SKUs with established certification credentials.
- Industrial Suppliers:Integrated MRO distributors capture multi-category procurement consolidation among manufacturing end users.
- Direct Sales:National equipment lessors in Alberta oil sands and British Columbia coastal logging now specify certified glove inclusion in multi-year operator rental agreements.
- Safety Equipment Distributors:Regional networks maintain JIS T 8116 certification inventory for Japanese metal fabrication compliance.
Industrial suppliers hold current volume; direct sales through equipment lessors are expanding most quickly as fleet procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy machinery operators in the United States drive the largest procurement volume, while German precision engineering and Japanese automotive stamping sustain premium-tier demand for certified damping performance.
United States
Construction fleet operators across Texas, California, and Florida consolidate glove procurement under multi-state equipment rental agreements. OSHA 29 CFR 1910.95 enforcement compresses compliance timelines for jackhammer and compactor crews. The Permian Basin oil patch and Gulf Coast petrochemical corridor anchor demand for chemical-resistant nitrile variants.
Germany
Metal fabrication shops in Stuttgart and Munich specify frequency-calibrated gloves for rotary hammer and angle grinder operations. EU Machinery Directive 2006/42/EC mandates vibration emission declarations, pushing OEMs to bundle certified hand protection with new equipment sales. Baden-Württemberg's automotive supplier network sustains premium-tier procurement.
Japan
Automotive stamping plants in Toyota City and Yokohama demand JIS T 8116-certified damping performance across multiple frequency bands. The Ministry of Health, Labour and Welfare maintains tiered classification thresholds that fragment product acceptance criteria. Chubu region precision engineering clusters concentrate nitrile-coated volume.
Canada
Forestry contractors in British Columbia and oil sands operators in Alberta standardize procurement through provincial equipment lessors. Direct distributor relationships with national rental chains displace site-level spot purchasing. Cold-climate neoprene variants compete for chainsaw operator share across Nordic-influenced supply chains.
Australia
Western Australian iron ore and copper operations prioritize adaptive gel-palm engineering for 24-hour continuous use. Mining contractors in the Pilbara region deploy shear-thickening composites to reduce inventory burdens across varying equipment types. Perth-based procurement offices coordinate Pacific Rim supply agreements.
Global Anti-Vibration Gloves Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connected-worker integration and adaptive material platforms. The vendor base clusters around three archetypes: diversified industrial safety conglomerates with cross-category chemical resistance portfolios, specialized glove fabricators with direct forestry and mining distributor relationships, and material-science-driven innovators engineering frequency-specific damping layers. Consolidation pressures favor M&A activity among mid-tier European compounders, while capacity expansion concentrates in East Asian nitrile-butadiene rubber corridors.
Within the diversified safety conglomerate tier, Ansell and 3M exemplify portfolio breadth that spans chemical-resistant lines into vibration-dampening procurement frameworks. Among specialized fabricators, Superior Glove anchors Canadian forestry supply chains through direct relationships with provincial equipment lessors. Ergodyne represents the material-science vector, occupying a position defined by gel-palm engineering targeted at maintenance technicians in wind-energy servicing.
| Leading Market Players |
|---|
| Ansell |
| Garmor |
| Ergodyne |
| 3M |
| SHOWA GROUP |
| Superior Glove |
| Protective Industrial Products |
| Youngstown Glove |
| HexArmor |
| Others |
Supply & Pricing Matrix
Chloroprene and nitrile-butadiene rubber composite feedstock costs cascade through three distinct pricing tiers, with East Asian petrochemical corridor concentration compressing margins on standard-grade nitrile-coated variants while German and Japanese certification premiums sustain elevated price floors for frequency-calibrated JIS T 8116 and ISO 10819-compliant products.
Pricing Analysis
Volume concentrates in transactional per-unit sales of nitrile-coated standard grades to construction contractors, while margins accrue to certified premium tiers where ISO 10819 and JIS T 8116 frequency-band testing creates differentiation. Price stratification separates oil-resistant nitrile formulations from thermal-stable neoprene and spark-resistant leather variants. Cost compression in entry-level foam segments intensifies as Indian construction labor formalization drives demand for disposable replacement cycles. Fleet operators consolidating procurement through national equipment lessors exhibit lowest price sensitivity, whereas spot-purchasing specialty store buyers in fragmented maintenance trades resist premium positioning.
Supply Chain Analysis
Freight cost volatility on nitrile-butadiene rubber composites shipped from South Korean and Chinese petrochemical hubs exposes manufacturers to margin erosion, particularly for North American construction glove assemblers. Raw material sourcing draws from chloroprene producers in Japan and Thailand alongside nitrile-butadiene rubber compounders in China and South Korea. Tariff friction on East Asian rubber imports constitutes the primary structural risk. Distribution runs through industrial MRO distributors and direct sales channels with national equipment lessors, displacing traditional safety equipment distributor networks in Canadian forestry and US pipeline construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shear-thickening gel composites are displacing static viscoelastic polymer layers, compressing the traditional trade-off between damping performance and manual dexterity while forcing portfolio recalibration across incumbent and entrant positioning.
For Market Incumbents: Anchor certification investment in ISO 10819 and JIS T 8116 frequency-specific testing capacity to defend against adaptive material platforms eroding static polymer market share. Pursue backward integration into chloroprene and nitrile-butadiene rubber compound production to mitigate East Asian feedstock concentration. Control channel relationships with national equipment lessors in Alberta oil sands and British Columbia coastal logging as procurement centralization accelerates. For New Entrants and Emerging Players: National equipment lessors in Canadian forestry and US pipeline construction represent the most penetrable channel partner type, with consolidated fleet procurement displacing distributor-led spot purchasing. Target wind-energy servicing technicians in Denmark and Spain with tether-compatible gel-palm engineering as offshore installation scales. Pursue white-space in India's formalizing construction labor market with entry-certified nitrile-coated variants priced for volume replacement cycles. For Investors and Strategic Acquirers: CE marking harmonization with ISO 10819 standards is the leading indicator that cross-border certification simplification will accelerate M&A activity among mid-tier European compounders. The five-to-ten year viability window favors material-science-driven innovators with frequency-specific damping layer expertise over diversified safety conglomerates dependent on chemical-resistant cross-selling. Monitor queue times at third-party ISO 10819 testing laboratories as the signal for certification bottleneck intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of nitrile-butadiene rubber composites insulates margins from East Asian tariff exposure. |
| ISO 10819 Testing Capacity Expansion | Reduced 12-16 week laboratory queue times accelerate product launches and contract qualification cycles. |
| Equipment Lessor Direct Sales Partnership | Multi-year operator rental agreements convert site-level spot purchasing into systematic procurement programs. |
| Shear-Thickening Gel R&D Investment | Adaptive frequency-specific attenuation automates inventory reduction across varying equipment vibration signatures. |
| Nitrosamine-Free Formulation Transition | REACH Annex XVII compliance leverages German automotive supplier spillover from seal manufacturing process knowledge. |
Research Methodology
Independent corroboration across primary interviews with plant safety officers, fleet procurement managers, polymer compounders, and vibration testing laboratory directors, alongside secondary validation through OSHA enforcement records, EU Machinery Directive implementation reports, JIS T 8116 certification databases, and customs trade data on chloroprene and nitrile-butadiene rubber imports, underwrites the qualitative findings. Bottom-up demand modeling from construction, metal fabrication, forestry, and mining end-use segments triangulates against top-down supply-side capacity assessments across East Asian petrochemical corridors.
Rate-of-change decomposition across the projection horizon segments volume and value by material composition, application sector, end-user job function, and distribution channel. CAGRs derive from tool fleet expansion rates, regulatory enforcement intensity trajectories, and battery-powered platform adoption curves affecting vibration signature profiles. Industry-specific forecast inputs incorporate OSHA inspection frequency trends and EU Machinery Directive bundling mandates.
Caveats apply where battery-powered tool vibration signature shifts could obsolete current glove certification categories, or where REACH Annex XVII reformulation timelines extend beyond compounder adaptation capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Scuba Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Intrinsic Safety Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market