
 Earthing Lightning Protection System Market | 2026-2036
Earthing Lightning Protection System Market Size, Share, and Industry Trends Forecast 2026-2036
Earthing Lightning Protection System Market Analysis
Preventive maintenance subscriptions for surge protection assets is decoupling hardware sales from long-term revenue streams. ABB leverages its electrification software platform to anchor recurring service contracts across European industrial complexes. Eaton Corporation competes through vertical integration into surge arrester manufacturing, while Raycap specializes in telecommunications-specific protection assemblies for tower operators worldwide.
An earthing lightning protection system comprises conductive pathways, grounding electrodes, and surge diversion devices engineered to dissipate atmospheric electrical discharge safely into the earth, typically employing copper-clad steel rods with impedance below 10 ohms and bonding conductors sized per fault-current calculations. Its primary purpose protects structures, equipment, and personnel from thermal damage and electromagnetic interference caused by direct or indirect lightning strikes. Surge arresters within product type segments command premium positioning due to semiconductor-grade component requirements, while telecommunication towers among application categories absorb disproportionate investment as 5G densification proceeds. Hybrid systems across technology segments capture expanding share by combining active early streamer emission with passive Faraday cage principles.
IEC 62305 and NFPA 780 shape product certification requirements and installation protocols, compelling manufacturers to maintain multi-standard testing capabilities. India's CEA mandates earthing specifications for grid-connected renewable installations, redirecting procurement toward certified contractors. Utility providers among end users now specify integrated solutions bundling hardware with remote monitoring diagnostics. Stakeholders must evaluate which regulatory convergence between IEC and national electrical codes will determine acceptable product configurations in priority markets.
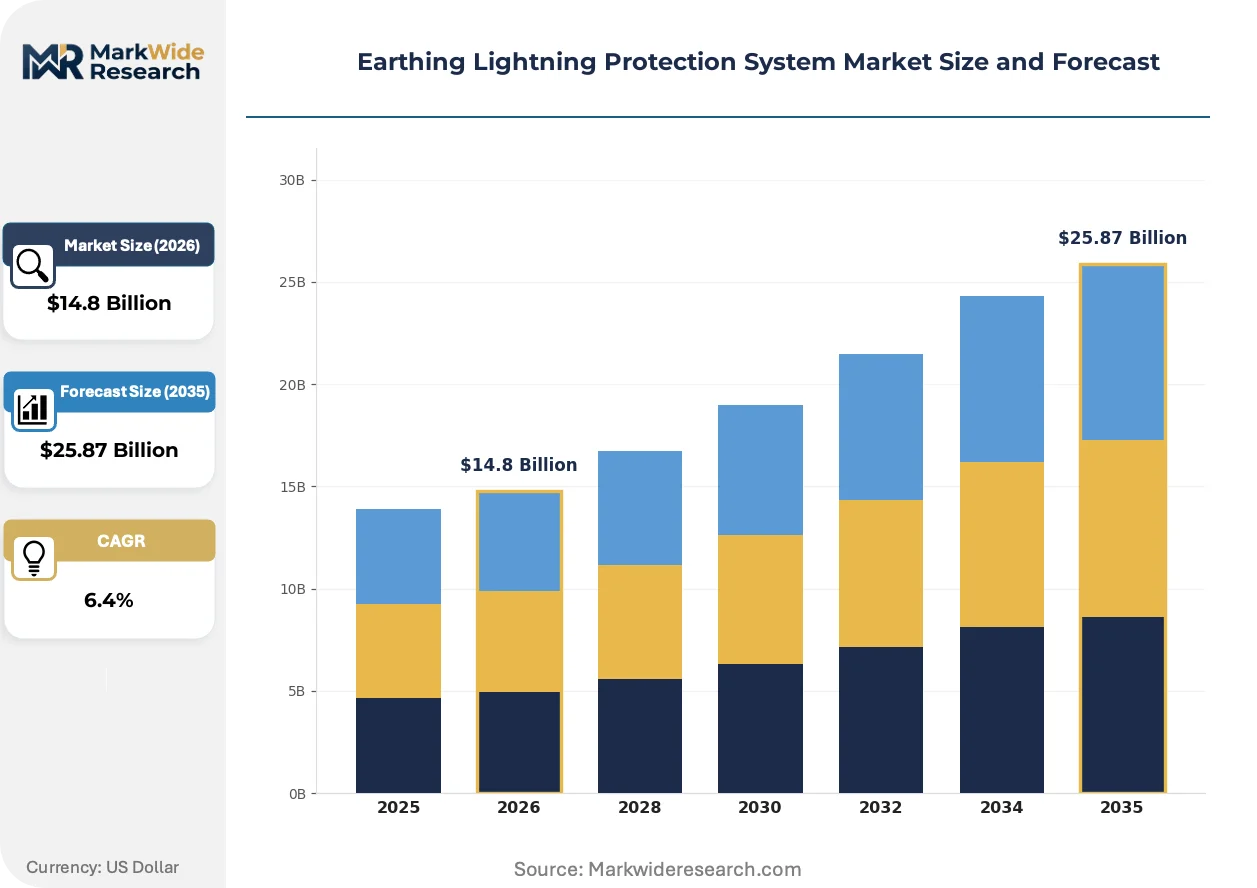
Market Dynamics
Telecommunication tower operators are consolidating procurement around integrated lightning protection bundles that combine hardware with predictive monitoring, compressing vendor margins while locking in decade-long service relationships across 5G infrastructure rollouts.
Growth Catalysts
- IEC 62305 Compliance Mandates:European Union member states enforce lightning protection standards for critical infrastructure, compelling utilities and data centers to upgrade legacy installations with certified surge diversion systems.
- Copper-Bonded Steel Electrode Demand:India's renewable energy sector under CEA mandates drives procurement of low-impedance grounding electrodes for solar farms and wind installations.
- 5G Densification:Tower operators across Brazil and South Africa deploy hybrid protection assemblies combining active early streamer emission with passive Faraday cage principles.
Market Restraints
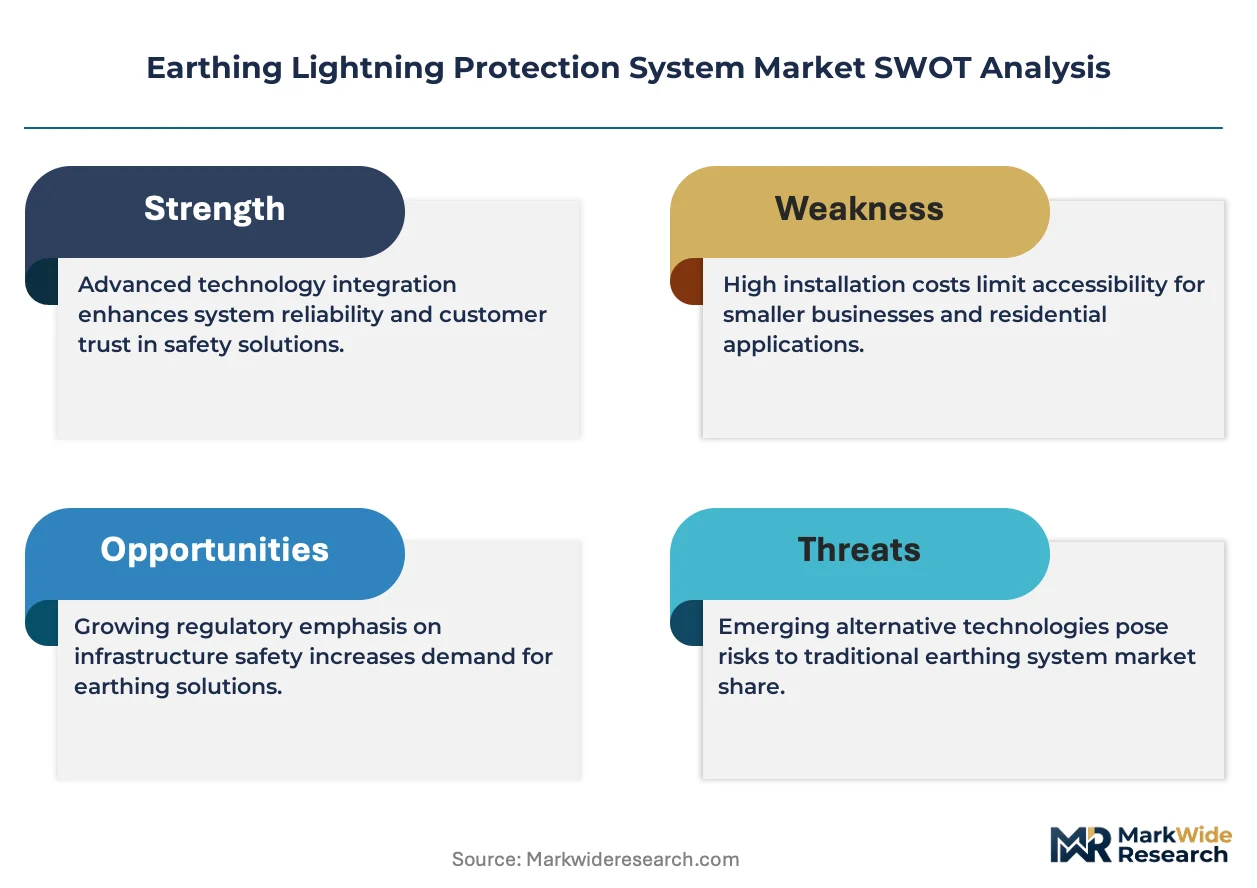
- Copper Price Volatility:Raw material fluctuations in copper-clad steel rod production compress manufacturer margins and destabilize contract pricing for utility-scale projects.
- Installation Skill Concentration:Certified lightning protection engineers cluster in Germany, the United Kingdom, and Japan, creating deployment bottlenecks for emerging market infrastructure.
- Grounding System Longevity:Decades-long replacement cycles for buried electrodes limit recurring revenue potential and elongate payback periods for new market entrants.
Strategic Opportunities
- Remote Monitoring Convergence:Integration of IoT sensors with traditional surge arresters enables predictive maintenance subscriptions, transforming one-time hardware sales into recurring revenue streams for industrial facility managers.
- Data Center Construction Boom:Hyperscale facilities in Singapore and Ireland specify integrated lightning protection with thermal monitoring diagnostics, opening premium positioning for certified contractors.
- CEA Grid-Connected Mandates:India's renewable installation standards redirect procurement toward certified grounding system providers with demonstrated utility-scale track records.
Industry Challenges
- Multi-Standard Testing Infrastructure:Manufacturers must maintain simultaneous IEC 62305, NFPA 780, and national electrical code certification capabilities, straining R&D budgets and elongating product launch timelines.
- Legacy System Integration Complexity:Retrofitting active early streamer emission technology into existing Faraday cage installations requires site-specific engineering and specialized bonding expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthing Lightning Protection System Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grounding Rods, Surge Arresters, Grounding Mats, Bonding Conductors Application: Industrial Facilities, Commercial Buildings, Residential Homes, Telecommunication Towers Technology: Active Systems, Passive Systems, Hybrid Systems, Integrated Solutions End User: Construction Firms, Electrical Contractors, Government Agencies, Utility Providers |
| Companies Covered | Pentair, A.N. Wallis, ABB, Lightning Master Corporation, Fatech Electronic, Raycap, Alltec Corporation, Eaton Corporation, Harger Lightning & Grounding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthing Lightning Protection System Market Emerging Trajectories
Active protection technologies are converging with semiconductor-grade surge components to create intelligent lightning defense systems that self-diagnose and report impedance degradation before failure.
Early streamer emission technology is electrifying competitive positioning in the lightning protection sector. These systems extend the protected zone radius beyond conventional Faraday cage coverage. Telecommunication tower operators in Southeast Asia and the Middle East are adopting hybrid configurations at accelerated pace. The technology is electrifying vendor differentiation strategies by enabling premium pricing for reduced footprint installations in dense urban environments.
India's CEA technical standards for renewable energy earthing are reshaping procurement specifications for grid-connected solar and wind assets. The mandates require documented impedance testing below 10 ohms and bonded conductor sizing per fault-current calculations. Domestic installation contractors must now demonstrate certified compliance to qualify for utility-scale tenders. Renewable project developers are responding by pre-qualifying grounding system providers with established CEA certification records.
Service contract unbundling is fragmenting traditional hardware-plus-installation bundles across European industrial complexes. Facility managers now separately negotiate surge arrester supply, installation labor, and predictive maintenance subscriptions. Channel intermediaries specializing in industrial electrification software are capturing margin previously held by hardware manufacturers. Germany and the Netherlands exhibit the most advanced disaggregation, with remote monitoring diagnostics sold as standalone annual subscriptions independent of initial equipment procurement.
Earthing Lightning Protection System Market Segmentation
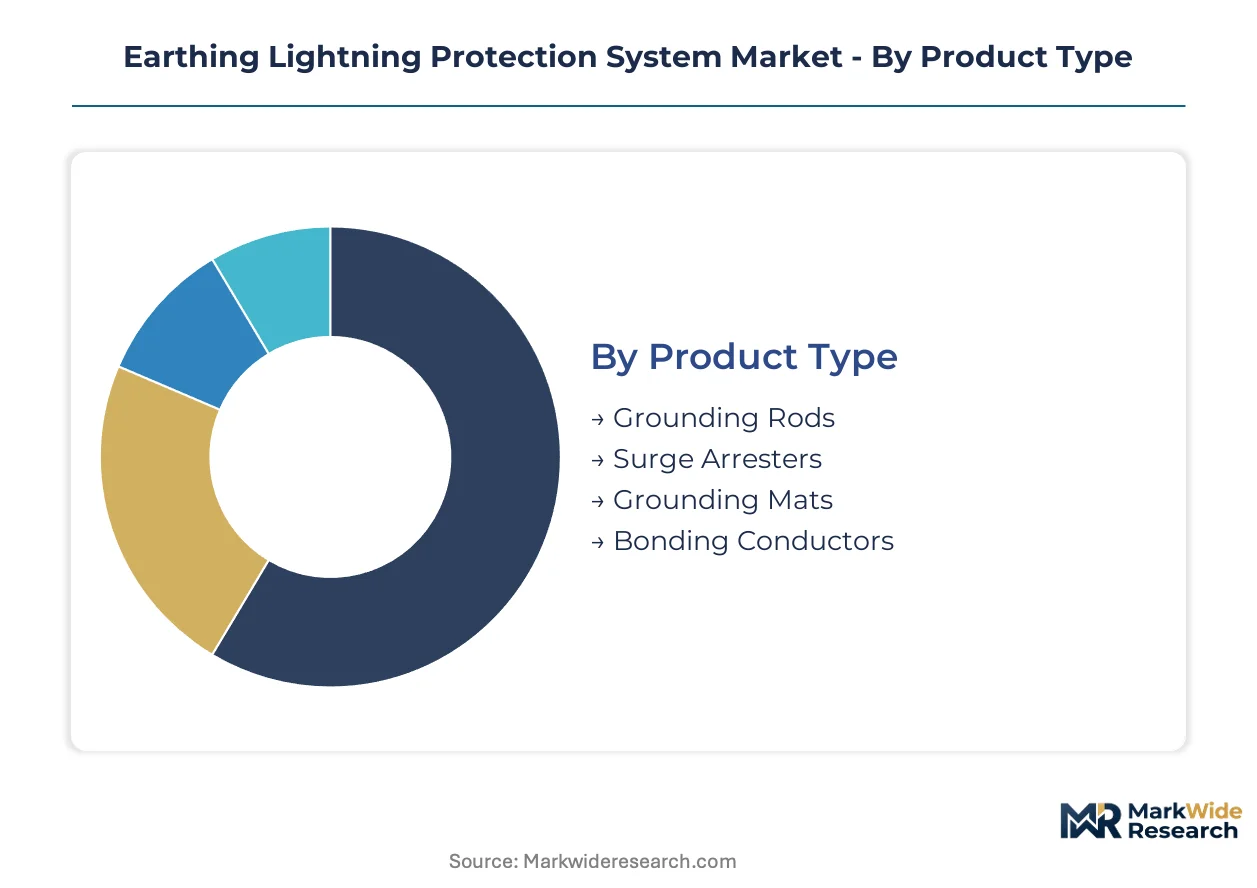
Earthing lightning protection systems fragment across four critical dimensions that determine procurement patterns, installation complexity, and long-term service revenue potential. Each category reveals distinct margin structures and competitive dynamics that shape vendor positioning strategies.
Product Type:
Standalone grounding components dominate utility-scale procurement, while integrated assemblies gain traction in space-constrained urban installations.
- Grounding Rods:Copper-clad steel rods with impedance specifications below 10 ohms form the foundation of renewable energy installations. India's CEA mandates concentrate procurement toward certified contractors supplying utility-scale solar and wind farms with documented compliance records.
- Surge Arresters:Semiconductor-grade metal-oxide varistors command premium positioning due to precision manufacturing requirements. Telecommunication tower operators in Brazil and South Africa specify these for 5G infrastructure densification, bundling hardware with predictive monitoring subscriptions.
- Grounding Mats:Mesh configurations protect substations and data centers with uniform potential distribution.
- Bonding Conductors:Sized per fault-current calculations, these interconnect protection elements across facility perimeters.
Grounding rods lead volumes today; surge arresters are gaining share fastest.
Application:
Cost tier separation emerges sharply across installation scales, with industrial facilities absorbing premium solutions and residential segments competing on contractor labor efficiency.
- Industrial Facilities:Manufacturing complexes and processing plants demand comprehensive protection with thermal monitoring diagnostics. Germany's industrial electrification standards drive specification of integrated solutions bundling hardware with remote monitoring capabilities.
- Telecommunication Towers:5G densification accelerates deployment of hybrid protection assemblies across Southeast Asia and the Middle East. Tower operators consolidate procurement around predictive maintenance subscriptions that compress upfront margins while securing decade-long service relationships.
- Commercial Buildings:Office complexes and retail centers prioritize IEC 62305 compliance for insurance and regulatory requirements.
- Residential Homes:Single-family and multi-unit dwellings represent price-sensitive volume segments with localized contractor networks.
Industrial facilities anchor revenue concentration; telecommunication towers exhibit steepest expansion trajectory.
Technology:
Technology maturity curves diverge sharply, with passive Faraday principles representing installed base and active emission systems capturing premium positioning in dense urban environments.
- Hybrid Systems:Configurations combining active early streamer emission with passive Faraday cage principles electrify vendor differentiation strategies. These systems reduce footprint requirements for telecommunication towers in dense urban environments across Brazil and South Africa.
- Active Systems:Early streamer emission technology extends protected zone radius beyond conventional coverage. Southeast Asian tower operators adopt these at accelerated pace for premium pricing in space-constrained installations.
- Passive Systems:Traditional Faraday cage principles maintain cost advantages for standard commercial and residential applications.
- Integrated Solutions:Bundled hardware with IoT-enabled diagnostics transform one-time sales into recurring revenue streams for industrial facility managers.
Passive systems dominate installed base; hybrid configurations are climbing the fastest.
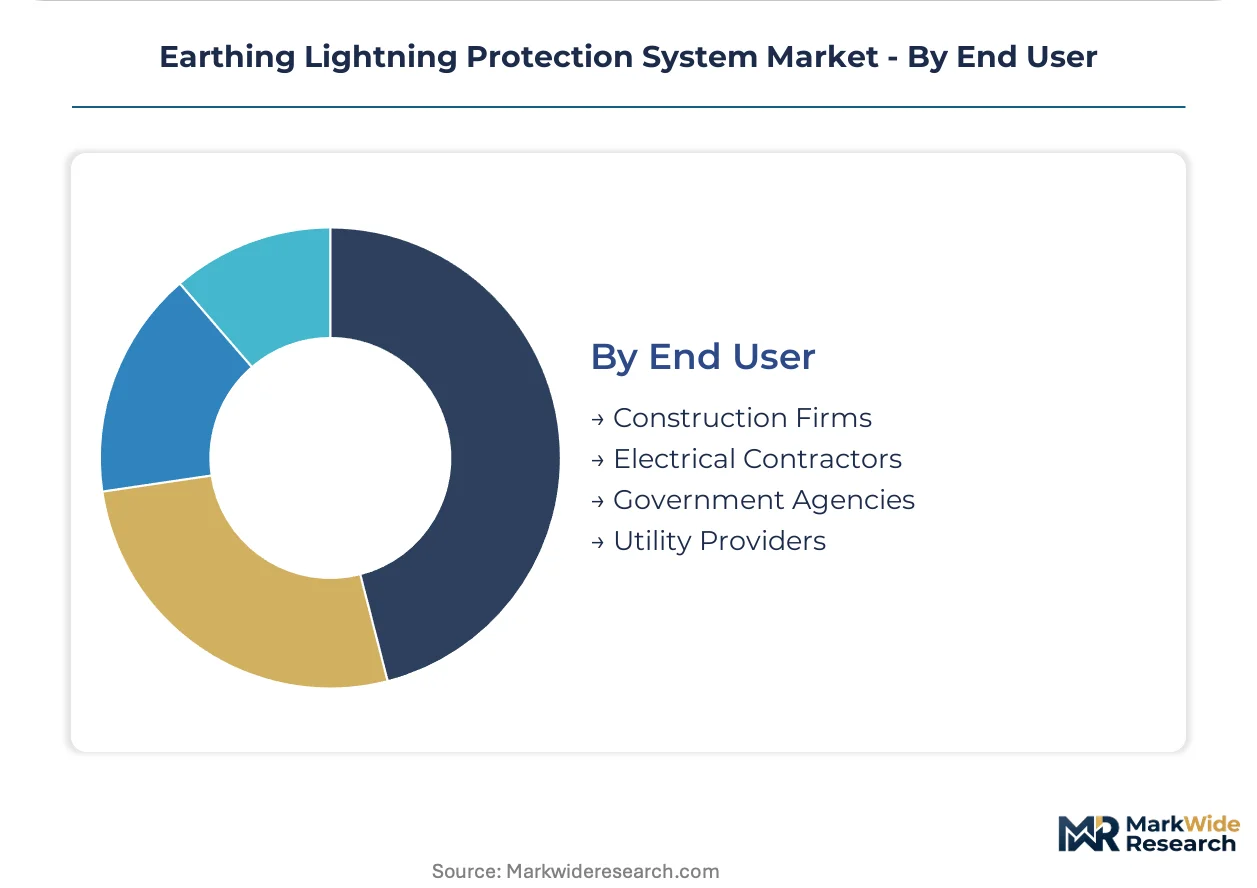
End User:
Customer type determines procurement channel structure, with utility providers specifying integrated solutions and electrical contractors competing on installation labor efficiency.
- Utility Providers:Grid operators and renewable developers now mandate bundled hardware with remote monitoring diagnostics. India's CEA technical standards redirect procurement toward certified grounding system providers with demonstrated utility-scale track records.
- Electrical Contractors:Installation specialists capture margin through certified lightning protection engineering concentrated in Germany, the United Kingdom, and Japan, creating deployment bottlenecks for emerging market infrastructure.
- Construction Firms:General contractors specify protection systems during building development phases with varying compliance rigor.
- Government Agencies:Public infrastructure projects emphasize multi-standard certification capabilities spanning IEC 62305 and national electrical codes.
Electrical contractors handle greatest installation volume; utility providers are expanding procurement most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating production to jurisdictions with lower certification costs while maintaining IEC 62305 compliance for EU market access. This regulatory arbitrage concentrates electrode fabrication in India and surge arrester assembly in Southeast Asian export zones.
United States
Data center construction in Virginia and Texas drives demand for integrated protection with thermal monitoring diagnostics. NFPA 780 compliance mandates shape procurement specifications for hyperscale facilities. Chicago-based electrical contractors dominate certified installation capacity for industrial complexes.
Germany
Industrial electrification standards propel specification of bundled hardware with remote monitoring capabilities. IEC 62305 enforcement compels utilities and manufacturing plants to upgrade legacy installations. The Ruhr industrial cluster concentrates certified lightning protection engineering expertise.
India
CEA technical standards for grid-connected renewable assets redirect procurement toward certified grounding system providers. Solar farms in Rajasthan and Gujarat absorb copper-bonded steel electrodes with documented impedance below 10 ohms. Domestic contractors in Maharashtra must demonstrate compliance records to qualify for utility-scale tenders.
Brazil
5G infrastructure densification accelerates deployment of hybrid protection assemblies across telecommunication towers. ANVISA and national electrical codes create multi-layer compliance requirements for imported surge components. São Paulo tower operators consolidate procurement around predictive maintenance subscriptions.
Singapore
Hyperscale data center construction specifies integrated lightning protection with IoT-enabled diagnostics. The city-state's position as a regional logistics hub concentrates procurement decision-making for Southeast Asian tower operators. Jurong Island industrial complexes anchor premium positioning for certified contractors.
Earthing Lightning Protection System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with industrial facilities favoring established electrification brands and telecom towers accepting OEM assemblies. The vendor base clusters around three strategic archetypes: diversified electrification conglomerates, telecommunications-specific protection specialists, and regional grounding component fabricators. Capacity expansion and backward integration into semiconductor-grade varistor production represent the dominant competitive moves.
Among diversified electrification conglomerates, ABB and Eaton Corporation exemplify the integrated-solutions archetype, bundling hardware with software-enabled service contracts. Raycap occupies a specialist position within telecommunications-specific protection, reflecting the segment's distinct procurement patterns. These three companies represent contrasting approaches to capturing recurring revenue streams in an industry transitioning from one-time hardware sales toward predictive maintenance subscriptions.
| Leading Market Players |
|---|
| Pentair |
| A.N. Wallis |
| ABB |
| Lightning Master Corporation |
| Fatech Electronic |
| Raycap |
| Alltec Corporation |
| Eaton Corporation |
| Harger Lightning & Grounding |
| Others |
Supply Flow & Price Mechanics
Active early streamer emission manufacturing is displacing conventional Faraday cage fabrication methods, simultaneously compressing production cycle times and concentrating electrode supply among certified Southeast Asian assemblers. This technology transition rewards vendors with backward integration into semiconductor-grade varistor production while penalizing pure-play grounding rod fabricators exposed to copper price volatility.
Pricing Analysis
Distributor margin stacking separates certified surge arrester supply from direct-to-utility procurement of copper-bonded electrodes. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 62305 certification grade and remote monitoring bundling. Cost compression in standard-tier grounding rod supply is intensifying because Indian solar developers are consolidating procurement around documented CEA compliance records. Residential contractors exhibit highest price sensitivity, while data center operators absorb premium positioning for thermal monitoring diagnostics.
Supply Chain Analysis
Refurbishment flows for surge protection assets remain underdeveloped, though ABB and Eaton are piloting electrode recovery programs in Germany. Raw material sourcing draws from Chilean copper concentrate, Chinese steel rod feedstock, and Japanese metal-oxide varistor ceramics. Single-source vulnerability concentrates in semiconductor-grade surge component supply anchored to Japanese and South Korean foundries. Distribution runs through certified electrical contractor networks in industrialized markets and direct OEM relationships for telecommunication tower operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IEC 62305 enforcement across European Union member states compounds demand for certified surge diversion systems, creating sustained procurement momentum for vendors with multi-standard testing capabilities.
For Market Incumbents: Lock in decade-long predictive maintenance subscriptions with telecommunication tower operators before 5G densification procurement peaks. Deepen backward integration into copper-bonded steel electrode production to defend against raw material margin compression. Prioritize certification investment spanning NFPA 780 and national electrical codes to maintain access across fragmented regulatory environments.
For New Entrants and Emerging Players: Begin with CEA-compliant grounding system provision for India's utility-scale solar installations, where certified contractor scarcity creates procurement bottlenecks. Target remote monitoring diagnostics as a standalone service offering for European industrial facilities disaggregating hardware from maintenance contracts. Pursue partnership routes with established surge arrester assemblers to bypass semiconductor-grade component manufacturing barriers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional grounding component fabricators lacking IoT-enabled service capabilities, presenting consolidation targets for electrification conglomerates seeking recurring revenue streams. Long-term viability hinges on transformation from transactional hardware sales toward subscription-based predictive maintenance models. Monitor copper price volatility and CEA tender award volumes as inflection indicators for margin expansion versus compression cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Varistor Production | Captive supply of semiconductor-grade components insulates margins from Japanese foundry pricing power. |
| Predictive Maintenance Platform Launch | IoT-enabled diagnostics transform ABB's electrification software into recurring revenue anchors for European industrial complexes. |
| CEA Certification Investment | Documented compliance records qualify domestic contractors for Rajasthan and Gujarat solar farm tenders. |
| Hybrid System Assembly Expansion | Active-passive combination configurations command premium positioning in São Paulo's dense 5G tower deployments. |
| Multi-Standard Testing Infrastructure Buildout | Simultaneous IEC 62305 and NFPA 780 capabilities accelerate product launch timelines for global market access. |
Methodological Framework
Bottom-up telecommunication tower and data center installation modeling reconciled against top-down copper-bonded electrode production tracking forms the analytical core of this study. Primary fieldwork encompassed lightning protection engineering directors, utility procurement leads, certified installation contractors, and surge arrester manufacturing plant managers. Secondary validation drew from IEC certification registries, CEA technical standard filings, customs trade data for grounding component imports, and SEC disclosures from electrification conglomerates. Triangulation across these sources anchors volume estimates to observable procurement patterns rather than survey extrapolation.
Historical trendline analysis of certified installation growth and renewable energy capacity additions informed projection parameters across the analysis window. Segmentation modeling incorporated product type, application category, technology maturity, and end-user procurement channel structure. CAGRs derive from regression analysis of impedance specification adoption curves and predictive maintenance subscription penetration rates. Forecast inputs include 5G tower densification schedules, CEA mandate implementation timelines, and data center construction permitting velocity.
Several conditions sit outside the modeled scope, including force majeure disruptions to copper concentrate supply and unilateral regulatory revisions to IEC 62305 testing protocols. Forecasts reflect assumptions regarding continued CEA enforcement consistency and telecommunication operator capital commitment stability. Practitioners should monitor copper LME price bands and hyperscale facility construction starts for early signals of demand trajectory revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
United States Fire Sprinklers Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Fire Suppression Agent Market
Fire Safety & Protection
Global Flame Arrestors Market
Fire Safety & Protection
UAE Firefighting Foam Market
Fire Safety & Protection
Global Fire Barrier Sealant Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Fire Alarm Systems Market
Fire Safety & Protection
Fire Rated Cables Market
Fire Safety & Protection
Fire Fighting Foam Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Smoke Pressure System Market
Fire Safety & Protection
US Fire Alarm and Detection Market